
 Vaccine Vial Rubber Stopper Market | 2026-2036
Vaccine Vial Rubber Stopper Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Vial Rubber Stopper Market Analytics
EU MDR is repositioning the cost-of-entry calculus for stopper suppliers by mandating exhaustive biocompatibility documentation and traceability across the supply chain. Daikyo Seiko leverages its fluoropolymer-coated stoppers to sustain premium positioning in high-sensitivity biologics applications. West Pharmaceutical Services anchors North American supply through integrated elastomer and aluminum seal manufacturing. Dätwyler Holding differentiates via backward integration into halobutyl rubber compounding, controlling raw material quality for European pharmaceutical clients.
A vaccine vial rubber stopper is an elastomeric closure, typically composed of bromobutyl or chlorobutyl rubber with optional fluoropolymer lamination, designed to seal glass vials while maintaining sterility and enabling needle puncture for dose withdrawal. The component must meet particulate limits, self-sealing resealability, and compatibility with freeze-thaw cycles across temperature ranges from minus eighty degrees Celsius to ambient storage. Synthetic rubber stoppers lead volume due to superior extractables profiles versus natural rubber, while silicone variants capture fastest growth in cell and gene therapy applications requiring inert contact surfaces. Biologics applications concentrate margin pools where closure failure risks batch loss valued in the millions, driving pharmaceutical companies toward validated single-source supply agreements.
FDA container closure guidance, EU MDR, and ISO 8871-5 collectively define the testing matrix for elastomeric closures, with FDA emphasizing extractables protocols and EU MDR requiring notified body oversight for device-drug combination products. China's NMPA has aligned its pharmacopoeia with ICH Q3D on elemental impurities, forcing reformulation of rubber curing agents across Asian supply bases. Stakeholders must monitor how USP and EP convergence on particulate standards reshapes qualification timelines for multi-market suppliers.
Market Dynamics
mRNA and viral vector manufacturing platforms are forcing pharmaceutical companies to requalify their entire container closure systems for lower-temperature storage and reduced extractables profiles. This technological inflection is compressing supplier qualification timelines while expanding the addressable premium segment for coated elastomeric closures.
Growth Catalysts
- EU MDR combination product oversight:The regulation's expanded scope for device-drug interfaces is mandating upgraded documentation for stoppers used in prefilled syringes and vials, pulling demand toward validated suppliers with established notified body relationships.
- Cell and gene therapy cold chain:Cryogenic storage requirements for CAR-T and gene editing therapies are accelerating silicone stopper adoption for their inert surface properties across minus eighty degrees Celsius cycles.
- India's vaccine production scaling:Domestic manufacturing capacity expansion under the Universal Immunization Programme is concentrating procurement volume for bromobutyl rubber closures among local fill-finish facilities.
Market Restraints
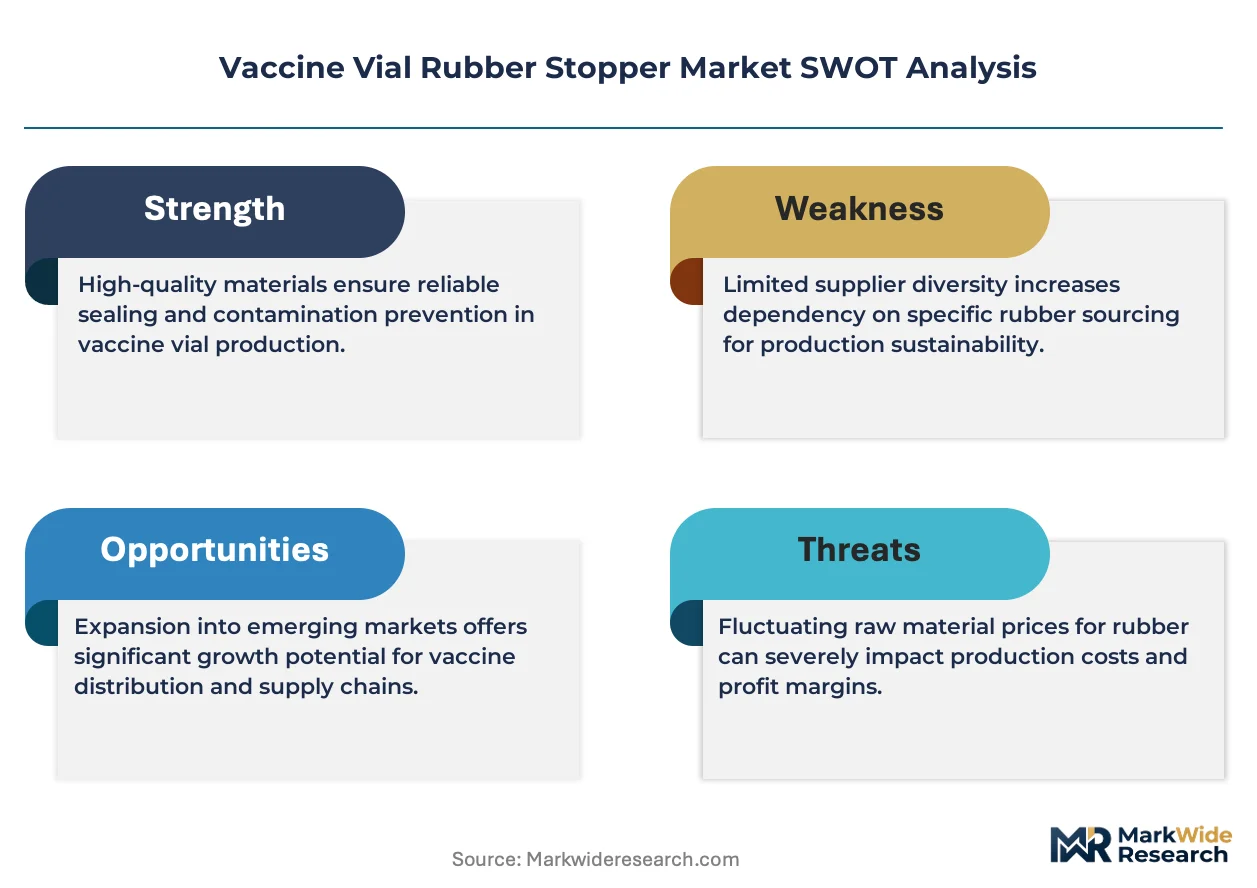
- Halobutyl rubber feedstock concentration:Four Asian petrochemical complexes control over seventy percent of pharmaceutical-grade bromobutyl supply, creating input cost volatility when cracker operations face turnaround schedules.
- Extractables testing burden:FDA's updated container closure guidance requires comprehensive analytical protocols that add twelve to eighteen months to new supplier qualification, freezing out mid-tier competitors.
- Glass vial format substitution:Polymer syringes and blow-fill-seal ampoules are capturing share in single-dose applications, compressing addressable volume for traditional rubber stopper-vial combinations.
Strategic Opportunities
- China's NMPA pharmacopoeia alignment:The regulator's adoption of ICH Q3D elemental impurity standards is forcing reformulation of rubber curing agents, creating first-mover advantage for suppliers with pre-validated clean compound portfolios.
- Continuous manufacturing integration:Real-time release testing and automated fill-finish lines are converging with fluoropolymer-coated stoppers to eliminate silicone oil particulate concerns in high-speed production environments.
- Personalized medicine dose formats:Micro-volume vials for individualized oncology therapies represent an underpenetrated application segment requiring specialized small-diameter closure designs.
Industry Challenges
- Elastomer formulation chemistry expertise:The specialized knowledge required for halobutyl curing agent selection and lamination bonding is concentrated among retiring technical specialists, constraining R&D throughput at emerging suppliers.
- Multi-jurisdiction certification synchronization:Divergent USP and EP particulate testing methodologies force parallel qualification tracks, extending time-to-revenue for new product introductions by nine to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Vial Rubber Stopper Market |
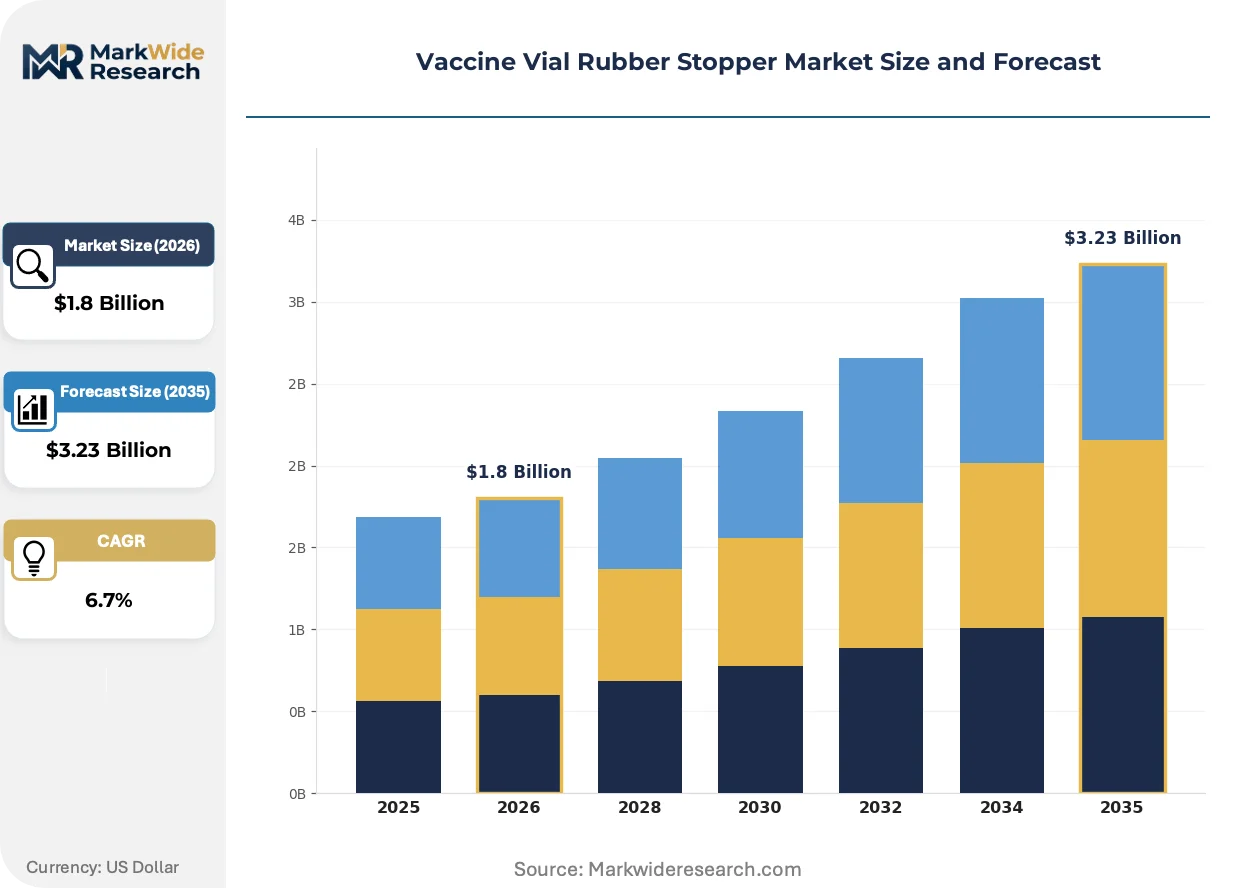
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Rubber, Synthetic Rubber, Silicone, Others Application: Pharmaceuticals, Biologics, Diagnostics, Others End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Clinics Packaging Type: Bulk Packs, Individual Packs, Customized Packs, Others |
| Companies Covered | Daikyo Seiko, AptarGroup, West Pharmaceutical Services, Schott AG, Nipro Corporation, Freudenberg Medical, Dätwyler Holding, Hualan NPM, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Vial Rubber Stopper Market Evolving Landscape
Fluoropolymer barrier technologies and automated vision inspection systems are converging to redefine quality assurance thresholds for high-value biologics containment. These developments are compressing the acceptable defect rate from parts-per-thousand to parts-per-million while expanding the functional temperature envelope.
Fluoropolymer film lamination technology is modularizing the traditional stopper manufacturing stack by separating the elastomeric seal function from the drug contact surface. Biologics manufacturers adopting these coated closures are reducing silicone oil particulate counts by orders of magnitude. The technology is modularizing supplier value chains, forcing compounders to either license coating IP or cede premium positioning to laminated product specialists.
EU MDR's expanded device classification for container closure systems is mandating notified body oversight for stoppers used in combination products. This regulatory friction is compressing the qualified supplier base to firms with established European technical documentation. High-sensitivity biologics applications are experiencing the most acute compliance pressure, driving consolidation in the premium tier.
Single-source supply agreements are displacing multi-vendor qualification strategies as pharmaceutical companies seek to amortize validation costs across longer contract horizons. Large molecule manufacturers are consolidating procurement with integrated elastomer-and-seal suppliers who can assume technical liability for the complete containment system. This concentration is most visible in North American biologics manufacturing clusters, where batch failure costs exceed single-digit millions.
Vaccine Vial Rubber Stopper Market Segmentation
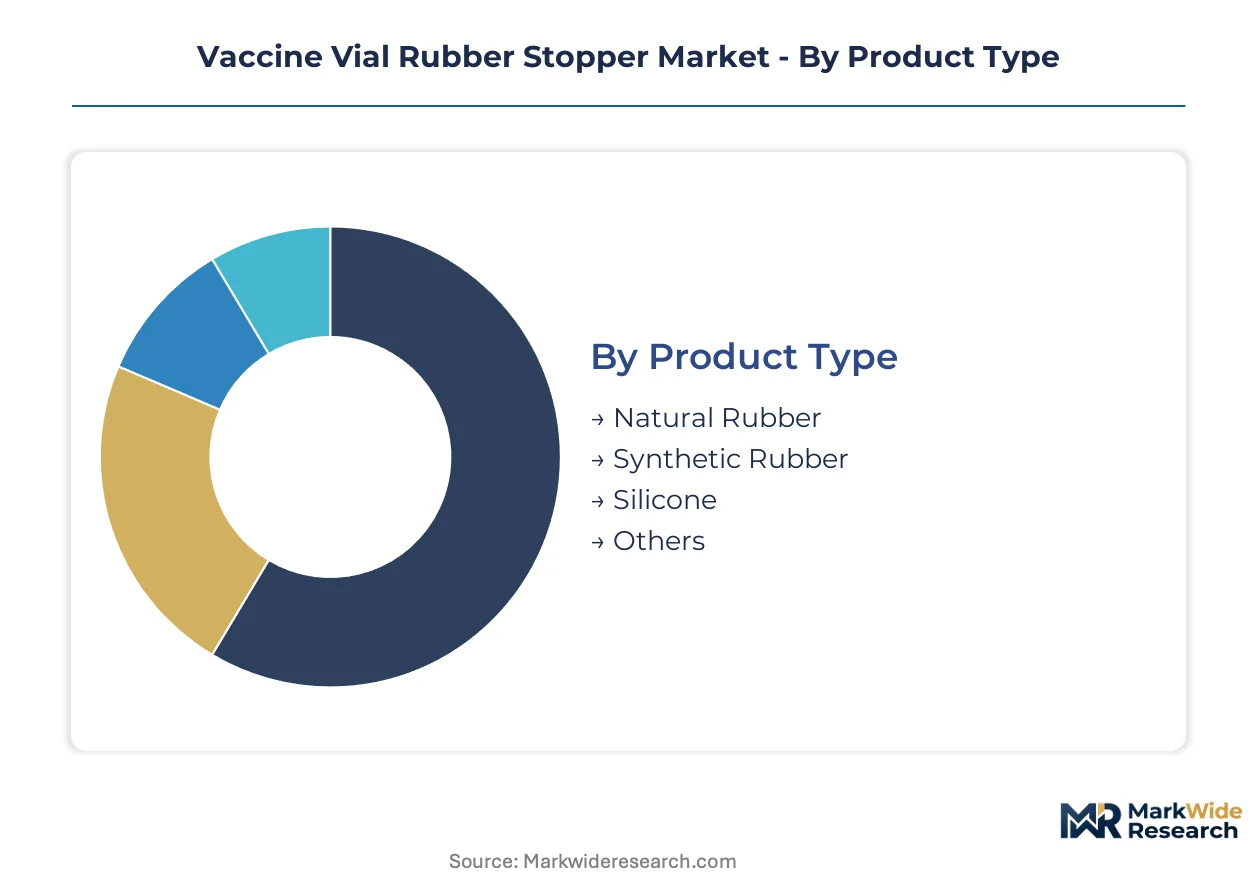
Segmentation in the vaccine vial rubber stopper market reveals how formulation chemistry, application risk profiles, and procurement scale reshape supplier-customer relationships. Pharmaceutical buyers segment their sourcing strategies across material purity tiers and cold-chain performance requirements.
Product Type:
Buyers differentiate primarily by extractables tolerance and temperature resilience, with biologics manufacturers paying premiums for inert contact surfaces that minimize protein aggregation risk.
- Synthetic Rubber:Bromobutyl and chlorobutyl compounds dominate commercial volumes through superior oxygen barrier properties and reduced leachable profiles versus natural alternatives. Demand concentrates among multi-dose vaccine producers in India and China, where national immunization programs prioritize cost-efficient synthetic formulations validated under NMPA and CDSCO pharmacopoeia standards.
- Silicone:Platinum-cured silicone stoppers offer the lowest surface energy and particulate generation, making them indispensable for cell and gene therapy applications requiring cryogenic stability through minus eighty degrees Celsius freeze-thaw cycles. CAR-T manufacturers in the United States and Germany are accelerating procurement of silicone variants despite unit cost premiums.
- Natural Rubber:Hevea brasiliensis-derived stoppers retain niche positioning in emerging market single-dose vaccines where regulatory extractables thresholds remain less stringent.
- Others:Hybrid laminates and experimental thermoplastic elastomers occupy pre-commercial evaluation phases at major pharmaceutical fill-finish operators.
Volume sits with synthetic rubber; growth tilts toward silicone.
Application:
Application segmentation tracks containment failure cost exposure, with batch values ranging from thousands in diagnostics to millions in commercial biologics.
- Biologics:Monoclonal antibodies, mRNA vaccines, and viral vector gene therapies demand fluoropolymer-coated or ultra-pure silicone closures validated for sub-visible particulate limits under FDA container closure guidance. German and Swiss biologics manufacturers are consolidating supply agreements with integrated elastomer-and-seal suppliers who assume technical liability for complete containment systems.
- Pharmaceuticals:Small-molecule injectables and traditional vaccines utilize standard halobutyl stoppers where self-sealing resealability and moisture vapor transmission rates drive specification compliance. Indian fill-finish facilities under the Universal Immunization Programme anchor procurement volume for bromobutyl rubber in this segment.
- Diagnostics:In-vitro diagnostic reagent vials require lower particulate specifications than drug applications, opening procurement to mid-tier compounders with streamlined validation protocols.
- Others:Veterinary vaccines and cosmetic ampoules represent fragmented demand with limited premium pricing power.
Biologics commands margin concentration; pharmaceuticals moves volume.
End User:
End user segmentation reflects validation burden distribution, with large pharmaceutical companies internalizing qualification costs that smaller clinical operators cannot absorb.
- Pharmaceutical Companies:Multinational vaccine manufacturers and contract development manufacturing organizations drive specification-setting through single-source supply agreements spanning five-to-ten year horizons. These buyers require comprehensive extractables documentation, notified body oversight for EU MDR combination products, and traceability across halobutyl rubber supply chains.
- Research Laboratories:Academic and government research institutions prioritize small-lot flexibility and rapid qualification timelines over unit cost optimization, creating demand for catalog-standard stoppers with abbreviated testing protocols.
- Hospitals:Hospital pharmacy compounding operations source through group purchasing organizations focused on sterile packaging integrity for patient-ready doses.
- Clinics:Point-of-care vaccination sites consume pre-filled syringe formats that bypass traditional vial-stopper combinations entirely.
Pharmaceutical companies dominate procurement value; research laboratories show the steepest expansion trajectory for specialized small-batch formats.
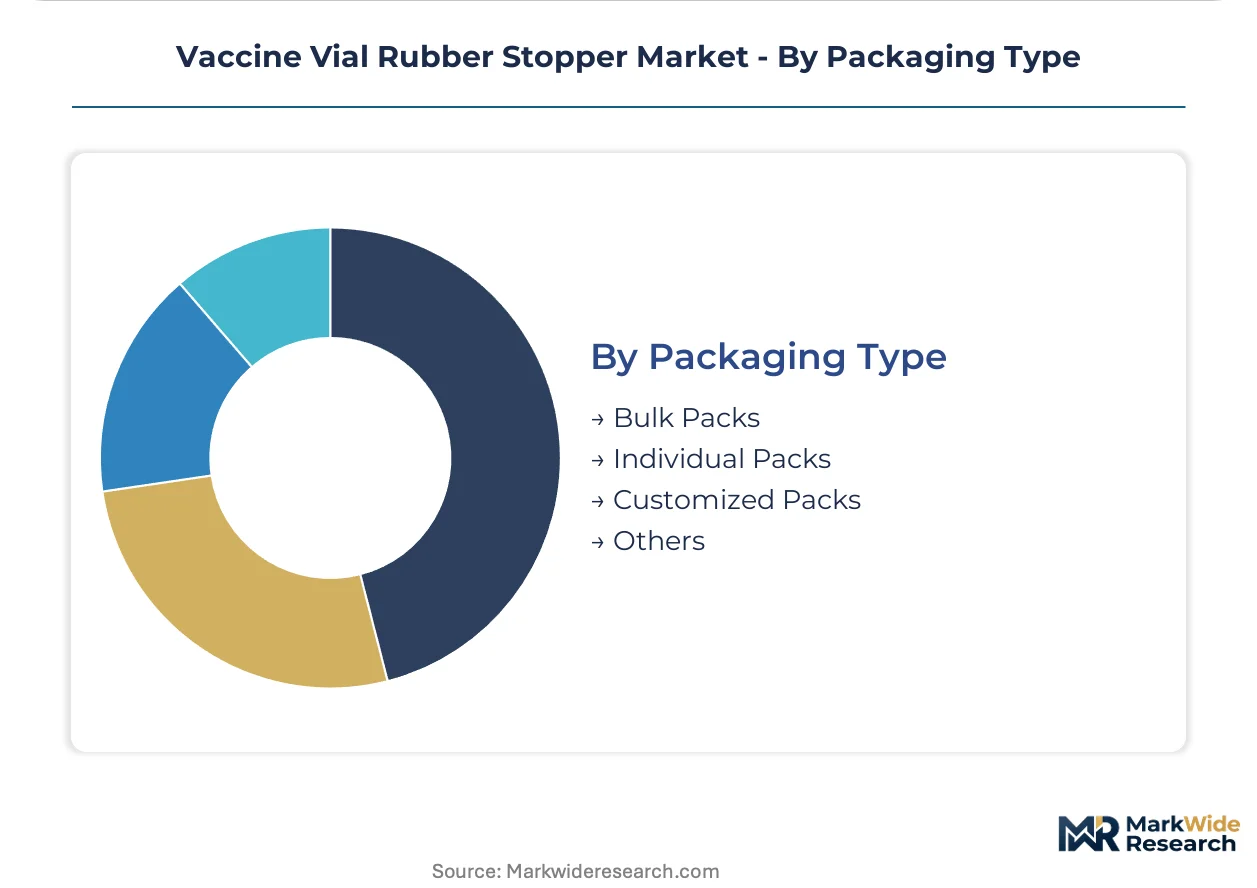
Packaging Type:
Packaging segmentation tracks automation compatibility and contamination risk management across fill-finish line configurations.
- Bulk Packs:Unnested stoppers in polyethylene-lined drums serve high-speed automated vial sealing operations at commercial vaccine manufacturing scale. German and Japanese fill-finish equipment manufacturers design handling systems around bulk feed geometries.
- Individual Packs:Pre-sterilized single-stopper pouches eliminate depyrogenation steps for clinical trial materials and personalized medicine batches where cross-contamination risks outweigh packaging cost premiums.
- Customized Packs:Nest-and-stack configurations and customer-specific bagging protocols accommodate continuous manufacturing integration and real-time release testing workflows.
- Others:Specialty cleanroom presentations and gamma-irradiated formats serve aseptic processing requirements in cell therapy cleanrooms.
Bulk packs carry manufacturing volume; customized packs gains share fastest through continuous manufacturing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones and China's biomedical industrial parks concentrate vaccine vial rubber stopper demand through tax-advantaged manufacturing clusters serving domestic immunization programs and export markets.
United States
mRNA vaccine manufacturers in Massachusetts and North Carolina drive procurement of fluoropolymer-coated stoppers validated for ultra-cold chain storage. FDA container closure guidance mandates exhaustive extractables documentation, extending supplier qualification timelines. The Research Triangle Park cluster anchors technical validation services for elastomeric closure systems.
Germany
CAR-T therapy producers in Baden-Württemberg and monoclonal antibody manufacturers in Bavaria accelerate silicone stopper adoption for cryogenic stability requirements. EU MDR combination product oversight forces notified body relationships for device-drug interface documentation. The Rhine-Main biotech corridor concentrates single-source supply agreement negotiations with integrated elastomer suppliers.
China
NMPA pharmacopoeia alignment with ICH Q3D elemental impurity standards compels reformulation of rubber curing agents across domestic compounders. The Yangtze River Delta biomedical zone hosts fill-finish facilities scaling under national vaccine self-sufficiency mandates. Suzhou and Shanghai industrial parks concentrate backward-integrated halobutyl rubber processing capacity.
India
Universal Immunization Programme expansion drives bromobutyl rubber closure procurement at CDSCO-registered fill-finish facilities in Maharashtra and Gujarat. PLI scheme incentives attract multinational elastomer suppliers to establish local compounding operations. The Hyderabad-Visakhapatnam vaccine manufacturing belt anchors volume procurement for multi-dose vial formats.
Switzerland
Swissmedic oversight of combination products positions the Basel biopharma cluster for premium-tier stopper qualification. Gene therapy manufacturers around Lake Geneva demand silicone variants validated for minus eighty degrees Celsius logistics. The country's precision manufacturing heritage supports automated vision inspection system deployment for particulate detection.
Vaccine Vial Rubber Stopper Market Competitive Landscape
Japanese and German producers anchor the premium tier; Chinese and Indian compounders hold volume positioning through cost-optimized halobutyl formulations. Market structure stratifies across three tiers: integrated elastomer-and-seal suppliers assuming technical liability, specialized fluoropolymer coating licensors, and regional compounders serving emerging market pharmacopoeia standards. Consolidation pressures favor backward-integrated players controlling curing agent quality, while mid-tier competitors face exclusion from biologics procurement through FDA qualification timeline burdens.
Within the integrated systems tier, West Pharmaceutical Services and Dätwyler Holding exemplify suppliers combining elastomer manufacturing with aluminum seal production to assume complete containment liability. Daikyo Seiko occupies a distinct position through fluoropolymer lamination specialization serving high-sensitivity biologics applications. These three entities represent contrasting geographic and technical archetypes: North American integrated manufacturing, European backward-integrated compounding, and Japanese surface technology licensing.
| Leading Market Players |
|---|
| Daikyo Seiko |
| AptarGroup |
| West Pharmaceutical Services |
| Schott AG |
| Nipro Corporation |
| Freudenberg Medical |
| Dätwyler Holding |
| Hualan NPM |
| Becton Dickinson and Company |
| Others |
Value Network & Pricing Analysis
Fluoropolymer lamination adoption is simultaneously elevating unit economics for premium-tier suppliers and compressing margins for uncoated compounders unable to license barrier technology. This process bifurcation concentrates pricing power among Japanese and German coating specialists while forcing volume-tier Asian producers into cost-competitive halobutyl formulations.
Pricing Analysis
Lead-time-driven pricing premiums reward suppliers with pre-validated extractables documentation under FDA container closure guidance, while spot-market halobutyl compounds trade at discounts for buyers accepting extended qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer-coated closures from validated synthetic rubber from basic bromobutyl formulations. Cost compression in economy-tier procurement is intensifying because Indian and Chinese national immunization programs consolidate volume awards. Research laboratories show the steepest price sensitivity due to small-lot purchasing power, while CAR-T manufacturers absorb premiums for cryogenic-validated silicone variants.
Supply Chain Analysis
Single-source vulnerability sits with four Asian petrochemical complexes controlling pharmaceutical-grade bromobutyl rubber feedstock. Manufacturing concentration in China, India, and Japan anchors global elastomeric closure output, with German and Swiss facilities serving European biologics clusters. Halobutyl rubber compounding, fluoropolymer film sourcing, and precision molding equipment constitute critical input dependencies. Tariff exposure on Chinese-sourced curing agents threatens margin stability at compounders lacking backward integration. Distribution runs through direct pharmaceutical supply agreements rather than distributor networks, with fill-finish operators qualifying suppliers as single-source partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over halobutyl rubber curing agent quality and fluoropolymer coating IP determines tier positioning. Players are pursuing upstream captive supply of pharmaceutical-grade elastomers to escape feedstock volatility.
For Market Incumbents: Cement technical liability advantages by assuming complete containment system accountability across elastomer-and-seal combinations, matching West Pharmaceutical Services and Dätwyler Holding integration models. Deepen notified body relationships for EU MDR combination product oversight before qualification timelines freeze out mid-tier competitors. Prioritize capacity addition in Yangtze River Delta and Hyderabad-Visakhapatnam clusters to capture India's Universal Immunization Programme procurement consolidation. For New Entrants and Emerging Players: Enter via micro-volume vial closure specialization for personalized oncology therapies, a segment where large incumbants lack customized small-diameter designs. Target research laboratory procurement channels where abbreviated validation protocols reduce FDA documentation barriers. Pursue licensing partnerships with Japanese fluoropolymer coating licensors rather than competing on uncoated halobutyl commodity supply. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated pharmaceutical packaging conglomerates seeking elastomeric closure capabilities. Long-term viability over the mid-term projection horizon hinges on backward integration into curing agent quality control and established notified body relationships. Watch for NMPA enforcement of ICH Q3D elemental impurity standards as the inflection signal that separates pre-validated clean compound portfolios from reformulation-lagged competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halobutyl Rubber Compounding | Dätwyler Holding's captive curing agent supply insulates European pharmaceutical clients from Asian petrochemical volatility. |
| Fluoropolymer Coating Technology Licensing | Daikyo Seiko's surface technology IP enables biologics manufacturers to reduce silicone oil particulate counts by orders of magnitude. |
| Notified Body Relationship Establishment | EU MDR combination product oversight mandates technical documentation partnerships that compress the qualified supplier base. |
| Continuous Manufacturing Integration | Automated fill-finish line compatibility with fluoropolymer-coated stoppers eliminates particulate concerns in high-speed production environments. |
| Regional Compounding Capacity Expansion | India's PLI scheme incentives attract multinational suppliers to localize bromobutyl rubber processing for Universal Immunization Programme procurement. |
Research Methodology
Multi-period observation of FDA container closure guidance implementation, EU MDR notified body oversight expansion, and NMPA pharmacopeia alignment anchored the trend analysis, supplemented by interviews with fill-finish operations directors, elastomer compounder technical leads, pharmaceutical procurement managers, and regulatory affairs specialists at biologics manufacturers. Secondary validation drew from FDA guidance documents, EMA combination product classifications, CDSCO registration databases, and SEC filings of publicly traded packaging suppliers. Bottom-up segment sizing triangulated against top-down industry association aggregates.
Input-output matrices modeled elastomer formulation chemistry, cold-chain performance requirements, and procurement scale across product type, application risk tier, end-user validation burden, and packaging automation compatibility dimensions. CAGRs were derived from segment-level growth rate synthesis across the projection horizon. Industry-specific forecast inputs incorporated mRNA platform expansion trajectories and viral vector manufacturing capacity buildouts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt halobutyl rubber feedstock disruption or accelerated glass vial substitution by polymer syringe formats. Deviation in FDA extractables testing protocol stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Prescription Pharmacy Bags Market
Pharmaceutical Packaging
Pharmaceutical Bottles Market
Pharmaceutical Packaging
Single Dose Dispensers Market
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Glass Medicine Bottles Market
Pharmaceutical Packaging
North America Ampoules Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market
Pharmaceutical Packaging
Polymer Vials Market
Pharmaceutical Packaging
Anti-Counterfeit Pharmaceutical Packaging Market