
 Sleeve Rubber Stoppers Market | 2026-2036
Sleeve Rubber Stoppers Market Size, Share, and Industry Trends Forecast 2026-2036
Sleeve Rubber Stoppers Market Analytics
Modular vial-closure systems with pre-assembled sleeve stopper components is hardening as the preferred configuration for high-speed fill-finish lines. West Pharmaceutical Services anchors this shift through integrated elastomer and delivery system manufacturing. Datwyler Holding leverages its Swiss and Belgian facilities to sustain leadership in coated and ready-to-use formats. Jiangsu Hualan New Pharmaceutical Material competes on cost-optimized butyl rubber output for Asian injectable producers.
Sleeve rubber stoppers are elastomeric closures, typically formulated from bromobutyl or chlorobutyl rubber with lamination or fluoropolymer coating, manufactured by compression or injection molding to achieve specified penetration force and reseal integrity after multiple needle entries. Their primary purpose is to maintain sterile barrier integrity in parenteral drug containers while permitting safe needle access. Butyl stoppers command the largest product type position due to superior gas barrier properties and low extractable profiles required for sensitive biologics. Pharmaceutical packaging dominates application demand as the shift toward prefilled syringes and lyophilized vials intensifies specification requirements. Silicone stoppers represent the fastest-growing formulation-adjacent segment where platinum-cured elastomers displace peroxide-cured alternatives in high-value therapeutic categories.
FDA extractables and leachables guidelines, EMA Annex 1 revision on sterile manufacturing, and USP Chapter 381 elastomeric closure standards collectively elevate barrier performance and biocompatibility requirements for sleeve stopper suppliers. These frameworks compel manufacturers to validate coating consistency, particulate control, and lot-to-lot uniformity as baseline market access conditions. Stakeholders must monitor evolving regulatory alignment between FDA and EMA on container closure integrity testing protocols to anticipate qualification burden shifts.
Market Dynamics
Modular vial-closure systems with pre-assembled sleeve stopper components are hardening as the dominant configuration for high-speed fill-finish lines, compressing qualification timelines and elevating specification barriers for component suppliers.
Growth Catalysts
- FDA extractables and leachables guidelines:These standards tighten material purity requirements for parenteral drug containers, forcing pharmaceutical manufacturers toward validated, coated elastomer solutions that reduce contamination risk.
- Biologics manufacturing expansion:The shift toward sterile injectables and lyophilized formulations drives specification requirements for gas-barrier closures with low extractable profiles.
- Prefilled syringe adoption:This delivery format concentrates demand for ready-to-use, coated stoppers that integrate seamlessly with automated assembly systems.
Market Restraints
- Halobutyl rubber feedstock concentration:Specialty elastomer supply concentrates among a limited set of petrochemical refiners, exposing converters to input cost volatility and allocation constraints.
- Fluoropolymer coating equipment intensity:Plasma deposition and lamination systems require substantial capital outlay, creating barriers for mid-scale entrants seeking coated product qualification.
- EMA Annex 1 sterile manufacturing revision:This framework elevates particulate control and container closure integrity testing burdens, extending validation timelines for new supplier qualification.
Strategic Opportunities
- India injectable manufacturing expansion:CDSCO regulatory alignment with ICH standards and PLI scheme incentives for domestic API and formulation production create demand for qualified closure suppliers.
- Platinum-cured silicone displacement:This material convergence addresses peroxide-cured elastomer limitations in high-value therapeutic categories, opening premium positioning for certified converters.
- Ready-to-use format penetration:Sterile, pre-washed, and pre-assembled stopper-vial combinations reduce fill-finish line contamination risk, commanding price premiums in biologics applications.
Industry Challenges
- Coating consistency validation:Fluoropolymer lamination uniformity across lot-to-lot production requires sophisticated metrology and statistical process control that strains quality engineering capacity.
- Container closure integrity testing protocol alignment:Divergent FDA and EMA expectations on test method validation create dual-track qualification burdens for suppliers serving both jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sleeve Rubber Stoppers Market |
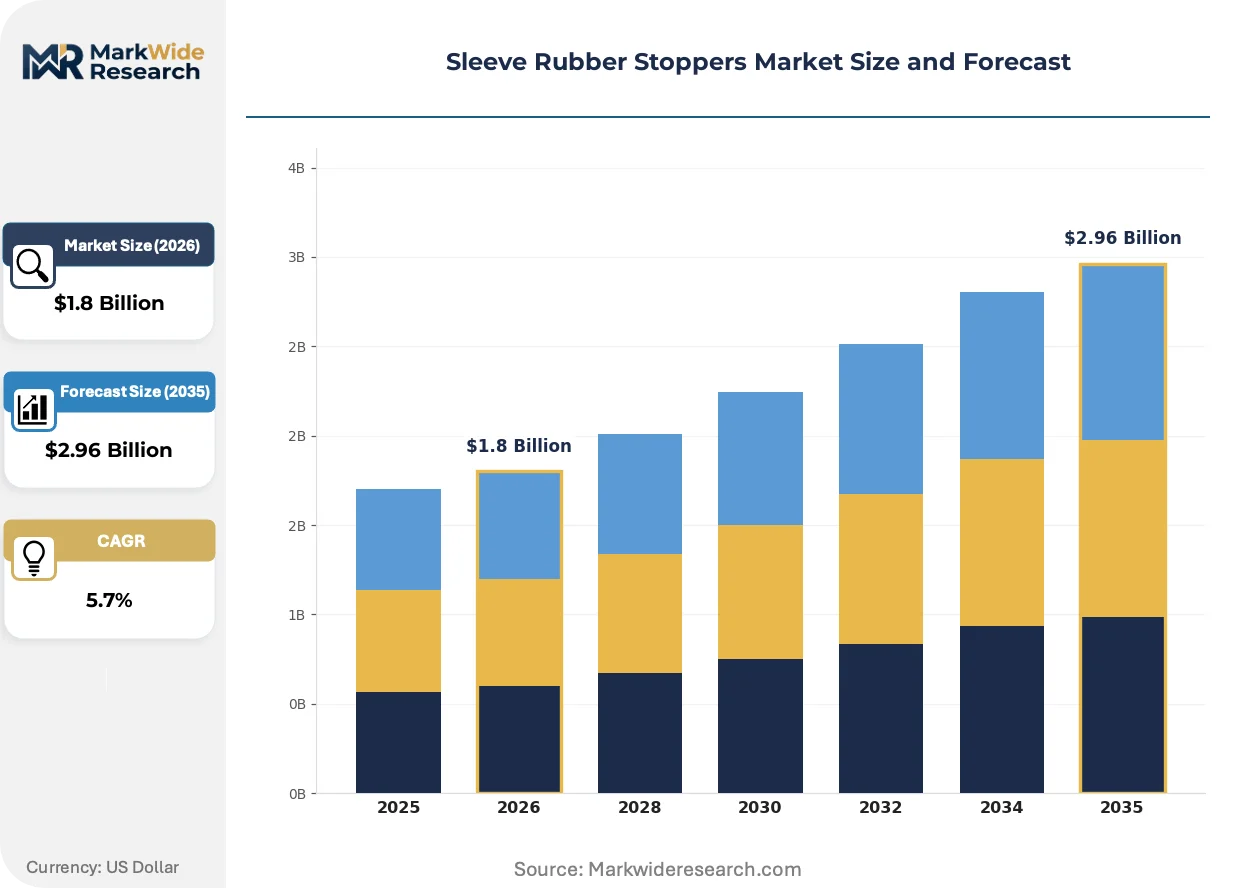
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Stoppers, Natural Rubber Stoppers, EPDM Stoppers, Butyl Stoppers Application: Pharmaceutical Packaging, Laboratory Equipment, Food & Beverage, Chemical Storage Formulation: Liquid Formulation, Powder Formulation, Granular Formulation, Viscous Formulation Industry Vertical: Healthcare, Food Industry, Cosmetics, Agriculture |
| Companies Covered | West Pharmaceutical Services, AptarGroup, Datwyler Holding, Saint-Gobain Performance Plastics, DWK Life Sciences, VWR International, The Plasticoid Company, Stelmi Italia, Jiangsu Hualan New Pharmaceutical Material, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sleeve Rubber Stoppers Market Evolving Landscape
Platinum-cured silicone elastomers are absorbing market share from peroxide-cured alternatives as biologics manufacturers prioritize extractable profile consistency. This material shift compresses the competitive set for high-value therapeutic closures.
Fluoropolymer coating technology is absorbing incremental specification requirements from EMA Annex 1 and FDA extractables guidelines. Lyophilized vial and prefilled syringe manufacturers in Germany and Switzerland are adopting plasma-deposited barrier layers at accelerated rates. This adoption pattern is compressing margins for uncoated commodity stopper producers.
EMA Annex 1 revision on sterile manufacturing mandates enhanced container closure integrity assurance and particulate monitoring. Pharmaceutical packaging operations in Belgium and Ireland are reconfiguring fill-finish lines to accommodate pre-assembled, ready-to-use stopper systems. This regulatory pressure is elevating qualification barriers for non-integrated component suppliers.
Consolidated procurement by contract manufacturing organizations is compressing supplier bases and extending master service agreement terms. Large parenteral drug producers in the United States and China are awarding multi-year, sole-source contracts to qualified closure suppliers with integrated coating and washing capabilities. This concentration pattern is marginalizing small-scale, undifferentiated converters.
Sleeve Rubber Stoppers Market Segmentation
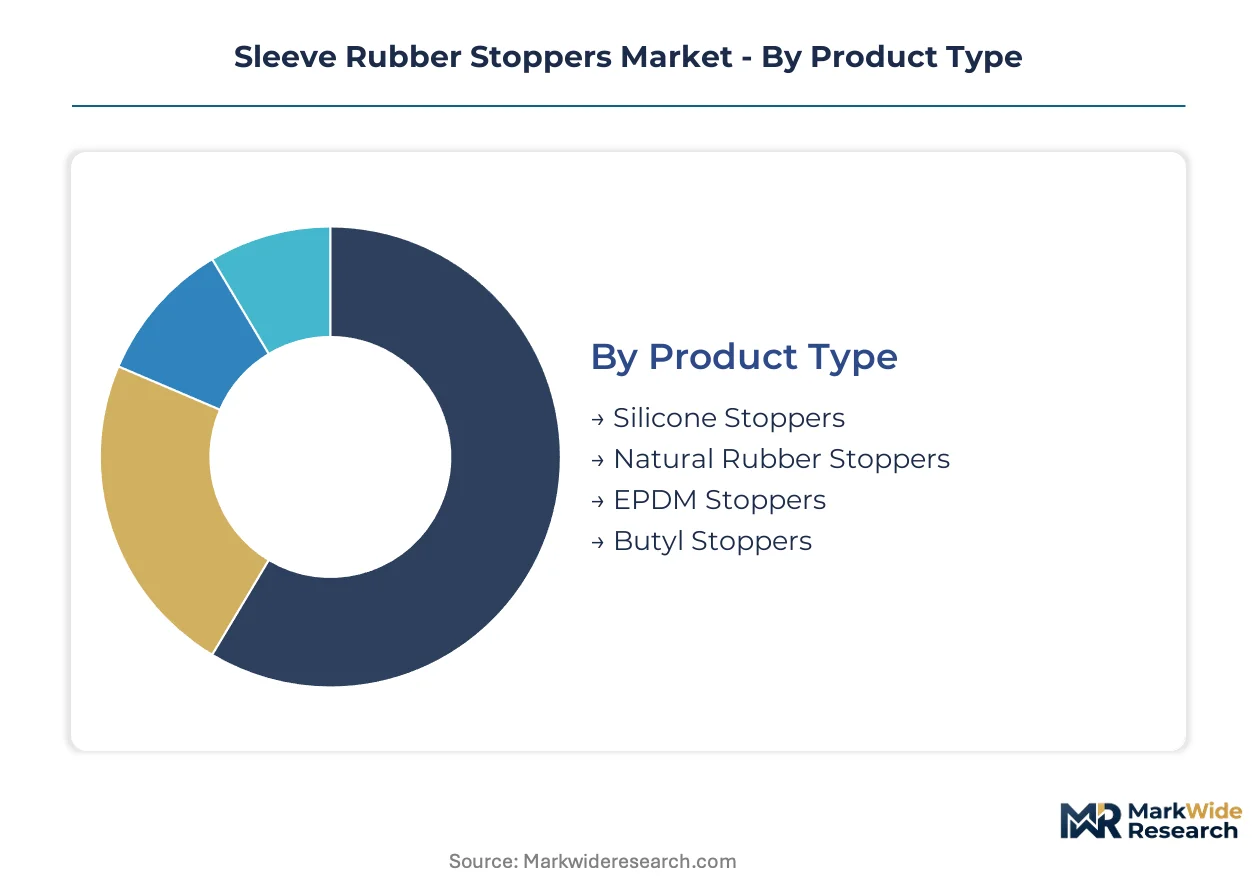
Sleeve rubber stopper segmentation reflects divergent supply chain economics across elastomer chemistries and end-use specifications. Each dimension carries distinct qualification burdens, coating requirements, and geographic sourcing patterns that reshape competitive positioning.
Product Type:
Halobutyl rubber feedstock concentration among limited petrochemical refiners exposes converters to input cost volatility and allocation constraints across all product categories.
- Butyl Stoppers:Formulated from bromobutyl or chlorobutyl rubber with lamination or fluoropolymer coating, these achieve specified penetration force and reseal integrity after multiple needle entries. Demand concentrates in Germany and the United States where parenteral drug manufacturing clusters require superior gas barrier properties and low extractable profiles for sensitive biologics.
- Silicone Stoppers:Platinum-cured elastomers displace peroxide-cured alternatives in high-value therapeutic categories. Switzerland and Belgium drive specification requirements as lyophilized vial and prefilled syringe manufacturers adopt plasma-deposited barrier layers at accelerated rates.
- Natural Rubber Stoppers:Conventional elastomeric closures with higher extractable profiles serve cost-sensitive applications outside regulated pharmaceutical channels.
- EPDM Stoppers:Ethylene-propylene-diene monomer formulations offer chemical resistance for industrial containment applications with reduced barrier requirements.
Today's leader: Butyl Stoppers. Tomorrow's challenger: Silicone Stoppers.
Application:
EMA Annex 1 sterile manufacturing revision elevates container closure integrity testing burdens, extending validation timelines unevenly across application categories.
- Pharmaceutical Packaging:Maintains sterile barrier integrity in parenteral drug containers while permitting safe needle access. Prefilled syringe adoption in China and the United States concentrates demand for ready-to-use, coated stoppers that integrate with automated assembly systems.
- Laboratory Equipment:Sealing solutions for analytical instruments and research consumables with moderate barrier specifications.
- Food & Beverage:Closure applications with regulatory requirements distinct from pharmaceutical extractables standards.
- Chemical Storage:Industrial containment emphasizing chemical compatibility over biocompatibility validation.
Pharmaceutical Packaging commands the dominant revenue position; Laboratory Equipment offers the steepest expansion trajectory in emerging research markets.
Formulation:
Coating consistency validation requirements intensify with formulation viscosity and particulate sensitivity, compressing margins for undifferentiated converters.
- Liquid Formulation:Injectable and infusion products with the most stringent extractables and leachables standards. FDA guidelines on material purity force pharmaceutical manufacturers toward validated, coated elastomer solutions that reduce contamination risk.
- Powder Formulation:Lyophilized and dry-fill applications requiring moisture barrier integrity.
- Granular Formulation:Intermediate processing stages with moderate environmental protection needs.
- Viscous Formulation:High-viscosity injectables and suspensions with specialized penetration force specifications.
Liquid Formulation anchors current procurement volumes; Powder Formulation gains share fastest as lyophilized biologics expand.
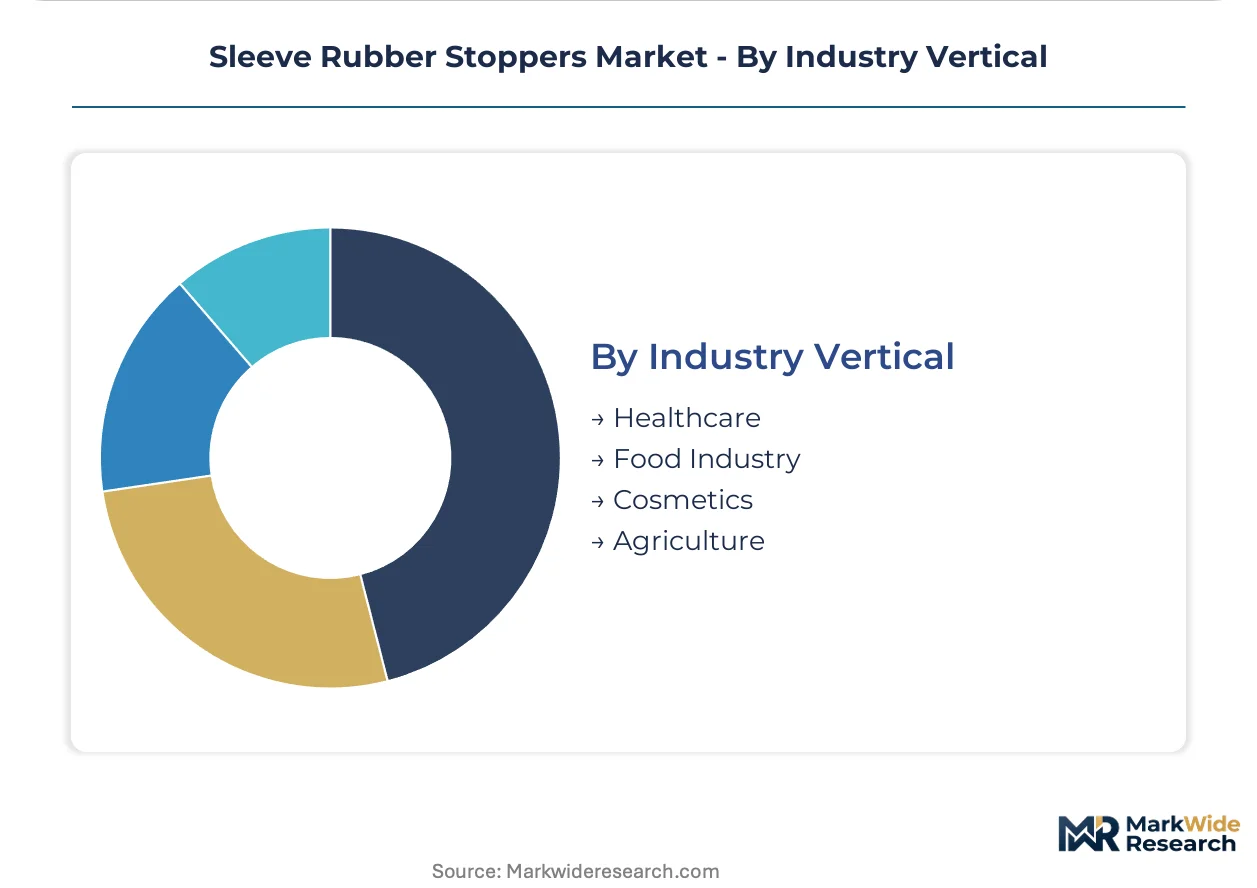
Industry Vertical:
Consolidated procurement by contract manufacturing organizations compresses supplier bases and extends master service agreement terms across verticals.
- Healthcare:Dominated by parenteral drug manufacturing with FDA and EMA regulatory alignment on container closure integrity testing protocols. Large producers in the United States and China award multi-year, sole-source contracts to qualified closure suppliers with integrated coating and washing capabilities.
- Food Industry:Packaging applications with national food safety regulator compliance requirements.
- Cosmetics:Premium positioning with aesthetic and functional closure specifications.
- Agriculture:Chemical containment with cost-optimized performance thresholds.
Healthcare vertical dominates value capture; Food Industry vertical presents the most accessible qualification pathway for new entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The sleeve rubber stopper industry traces its commercial origins to Swiss and German pharmaceutical packaging clusters established in the mid-twentieth century, where precision elastomer molding first met sterile injectable requirements. Today's manufacturing geography reflects that heritage while incorporating new production centers in Asia and North America.
United States
FDA extractables and leachables guidelines drive pharmaceutical manufacturers toward validated, coated elastomer solutions that reduce contamination risk in parenteral drug containers. The IRA domestic manufacturing provisions and reshoring incentives strengthen demand for qualified closure suppliers with integrated coating capabilities. Fill-finish operations in Massachusetts and North Carolina reconfigure lines to accommodate pre-assembled, ready-to-use stopper systems.
Germany
EMA Annex 1 revision on sterile manufacturing elevates container closure integrity testing burdens for lyophilized vial and prefilled syringe producers. The national pharmaceutical regulator enforces strict particulate control standards that compress margins for uncoated commodity stopper producers. Manufacturing clusters in Bavaria and Baden-Württemberg adopt plasma-deposited fluoropolymer barrier layers at accelerated rates.
China
NMPA alignment with ICH standards and domestic biologics manufacturing expansion intensify specification requirements for gas-barrier closures. Dual carbon goals and environmental compliance pressures reshape halobutyl rubber feedstock sourcing strategies for converters. Parenteral drug manufacturing in Jiangsu and Zhejiang provinces concentrates demand for cost-optimized butyl rubber output from regional suppliers.
Switzerland
Swissmedic pharmaceutical packaging standards and proximity to high-value therapeutic manufacturers sustain premium positioning for platinum-cured silicone formulations. The country's precision manufacturing heritage supports sophisticated metrology and statistical process control for coating consistency validation. Basel and Zurich pharmaceutical clusters specify ready-to-use, pre-washed stopper-vial combinations for biologics applications.
India
CDSCO regulatory alignment with ICH standards and PLI scheme incentives for domestic API and formulation production create demand for qualified closure suppliers. Injectable manufacturing expansion in Maharashtra and Gujarat reconfigures procurement toward certified converters with validated coating capabilities. The country's contract manufacturing organizations compress supplier bases and extend master service agreement terms.
Sleeve Rubber Stoppers Market Competitive Landscape
The competitive structure tilts toward integrated elastomer specialists with captive coating and washing capabilities. Tiered positioning separates premium converters serving biologics manufacturers from cost-optimized suppliers targeting generic injectable producers. Three archetypes dominate: multinational integrated systems providers, regional coating specialists, and commodity-scale butyl rubber converters. Consolidation through multi-year sole-source contracts and backward integration into halobutyl rubber compounding represent the dominant competitive moves.
Among the integrated systems tier, West Pharmaceutical Services and Datwyler Holding exemplify the premium positioning archetype through combined elastomer manufacturing and delivery system integration. Jiangsu Hualan New Pharmaceutical Material occupies a position within the cost-optimized converter segment, representing regional-scale competition focused on Asian injectable production. Saint-Gobain Performance Plastics and DWK Life Sciences sit within the diversified materials conglomerate category, leveraging broader industrial portfolios to sustain closure market participation.
| Leading Market Players |
|---|
| West Pharmaceutical Services |
| AptarGroup |
| Datwyler Holding |
| Saint-Gobain Performance Plastics |
| DWK Life Sciences |
| VWR International |
| The Plasticoid Company |
| Stelmi Italia |
| Jiangsu Hualan New Pharmaceutical Material |
| Others |
Value Network & Pricing Analysis
Backward integration into halobutyl rubber compounding anchors both supply security and pricing power for sleeve rubber stopper converters, as captive feedstock control insulates qualified suppliers from petrochemical refiner allocation volatility while supporting premium positioning in biologics-grade closure markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates platinum-cured silicone formulations for biologics from coated halobutyl for sterile injectables and uncoated commodity butyl for generic applications. Price differentiation hinges on FDA extractables validation tier and volume scale, with multi-year sole-source contracts commanding 15-30% premiums over spot procurement. Cost compression in the economy tier intensifies as Chinese converters expand coated capacity. Contract manufacturing organizations exhibit highest price sensitivity; Swiss and German biologics manufacturers show lowest sensitivity due to regulatory qualification switching costs.
Supply Chain Analysis
Domestic-content mandates in the United States and India are reshaping sourcing patterns, with IRA domestic manufacturing provisions and India's PLI scheme incentivizing localized halobutyl rubber conversion. Feedstock supply concentrates in Germany, China, and the United States where petrochemical refiners produce specialty bromobutyl and chlorobutyl grades. Raw material dependencies rest on halobutyl rubber, fluoropolymer coating resins, and platinum catalyst systems. Single-source vulnerability around plasma deposition equipment creates qualification bottlenecks. Distribution runs through pharmaceutical packaging distributors and direct contracts with parenteral drug manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sleeve rubber stoppers market functions as a stable compounder, with regulatory qualification barriers and biologics manufacturing expansion sustaining predictable returns across the analysis window.
For Market Incumbents: Extend coating capability investments to capture platinum-cured silicone displacement in lyophilized vial applications. Consolidate supplier relationships with CDSCO-registered Indian contract manufacturers before domestic converters achieve ICH-aligned validation. Backward integration into halobutyl rubber compounding defends margin position against feedstock allocation constraints from limited petrochemical refiners. For New Entrants and Emerging Players: Contract manufacturing organizations in India represent the most penetrable channel partner type, as PLI scheme expansion and CDSCO regulatory alignment create demand for qualified closure suppliers without established incumbent relationships. Target food and beverage laboratory equipment segments where barrier specifications sit below pharmaceutical extractables thresholds. Pursue private-label partnerships with regional pharmaceutical packaging distributors as the primary go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale coating specialists because EMA Annex 1 and FDA extractables guidelines are extending validation timelines and concentrating procurement among qualified suppliers with integrated capabilities. Five-to-ten year viability frames around regulatory compliance rather than technology disruption. Acquisition targets should demonstrate validated fluoropolymer lamination and statistical process control for lot-to-lot uniformity. Watch for FDA-EMA protocol alignment on container closure integrity testing as the inflection indicator for qualification burden shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halobutyl Compounding | Captive feedstock control insulates margin from petrochemical refiner allocation volatility. |
| Platinum-Cured Silicone Capacity Addition | Addresses peroxide-cured elastomer limitations in high-value therapeutic categories. |
| Ready-to-Use Format Certification | Pre-washed, pre-assembled systems command price premiums in biologics applications. |
| CDSCO Regulatory Alignment Investment | Qualification for India's PLI-supported injectable manufacturing expansion. |
| Fluoropolymer Coating Metrology Expansion | Statistical process control for lamination uniformity satisfies EMA Annex 1 particulate mandates. |
Research Methodology
Direct dialogue with fill-finish operations managers, regulatory affairs leads at parenteral drug manufacturers, procurement directors at contract manufacturing organizations, and quality engineering heads at elastomer converters grounded the qualitative foundation. Secondary validation drew from FDA 483 observation databases, EMA inspection findings, USP Chapter 381 revision drafts, and customs trade data on halobutyl rubber imports. Bottom-up and top-down triangulation reconciled unit volume estimates with value aggregation across product type, application, formulation, and industry vertical segments.
Bottom-up modeling anchored volume projections to parenteral drug manufacturing capacity expansion across Germany, the United States, China, Switzerland, and India, while top-down validation checked aggregate revenue against pharmaceutical packaging spend patterns. Segmentation dimensions included elastomer chemistry, coating technology, delivery system integration level, and regional regulatory cluster. CAGRs derived from regression analysis of historical pharmaceutical packaging growth rates adjusted for biologics share expansion and prefilled syringe adoption curves. Forecast inputs incorporated NMPA alignment timelines with ICH standards and EMA Annex 1 implementation phases.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to halobutyl rubber feedstock allocation disruptions, FDA-EMA protocol divergence on container closure integrity testing, and Chinese environmental compliance enforcement reshaping regional supply. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Vietnam Plastic Caps and Closures Market
Caps and Closures
T-Top Closures Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Beverage Caps and Closures Market
Caps and Closures
Metal Closures Market
Caps and Closures
Magnetic Closure Box Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Poland Plastic Caps and Closures Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
IBC Caps Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Handheld Induction Cap Sealers Market
Caps and Closures
Spigot End Cap Market
Caps and Closures
Ribbed Closures Market
Caps and Closures
US Caps and Closure Market
Caps and Closures
Australia and New Zealand Plastic Caps and Closures Market