
 Russia Container Glass Market | 2026-2036
Russia Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Container Glass Market Insights
Buyer consolidation among Russian beverage conglomerates is repositioning procurement power toward fewer, larger contracts with container glass suppliers. Sisecam leverages its Anatolian manufacturing heritage to sustain furnace efficiency advantages across southern Russian distribution corridors. CHSZ Group anchors volume supply through its legacy position in the Central Federal District. Verallia competes on premium cosmetic and pharmaceutical glass specialization where defect tolerance standards exceed commodity benchmarks.
Russia container glass comprises silica-soda-lime formulations melted at 1500–1600°C and formed through blow molding or press-and-blow sequences to create hermetic, chemically inert vessels for liquid and semi-solid storage. The material's oxygen barrier properties and infinite recyclability without quality degradation make it indispensable for alcoholic beverages, injectable medicines, and volatile essential oils. Amber glass dominates pharmaceutical vial production where UV protection preserves active compound stability, while clear glass leads food and beverage bottle volumes driven by vodka and mineral water branding requirements. Blow molding commands capital investment concentration due to its flexibility across bottle geometries, though press-and-blow methods gain traction in standard-format pharmaceutical jars where dimensional precision reduces downstream filling line stoppages.
BIS-equivalent GOST standards and EAEU technical regulation TR CU 005/2011 govern container glass safety, migration limits, and labeling compliance across Russian customs territory. Rosstandart certification requirements shape furnace investment timelines and product qualification protocols for export-oriented manufacturers. Stakeholders must monitor EAEU packaging waste directive harmonization progress and its implications for post-consumer cullet collection infrastructure economics.
Market Dynamics
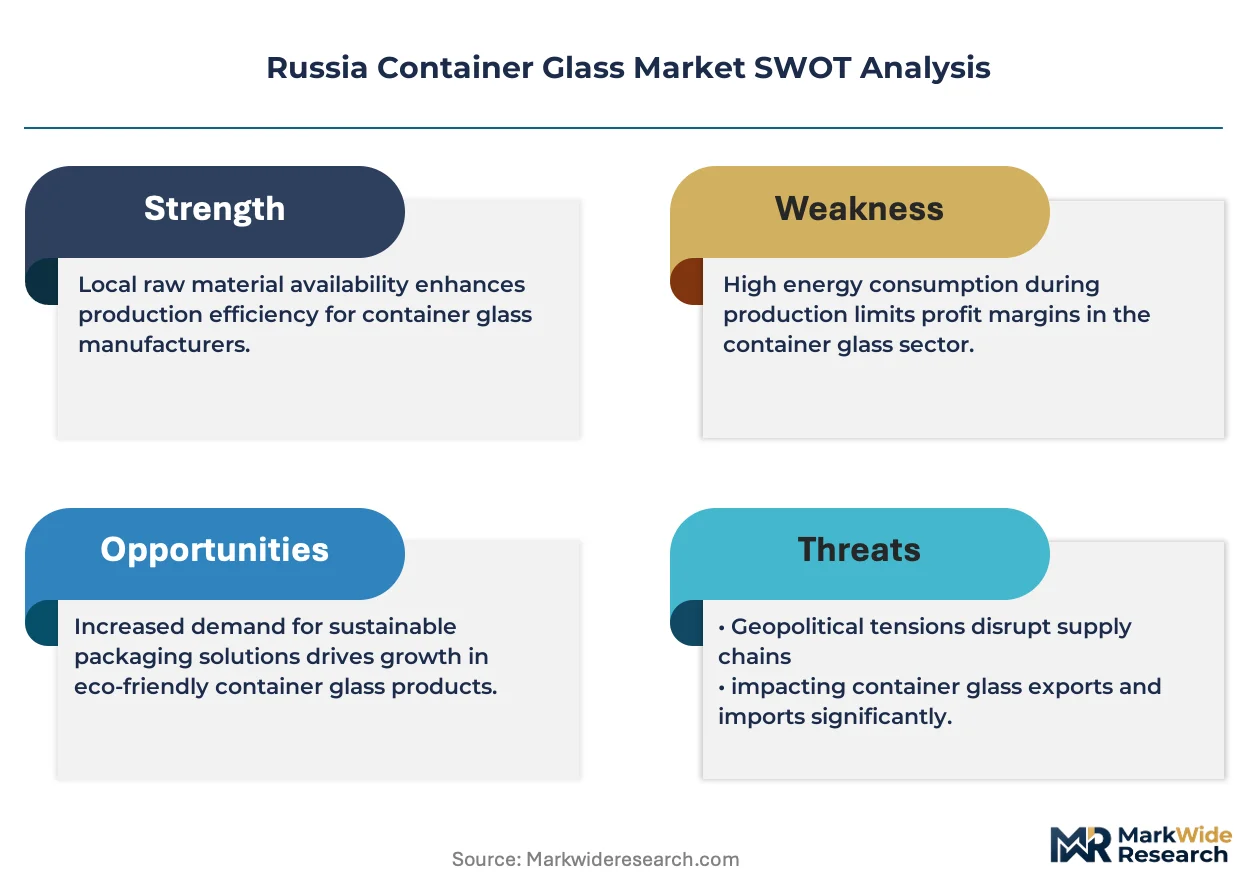
Furnace capacity consolidation across the Central Federal District is concentrating supply leverage among three dominant producers, compressing procurement timelines for mid-tier beverage bottlers while amplifying price volatility exposure during natural gas tariff adjustments.
Growth Catalysts
- EAEU TR CU 005/2011 migration limits:Tighter heavy metal thresholds are forcing domestic converters to upgrade melting furnaces, creating captive demand for compliant cullet processing infrastructure.
- Premium spirits packaging upgrade cycles:Vodka and brandy exporters in Moscow Oblast are specifying thicker wall weights and embossed shoulder designs to differentiate shelf presence in duty-free channels.
- Southern distribution corridor expansion:New rail-linked warehousing clusters near Rostov-on-Don are shortening lead times to Black Sea export terminals for container glass shipments.
Market Restraints
- Natural gas price volatility:Furnace operations consume 35-40% of production cost structures, exposing margins to Gazprom tariff revisions and seasonal heating-demand spikes.
- Single-source soda ash dependency:Bashkir Soda Company dominates domestic sodium carbonate supply, creating input concentration risk for glassmakers in the Volga Federal District.
- Aluminum can substitution in beer:Baltika and AB InBev Efes are accelerating metal packaging conversion for sub-premium SKUs, compressing clear glass volume in the 0.5L standard format.
Strategic Opportunities
- Far Eastern pharmaceutical glass underpenetration:Khabarovsk and Vladivostok lack dedicated amber glass furnace capacity, forcing drug manufacturers to source from distant Central District suppliers.
- Post-consumer cullet collection infrastructure:EAEU packaging waste directive harmonization is mandating extended producer responsibility schemes that reward vertically integrated recyclers.
- Lightweighting technology convergence:Narrow-neck press-and-blow systems combined with predictive thermal modeling are enabling 15-20% weight reduction in standard wine bottles without strength compromise.
Industry Challenges
- Refractory engineer talent scarcity:Specialized furnace maintenance expertise concentrates among retiring Soviet-era technical institutes, constraining rebuild cycle acceleration.
- GOST-R certification timeline compression:Rosstandart qualification protocols for new amber glass formulations require 18-24 month validation windows, delaying product line extensions.
- Legacy batch plant automation gaps:Silica and limestone handling facilities in older Central District sites lack real-time moisture monitoring, introducing compositional variance that elevates defect rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Container Glass Market |
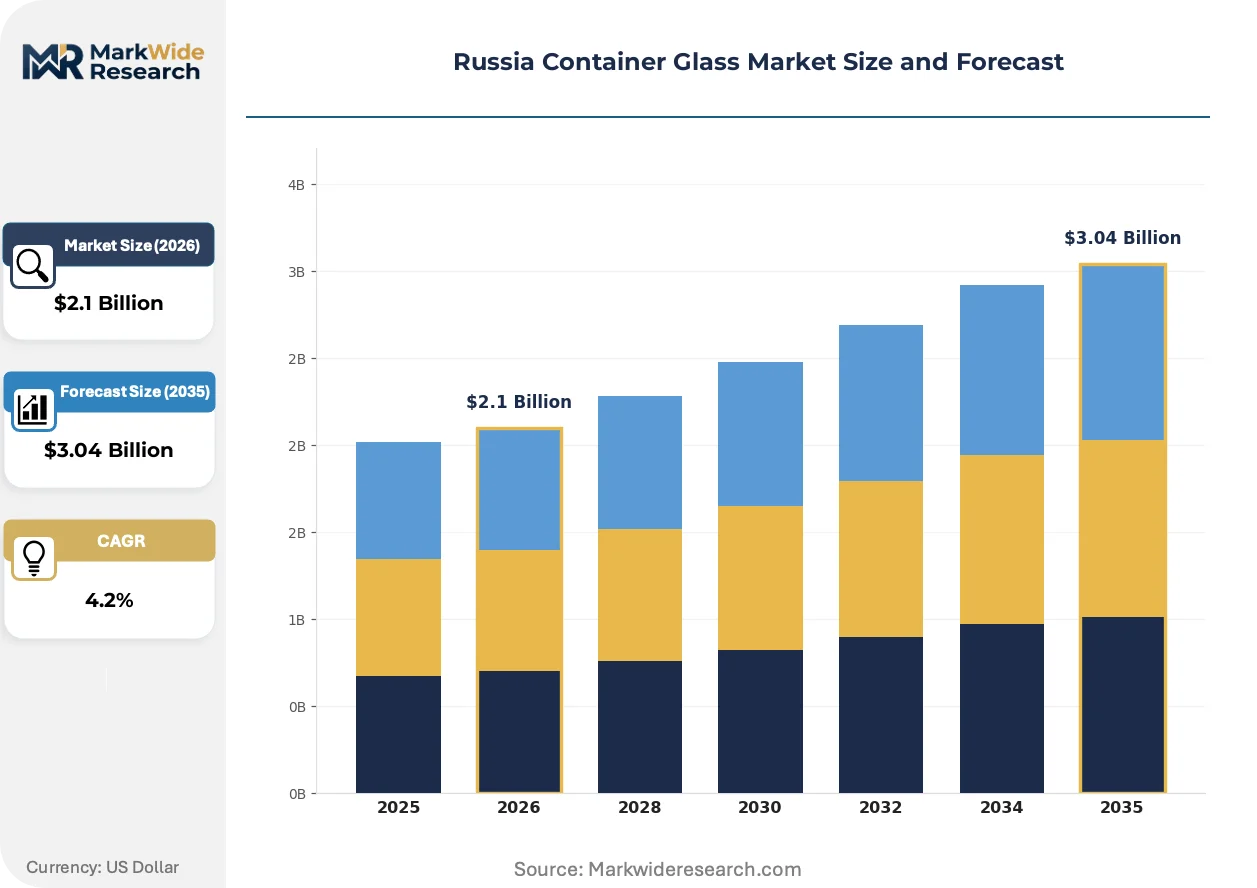
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.04 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Canisters End User: Food & Beverage, Pharmaceuticals, Cosmetics, Household Products Form: Clear Glass, Amber Glass, Green Glass, Frosted Glass Manufacturing Stage: Blow Molding, Press & Blow, Container Production, Cold End Processing |
| Companies Covered | CHSZ Group, Krasnoye Echo, Sisecam, Steklotech, Vladimir Glass, Verallia, Rusjam Steklotara Holding, Kavminsteklo, Avangard-Glass, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Container Glass Market Trends and Innovations
Digital furnace control architectures and cullet beneficiation advances are compressing energy intensity benchmarks while enabling faster color-change sequences that respond to shorter procurement cycles from consolidated beverage buyers.
Electro-boosted melting technology is unifying thermal efficiency gains with emissions reduction mandates. Sisecam and CHSZ Group are retrofitting regenerative furnaces with auxiliary electrode arrays to cut natural gas combustion by 12-18% in high-pull operations. This convergence is enabling faster furnace restart protocols after color campaigns, compressing downtime losses that previously deterred smaller-batch pharmaceutical runs.
Rosstandart is tightening GOST 32578-2013 surface defect tolerances for pharmaceutical vials, mandating automated optical inspection systems that reject containers with seed or stone inclusions exceeding 0.3mm. Injectable drug manufacturers in Moscow Oblast are qualifying suppliers against these benchmarks, forcing commodity glassmakers to segregate production lines or exit the segment. The compliance burden falls heaviest on legacy press-and-blow operations lacking machine vision integration.
Consolidated procurement contracts now specify outcome-based defect liability rather than per-batch rejection terms. Major beverage conglomerates in the Central Federal District are shifting from spot purchasing to multi-year framework agreements that penalize downstream filling-line stoppages caused by dimensional variance. This transfer of operational risk is compressing supplier margins while rewarding furnace operators with statistical process control capabilities that guarantee Cpk indices above 1.33 for critical bottle dimensions.
Russia Container Glass Market Segmentation
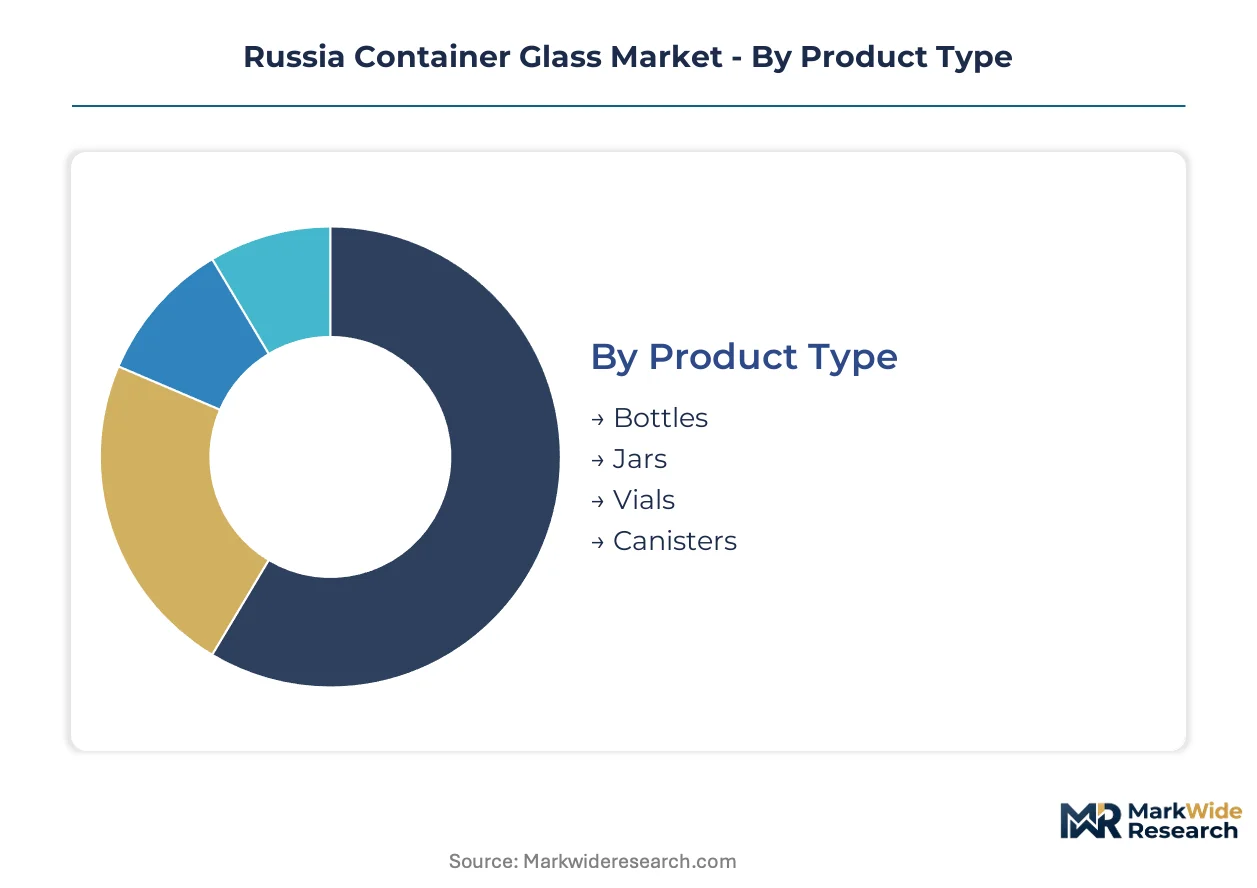
Segmentation reveals how capital deployment, regulatory compliance, and end-use specifications fragment procurement requirements across the Russian container glass value chain. Furnace configuration and color campaign flexibility determine which producers capture volume versus premium niche positions.
Product Type:
Bottles and jars command the heaviest furnace investment due to volume pull and dimensional precision requirements, while vials and canisters operate on shorter production runs with faster color-change protocols.
- Bottles:Standard neck-finish configurations dominate vodka, mineral water, and beer packaging in Moscow Oblast. Central Federal District beverage conglomerates specify wall-thickness tolerances within 0.5mm to prevent downstream filling-line pressure failures.
- Jars:Wide-mouth press-and-blow formats serve preserved foods and condiments. Rostov-on-Don distribution corridors shorten lead times for Black Sea export consignments of standard 0.5L and 1.0L capacities.
- Vials:Narrow-neck pharmaceutical formats require amber glass compliance with GOST 32578-2013 defect thresholds. Injectable drug manufacturers in Moscow Oblast mandate automated optical inspection for seed inclusions.
- Canisters:Large-format press-and-blow vessels store industrial chemicals and volatile essential oils. Chemical resistance specifications exceed food-grade benchmarks.
Most installed capacity flows through bottles. Expansion is steepest in vials.
End User:
Customer concentration patterns split procurement power between consolidated beverage bottlers and fragmented pharmaceutical qualifiers.
- Food & Beverage:Alcoholic and non-alcoholic bottlers in Moscow Oblast drive clear glass volume with standardized 0.5L and 0.7L formats. Baltika and AB InBev Efes are accelerating aluminum substitution in beer sub-premium SKUs.
- Pharmaceuticals:Injectable drug manufacturers demand amber glass with UV transmission below 10% at 290-450nm wavelengths. Rosstandart certification timelines stretch 18-24 months for new formulation qualification.
- Cosmetics:Premium fragrance and skincare brands specify frosted or decorated shoulder designs. Defect tolerance standards exceed commodity benchmarks.
- Household Products:Cleaning chemical packagers prioritize chemical inertness and hermetic seal integrity over aesthetic specifications.
Food & Beverage absorbs the majority of furnace throughput. Pharmaceuticals is climbing the fastest.
Form:
Color campaign economics and raw material sourcing differentiate margin profiles across glass compositions.
- Clear Glass:Silica-soda-lime formulations without colorants dominate vodka and mineral water branding requirements. Natural gas-fired furnaces melt batches at 1500-1600°C.
- Amber Glass:Iron-sulfur-carbon chemistry blocks UV transmission for pharmaceutical active compound stability. Khabarovsk and Vladivostok lack dedicated furnace capacity, forcing Far Eastern drug manufacturers to source from distant Central District suppliers.
- Green Glass:Chromium-iron colorants serve wine and olive oil segments. Smaller batch volumes constrain furnace utilization rates.
- Frosted Glass:Acid-etching or ceramic coating post-processing adds value for premium cosmetic positioning. Cold end processing capacity concentrates in legacy Central District sites.
Clear glass holds the largest installed base. Amber glass is gaining share fastest.
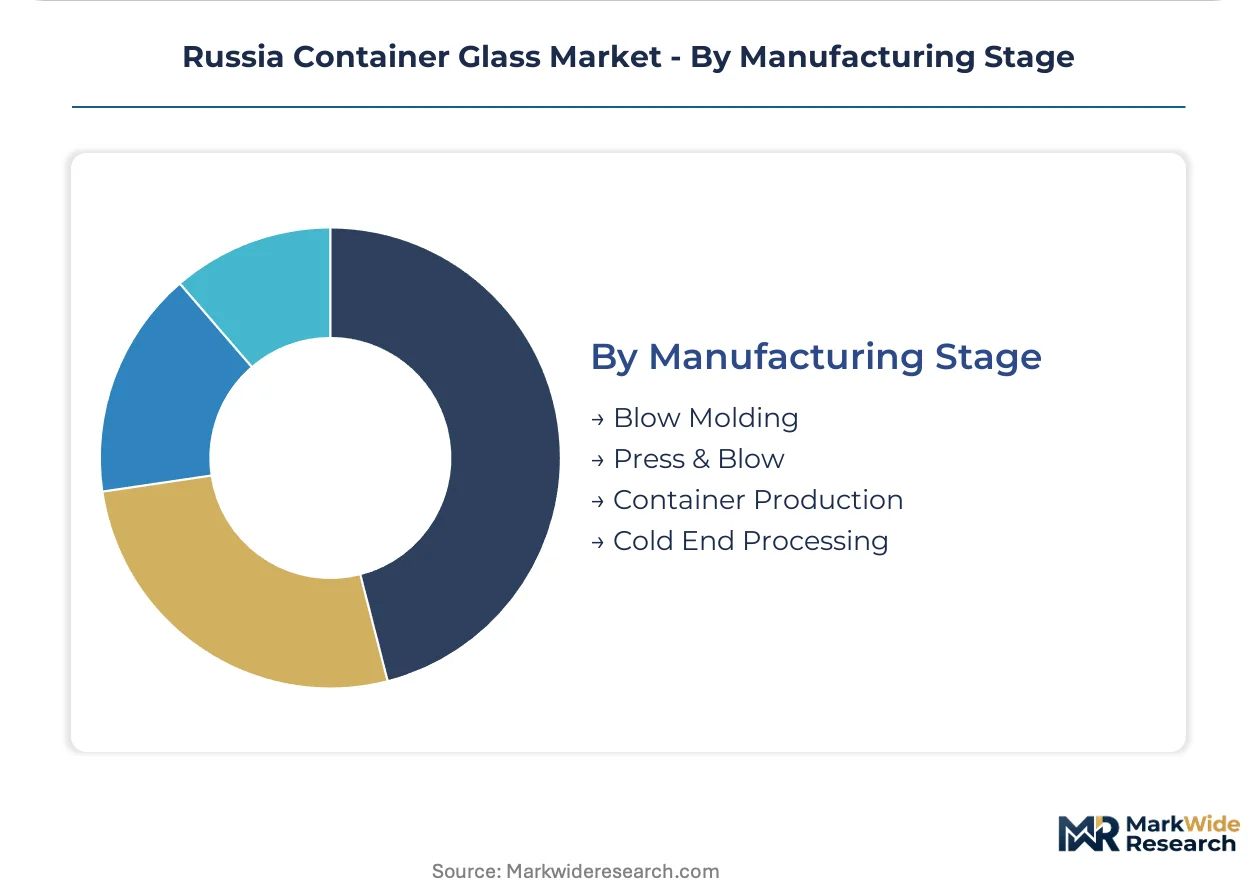
Manufacturing Stage:
Process automation intensity varies sharply between forming methods and downstream finishing.
- Blow Molding:IS machine flexibility accommodates diverse bottle geometries across beverage categories. Capital investment concentrates here due to volume scale.
- Press & Blow:Mechanical precision reduces dimensional variance in pharmaceutical jars and standard-format containers. Narrow-neck systems enable lightweighting without strength compromise.
- Container Production:Integrated furnace-to-forming operations dominate Central Federal District supply. Three producers control the majority of effective capacity.
- Cold End Processing:Inspection, decoration, and palletization complete the value chain. Automated optical systems now reject seed or stone inclusions exceeding 0.3mm under tightened GOST standards.
Container production commands the most capital deployment. Cold end processing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Unlike Germany's precision-engineered pharmaceutical glass corridor, Russia's container glass geography clusters around legacy Soviet industrial basins and emergent southern distribution nodes. This concentration pattern shapes procurement logistics and furnace investment cycles across distinct sub-regional economies.
Central Federal District
Moscow Oblast beverage conglomerates drive clear glass procurement for vodka and mineral water bottling. EAEU TR CU 005/2011 migration limit enforcement tightens heavy metal thresholds for suppliers serving this cluster. CHSZ Group anchors volume supply through legacy furnace positions in Dmitrov and Kirzhach, compressing procurement timelines for mid-tier bottlers.
Volga Federal District
Bashkir Soda Company's sodium carbonate dominance creates input concentration risk for glassmakers in this region. Rosstandart certification protocols stretch qualification windows for new amber formulations. Kazan and Ufa industrial zones host secondary forming operations feeding pharmaceutical and cosmetics segments with press-and-blow capacity.
Southern Federal District
Rostov-on-Don warehousing clusters shorten lead times to Black Sea export terminals for container glass shipments. Premium spirits producers in this corridor specify thicker wall weights and embossed shoulder designs for duty-free channel differentiation. Sisecam leverages Anatolian manufacturing heritage to sustain furnace efficiency advantages across southern Russian distribution networks.
Northwestern Federal District
St. Petersburg's port infrastructure supports import-dependent cullet beneficiation for amber glass production. Vladimir Glass operates legacy sites in this region serving food preservation jar demand. Cold end processing capacity concentrates here for acid-etching and ceramic coating post-processing of premium cosmetic containers.
Far Eastern Federal District
Khabarovsk and Vladivostok lack dedicated amber glass furnace capacity, forcing drug manufacturers to source from distant Central District suppliers. This underpenetration creates structural supply chain elongation for pharmaceutical packaging. Post-consumer cullet collection infrastructure remains nascent, constraining EAEU packaging waste directive compliance economics.
Russia Container Glass Market Competitive Landscape
Central Federal District producers anchor volume supply; southern corridor specialists hold distribution efficiency advantages. Three dominant furnace operators control effective capacity consolidation, compressing procurement timelines while amplifying price volatility exposure during natural gas tariff adjustments. Strategic archetypes split between scale-driven commodity suppliers, premium cosmetic and pharmaceutical specialists, and vertically integrated recyclers. Competitive moves concentrate on furnace rebuild cycles and multi-year framework agreements that transfer downstream filling-line stoppage risk.
Within the scale-driven tier, CHSZ Group and Rusjam Steklotara Holding occupy positions exemplifying legacy Soviet industrial consolidation. Sisecam represents cross-border manufacturing heritage leveraging southern distribution corridors. Verallia sits within the premium specialization archetype where defect tolerance standards exceed commodity benchmarks. Kavminsteklo and Avangard-Glass exemplify mid-tier regional fabricators serving fragmented food and beverage procurement.
| Leading Market Players |
|---|
| CHSZ Group |
| Krasnoye Echo |
| Sisecam |
| Steklotech |
| Vladimir Glass |
| Verallia |
| Rusjam Steklotara Holding |
| Kavminsteklo |
| Avangard-Glass |
| Others |
Pricing and Supply Chain Analysis
Refractory engineer scarcity in the Central Federal District widens labor-cost differentials between Soviet-legacy furnace sites and modernized southern corridors, stretching pricing-tier spreads across premium pharmaceutical glass and commodity beverage formats.
Pricing Analysis
Capacity additions in the Southern Federal District are reshaping price floors for standard clear glass bottles serving Black Sea export channels. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy cullet-blended tiers stratifies procurement contracts. Pricing pressure stems from natural gas tariff volatility compressing furnace operator margins. Mid-tier beverage bottlers exhibit highest price sensitivity due to consolidated buyer leverage, while injectable drug manufacturers accept premium positioning for GOST 32578-2013 certified amber glass.
Supply Chain Analysis
GOST-R certification timelines for new amber formulations gate supplier qualification, stretching 18-24 month validation windows that favor incumbent furnace operators. Manufacturing concentrates in Russia, Turkey, and Belarus within the EAEU customs territory. Raw material sourcing draws from Bashkir Soda Company sodium carbonate, Ukrainian silica sands, and domestic limestone deposits. Single-source soda ash dependency creates structural vulnerability for Volga Federal District glassmakers. Distribution runs through rail-linked warehousing clusters near Rostov-on-Don shortening lead times to Black Sea terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia container glass functions as a stable compounder where EAEU packaging safety regulations generate steady furnace upgrade demand across replacement cycles.
For Market Incumbents: Cement furnace efficiency advantages through electro-boosted melting retrofits that cut natural gas combustion in high-pull operations. Deepen captive cullet processing infrastructure ahead of extended producer responsibility mandate enforcement. Aluminum can substitution in beer sub-premium SKUs threatens clear glass volume, requiring accelerated lightweighting technology deployment to defend commodity positioning. For New Entrants and Emerging Players: Launch via dedicated amber glass furnace capacity targeting Far Eastern pharmaceutical underpenetration in Khabarovsk and Vladivostok. The most penetrable segment is injectable drug packaging where distant Central District sourcing elongates supply chains. Qualify against tightened GOST 32578-2013 defect thresholds through automated optical inspection integration as primary go-to-market angle. For Investors and Strategic Acquirers: Beverage conglomerates with backward integration appetite represent the most active acquirer category in this space. Five-to-ten year viability hinges on EAEU waste directive harmonization progress rewarding vertically integrated recyclers. Acquisition targets should display statistical process control capabilities guaranteeing Cpk indices above 1.33. Watch for Gazprom tariff revision announcements as margin inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Furnace Electro-Boost Retrofit | Sisecam and CHSZ Group deployments cut natural gas combustion 12-18% in high-pull operations. |
| Amber Glass Capacity Expansion | Far Eastern pharmaceutical demand outruns local supply, forcing sourcing from distant Central District suppliers. |
| Cullet Beneficiation Infrastructure | EAEU packaging waste directive harmonization mandates extended producer responsibility schemes favoring integrated recyclers. |
| Automated Optical Inspection Integration | Rosstandart's tightened GOST 32578-2013 surface defect tolerances mandate machine vision for pharmaceutical qualification. |
| Multi-Year Framework Agreements | Central Federal District beverage conglomerates shift procurement risk downstream through outcome-based defect liability terms. |
Research Methodology
Coverage spans the Central, Volga, Southern, Northwestern, and Far Eastern Federal Districts, with primary inputs from each. The research combines interviews with furnace operations managers, beverage procurement directors, pharmaceutical packaging engineers, and Rosstandart certification specialists alongside secondary validation. Secondary sources include EAEU technical regulation filings, GOST standard revision notices, Gazprom tariff disclosure archives, and customs trade flow records. Bottom-up furnace capacity modeling triangulates against top-down end-use demand aggregation.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include product type, end-user industry, glass composition, and manufacturing process stage. CAGRs derive from furnace pull capacity forecasts cross-referenced with beverage bottling line expansion announcements and pharmaceutical packaging qualification pipelines. Natural gas price scenarios and EAEU regulatory timeline assumptions feed sensitivity testing.
Several conditions sit outside the modeled scope, including geopolitical trade restriction escalations, abrupt furnace failure events, and EAEU membership composition changes. Forecasts reflect documented assumptions about regulatory enforcement pace and energy tariff trajectories. A model refresh is warranted upon material change in Gazprom export tariff schedules or EAEU packaging waste directive implementation deadlines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
Glass Growlers Market
Glass Packaging
Dosing Bottles Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Asia - Pacific Glass Bottles and Containers Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
UAE Container Glass Market
Glass Packaging
Global Glass Bottles and Containers Market
Glass Packaging
Glass Veil Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Dominican Republic Container Glass Market