
 Glass Bottle Molds Market | 2026-2036
Glass Bottle Molds Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Bottle Molds Market Analytics
Tool-and-die engineering talent scarcity is reorganizing competitive dynamics across the glass bottle molds sector. Heye International GmbH leverages its German engineering base to sustain precision mold exports worldwide. Changshu Weiheng Mould Manufacture Co. Ltd. anchors high-volume production for Asian beverage manufacturers through cost-optimized casting operations. Omco International N.V. competes on multi-cavity mold configurations that reduce per-unit glass forming cycle times for European distillers.
Glass bottle molds are precision-machined metal tools—typically cast iron or nickel-alloy steel with integrated cooling channels—that shape molten glass into container form through blow, press, or injection processes, with cavity tolerances often held within 0.05 mm to ensure dimensional repeatability across millions of cycles. Blow molds dominate current installed capacity due to their ubiquity in beverage and pharmaceutical container production, while stretch molds command premium pricing from cosmetic brands demanding complex asymmetric geometries. Soda lime glass applications generate the largest volume demand for mold replacements, though borosilicate glass segments require specialized heat-resistant mold alloys that sustain wider margin pools for technical specialists.
FDA food-contact surface regulations and EU REACH restrictions on hexavalent chromium plating are elevating compliance costs for mold coating suppliers and narrowing approved material lists. China's GB standards for industrial mold steel grades and SAMR quality certification requirements shape import eligibility for foreign equipment entering domestic glassworks. Stakeholders must monitor evolving alloy substitution timelines and regional certification divergence when allocating R&D budgets across manufacturing footprints.
Market Dynamics
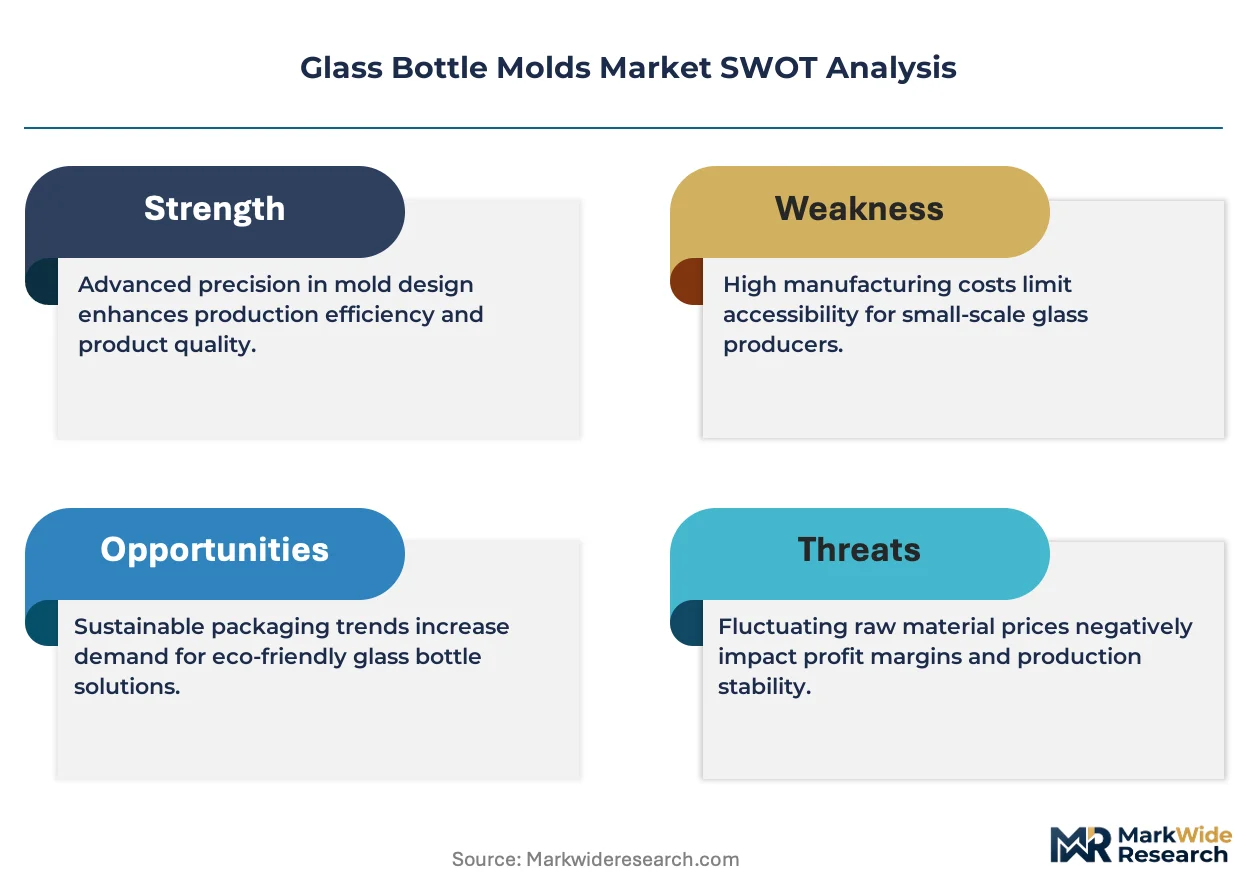
REACH compliance deadlines in Europe and FDA food-contact material rules are compressing approved alloy lists for mold surfaces, forcing foundries to reformulate nickel-alloy compositions and validate new coating chemistries before existing plating processes sunset.
Growth Catalysts
- Premium spirits bottling expansion:Craft distillers in Germany and Italy are commissioning multi-cavity blow molds for limited-edition releases, pulling specialized tooling orders toward European engineering centers.
- REACH substance restrictions:ECHA's tightening limits on hexavalent chromium in surface coatings are accelerating R&D into trivalent alternatives and physical vapor deposition finishes for mold durability.
- Stretch mold adoption:Cosmetic brands in France and South Korea are specifying asymmetric bottle geometries that require precision stretch-blow tooling, expanding addressable market for complex cavity specialists.
Market Restraints
- Nickel price volatility:Mold alloy feedstock costs fluctuate with LME nickel trading, squeezing margin predictability for foundries locked into annual supply contracts with glassworks.
- Tool-and-die engineering scarcity:Germany and Japan face acute shortages of precision machinists capable of holding 0.05 mm cavity tolerances, capping expansion velocity for high-specification mold exporters.
- Alternative packaging substitution:Lightweight PET and aluminum can formats are capturing share in mass-market beverage segments, reducing replacement mold demand for standardized soda lime containers.
Strategic Opportunities
- Pharmaceutical serialization compliance:EU MDR and FDA track-and-trace mandates are requiring mold-integrated micro-embossing for lot codes, opening premium retrofit services for existing installed base.
- Borosilicate technical glass expansion:Laboratory and cookware segments in China are scaling output, creating demand for heat-resistant mold alloys that command wider margin pools than commodity soda lime tooling.
- Digital twin integration:Convergence of computational fluid dynamics with additive manufacturing is enabling rapid prototyping of conformal cooling channels, compressing new product introduction timelines for mold designers.
Industry Challenges
- Certification timeline compression:SAMR quality certification for foreign equipment entering Chinese glassworks requires extensive documentation cycles that delay revenue recognition for export-focused manufacturers.
- Legacy cooling channel retrofit complexity:Existing cast iron mold inventories lack integrated thermal management, forcing glassworks to choose between costly replacement or suboptimal cycle times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Bottle Molds Market |
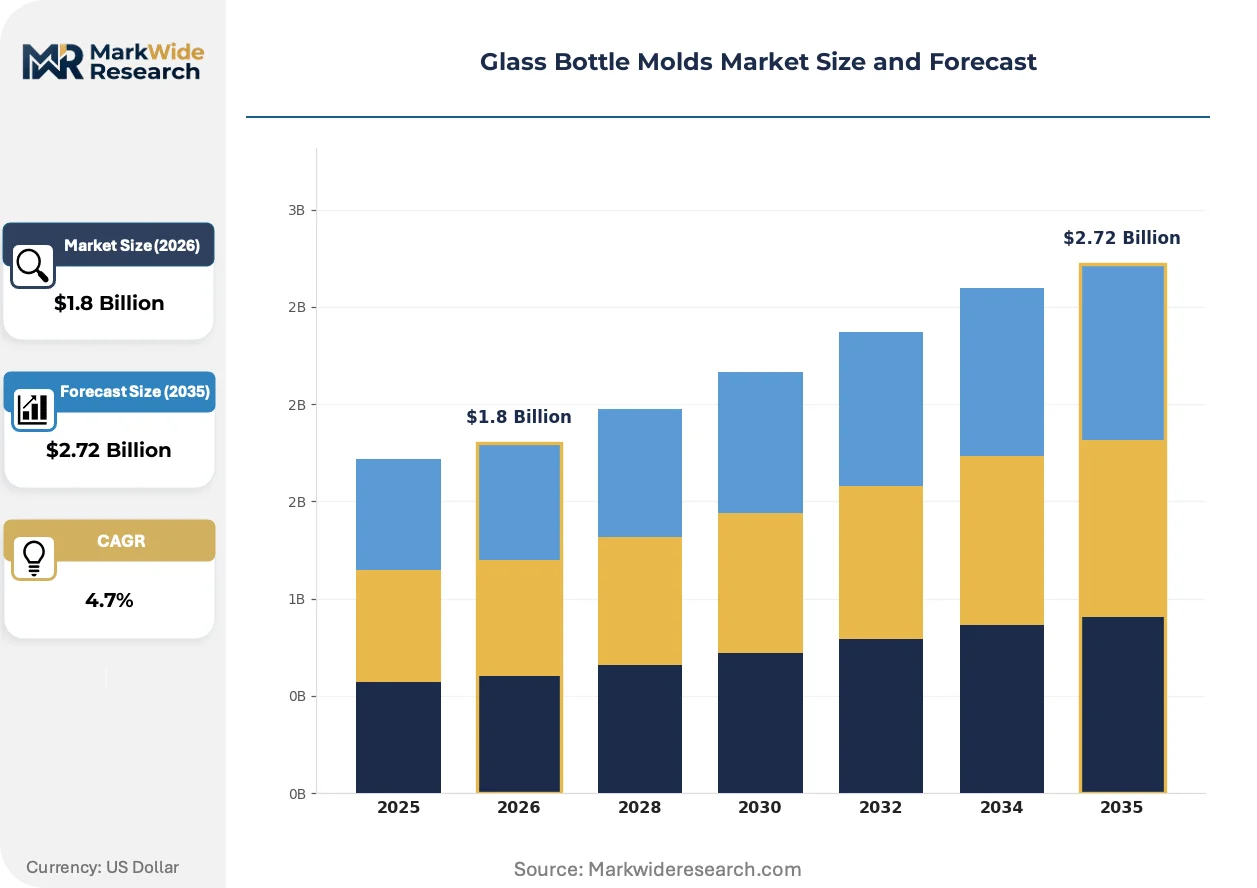
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Molds, Press Molds, Injection Molds, Stretch Molds Application: Food & Beverages, Pharmaceuticals, Cosmetics, Household Products End User: Beverage Manufacturers, Cosmetic Companies, Pharmaceutical Firms, Packaging Suppliers Material: Soda Lime Glass, Borosilicate Glass, Lead Crystal Glass, Aluminosilicate Glass |
| Companies Covered | Owens-Illinois, Inc., Heye International GmbH, Emhart Glass SA, Bucher Emhart Glass, Omco International N.V., Changshu Weiheng Mould Manufacture Co. Ltd., Changshu Jianhua Mould Technology Co. Ltd., Jinggong Mould Manufacturing Co. Ltd., Rayotek Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Bottle Molds Market Evolving Landscape
Digital manufacturing techniques and regulatory chemistry shifts are restructuring how mold designs move from specification to production floor, with cooling efficiency and surface compliance emerging as the primary axes of technical differentiation.
Additive-manufactured conformal cooling channels are supplanting straight-drilled passages in high-cavity blow molds. European pharmaceutical container specialists are adopting these designs fastest, cutting glass forming cycle times by enabling uniform heat extraction that conventional drilling cannot achieve. The technology is compressing competitive advantage toward foundries with in-house metal printing capability.
EU REACH annex XVII amendments restricting hexavalent chromium plating are forcing mold surface treatment suppliers to validate trivalent chromium and ceramic-based alternatives. Industrial consequence includes extended qualification periods for new coating chemistries and narrowed approved vendor lists for European glassworks. Distillers and cosmetic brands with premium positioning are absorbing higher per-cavity costs to maintain surface finish standards.
Consolidated procurement by multinational beverage groups is disintermediating regional mold distributors. Direct engineering relationships between Changshu and Shanghai-based glassworks, or between Heye and Rhine-Ruhr container manufacturers, are replacing arm's-length purchasing through trading houses. This pattern is most visible in China and Germany where output concentration supports dedicated account engineering models.
Glass Bottle Molds Market Segmentation
Mold geometry complexity and thermal management requirements create divergent margin structures across product categories. End-use certification demands and alloy specifications further stratify profitability pools, forcing suppliers to prioritize segments where technical barriers protect pricing power.
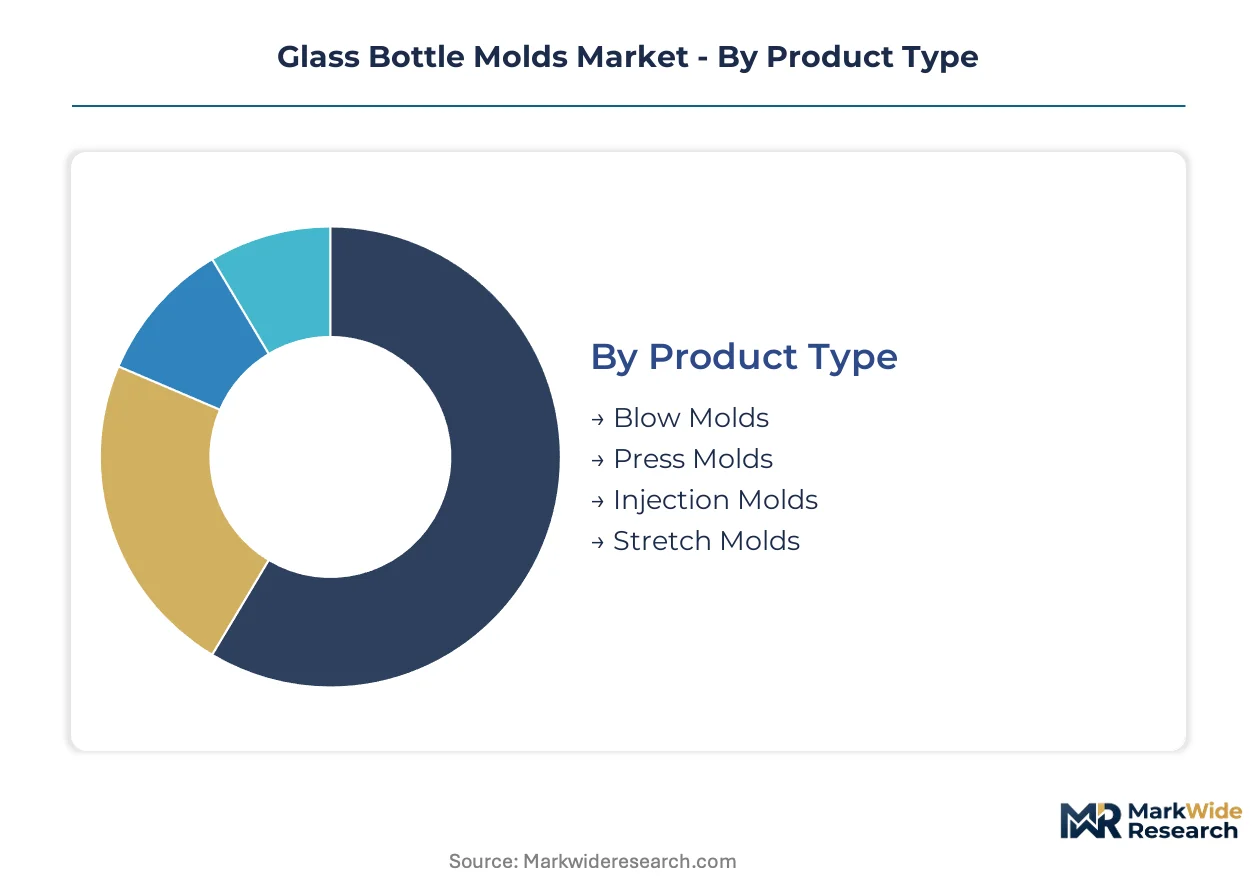
Product Type:
Wider margin pools concentrate in multi-cavity stretch configurations where cosmetic brands pay premiums for asymmetric cavity precision.
- Blow Molds:Cast iron or nickel-alloy steel tools with integrated cooling channels dominate beverage and pharmaceutical container production. Demand concentrates in Germany and Italy where craft distillers commission multi-cavity configurations for limited-edition spirit releases, pulling specialized orders toward European engineering centers.
- Stretch Molds:Precision-machined tooling enables complex asymmetric bottle geometries through controlled axial elongation. Cosmetic brands in France and South Korea specify these configurations, expanding addressable market for cavity specialists who command premium pricing.
- Press Molds:Mechanical compression tooling for thick-walled containers and technical glassware.
- Injection Molds:Direct glass injection systems for precision medical and laboratory applications.
The dominant share belongs to Blow Molds, while Stretch Molds is closing the gap fastest.
Application:
Regulatory compliance intensity varies sharply across end-uses, with pharmaceutical serialization mandates creating retrofit service opportunities unavailable in commodity segments.
- Pharmaceuticals:Mold-integrated micro-embossing for EU MDR and FDA track-and-trace lot codes. European container specialists adopt additive-manufactured conformal cooling fastest, cutting cycle times through uniform heat extraction.
- Cosmetics:Asymmetric geometry requirements drive stretch-blow tooling adoption. Premium positioning absorbs higher per-cavity costs to maintain surface finish standards under REACH coating restrictions.
- Food & Beverages:High-volume soda lime container production with standardized replacement cycles.
- Household Products:Durable goods molding with less stringent dimensional tolerances.
Pharmaceuticals commands the highest unit margins, though Cosmetics demonstrates the steepest expansion trajectory.
End User:
Procurement consolidation patterns reshape channel economics, with direct engineering relationships displacing distributor intermediation.
- Beverage Manufacturers:Consolidated multinational groups drive high-volume mold procurement. Direct relationships between foundries and Shanghai-based glassworks replace arm's-length purchasing through trading houses.
- Cosmetic Companies:Brand-led specification of asymmetric geometries requires dedicated account engineering.
- Pharmaceutical Firms:Serialization compliance creates premium retrofit demand for existing installed base.
- Packaging Suppliers:Contract manufacturing relationships with standardized tooling requirements.
Beverage Manufacturers holds the largest volume position, while Pharmaceutical Firms is gaining share fastest on compliance-driven retrofit demand.
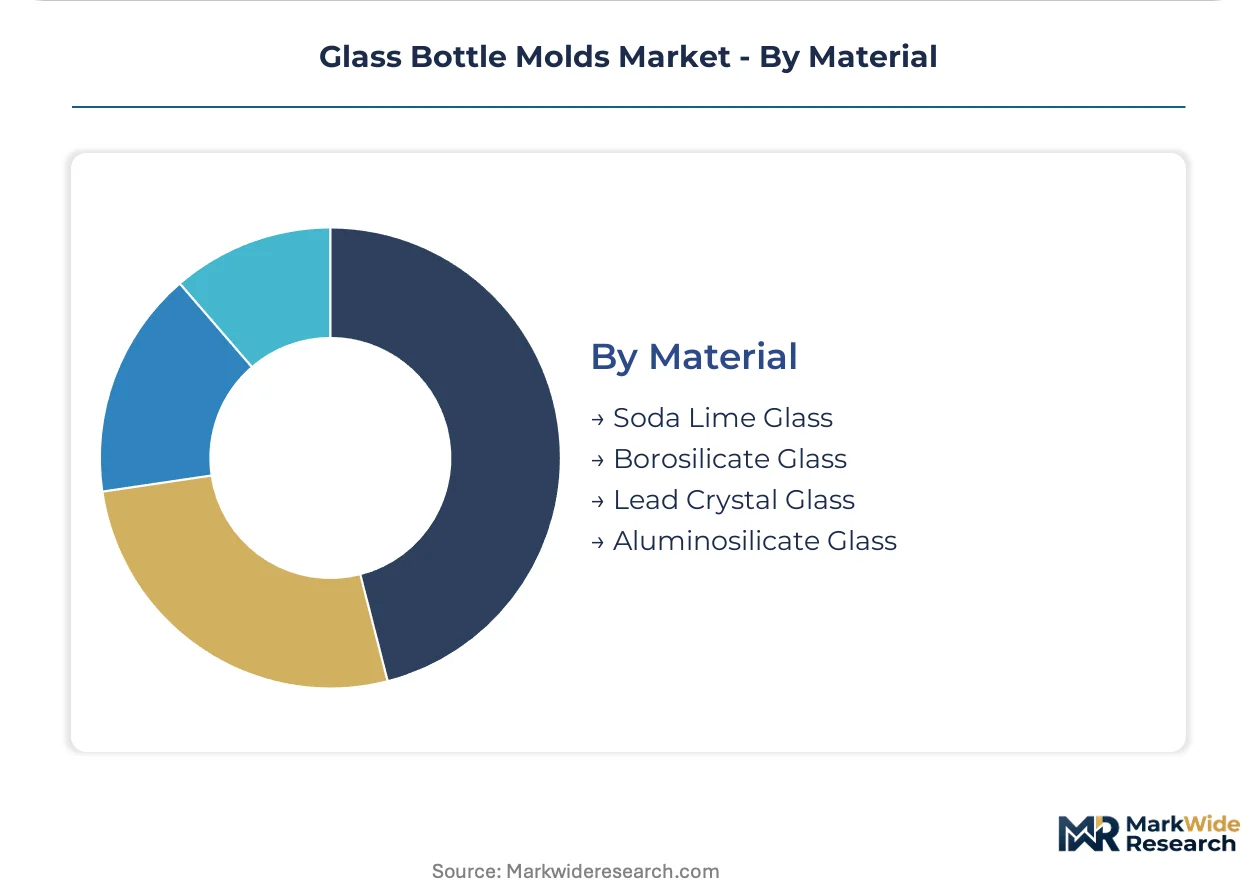
Material:
Heat resistance specifications determine alloy selection and foundry capability requirements, with technical glass segments commanding specialist premiums.
- Soda Lime Glass:Standard container glass generating largest replacement volume demand. Lightweight PET substitution captures mass-market beverage share, reducing mold replacement frequency for standardized formats.
- Borosilicate Glass:Laboratory and cookware segments in China scale output, creating demand for heat-resistant mold alloys that sustain wider margin pools than commodity tooling.
- Lead Crystal Glass:Decorative and luxury applications with specialized surface finish requirements.
- Aluminosilicate Glass:High-temperature technical applications requiring advanced thermal management.
Soda Lime Glass maintains the dominant installed base, while Borosilicate Glass is expanding most quickly on technical glass output growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Italian engineering centers where precision mold tolerances command premiums, while cost-optimized production in China's eastern provinces competes on volume terms with narrower margin capture.
Germany
Craft distillers in the Rhine-Ruhr corridor commission multi-cavity blow molds for limited-edition spirit releases, pulling specialized tooling orders toward domestic engineering centers. ECHA's REACH annex XVII amendments on hexavalent chromium plating force foundries to reformulate surface coating chemistries ahead of compliance deadlines. Bavaria's precision machining clusters face acute tool-and-die engineering scarcity that caps expansion velocity for high-specification mold exporters.
China
Laboratory and cookware segments scale borosilicate glass output, creating demand for heat-resistant mold alloys that sustain wider margin pools than commodity soda lime tooling. SAMR quality certification requirements for foreign equipment entering domestic glassworks impose extensive documentation cycles that delay revenue recognition. The Yangtze River Delta manufacturing belt anchors high-volume production for Asian beverage manufacturers through cost-optimized casting operations.
Italy
Premium spirits bottlers expand mold procurement for asymmetric limited-release formats, sustaining demand for complex cavity specialists. EU REACH substance restrictions on hexavalent chromium accelerate R&D investment into trivalent alternatives and physical vapor deposition finishes. Northern Italian glassworks clusters concentrate container output where direct engineering relationships with foundries displace arm's-length distributor purchasing.
France
Cosmetic brands specify asymmetric bottle geometries requiring precision stretch-blow tooling, expanding addressable market for cavity specialists who command premium pricing. ECHA compliance deadlines compress approved alloy lists for mold surfaces, forcing reformulation of nickel-alloy compositions. The Île-de-France region hosts pharmaceutical container specialists adopting additive-manufactured conformal cooling designs fastest.
South Korea
Cosmetic manufacturers drive stretch mold adoption for complex asymmetric geometries in premium skincare and fragrance packaging. The country's national industrial standards body aligns mold steel grade specifications with evolving export market requirements. Seoul-Incheon manufacturing corridors concentrate technical glass demand that pulls specialized tooling orders toward regional engineering centers.
Glass Bottle Molds Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with German and Japanese engineering houses commanding premium positioning on precision tolerances while Chinese foundries capture volume share through scale-optimized operations. The market structures around a tiered competitive map where multi-cavity complexity specialists, regional volume producers, and integrated glass equipment suppliers occupy distinct profit pools. Three archetypes dominate: precision engineering specialists, high-volume casting operators, and full-line glass equipment integrators. Competitive moves concentrate on direct account engineering relationships with multinational beverage groups and additive manufacturing capability acquisition for conformal cooling channel integration.
Within the precision engineering tier, Heye International GmbH and Omco International N.V. exemplify European mold specialists who anchor premium positioning through tolerance-holding expertise. Changshu Weiheng Mould Manufacture Co. Ltd. occupies a position among scale-driven Chinese fabricators serving high-volume Asian beverage procurement. These three represent the competitive spectrum from precision-specialist to cost-optimized production without claiming specific strategic actions or financial performance.
| Leading Market Players |
|---|
| Owens-Illinois, Inc. |
| Heye International GmbH |
| Emhart Glass SA |
| Bucher Emhart Glass |
| Omco International N.V. |
| Changshu Weiheng Mould Manufacture Co. Ltd. |
| Changshu Jianhua Mould Technology Co. Ltd. |
| Jinggong Mould Manufacturing Co. Ltd. |
| Rayotek Scientific Inc. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between German precision foundries and Rhine-Ruhr glassworks lock in nickel-alloy feedstock access while stabilizing per-cavity pricing visibility across multi-year mold procurement cycles. These arrangements insulate premium engineering centers from spot nickel volatility on the LME while committing buyers to minimum volume thresholds that sustain foundry utilization rates.
Pricing Analysis
The customization-premium spread between configured-to-order multi-cavity stretch molds and standardized blow mold catalog offerings spans three performance tiers. Project-based pricing dominates complex cavity work where cosmetic brands specify asymmetric geometries, while per-unit transactional structures govern soda lime container replacement cycles. Price differentiation hinges on REACH-compliant surface certification grade and volume scale, with pharmaceutical serialization retrofits commanding the widest premiums. Cost compression in commodity soda lime segments is intensifying because PET substitution captures mass-market beverage share. Beverage manufacturers exhibit highest price sensitivity due to consolidated procurement leverage, while cosmetic houses absorb premium positioning costs.
Supply Chain Analysis
Germany, Italy, and China's eastern provinces anchor precision mold fabrication and high-volume casting respectively. Nickel-alloy steel feedstock, specialized coating chemistries, and precision machining capacity constitute critical input dependencies. Supply chain risk centers on single-source vulnerability for trivalent chromium plating validation under ECHA deadlines. Distribution runs through direct engineering relationships that displace regional distributor intermediation, particularly visible in Shanghai-Rhine-Ruhr manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Glass bottle molds sit in early-cycle expansion as pharmaceutical serialization mandates and borosilicate technical glass scaling create retrofit and new-build demand tailwinds that outpace commodity container replacement softness.
For Market Incumbents: Fortify precision engineering differentiation by embedding additive manufacturing capability for conformal cooling channels and securing SAMR pre-certification documentation for Chinese market access. Defend against Chinese volume competitors by anchoring multi-cavity complexity expertise that commands premium positioning in European spirits and cosmetic segments. For New Entrants and Emerging Players: Retrofit service capacity for legacy mold installed base represents the most penetrable white-space where incumbents under-serve pharmaceutical compliance timelines. Target EU MDR and FDA track-and-trace retrofit demand with rapid-turn micro-embossing integration services. Pursue borosilicate technical glass foundry partnerships in China's Yangtze Delta as the go-to-market angle for heat-resistant alloy specialization. For Investors and Strategic Acquirers: Precision-cavity specialists with in-house metal printing capability and validated trivalent coating chemistries constitute the priority acquisition archetype for medium-term consolidation. Long-term viability frames around additive manufacturing convergence and regulatory coating substitution timelines. Monitor ECHA enforcement patterns on hexavalent chromium sunset dates as the inflection signal for coating chemistry validation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Integration | In-house metal printing capability compresses conformal cooling channel prototyping timelines for pharmaceutical container specialists. |
| REACH-Compliant Coating Validation | Trivalent chromium and PVD finish qualification ahead of ECHA deadlines secures approved vendor status with European glassworks. |
| Direct Account Engineering Model | Consolidated beverage procurement patterns reward dedicated technical relationships that displace distributor intermediation. |
| Pharmaceutical Serialization Retrofit Services | Mold-integrated micro-embossing capability captures EU MDR and FDA track-and-trace compliance premiums. |
| Borosilicate Alloy Specialization | Heat-resistant mold steel expertise commands wider margin pools from laboratory and cookware technical glass scaling in China. |
Research Methodology
Desk research of customs trade databases, SEC filings from glass equipment manufacturers, and ECHA regulatory guidance documents preceded structured interviews with mold foundry operations managers, beverage procurement directors at multinational groups, pharmaceutical container engineering leads, and precision machining cluster supervisors. Primary fieldwork validated alloy substitution timelines and coating chemistry qualification cycles against secondary sourcing from industry association technical bulletins and SAMR certification procedure manuals. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects. Segmentation modeling spans mold geometry complexity, thermal management specification, end-use certification intensity, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and net new capacity formation patterns. Forecast inputs incorporate nickel LME price trajectory assumptions and REACH compliance deadline enforcement probability.
Forecasts assume regulatory continuity in EU REACH annex XVII amendments and FDA food-contact material rules; material policy shifts would require re-modeling of coating chemistry substitution timelines and approved alloy lists. Forecasts reflect assumptions on SAMR documentation cycle durations and ECHA enforcement resourcing. Recalibration cycles align with material shifts in nickel price volatility patterns and pharmaceutical serialization mandate implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Angola Container Glass Market
Glass Packaging
Brazil Container Glass Market
Glass Packaging
Glass Frosting for Packaging Market
Glass Packaging
Cosmetic and Perfume Glass Packaging Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
Global Glass Packaging Rectifier Diode Market
Glass Packaging
Asia Pacific Pharmaceutical Glass Packaging Market
Glass Packaging
United Kingdom Container Glass Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Paragon Glass Jar Market
Glass Packaging
Argentina Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Thin Wall Glass Container Market