
 Peru Container Glass Market | 2026-2036
Peru Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Peru Container Glass Market Insights
Leasing arrangements for furnace rebuilds and asset-light production partnerships are reshaping competitive entry in Peruvian container glass. Owens-Illinois Inc. leverages its regional furnace network to sustain bulk supply contracts with Andean beverage producers. Ardagh Group S.A. competes through specialized lightweight bottle designs that reduce transport costs across Peru's mountainous logistics corridors. Vitro S.A.B. de C.V. anchors its position via backward integration into silica sand sourcing from northern Peruvian quarries.
Container glass comprises silica sand, soda ash, limestone, and cullet melted at temperatures exceeding 1,500°C to form chemically inert, impermeable vessels for liquid and solid storage. The material's non-reactive surface and infinite recyclability make it indispensable for preserving flavor integrity and extending shelf life in food, pharmaceutical, and cosmetic applications. Bottles dominate Peru's product mix due to entrenched demand from pisco distillers and craft beer brands, while jars capture expanding margin pools in artisanal food exports. The pharmaceutical application segment is gaining structural importance as Peru's domestic generics industry scales up compliance with international pharmacopeia standards for primary packaging.
Peru's Ministry of Environment enforces Extended Producer Responsibility frameworks that mandate post-consumer glass collection targets, while INDECOPI oversees labeling and quality standards under national metrology regulations. These rules elevate compliance costs for imported alternatives and reinforce demand for locally manufactured container glass with verified recycled content. Stakeholders must monitor how forthcoming revisions to Peru's packaging waste decree will alter cullet recovery economics and furnace feedstock specifications.
Market Dynamics
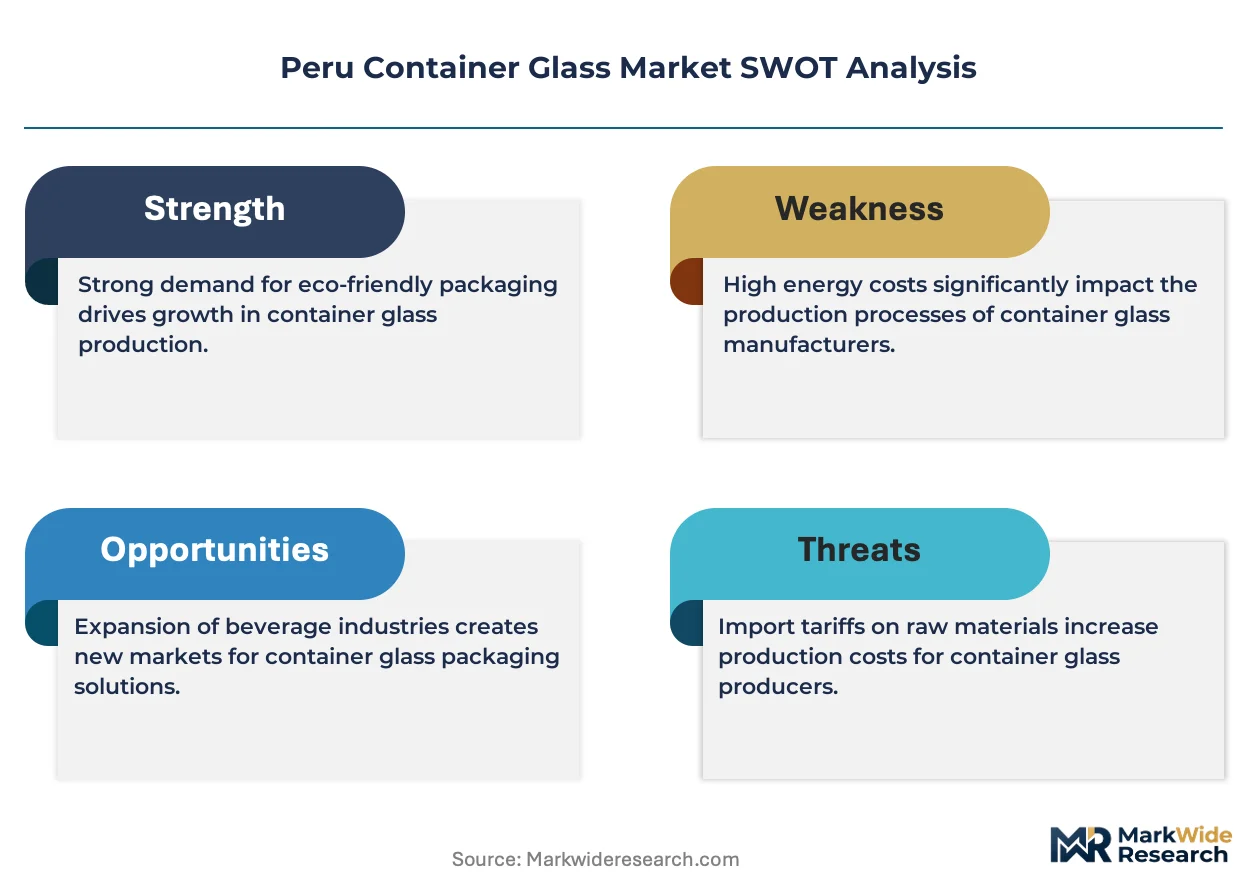
Peru's container glass sector faces intensifying pressure from the Ministry of Environment's Extended Producer Responsibility mandates, which are recalibrating furnace economics around cullet recovery rates and certified recycled content thresholds.
Growth Catalysts
- Extended Producer Responsibility mandates:Peru's Ministry of Environment enforces escalating post-consumer glass collection targets that lock in demand for locally manufactured container glass with verified recycled content.
- Artisanal food exports:Peruvian specialty producers of ají panca pastes and native fruit preserves are switching to premium glass jars to meet EU and US import packaging standards.
- Pisco distillation heritage:Denomination of Origin protections for pisco require traditional glass bottling, insulating domestic container glass from PET substitution in spirits packaging.
Market Restraints
- Natural gas price volatility:Furnace operations depend on Camisea basin natural gas, exposing margins to feedstock cost swings that electric melting cannot yet offset.
- Silica sand supply concentration:Northern Peruvian quarries dominate high-purity silica sourcing, creating geographic chokepoints for furnace feedstock security.
- Lightweight PET barrier advances:Multilayer plastic bottles with oxygen scavenger technologies are capturing share in non-premium beverage segments.
Strategic Opportunities
- Arequipa brewing cluster expansion:Craft beer production growth in southern Peru is generating demand for specialized amber and flint bottle runs with shorter lead times.
- Pharmaceutical serialization compliance:Peru's domestic generics industry scaling up to international pharmacopeia standards requires primary packaging with tamper-evident glass integrity.
- Returnable bottle pool systems:Deposit-refund frameworks under revision by environmental regulators could institutionalize closed-loop glass logistics for beverage producers.
Industry Challenges
- Furnace rebuild skill scarcity:Refractory engineering expertise for large-scale glass tank repairs concentrates among aging technical specialists in Lima's industrial corridor.
- INDECOPI certification timelines:National metrology compliance for new bottle designs extends product launch cycles, compressing competitive response windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peru Container Glass Market |
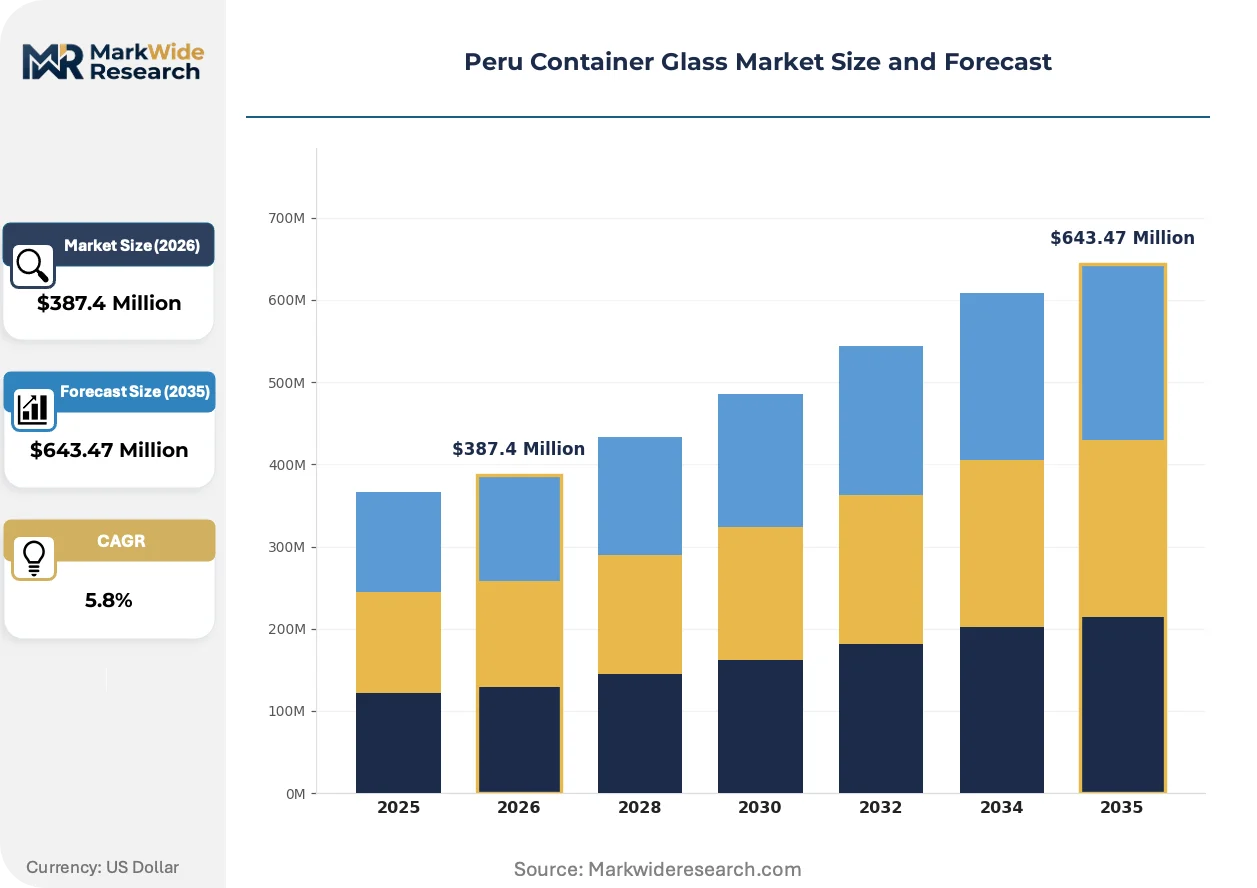
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $643.47 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Vials Application: Food & Beverage, Pharmaceuticals, Cosmetics, Household End User: Manufacturers, Retailers, Distributors, Brands Design Type: Custom, Stock, Decorative, Functional |
| Companies Covered | Owens-Illinois Inc., Ardagh Group S.A., Vitro S.A.B. de C.V., Saint-Gobain S.A., Amcor Limited, Gerresheimer AG, Verallia Packaging SAS, FrigoGlass, BA Glass BV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peru Container Glass Market Trends and Innovations
Electrification of melting technology and digitization of quality assurance are compressing the cost-performance gap between container glass and alternative packaging formats in Peruvian manufacturing.
Oxy-fuel combustion systems are rendering obsolete traditional air-fuel furnace configurations in Peru's coastal glass plants. Beverage bottlers in Lima's industrial corridor are retrofitting melting tanks to reduce nitrogen oxide emissions ahead of anticipated air quality regulations. This technology transition is rendering obsolete the capital-light rebuild cycles that previously sustained marginal producers.
Peru's Ministry of Environment is tightening Extended Producer Responsibility enforcement through quantified post-consumer recovery targets and labeling mandates. INDECOPI oversight of quality standards now requires traceable recycled content verification for domestic container glass. Food exporters targeting EU markets are accelerating compliance investments to preempt REACH-aligned packaging documentation requirements.
Consolidated procurement by multinational beverage bottlers is displacing fragmented spot purchasing across Peru's container glass market. Arequipa's brewing cluster and Lima's pisco distillers are migrating toward multi-year supply agreements with volume guarantees and co-developed lightweight designs. This purchasing concentration is most visible among Andean beverage producers seeking logistics cost reductions across mountainous distribution corridors.
Peru Container Glass Market Segmentation
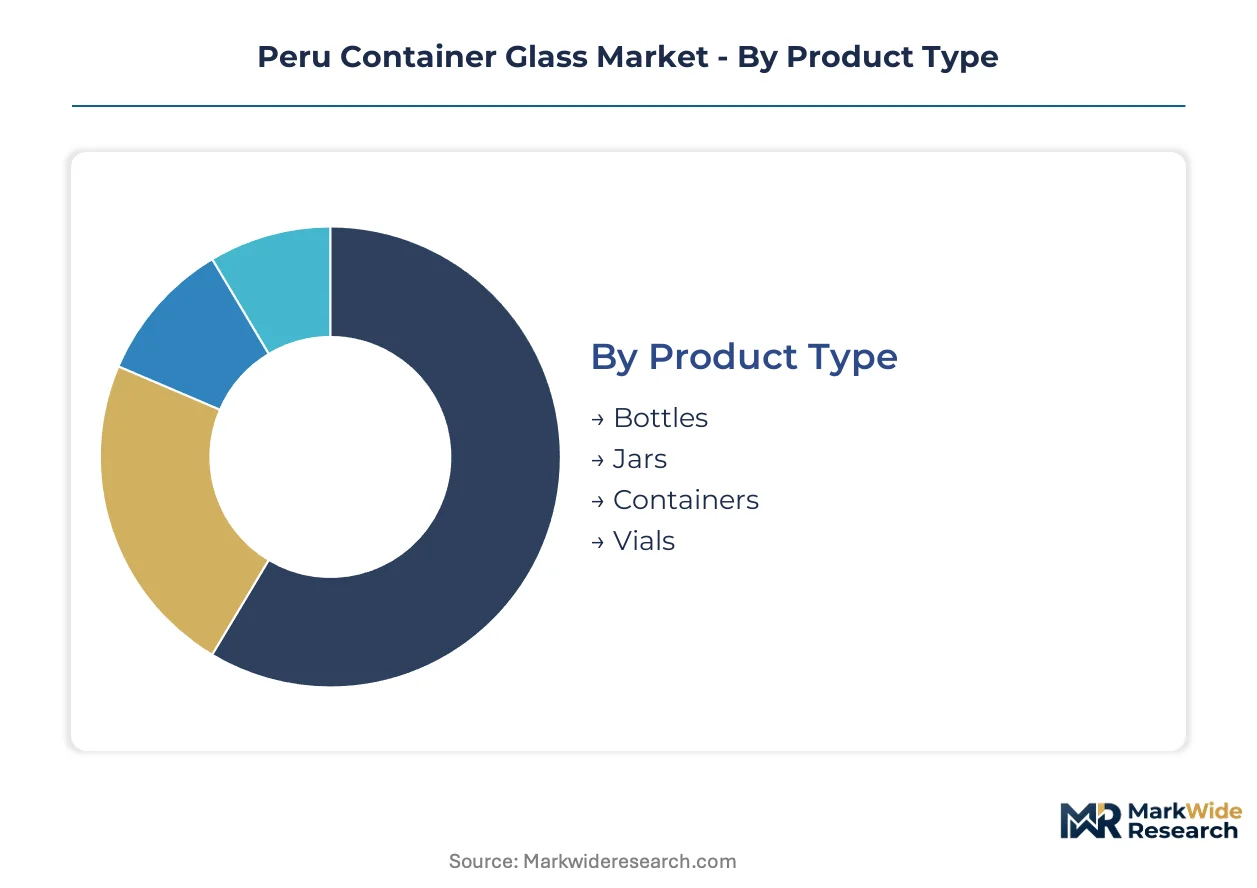
Peru's container glass market fragments across four distinct dimensions that shape furnace scheduling, mold investments, and distribution economics. Product type and application concentration determine batch chemistry and annealing protocols, while design specifications govern tooling amortization and minimum order quantities.
Product Type:
Volume concentration across Peru's glass plants tilts heavily toward beverage formats, with furnace campaigns optimized around bottle geometry and wall thickness specifications.
- Bottles:Flint and amber soda-lime compositions dominate pisco and craft beer filling lines across Lima's industrial corridor. Arequipa's brewing cluster is driving demand for specialized neck finishes and punt embossing that differentiate Andean brands in export markets.
- Jars:Wide-mouth configurations with vacuum-lug closures serve ají panca paste and native fruit preserve exporters targeting EU packaging compliance. Peruvian specialty food producers are upgrading from tinplate to glass for shelf-life extension in humid coastal climates.
- Containers:Squat pharmaceutical rounds and ovals accommodate tablet and powder dosing in domestic generics manufacturing.
- Vials:Type I borosilicate and treated soda-lime formats support injectable and diagnostic reagent packaging for Lima's expanding pharmaceutical formulation sector.
Bottles hold installed capacity. Jars are rotating up the share rankings.
Application:
End-use chemistry requirements segment furnace feedstock and quality assurance protocols across Peru's container glass output.
- Food & Beverage:Pisco denomination-of-origin mandates lock in glass bottling for spirits, while craft beer brands in Arequipa and Cusco specify amber UV protection. INDECOPI labeling enforcement for food contact materials elevates compliance costs for imported alternatives.
- Pharmaceuticals:Peru's domestic generics industry scaling toward international pharmacopeia standards requires Type II and Type III hydrolytic resistance certification. Serialization mandates from the national pharmaceutical regulator are driving tamper-evident closure integration.
- Cosmetics:Premium skincare and fragrance brands specify heavy-base flint bottles with silk-screen decoration for duty-free and retail channels.
- Household:Standard ware for cleaning agents and candle filling tolerates higher cullet ratios and lighter wall weights.
Food & Beverage anchors volume throughput. Pharmaceuticals is climbing the fastest on margin contribution.
End User:
Procurement scale and technical capability stratify Peru's container glass customer base into distinct service tiers.
- Manufacturers:Multinational beverage bottlers and pharmaceutical formulators in Lima's industrial corridor negotiate multi-year supply agreements with volume guarantees and co-developed lightweight designs.
- Retailers:Supermarket private-label programs for cooking oils and preserves drive demand for stock jar configurations with rapid mold turnaround.
- Distributors:Fragmented spot purchasing across regional pisco and wine bottlers concentrates in Ica and La Libertad valleys.
- Brands:Artisanal food exporters in Cusco and Ayacucho specify custom embossed bottles for origin storytelling in North American and European markets.
Manufacturers command furnace scheduling priority. Brands are gaining negotiation leverage through export volume commitments.
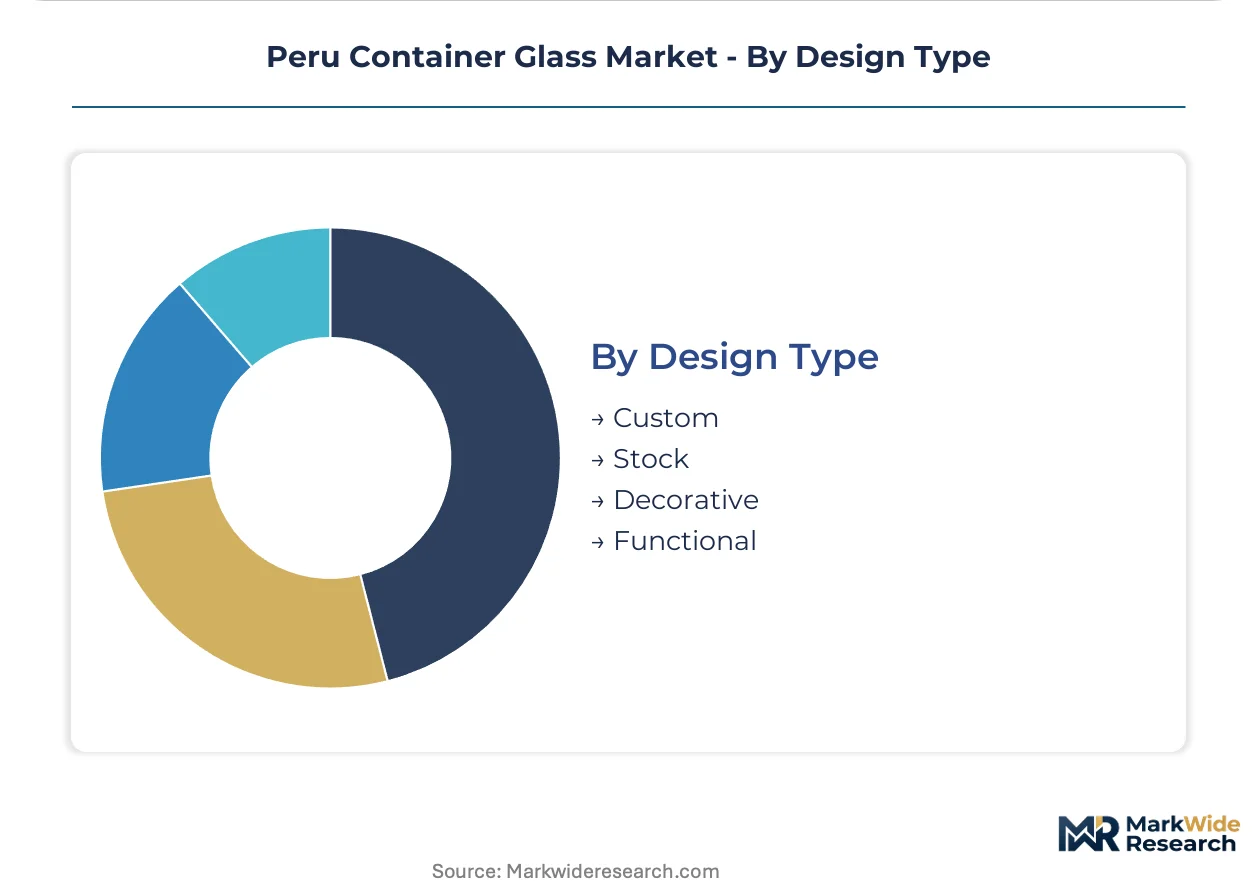
Design Type:
Tooling investment recovery and production flexibility trade off across Peru's mold fabrication and furnace campaign planning.
- Custom:Proprietary bottle shapes for pisco houses and craft breweries require dedicated mold sets with 12-18 month amortization horizons. Lima's glassworks maintain limited custom capacity for heritage brand relaunches.
- Stock:Standard Bordeaux, Burgundy, and pharmaceutical rounds minimize mold costs and compress lead times for mid-tier beverage and generics producers.
- Decorative:Applied ceramic labeling, embossing, and metallic finishes add 15-30% unit cost premiums for premium spirit and cosmetic positioning.
- Functional:Lightweighting protocols and stackability engineering reduce logistics costs across Peru's mountainous distribution corridors.
Stock designs absorb base volume. Custom work is expanding most quickly in craft beverage segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational beverage bottlers and pharmaceutical formulators concentrate procurement power in Lima's industrial corridor, while craft distillers and artisanal food exporters fragment demand across Peru's coastal valleys and Andean highlands.
Lima Metropolitan Area
Pisco distillers and multinational beverage bottlers anchor container glass consumption in Callao and Ate districts. Peru's Ministry of Environment enforces Extended Producer Responsibility collection targets that elevate compliance costs for imported alternatives. The Lima-Callao industrial corridor hosts furnace rebuild specialists whose aging technical expertise concentrates refractory engineering capacity.
Arequipa Region
Craft breweries in Arequipa's brewing cluster drive demand for specialized amber bottles with UV protection and custom punt embossing. INDECOPI labeling enforcement for food contact materials compresses product launch cycles for new bottle designs. Arequipa's mountainous logistics corridors reward lightweight bottle specifications that reduce transport costs to southern distribution networks.
Ica Valley
Wine and pisco producers in Ica's coastal valley sustain spot purchasing for standard flint and amber configurations. The Ministry of Environment's packaging waste decree revisions are recalibrating cullet recovery economics for regional bottlers. Ica's denomination-of-origin pisco houses require traditional glass bottling that insulates demand from PET substitution.
La Libertad Region
Trujillo-based food processors and regional beverage bottlers generate demand for stock jar configurations with rapid mold turnaround. INDECOPI national metrology regulations extend certification timelines for imported packaging alternatives. La Libertad's agricultural processing corridor is upgrading from tinplate to glass jars for shelf-life extension in humid coastal climates.
Cusco and Ayacucho Highlands
Artisanal food exporters in Cusco and Ayacucho specify custom embossed bottles for origin storytelling in North American and European markets. EU REACH-aligned packaging documentation requirements are accelerating compliance investments among specialty producers. These Andean highland clusters concentrate premium glass demand for native fruit preserves and ají panca paste exports.
Peru Container Glass Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Peru's container glass sector, producing a tiered structure where multinational furnace networks anchor bulk supply contracts while regional specialists capture custom design margins. Two strategic archetypes dominate: scale-driven operators leveraging regional furnace networks for volume guarantees, and lightweighting specialists reducing logistics costs across mountainous distribution corridors. Competitive moves concentrate on multi-year supply agreements with co-developed designs and backward integration into silica sand sourcing.
Among Mexico-based operators, Vitro S.A.B. de C.V. exemplifies the upstream-integrated archetype through captive silica sand sourcing from northern Peruvian quarries. Owens-Illinois Inc. and Ardagh Group S.A. occupy positions as scale-driven specialists, with the former anchoring regional furnace network coverage and the latter representing lightweight design capabilities for cost-sensitive logistics corridors.
| Leading Market Players |
|---|
| Owens-Illinois Inc. |
| Ardagh Group S.A. |
| Vitro S.A.B. de C.V. |
| Saint-Gobain S.A. |
| Amcor Limited |
| Gerresheimer AG |
| Verallia Packaging SAS |
| FrigoGlass |
| BA Glass BV |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Lima's furnace network compresses supplier margins while amplifying pricing power for silica-integrated operators. Peru's Ministry of Environment cullet mandates and Camisea basin natural gas volatility feed directly into contract indexation clauses.
Pricing Analysis
Cost-plus contracts with Camisea natural gas indexation dominate long-term agreements between furnace operators and Andean beverage producers. Pricing stratifies across premium lightweight designs for craft breweries, standard flint configurations for pisco houses, and economy amber runs for mass-market beer. Price differentiation hinges on INDECOPI certification grade and volume scale commitments. Cost compression in economy tiers is intensifying because multilayer PET bottles with oxygen scavenger technologies are capturing non-premium share. Regional pisco bottlers in Ica and La Libertad valleys exhibit highest price sensitivity; multinational beverage bottlers in Lima's industrial corridor show lowest sensitivity due to co-developed design investments.
Supply Chain Analysis
Export-control regimes on oxy-fuel combustion technology from European and US suppliers constrain furnace modernization timelines for Peruvian operators. Geographic supply concentration centers on northern Peruvian quarries for high-purity silica sand, US Gulf Coast for soda ash, and domestic limestone deposits. Raw material dependencies rest on Camisea basin natural gas, imported boron for pharmaceutical vials, and post-consumer cullet recovery networks. Single-source vulnerability concentrates in refractory engineering expertise for large-scale tank repairs. Distribution runs through Lima-Callao port infrastructure for imported inputs, with finished glass moving via mountainous corridors to Arequipa's brewing cluster and southern distribution networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peru's container glass sector operates as a substitution defense against advancing PET barrier technologies and lightweight plastic formats. Incumbents must navigate multilayer oxygen scavenger bottles that are eroding non-premium beverage share.
For Market Incumbents: Harden furnace economics through captive silica sand sourcing from northern Peruvian quarries to offset Camisea natural gas volatility. Deepen backward integration into cullet recovery networks ahead of Ministry of Environment decree revisions. Lock in multi-year supply agreements with Arequipa's brewing cluster to secure volume guarantees against PET substitution in craft beer segments.
For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical serialization compliance by targeting Lima's domestic generics industry with Type II hydrolytic resistance certification. Penetrate Cusco and Ayacucho artisanal food export clusters through custom embossed designs for EU REACH-aligned packaging documentation. Lead with rapid INDECOPI certification turnaround as the primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across oxy-fuel furnace rebuilds as air-fuel configurations face obsolescence. Long-term viability favors operators with upstream silica sand control and established cullet recovery infrastructure. Acquisition target archetype: regional specialists with lightweighting capabilities and Arequipa brewing cluster relationships. Watch for Ministry of Environment packaging waste decree revisions as the signal for cullet economics inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silica Sourcing | Captive northern Peruvian quarry access insulates margins from feedstock chokepoints. |
| Oxy-Fuel Furnace Retrofit | Camisea gas efficiency gains position operators ahead of anticipated air quality regulations. |
| Lightweight Bottle Design Partnership | Co-developed specifications reduce logistics costs across mountainous distribution corridors. |
| Cullet Recovery Network Expansion | Post-consumer collection infrastructure secures compliance with Ministry of Environment mandates. |
| Pharmaceutical Certification Investment | Type II hydrolytic resistance unlocks Lima generics industry serialization requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with furnace operations managers, beverage procurement directors at multinational bottlers, pharmaceutical packaging engineers, and INDECOPI regulatory affairs specialists. Secondary validation drew from Peruvian Ministry of Environment decree drafts, INDECOPI metrology filings, Camisea basin natural gas pricing disclosures, and EU REACH packaging documentation requirements. Bottom-up volume estimates from individual furnace outputs were triangulated against top-down consumption projections from end-use sector analysis.
Calibration against historical furnace utilization rates and natural gas cost pass-through patterns anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application chemistry requirements, end-user procurement scale, and design specification complexity. CAGRs were derived from trend extrapolation of returnable bottle pool adoption and pharmaceutical compliance investments. Industry-specific forecast inputs incorporated pisco denomination-of-origin bottling mandates and craft beer production growth in southern Peru.
Sensitivities concentrate around Ministry of Environment Extended Producer Responsibility enforcement intensity and Camisea basin natural gas pricing volatility. Forecasts reflect documented assumptions on furnace rebuild cycles and cullet recovery rate trajectories. Material shifts in PET barrier technology cost-performance ratios or Peruvian packaging waste decree implementation timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Glass Bottles and Jars Decoration Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
North America Glass Packaging Market
Glass Packaging
Saudi Arabia Pharmaceutical Glass Packaging Market
Glass Packaging
Sweden Container Glass Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
Poland Container Glass Market
Glass Packaging
Global Twin Neck Dosing Bottle Market
Glass Packaging
Spain Packaging Market
Glass Packaging
Container Glass Coatings Market
Glass Packaging
Egypt Glass Packaging Market