
 North America Nano Sensors Market | 2026-2036
North America Nano Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Nano Sensors Market Insights
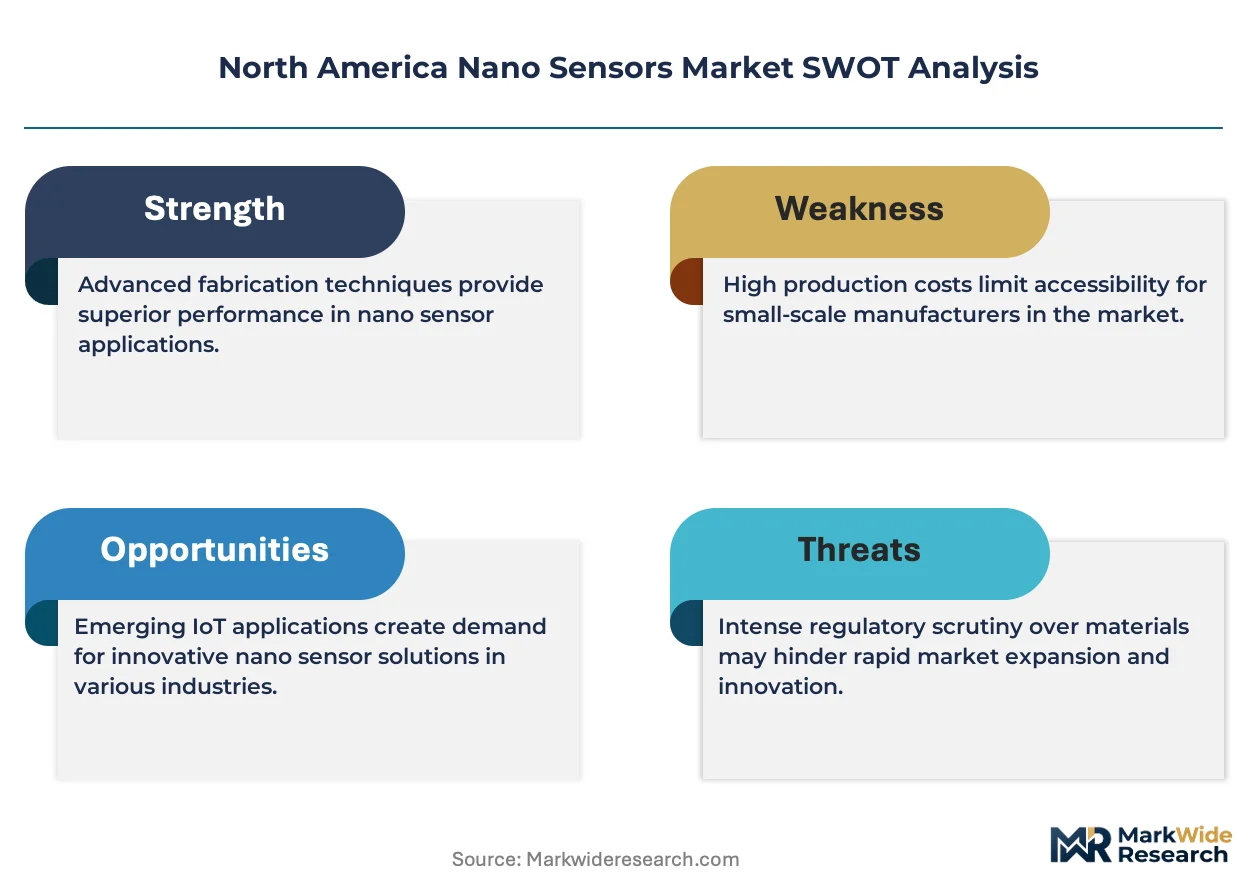
Healthcare diagnostics is pivoting toward nano sensor integration as precision medicine protocols expand across hospital networks and point-of-care facilities. Analog Devices Inc leverages its MEMS fabrication expertise to supply high-resolution pressure sensing modules for wearable cardiac monitors. Honeywell International Inc anchors its position through backward integration into quantum dot synthesis for industrial gas detection arrays. Texas Instruments Incorporated competes by extending its foundry partnerships to produce nanowire-based electrochemical sensors at scale.
North America nano sensors are transduction devices engineered at sub-100 nanometer feature scales, typically employing carbon nanotube or metal oxide active layers to detect chemical, biological, or physical stimuli with femtomolar sensitivity. Their primary commercial purpose centers on real-time analyte quantification in environments where conventional microscale sensors lack resolution or response speed. Optical sensors dominate current revenue flows due to established photonics supply chains in the United States and Canada, while biochemical sensors represent the fastest-expanding margin pool as CLIA-waived diagnostic platforms gain pharmacy and clinic placement. Quantum dot technology leads R&D investment intensity among fabrication approaches, though nanowire architectures are displacing incumbent metal oxide configurations in humidity and VOC detection applications.
FDA premarket notification requirements for in vitro diagnostic nano sensors shape product development timelines and clinical validation budgets for entrants targeting healthcare end users. EPA National Ambient Air Quality Standards and OSHA permissible exposure limits create recurring replacement demand for industrial environmental monitoring deployments across manufacturing facilities. NHTSA autonomous vehicle guidance is forcing automotive suppliers to validate nano sensor reliability under extended temperature cycling protocols. Stakeholders must monitor how the convergence of FDA digital health pre-certification and EPA next-generation air monitoring initiatives reshapes qualification pathways and procurement specifications.
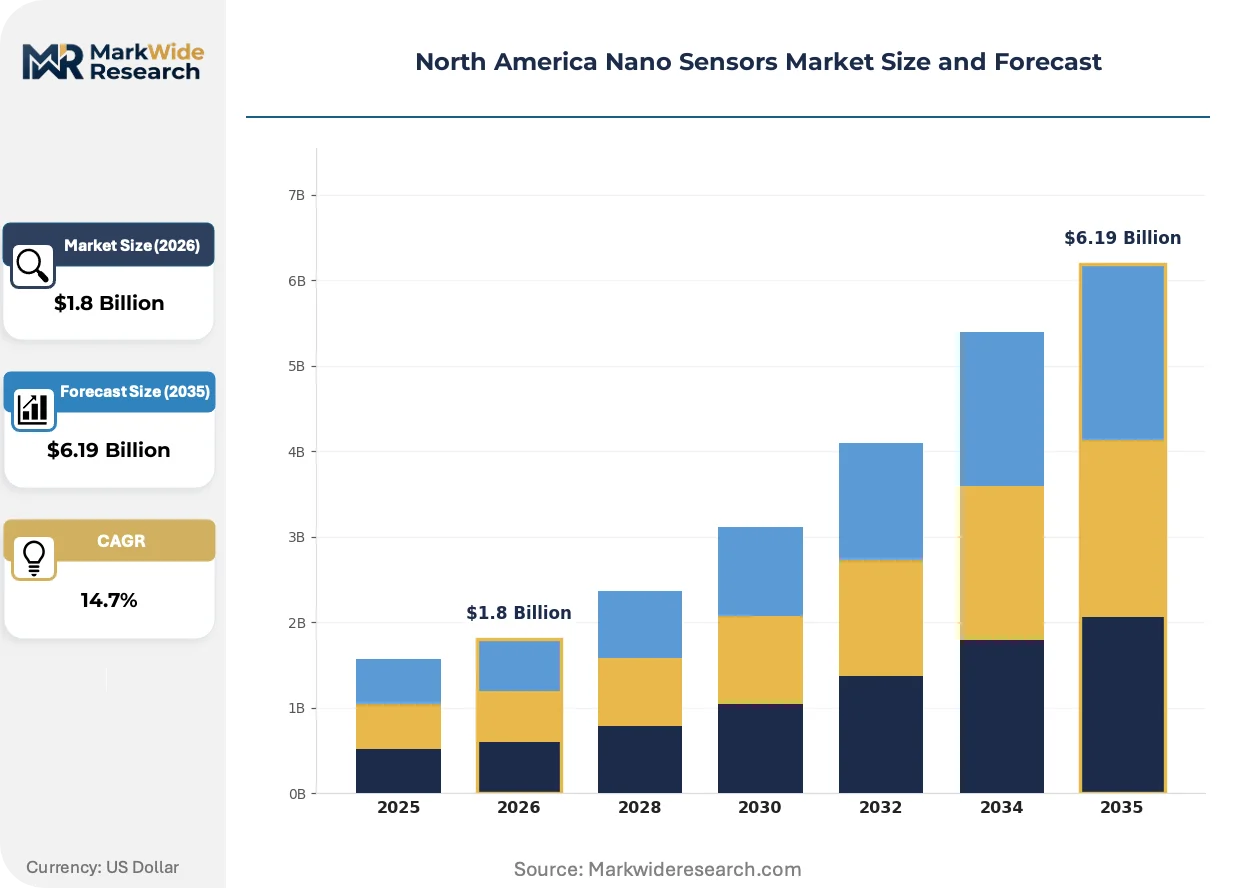
Market Dynamics
FDA digital health pre-certification pathways are compressing clinical validation timelines for nano sensor developers while EPA next-generation air monitoring mandates force industrial suppliers to refresh hardware fleets at accelerated cadences.
Growth Catalysts
- CLIA-waived diagnostic platforms:Pharmacy chains and urgent care networks across the United States are deploying point-of-care biochemical sensors for rapid infectious disease screening, bypassing centralized laboratory workflows.
- EPA National Ambient Air Quality Standards:Manufacturing facilities in the Great Lakes industrial corridor face recurring replacement cycles for VOC detection arrays to maintain compliance with tightened permissible exposure limits.
- Carbon nanotube fabrication:Foundry partnerships in Silicon Valley are scaling femtomolar-sensitivity electrochemical sensors for integration into next-generation wearable cardiac monitors.
Market Restraints
- Quantum dot precursor supply concentration:Rare earth element processing for cadmium-free quantum dots concentrates in a limited set of Asian chemical suppliers, exposing North American fabricators to input cost volatility and geopolitical disruption risk.
- FDA premarket notification complexity:In vitro diagnostic nano sensors require extensive clinical validation budgets that extend product development timelines and create capital barriers for early-stage entrants targeting hospital networks.
- Metal oxide sensor obsolescence pressure:Nanowire architectures are displacing incumbent metal oxide configurations in humidity detection applications, forcing legacy product line write-downs and manufacturing retooling costs.
Strategic Opportunities
- Underpenetrated Canadian healthcare procurement:Provincial health authorities in Ontario and Quebec are accelerating nano sensor adoption for remote patient monitoring in rural communities with limited laboratory infrastructure.
- NHTSA autonomous vehicle validation protocols:Extended temperature cycling requirements for automotive-grade nano sensors create qualification service revenue streams for testing laboratories serving Tier-1 suppliers.
- Photonics supply chain convergence:Established optical component foundries in the United States and Canada are integrating carbon nanotube deposition capabilities to capture biochemical sensor margins without greenfield fab investments.
Industry Challenges
- Nanofabrication process engineering talent scarcity:Cleanroom operators with MEMS and nanowire processing expertise command premium compensation in Boston's biotech corridor and Silicon Valley's semiconductor ecosystem, constraining production scaling.
- Legacy hospital IT integration complexity:Point-of-care nano sensor platforms require middleware development to interface with entrenched electronic health record systems from dominant healthcare IT vendors, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Nano Sensors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.19 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Chemical Sensors, Biochemical Sensors, Pressure Sensors Application: Environmental Monitoring, Healthcare Diagnostics, Consumer Electronics, Industrial Automation End User: Aerospace, Healthcare, Automotive, Electronics Technology: Nanowires, Carbon Nanotubes, Quantum Dots, Metal Oxides |
| Companies Covered | Analog Devices Inc, Honeywell International Inc, Texas Instruments Incorporated, OMRON Corporation, Teledyne Technologies, Lockheed Martin Corporation, Agilent Technologies, STMicroelectronics, Thermo Fisher Scientific Inc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Nano Sensors Market Trends and Innovations
Quantum dot synthesis techniques are maturing rapidly while regulatory frameworks for diagnostic nano sensors undergo structural revision across North American jurisdictions, reshaping competitive qualification requirements and procurement specifications simultaneously.
Photonic nano sensors employing plasmonic nanoparticle arrays are converging with smartphone-based readout platforms for at-home diagnostic applications. Pharmacy retailers and telehealth providers are piloting these integrated systems for chronic disease management. The structural consequence is compressing the addressable market for centralized laboratory testing while expanding direct-to-consumer revenue pools.
EPA next-generation air monitoring initiatives are mandating real-time particulate matter detection at finer spatial resolution across industrial zones. Manufacturing facilities in Texas and Ohio are retrofitting production lines with networked nano sensor arrays to preempt enforcement actions. The affected segment—petrochemical and semiconductor fabrication plants—is responding by consolidating vendor relationships with suppliers offering integrated hardware-software-compliance packages.
Hospital procurement departments are unbundling sensor hardware from service contracts and negotiating direct relationships with nano sensor fabricators previously accessed through distributor intermediaries. The channel disruption concentrates in cardiovascular and respiratory monitoring verticals where device margins are highest. This pattern is most visible in California and Massachusetts health systems with centralized supply chain autonomy.
North America Nano Sensors Market Segmentation
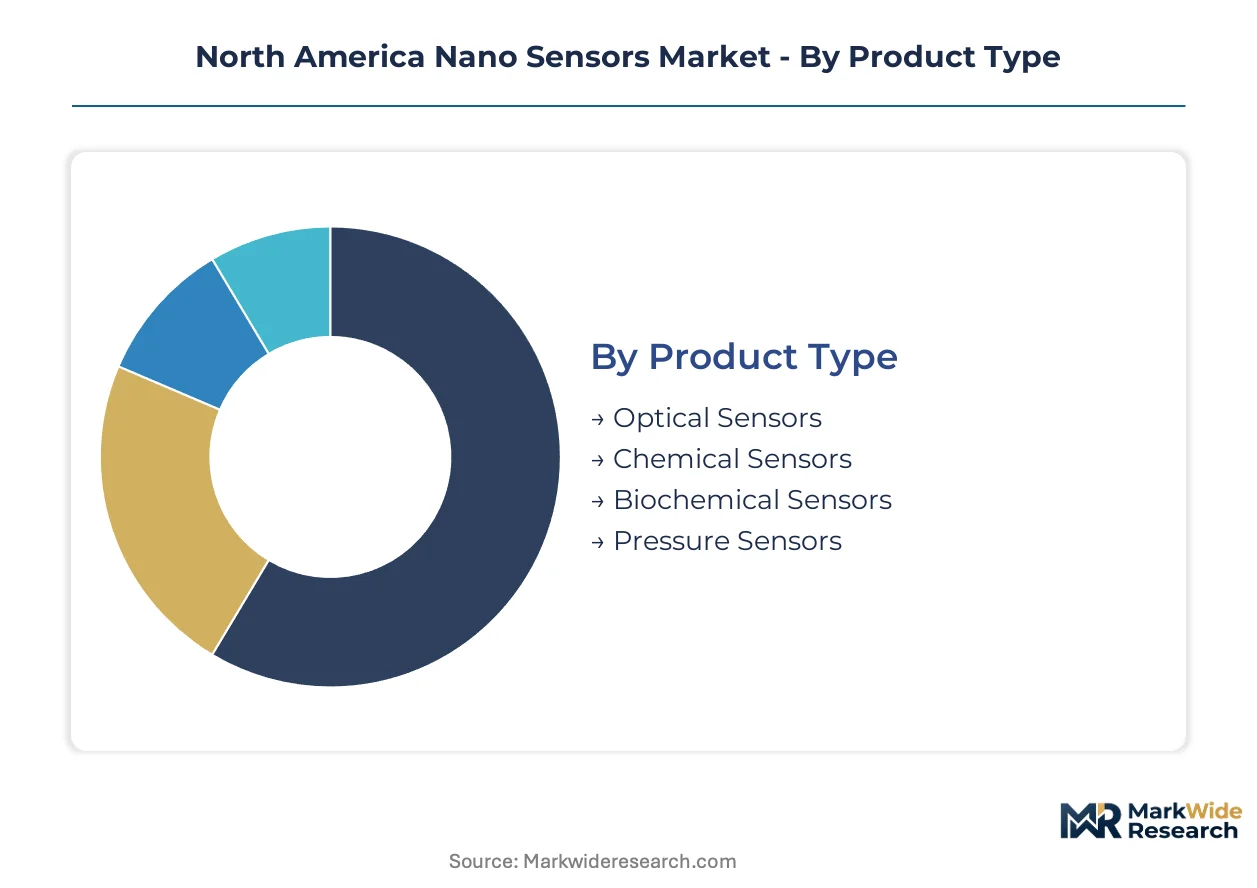
North American nano sensor procurement patterns diverge sharply between high-volume standardized components and premium validated systems. Understanding these tier dynamics reveals where margin pools concentrate and which fabrication approaches command pricing power.
Product Type:
Volume concentration favors optical platforms while biochemical variants capture premium positioning through diagnostic validation requirements.
- Optical Sensors:Plasmonic nanoparticle arrays and photonic crystal configurations dominate current revenue flows. Established foundries in Rochester, New York and Ottawa, Canada leverage legacy photonics infrastructure to serve environmental monitoring contracts across the Great Lakes corridor.
- Biochemical Sensors:Electrochemical transducers with carbon nanotube active layers achieve femtomolar sensitivity for point-of-care infectious disease screening. CLIA-waived platform deployments in CVS and Walgreens locations are accelerating replacement cycles for centralized laboratory workflows.
- Chemical Sensors:Metal oxide and conducting polymer configurations detect VOC and humidity variations in industrial process control.
- Pressure Sensors:MEMS-fabricated piezoresistive elements serve wearable cardiac monitoring and automotive tire pressure systems.
Mature deployment sits with Optical Sensors. Newer deployment is concentrated in Biochemical Sensors.
Application:
Healthcare diagnostics commands the steepest expansion trajectory while environmental monitoring generates recurring replacement revenue through regulatory mandates.
- Healthcare Diagnostics:FDA-cleared nano sensor platforms for cardiovascular and respiratory monitoring are penetrating hospital networks in Boston and San Francisco. Precision medicine protocols require real-time biomarker quantification that conventional microscale sensors cannot deliver.
- Environmental Monitoring:EPA National Ambient Air Quality Standards enforcement drives VOC and particulate detection array refreshes across Texas petrochemical facilities and Ohio manufacturing plants.
- Consumer Electronics:Smartphone-integrated gas and humidity sensors serve home air quality monitoring applications.
- Industrial Automation:Process control arrays in semiconductor fabrication plants monitor ultra-pure gas delivery systems.
Healthcare Diagnostics exhibits the fastest margin expansion. Environmental Monitoring sustains the most predictable replacement demand.
End User:
Healthcare procurement departments are consolidating vendor relationships while automotive qualification requirements create testing service revenue streams.
- Healthcare:Hospital networks in California and Massachusetts health systems negotiate directly with fabricators, bypassing distributor intermediaries for cardiovascular monitoring verticals.
- Automotive:NHTSA autonomous vehicle guidance forces Tier-1 suppliers to validate nano sensor reliability under extended temperature cycling protocols.
- Aerospace:FAA-certified pressure sensing modules serve altitude and cabin pressure monitoring in commercial aircraft.
- Electronics:Smartphone and wearable manufacturers integrate environmental and biometric sensors for consumer health tracking.
Healthcare procurement concentrates purchasing power. Automotive validation complexity extends supplier qualification timelines.
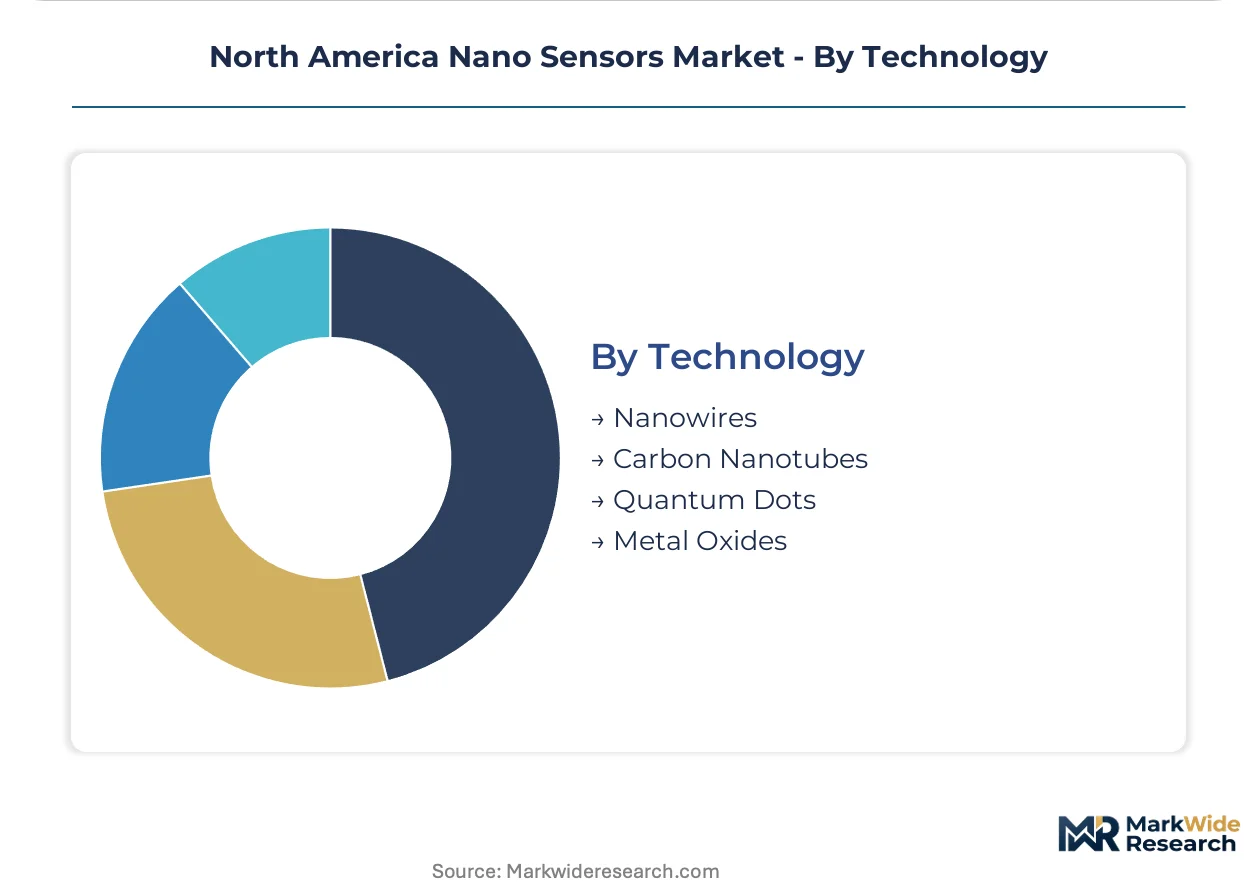
Technology:
Quantum dot synthesis attracts R&D investment intensity while nanowire architectures displace incumbent configurations in humidity detection.
- Carbon Nanotubes:Single-wall and multi-wall configurations enable electrochemical detection with exceptional signal-to-noise ratios. Foundry partnerships in Silicon Valley are scaling production for wearable cardiac monitor integration.
- Quantum Dots:Cadmium-free synthesis approaches are maturing rapidly for optical biosensing applications. Rare earth precursor supply concentration in Asian chemical suppliers exposes North American fabricators to input cost volatility.
- Nanowires:Silicon and metal oxide nanowire configurations achieve superior sensitivity in humidity and VOC detection compared to planar metal oxide films.
- Metal Oxides:Tin oxide and zinc oxide thin-film sensors serve established industrial gas detection applications facing obsolescence pressure.
Carbon Nanotubes anchor current production volumes. Quantum Dots command the highest R&D allocation intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity zones in Silicon Valley and Greater Boston concentrate nano sensor fabrication through federal tax incentives and state-level R&D credits. FDA premarket pathways and EPA enforcement mandates accelerate deployment timelines across the continent.
United States
Hospital networks in California and Massachusetts drive demand for CLIA-waived diagnostic platforms. FDA digital health pre-certification compresses validation timelines for cardiovascular monitoring entrants. Boston's biotech corridor and Silicon Valley's semiconductor ecosystem anchor fabrication capacity for electrochemical and optical sensor variants.
Canada
Provincial health authorities in Ontario and Quebec accelerate nano sensor procurement for remote patient monitoring. Health Canada regulatory alignment with FDA standards streamlines cross-border product approvals. Ottawa and Toronto host photonics foundries leveraging legacy telecom infrastructure for environmental monitoring contracts.
Mexico
Maquiladora operations in Baja California and Chihuahua integrate nano sensors for industrial process control in automotive and electronics assembly. Mexican environmental regulators tighten air quality enforcement in Monterrey's manufacturing belt. Guadalajara's electronics cluster attracts sensor packaging investments serving North American OEMs.
North America Nano Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with healthcare diagnostics favoring validated proprietary platforms and industrial applications accepting white-label configurations. The vendor base organizes around three archetypes: integrated semiconductor conglomerates with MEMS foundry assets, pure-play sensor specialists with quantum dot synthesis capabilities, and diversified industrial conglomerates with backward integration into materials processing. Competitive moves concentrate on foundry partnership expansion and qualification service bundling for automotive and aerospace certification requirements.
Among US-based semiconductor fabricators, Analog Devices Inc and Texas Instruments Incorporated exemplify the integrated conglomerate archetype through MEMS fabrication expertise and foundry partnership networks. Honeywell International Inc anchors the diversified industrial tier with upstream control over quantum dot synthesis for gas detection arrays. These three entities represent distinct strategic positions without overlapping segment focus.
| Leading Market Players |
|---|
| Analog Devices Inc |
| Honeywell International Inc |
| Texas Instruments Incorporated |
| OMRON Corporation |
| Teledyne Technologies |
| Lockheed Martin Corporation |
| Agilent Technologies |
| STMicroelectronics |
| Thermo Fisher Scientific Inc |
| Others |
Pricing and Supply Chain Analysis
Backward integration into quantum dot synthesis anchors Honeywell's supply position and pricing power against volatile rare earth precursor markets. Captive production of cadmium-free quantum dots insulates the firm from Asian chemical supplier concentration while commanding premium positioning in industrial gas detection arrays.
Pricing Analysis
Lead-time-driven pricing separates validated FDA-cleared platforms from spot-market commodity sensors. Three-tier pricing structure across CLIA-waived diagnostic, industrial environmental monitoring, and consumer electronics tiers reflects certification burden and clinical validation depth. Price differentiation hinges on FDA premarket notification completion and EPA compliance certification status. Cost compression in metal oxide humidity sensors is intensifying because nanowire architectures displace planar configurations. Hospital procurement committees exhibit lowest price sensitivity; electronics OEMs sourcing smartphone-integrated environmental sensors show highest elasticity.
Supply Chain Analysis
Cleanroom operator scarcity in Boston's biotech corridor and Silicon Valley's semiconductor ecosystem constrains production scaling and extends qualification timelines. Fabrication capacity concentrates in the United States, Canada, and Mexico's Baja California maquiladora belt. Rare earth precursor processing for quantum dots draws from concentrated Asian chemical suppliers. Single-source vulnerability in cadmium-free quantum dot precursor supply exposes North American fabricators to geopolitical disruption risk. Distribution runs through direct hospital procurement relationships and Tier-1 automotive supplier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America nano sensors market reads as a cost-of-compliance story where FDA premarket notification requirements create substantial barrier-to-entry moats for validated diagnostic platform developers.
For Market Incumbents: Hedge against nanowire architecture displacement in humidity detection by accelerating R&D partnerships with Silicon Valley foundries. Secure backward integration into carbon nanotube deposition capabilities to capture biochemical sensor margins without greenfield fab investments. Lock in multi-year service contracts with Great Lakes manufacturing facilities facing EPA-mandated VOC detection array refreshes.
For New Entrants and Emerging Players: Direct-to-consumer telehealth channels offer the most penetrable route around entrenched hospital procurement relationships. Target underpenetrated Canadian provincial health authorities in Ontario and Quebec accelerating remote patient monitoring procurement. White-label optical sensor platforms for environmental monitoring applications bypass FDA validation timelines entirely.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated semiconductor conglomerates seeking MEMS fabrication expansion. Five-to-ten year viability favors pure-play specialists with quantum dot synthesis capabilities and established EPA compliance track records. Watch NHTSA autonomous vehicle validation protocol finalization as inflection indicator for automotive-grade nano sensor demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Digital Health Pre-Certification Pursuit | Compresses clinical validation timelines for cardiovascular monitoring entrants seeking hospital network placement. |
| Foundry Partnership Expansion | Enables scaling of carbon nanotube electrochemical sensors for wearable cardiac monitor integration. |
| Quantum Dot Synthesis Backward Integration | Insulates against rare earth precursor supply concentration in Asian chemical supplier networks. |
| Canadian Provincial Health Authority Direct Engagement | Captures remote patient monitoring procurement acceleration in Ontario and Quebec rural communities. |
| NHTSA Automotive Validation Qualification | Creates testing service revenue streams for extended temperature cycling protocol compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, hospital GPO contracts managers, EPA compliance officers, and MEMS foundry operations directors combined with FDA 510(k) submission databases, EPA enforcement action records, and NHTSA guidance documents. Bottom-up sensor deployment quantification triangulated against top-down healthcare IT expenditure tracking.
Granularity-level modeling operated at technology-architecture, application-vertical, and end-user-procurement-channel dimensions across the projection horizon. CAGRs derived from segment-level unit economics and replacement-cycle analysis. Forecast inputs incorporated CLIA-waiver expansion trajectories, EPA National Ambient Air Quality Standards enforcement intensity, and carbon nanotube foundry yield improvement curves.
The model holds under stable FDA premarket review timelines and EPA enforcement continuity; deviation in quantum dot precursor trade restrictions or NHTSA protocol acceleration would shift volume trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Piezoelectric Sensor Market
Sensors and Controls
Silicon Photomultiplier (Sipm) Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Vision Sensor Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Digital Array Microphone Market
Sensors and Controls
Europe Proximity Sensors Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Manifold Absolute Pressure Sensor Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Global Blind Spot Monitor Market