
 Semiconductor Wafer Tape Market | 2026-2036
Semiconductor Wafer Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Wafer Tape Market Insights
Modular tape configurations for multi-die packaging is pivoting buyer procurement toward application-specific bundles rather than commodity rolls. Mitsui Chemicals leverages its polyimide resin backward integration to control raw material quality for high-temperature dicing applications. LINTEC Corporation anchors its position through precision coating technology that sustains thickness tolerances below two microns across 300mm widths. Nitto Denko Corporation competes by dominating UV-release adhesive formulations that enable clean detachment without residue.
Semiconductor wafer tape comprises pressure-sensitive adhesive films engineered to secure silicon wafers during mechanical dicing, grinding, and backside thinning operations, typically incorporating acrylic or rubber-based adhesives on polyimide or polyester carriers with controlled peel strengths between 50 and 300 grams per inch. Polyimide tape leads in value terms due to its thermal stability above 250°C during laser dicing of GaN power devices, while adhesive tape segments grow fastest as temporary bonding applications multiply in 3D-IC stacking processes. Wafer dicing remains the most mature application with stable replacement demand, though wafer mounting margins expand as foundries adopt thinner 50µm tapes for fragile compound semiconductor handling.
EPA regulations on volatile organic compound emissions constrain solvent-based adhesive manufacturing in the United States, while REACH substance restrictions in Europe mandate disclosure of phthalate plasticizers exceeding 0.1% concentration in tape formulations. Japan's METI enforces JIS standards for semiconductor materials traceability that exporters must satisfy for supply qualification. Stakeholders should monitor adhesive chemistry substitution timelines and foundry qualification cycles as decisive variables for capacity planning and regional sourcing strategy.
Market Dynamics
Advanced packaging architectures for AI chiplets are restructuring tape demand toward thinner, thermally stable formats that withstand laser dicing temperatures above 250°C while enabling clean UV-release detachment.
Growth Catalysts
- AI Chiplet Proliferation:Multi-die packaging in high-performance computing is pulling demand for application-specific tape bundles configured for heterogeneous integration.
- REACH Halogen-Free Mandates:European substance restrictions are accelerating adhesive reformulation toward halogen-free chemistries that maintain peel strength without phthalate plasticizers.
- Hsinchu Cluster Density:Taiwan's science park corridor concentrates the world's densest wafer processing operations, creating localized demand spikes for precision-coated tapes with sub-two-micron thickness tolerance.
Market Restraints
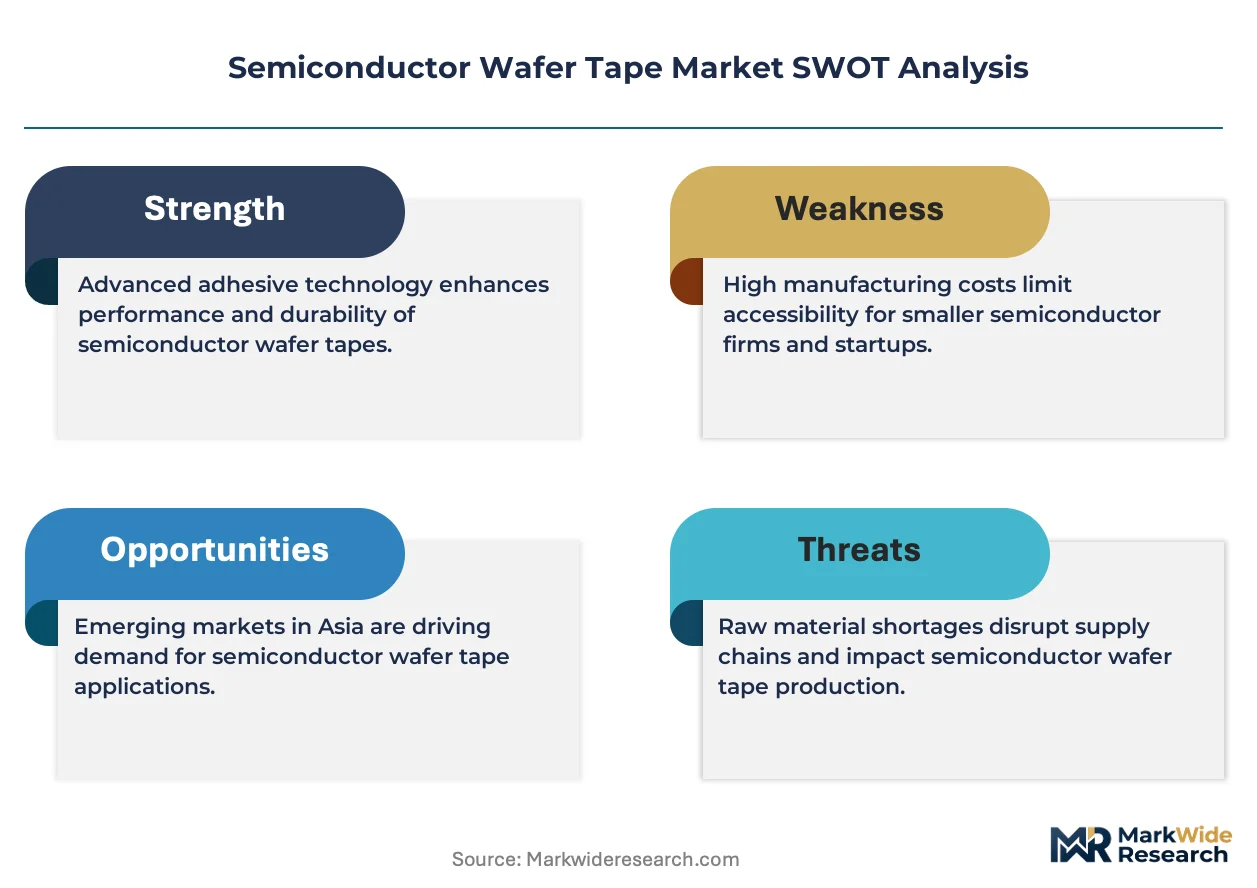
- Specialty Polyimide Feedstock Concentration:High-purity polyimide resin supply concentrates among Japanese and Korean chemical majors, exposing tape converters to input cost volatility and allocation risk.
- EPA Solvent Emission Controls:United States volatile organic compound regulations constrain solvent-based adhesive manufacturing, forcing capital-intensive aqueous system conversions or offshore production shifts.
- Thermal-Mechanical Trade-off Ceiling:Acrylic adhesives face fundamental performance boundaries above 200°C, limiting their deployment in GaN power device dicing where polyimide tapes command premium positioning.
Strategic Opportunities
- India Semiconductor Mission:The country's PLI scheme and fab incentive framework are attracting foundry investments that will require localized tape qualification and supply chain development.
- Temporary Bonding Expansion:3D-IC stacking processes are multiplying adhesive tape applications beyond traditional dicing into wafer-to-wafer bonding and carrier wafer management.
- UV-Release Formulation Gaps:Clean detachment without residue remains technically underserved in compound semiconductor handling, creating white space for specialized adhesive chemistry development.
Industry Challenges
- Foundry Qualification Cycle Compression:Tape vendors face 12-18 month qualification timelines at leading foundries, locking capacity commitments before volume certainty emerges.
- Coating Precision Talent Scarcity:The specialized workforce capable of sustaining sub-two-micron thickness control across 300mm widths concentrates in Japan and Taiwan, constraining geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Wafer Tape Market |
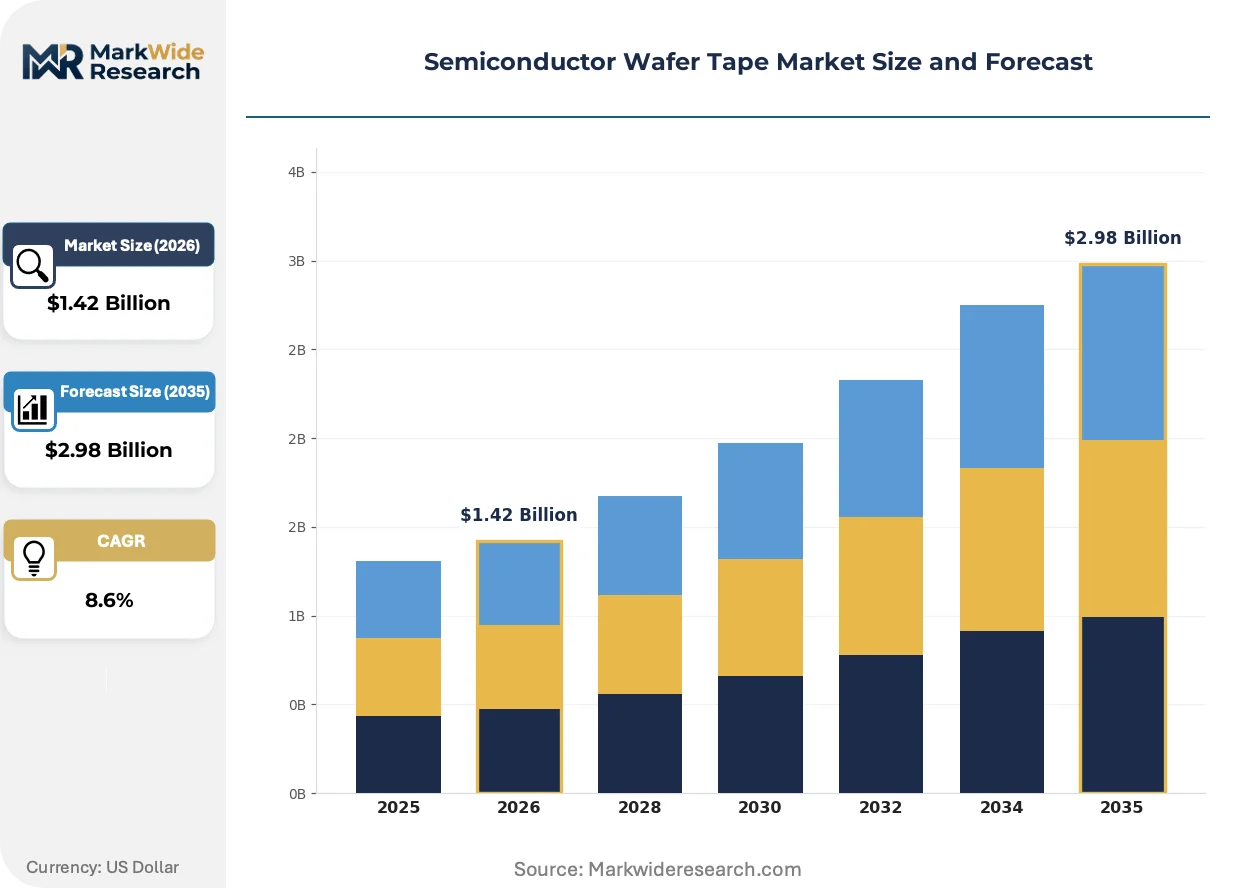
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyimide Tape, Polyester Tape, Adhesive Tape, Polyethylene Tape End User: Foundries, IDM Companies, Research Institutions, OEMs Application: Wafer Dicing, Wafer Backing, Wafer Mounting, Wafer Bonding Thickness: 50µm, 100µm, 150µm, 200µm |
| Companies Covered | Mitsui Chemicals, LINTEC Corporation, Nitto Denko Corporation, Furukawa Electric, Sekisui Chemical, Denka, Maxell Sliontec, 3M, UltraTape, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Wafer Tape Market Trends and Innovations
Laser dicing of brittle compound semiconductors is forcing tape architecture evolution, while regulatory chemistry constraints and procurement consolidation are simultaneously reshaping competitive requirements.
UV-release adhesive platforms are consolidating as the dominant detachment mechanism for fragile wafer handling. Leading foundries handling thinned silicon and compound semiconductors are standardizing on these formulations to eliminate mechanical stress during die pickup. The technology is consolidating multiple legacy adhesive categories into unified platforms that reduce inventory complexity for high-mix packaging operations.
REACH substance disclosure mandates are forcing systematic supply chain documentation across European-bound tape shipments. ECHA enforcement of phthalate concentration thresholds above 0.1% is compelling reformulation of legacy acrylic adhesives. High-temperature dicing segments are responding fastest, as GaN and SiC device manufacturers face dual pressure from automotive OEMs and European export requirements.
Application-specific tape bundles are displacing commodity roll procurement in advanced packaging accounts. IDMs and OSATs are consolidating vendor relationships around suppliers capable of configuring thickness, adhesive chemistry, and release properties per process node. This pattern concentrates most visibly in Taiwan's Hsinchu corridor, where TSMC and its supply base negotiate multi-parameter specifications rather than standard product codes.
Semiconductor Wafer Tape Market Segmentation
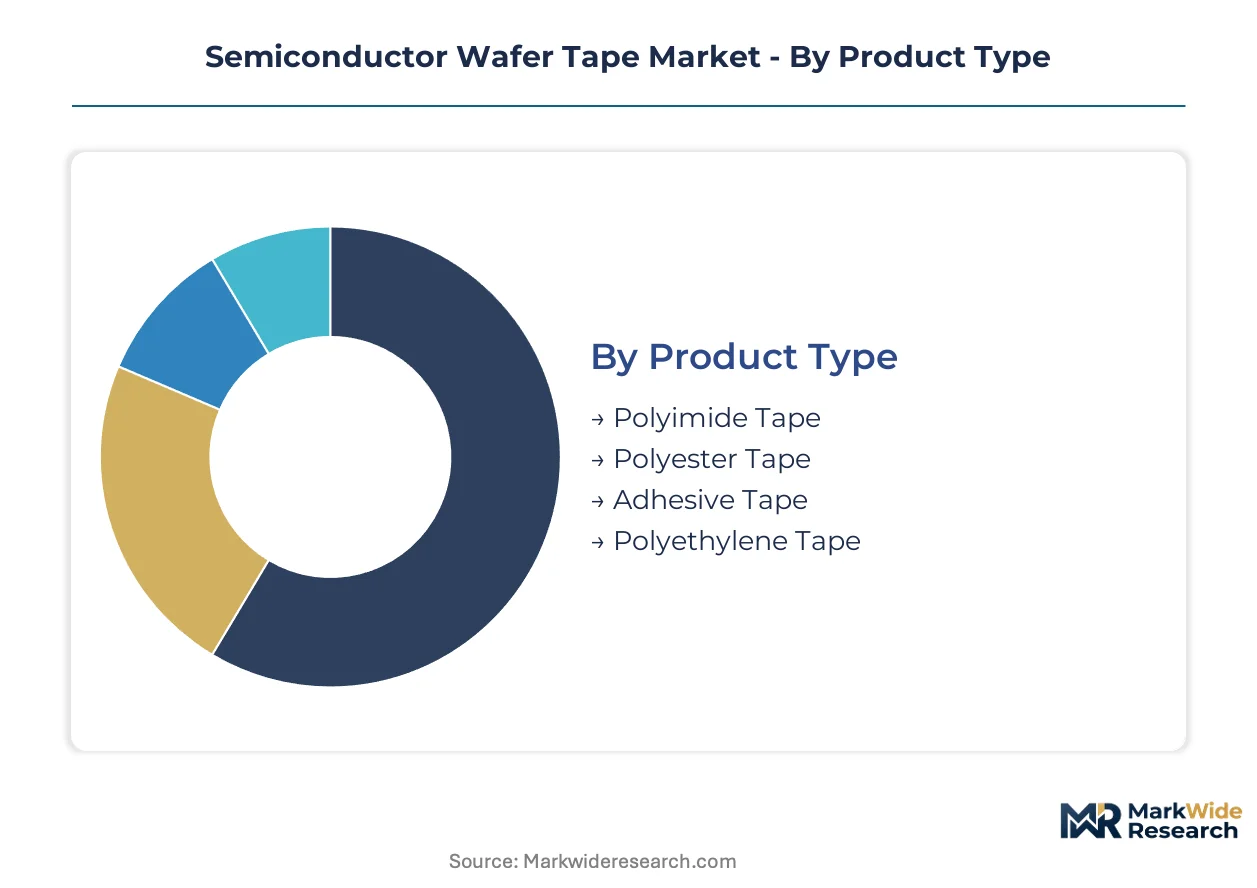
Semiconductor wafer tape segmentation reflects divergent technical requirements across process nodes. Customization intensity varies sharply by thermal exposure, wafer fragility, and foundry qualification protocols.
Product Type:
Customization depth runs from fully engineered solutions for extreme thermal environments to standardized commodity formats for ambient processing.
- Polyimide Tape:Aromatic polymer backbone delivers thermal stability above 250°C during laser dicing of GaN power devices. Demand concentrates in Taiwan's Hsinchu corridor where TSMC's advanced packaging operations specify sub-two-micron thickness tolerance for high-value die handling. Most installed capacity flows through Polyimide Tape. Expansion is steepest in Adhesive Tape.
- Adhesive Tape:Acrylic and rubber-based pressure-sensitive formulations enable temporary bonding in 3D-IC stacking processes with controlled peel strengths between 50 and 300 grams per inch. OSATs in South Korea's Pyeongtaek cluster are multiplying applications beyond traditional dicing into wafer-to-wafer bonding.
- Polyester Tape:Cost-optimized carrier for standard silicon wafer dicing with moderate thermal exposure below 150°C.
- Polyethylene Tape:Economy-grade option for research prototyping and non-critical grinding operations.
Polyimide commands premium positioning through raw material scarcity. Adhesive formats gain share fastest as temporary bonding multiplies.
End User:
Procurement sophistication escalates from volume-driven commodity purchasing to specification-intensive partnership models.
- Foundries:TSMC, Samsung Foundry, and Intel Foundry Services negotiate multi-parameter tape bundles configured per process node rather than standard product codes. These buyers impose 12-18 month qualification timelines that lock vendor capacity commitments.
- IDM Companies:Integrated device manufacturers blend captive packaging with outsourced assembly, creating hybrid procurement patterns that demand both application-specific and commodity tape formats.
- Research Institutions:Low-volume, high-mix purchasing with tolerance for wider specification bands.
- OEMs:Indirect demand through OSAT contracting with limited direct tape specification authority.
Foundries concentrate the highest-value procurement. IDMs are diversifying supplier relationships fastest.
Application:
Process maturity separates replacement-driven demand from emerging applications requiring co-development partnerships.
- Wafer Dicing:Mechanical sawing and laser ablation of silicon and compound semiconductors represents the most mature application with stable replacement demand. UV-release formulations are consolidating as the dominant detachment mechanism across Taiwan and South Korea.
- Wafer Mounting:Handling of thinned silicon and fragile compound semiconductors is pulling margins upward as foundries adopt 50µm tapes for GaN and SiC device processing.
- Wafer Backing:Structural support during backside grinding operations.
- Wafer Bonding:Temporary adhesive layers for 3D-IC stacking and carrier wafer management.
Wafer Dicing retains the largest installed base. Wafer Mounting is climbing the fastest as substrate thinning accelerates.
Thickness:
Dimensional specification directly correlates with wafer fragility and process thermal load.
- 50µm:Ultra-thin format for fragile compound semiconductor handling where mechanical stress minimization overrides cost considerations. TSMC's advanced packaging roadmaps specify this thickness for next-generation chiplet architectures.
- 100µm:Standard thickness for thinned silicon wafer processing across mature nodes.
- 150µm:Mid-range option for mixed-signal devices with moderate fragility.
- 200µm:Legacy thickness for robust silicon wafers in commodity packaging.
100µm dominates current volume. 50µm is gaining share fastest as substrate thinning penetrates power electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The semiconductor wafer tape industry traces its industrial lineage to post-war Japan, where precision polymer coating capabilities developed for electronics applications during the 1960s and 1970s established the technical foundations that still dominate high-temperature adhesive formulations today.
United States
Domestic demand concentrates around Intel's Arizona and Oregon fabrication complexes plus emerging foundry investments in Texas and New York. EPA volatile organic compound regulations constrain solvent-based adhesive manufacturing, forcing capital-intensive aqueous system conversions or offshore production shifts for tape converters serving American fabs. The Phoenix-Tucson corridor anchors the densest wafer processing cluster outside Asia, with TSMC's Arizona facility and Intel's expansion programs driving localized tape qualification requirements.
Japan
Japanese chemical majors control high-purity polyimide resin supply for extreme thermal applications above 250°C, with METI enforcing JIS standards for semiconductor materials traceability that exporters must satisfy. Domestic foundry investments by Rapidus in Hokkaido and legacy IDM operations in Kyushu sustain replacement demand for precision-coated formats. The Kansai region around Osaka hosts the deepest concentration of adhesive coating expertise, with sub-two-micron thickness control capabilities concentrated among established chemical conglomerates.
South Korea
Samsung Foundry and SK Hynix drive procurement for multi-parameter tape bundles configured per advanced packaging node, particularly for 3D-IC stacking applications in Pyeongtaek and Yongin complexes. The country's national industrial regulator maintains substance disclosure requirements aligned with REACH frameworks for European-bound exports. Seoul Capital Area foundries are standardizing UV-release formulations for fragile compound semiconductor handling, consolidating multiple legacy adhesive categories into unified platforms.
Taiwan
TSMC's Hsinchu Science Park corridor concentrates the world's densest wafer processing operations, creating localized demand spikes for precision-coated tapes with sub-two-micron thickness tolerance across 300mm widths. Domestic environmental regulations mirror European substance restrictions, accelerating halogen-free adhesive reformulation timelines. The Taichung and Tainan science park expansions are replicating Hsinchu's procurement patterns, with foundries negotiating application-specific bundles rather than commodity roll purchases.
China
Domestic foundry buildouts by SMIC and Hua Hong Semiconductor in Shanghai and Wuxi are developing localized tape supply chains, though high-temperature polyimide formats remain import-dependent. MIIT standards for semiconductor materials traceability create qualification barriers for non-domestic suppliers. The Yangtze River Delta clustering around Shanghai anchors the most sophisticated packaging operations, with compound semiconductor investments in Xiamen and Shenzhen pulling demand for thinner 50µm tape formats.
Semiconductor Wafer Tape Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal performance and coating precision dimensions, with aromatic polyimide specialists commanding pricing power that polyester carriers cannot match. The vendor base organizes into three tiers: integrated chemical conglomerates with captive resin supply, precision coating specialists with thickness control below two microns, and regional converters serving price-sensitive research and prototyping accounts. Dominant competitive moves include backward integration into polyimide resin production and strategic partnerships with foundries for 12-18 month qualification cycles.
Among Japanese chemical conglomerates, Mitsui Chemicals, LINTEC Corporation, and Nitto Denko Corporation occupy positions across the premium-tier spectrum. Mitsui Chemicals exemplifies the resin-integrated archetype through its polyimide backward integration. LINTEC Corporation represents the precision-coating specialist tier with thickness tolerance capabilities. Nitto Denko Corporation anchors the UV-release formulation segment that foundries are standardizing for fragile wafer handling.
| Leading Market Players |
|---|
| Mitsui Chemicals |
| LINTEC Corporation |
| Nitto Denko Corporation |
| Furukawa Electric |
| Sekisui Chemical |
| Denka |
| Maxell Sliontec |
| 3M |
| UltraTape |
| Others |
Pricing and Supply Chain Analysis
Specialized adhesive coating technicians concentrated in Japan's Kansai region and Taiwan's Hsinchu corridor command wage premiums that widen spreads between precision-grade and commodity tape tiers. Labor-cost differentials between these qualified coating specialists and general polymer film converters in lower-cost manufacturing zones directly shape three-tier pricing stratification across the semiconductor wafer tape market.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement negotiations, with polyimide resin grade and foundry qualification status as primary differentiation drivers. Cost compression in standard acrylic tapes is intensifying because EPA solvent emission controls force aqueous system conversions. IDM hybrid procurement teams exhibit highest price sensitivity, while TSMC-led foundry accounts prioritize thermal performance over unit economics.
Supply Chain Analysis
Foundry qualification cycles lasting 12-18 months function as supply chain gates that lock out unqualified converters regardless of pricing competitiveness. Raw material supply draws from Japan and South Korea for high-purity polyimide resin, Taiwan for precision coating capacity, and China for polyester carrier substrates. Single-source vulnerability concentrates in aromatic polyimide resin feedstock controlled by Mitsui Chemicals and select Korean chemical majors. Distribution runs through direct foundry contracts rather than distributor networks for qualified suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities in semiconductor wafer tape rest on substrate thinning trends that pull demand toward 50µm ultra-thin formats commanding premium positioning, alongside REACH-driven adhesive reformulation that rewards early halogen-free chemistry adopters with pricing power.
For Market Incumbents: Hedge against acrylic adhesive commoditization by deepening backward integration into polyimide resin production and securing dedicated coating capacity in Taiwan's expanding Taichung science park. Foundry qualification cycle compression threatens uncommitted capacity, making early engagement with Intel Foundry Services' Arizona ramp essential for volume lock-in.
For New Entrants and Emerging Players: REACH substance restrictions in Europe open a window for halogen-free adhesive specialists to penetrate automotive GaN power device supply chains where dual regulatory pressure from OEMs and export requirements accelerates reformulation demand. Target India's Semiconductor Mission beneficiaries in Gujarat and Assam for localized qualification partnerships, leveraging PLI scheme visibility to bypass 12-month foundry approval timelines.
For Investors and Strategic Acquirers: Chemical conglomerates with captive semiconductor materials portfolios are the most active acquirer in this space, seeking coating precision capabilities below two-micron tolerance. Long-term viability hinges on temporary bonding application expansion in 3D-IC stacking processes. Monitor UV-release formulation patent filings as inflection indicator for technology leadership shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyimide Resin | Mitsui Chemicals' captive supply secures raw material quality for 250°C laser dicing applications. |
| Precision Coating Capacity Expansion | LINTEC Corporation's sub-two-micron tolerance sustains TSMC qualification across 300mm widths. |
| Halogen-Free Adhesive Reformulation | REACH compliance enables European automotive GaN power device market access. |
| UV-Release Platform Standardization | Nitto Denko's clean detachment chemistry consolidates fragile compound semiconductor handling. |
| Foundry Qualification Partnership | 12-18 month engagement cycles lock capacity commitments before volume certainty emerges. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tape coating engineers, foundry procurement directors, adhesive R&D leads, and semiconductor packaging specialists with secondary validation through customs trade data, METI JIS standard filings, EPA emission control disclosures, and ECHA substance registration databases. Bottom-up segment sizing and top-down market triangulation cross-validated volume and value estimates.
Segment-weighting across product type, application, thickness specification, and end-user procurement sophistication shaped the analytical framework throughout the projection horizon. CAGRs derived from installed base replacement cycles, foundry capacity expansion schedules, and advanced packaging adoption curves modeled polyimide versus acrylic adhesive mix shifts and 50µm tape penetration rates.
Revisions become necessary when foundry qualification timelines compress further, REACH substance restrictions expand beyond halogen-free mandates, or polyimide resin allocation crises disrupt supply. A model refresh is warranted upon material change in AI chiplet architecture standardization that alters temporary bonding tape specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
IC Packaging and Testing Market
Semiconductor Packaging
Through Silicon via (TSV) Packaging Market
Semiconductor Packaging
Embedded Die Packaging Market
Semiconductor Packaging
Ceramic IC Packages Market
Semiconductor Packaging
Wafer Carrier Boxes Market
Semiconductor Packaging
Chip Carrier Socket Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market
Semiconductor Packaging
Outsourced Semiconductor Assembly and Testing Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Microtube Box Market
Semiconductor Packaging
3D Semiconductor Packaging Market
Semiconductor Packaging
Antenna-In-Package Technology Market
Semiconductor Packaging
Multichip Package Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market