
 Middle East and Africa Water Detection Sensors Market | 2026-2036
Middle East and Africa Water Detection Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Water Detection Sensors Market Foresight
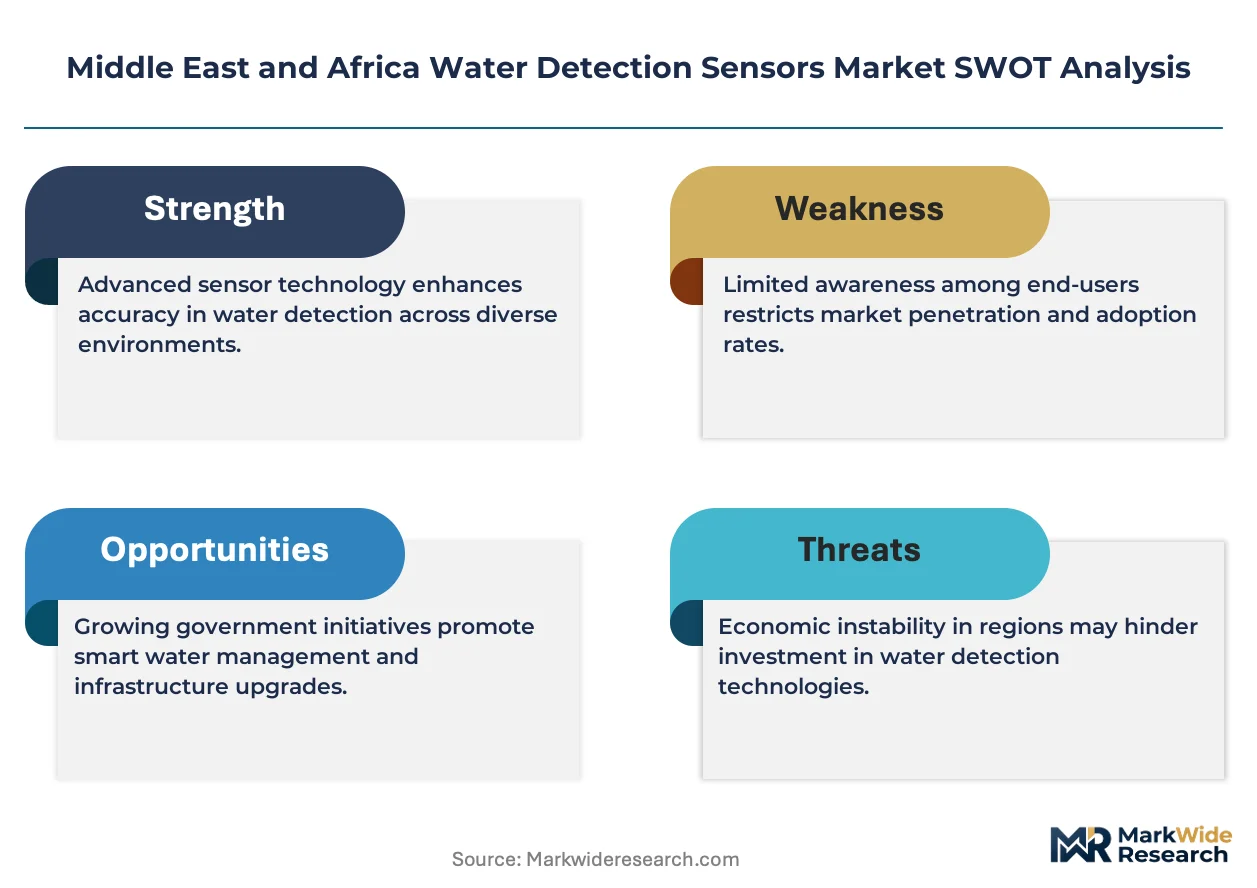
The UAE's updated green building regulations, specifically Estidama Pearl Rating requirements, is shifting procurement priorities toward IoT-enabled monitoring infrastructure. Siemens AG leverages its automation portfolio to anchor large-scale desalination facility contracts across the Gulf. Honeywell International Inc. competes through building management system integration, while Schneider Electric SE specializes in edge-computing architectures for remote pipeline networks.
Water detection sensors are electromechanical or photonic devices that identify moisture presence, liquid level changes, or flow anomalies through capacitive, resistive, optical, or ultrasonic transduction principles, typically operating within temperature ranges of minus forty to one hundred twenty degrees Celsius and IP-rated enclosures for harsh environments. These instruments serve primary industrial and commercial purposes including flood early warning, process fluid containment, and potable water distribution integrity. Capacitive and ultrasonic sensor types dominate current procurement volumes due to reliability in saline and high-temperature conditions prevalent across Middle Eastern installations. Wireless and IoT-enabled technology segments capture expanding margin pools as utilities prioritize real-time telemetry over periodic manual inspection regimes.
Saudi Arabia's National Water Regulator and South Africa's Department of Water and Sanitation enforce infrastructure monitoring standards that directly shape product certification requirements and market access conditions for imported sensor equipment. The UAE's MOHAP building safety codes and Israel's Water Authority efficiency mandates further tighten compliance frameworks for leakage prevention technology. Stakeholders must monitor evolving interoperability standards between legacy SCADA architectures and emerging cloud-native platforms to preserve contract eligibility across public utility tenders.
Market Dynamics
Smart metering mandates and desalination facility buildouts are compressing deployment timelines across municipal utilities, forcing sensor vendors to pre-certify equipment for multiple national standards simultaneously.
Growth Catalysts
- Saudi Arabia's National Water Strategy:Mandatory smart metering infrastructure upgrades across Riyadh and Jeddah distribution networks are pulling capacitive sensor volumes.
- Desalination capacity expansion:Ultrasonic flow sensors for reverse osmosis monitoring see concentrated demand from new Red Sea and Persian Gulf facilities.
- Dubai building code amendments:Automated leak detection is now compulsory in new commercial developments above 10,000 square meters.
Market Restraints
- Copper and rare-earth input volatility:Sensor coil manufacturing faces margin pressure from commodity price swings affecting capacitive element production.
- East Asian component concentration:Seventy percent of MEMS sensing elements originate from single-source suppliers in Taiwan and South Korea.
- Legacy SCADA incompatibility:Many South African municipalities operate 1990s-era control systems that cannot ingest IoT telemetry protocols.
Strategic Opportunities
- Nigeria's lagging utility infrastructure:Federal water privatization plans create first-mover positioning for leak detection system integrators.
- Edge-to-cloud architecture convergence:Schneider Electric and regional system integrators are bundling LoRaWAN gateways with sensor hardware.
- Israel Water Authority efficiency mandates:Subsidized retrofit programs for aging agricultural drip systems favor wireless soil moisture sensors.
Industry Challenges
- Embedded firmware engineering scarcity:Gulf-based utilities report six-month recruitment cycles for engineers capable of configuring Modbus-to-MQTT protocol bridges.
- Multi-jurisdiction certification timelines:Equipment must separately satisfy SFDA type approval in Saudi Arabia, BIS conformity in India-sourced components, and local metrology verification in each emirate.
- Retrofit integration complexity:Existing pipeline networks across Cairo and Johannesburg lack accessible mounting points for intrusive ultrasonic transducers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Water Detection Sensors Market |
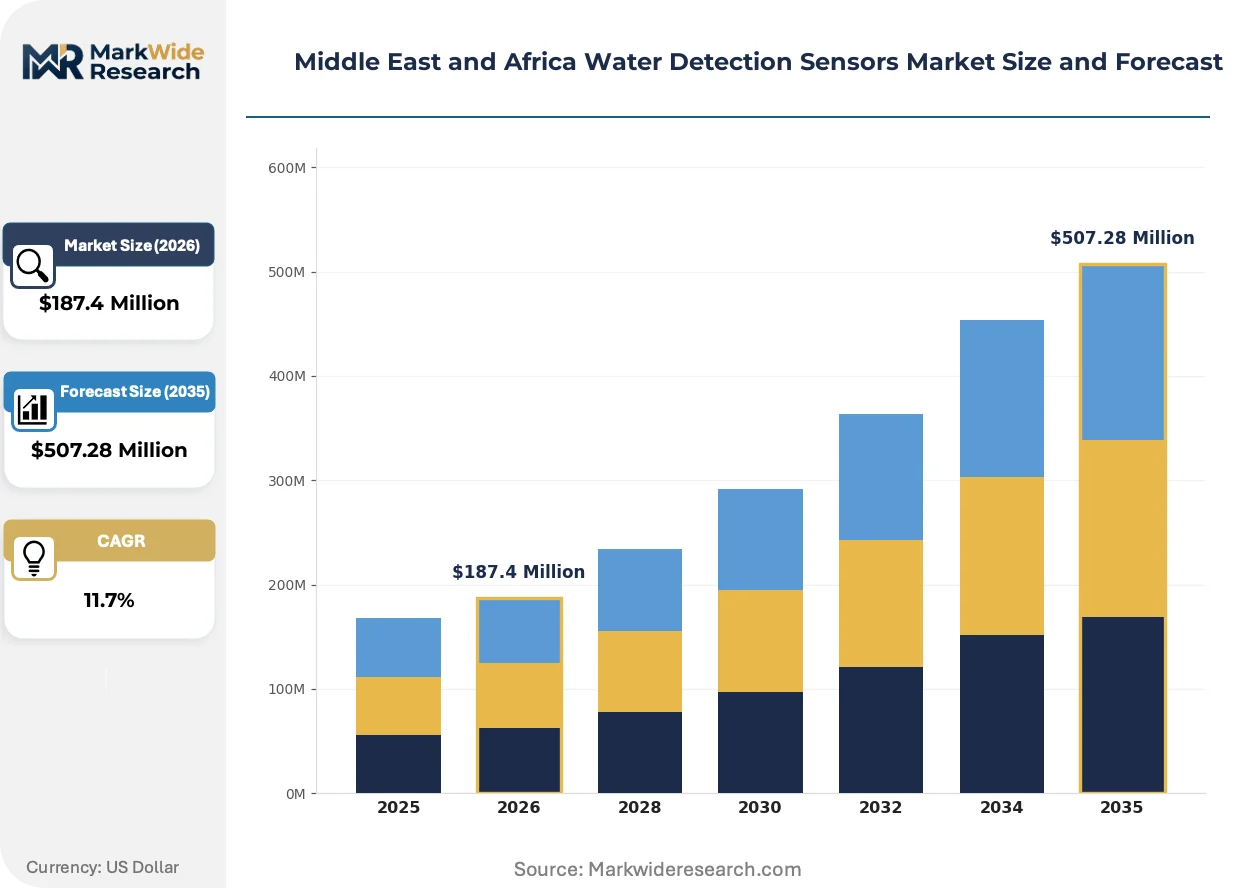
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Capacitive, Resistive, Optical, Ultrasonic Application: Flood Monitoring, Leak Detection, Environmental Monitoring, Industrial Use End User: Residential, Commercial, Industrial, Government Technology: Wired, Wireless, Hybrid, IoT-Enabled |
| Companies Covered | Honeywell International Inc., Siemens AG, Schneider Electric SE, ABB Ltd., Emerson Electric Co., KROHNE Group, Endress+Hauser AG, Aqualeak Detection Ltd., WINT – Water Intelligence, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Water Detection Sensors Market Shifts & Advancements
Photonic sensing architectures and AI-enabled anomaly detection are displacing electromechanical designs in high-value installations, while procurement patterns favor bundled hardware-software-service contracts over component-only sales.
Photonic leak detection is absorbing market share from traditional resistive probes in offshore oilfield water injection systems. Saudi Aramco and ADNOC facilities are piloting fiber-optic distributed temperature sensing for subsea pipeline integrity. This photonic shift is absorbing the premium segment once dominated by capacitive arrays, compressing average selling prices for conventional designs.
MOHAP's 2024 update to UAE Fire and Life Safety codes mandates continuous water monitoring in healthcare facilities and high-rise residential towers. The regulation requires real-time alarm transmission to civil defense command centers, not merely local facility alerts. Private hospital operators in Dubai and Abu Dhabi are accelerating procurement of IoT-enabled sensor networks to meet compliance deadlines.
Performance-based service contracts are displacing capital expenditure purchases among South African municipal utilities. Johannesburg Water and eThekwini Metro now contract for guaranteed leakage reduction outcomes rather than buying sensor hardware outright. This model shift is most visible in the Western Cape, where drought-driven water tariffs make conservation outcomes financially material to utility budgets.
Middle East and Africa Water Detection Sensors Market Segmentation
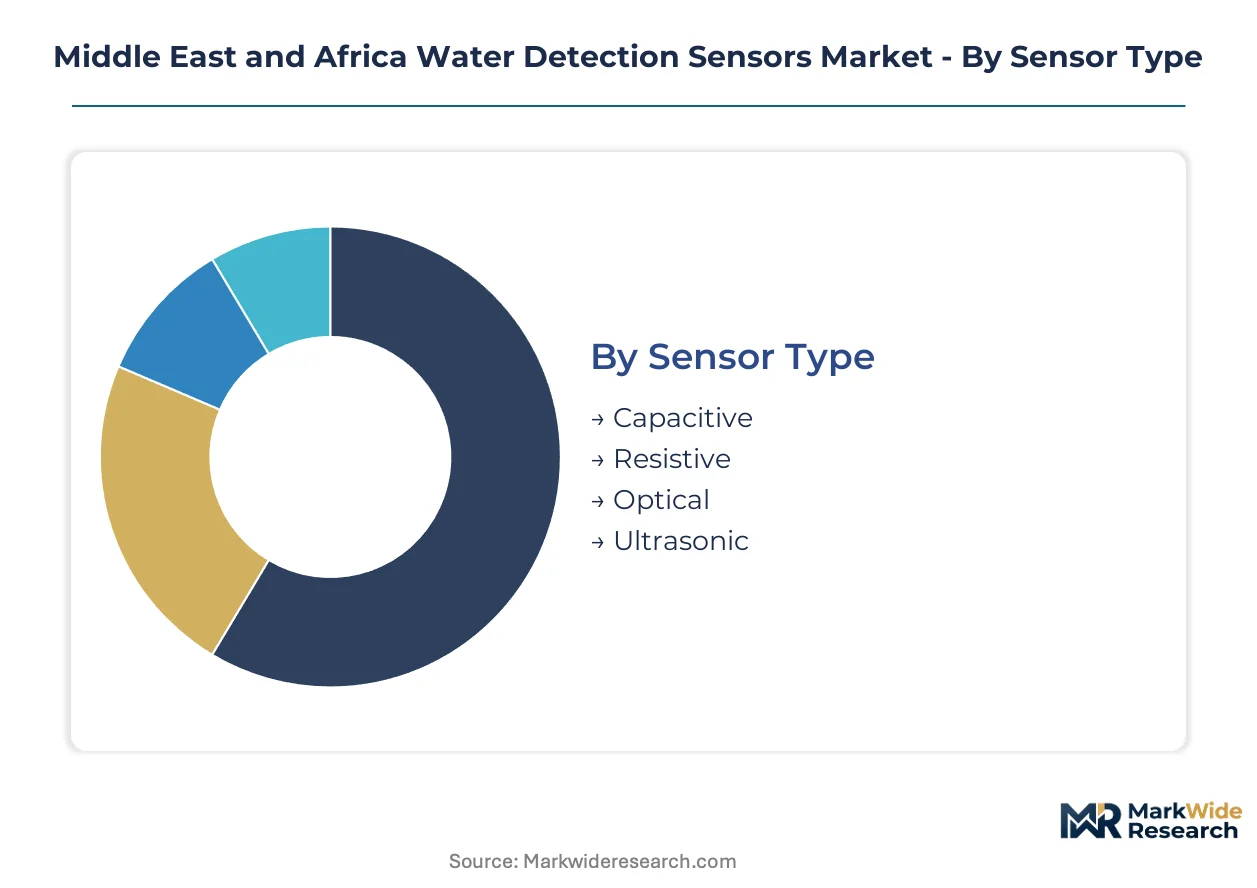
Water detection sensor procurement across the Middle East and Africa fragments sharply by technical specification and connectivity architecture. Capital allocation patterns diverge between legacy infrastructure retrofits and greenfield smart city deployments, with each segment demanding distinct engineering certifications and interoperability protocols.
Sensor Type:
Capital intensity escalates with measurement precision and environmental hardening requirements, driving divergent procurement strategies across municipal utilities and industrial operators.
- Capacitive:These sensors detect liquid presence through dielectric constant changes between conductive plates, achieving reliable performance in saline conditions prevalent at Saudi desalination plants. Dubai's building codes specify capacitive arrays for high-rise leak detection systems, pulling procurement volumes from commercial real estate developers seeking Estidama Pearl certification.
- Ultrasonic:Non-contact measurement via piezoelectric transducers enables flow monitoring in pressurized reverse osmosis trains without pipe intrusion. New Red Sea desalination facilities specify ultrasonic configurations for continuous membrane performance tracking, absorbing premium engineering budgets from facility EPC contractors.
- Resistive:Simple conductivity-based designs serve cost-constrained agricultural drip monitoring across Israel's subsidized retrofit programs.
- Optical:Photonic architectures using infrared absorption spectroscopy target offshore oilfield water injection integrity at ADNOC and Saudi Aramco facilities.
Most installed capacity flows through capacitive sensors. Expansion is steepest in ultrasonic configurations.
Application:
End-use requirements dictate sensor durability specifications and telemetry complexity, with industrial process control demanding the most sophisticated integration architectures.
- Leak Detection:Pipeline integrity systems combine point-source moisture sensors with pressure differential algorithms to pinpoint breach locations within municipal distribution grids. Johannesburg Water's performance-based service contracts specify guaranteed leakage reduction outcomes, shifting procurement toward integrated detection networks rather than standalone hardware.
- Flood Monitoring:Ultrasonic level sensors deployed in wadi channels and urban drainage networks feed real-time telemetry to civil defense command centers under UAE MOHAP's updated safety mandates. Abu Dhabi and Dubai municipalities are accelerating sensor network procurement to meet continuous monitoring requirements for healthcare facilities and residential towers.
- Environmental Monitoring:Groundwater table tracking across South Africa's Western Cape drought zones employs wireless soil moisture arrays.
- Industrial Use:Process fluid containment at chemical processing facilities requires ATEX-certified optical probes.
Leak detection commands the largest installed base. Flood monitoring is climbing the fastest.
End User:
Procurement authority and budget cycles vary dramatically across customer types, with government tenders imposing the most stringent certification and localization requirements.
- Industrial:Desalination plant operators and oilfield service companies specify redundant sensor arrays with SIL-rated safety integrity levels, driving capital expenditure toward high-availability configurations. Saudi Arabia's National Water Regulator mandates smart metering infrastructure upgrades that pull industrial-grade capacitive sensors into Riyadh and Jeddah distribution networks.
- Government:Municipal utilities across South Africa's Department of Water and Sanitation jurisdiction enforce infrastructure monitoring standards that shape product certification requirements for imported equipment. Federal water privatization plans in Nigeria create positioning opportunities for system integrators offering guaranteed outcome contracts.
- Commercial:Dubai building codes now require automated leak detection in new developments above 10,000 square meters.
- Residential:Smart home integration drives demand for WiFi-enabled point sensors in UAE luxury developments.
Industrial facilities deploy the densest sensor concentrations. Government procurement is expanding most quickly.
Technology:
Connectivity architecture determines integration complexity and recurring service revenue potential, with wireless deployments requiring substantial edge infrastructure investment.
- IoT-Enabled:Cloud-native sensor platforms with embedded MQTT protocol stacks enable real-time anomaly detection through machine learning pipelines. Schneider Electric and regional system integrators bundle LoRaWAN gateways with hardware deployments across remote pipeline networks, capturing expanding margin pools from telemetry subscription services.
- Wireless:Battery-powered LoRa and NB-IoT devices eliminate trenching costs for retrofit installations across Cairo and Johannesburg's legacy pipeline networks lacking accessible mounting points. Israeli Water Authority efficiency mandates subsidize wireless soil moisture sensors for aging agricultural drip systems.
- Wired:RS-485 and 4-20mA analog outputs persist in 1990s-era SCADA architectures that cannot ingest modern telemetry protocols.
- Hybrid:Dual-path redundancy combines wired primary measurement with wireless backup transmission for critical infrastructure.
Wired connections still dominate legacy infrastructure. IoT-enabled platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Water detection sensor deployment across the Middle East and Africa traces its commercial lineage to desalination infrastructure buildouts that began in Saudi Arabia and the UAE during the 1970s-1980s, with subsequent technology transfer enabling localized manufacturing and system integration capabilities across the Gulf and into North Africa.
Saudi Arabia
National Water Strategy mandates are pulling capacitive sensor volumes into Riyadh and Jeddah distribution networks for smart metering infrastructure. The Saudi Food and Drug Authority enforces type approval requirements that shape product certification timelines for imported equipment. Eastern Province desalination facilities specify ultrasonic flow sensors for reverse osmosis membrane performance tracking.
United Arab Emirates
Dubai's amended building codes now require automated leak detection in commercial developments exceeding 10,000 square meters. The Ministry of Health and Prevention updated 2024 Fire and Life Safety codes mandate continuous water monitoring with real-time alarm transmission to civil defense command centers. Abu Dhabi municipalities are accelerating sensor procurement for healthcare facility compliance.
South Africa
Johannesburg Water and eThekwini Metro have shifted to performance-based service contracts guaranteeing leakage reduction outcomes rather than capital hardware purchases. The Department of Water and Sanitation enforces infrastructure monitoring standards that determine market access for imported sensor equipment. Western Cape drought zones employ wireless soil moisture arrays for groundwater table tracking.
Israel
Water Authority efficiency mandates subsidize retrofit programs for aging agricultural drip irrigation systems favoring wireless soil moisture sensors. The national regulator's conservation targets are compressing deployment timelines for precision irrigation technology. Agricultural clusters in the Negev and Galilee regions are absorbing concentrated volumes of battery-powered monitoring devices.
Nigeria
Federal water privatization plans are creating first-mover positioning opportunities for leak detection system integrators seeking guaranteed outcome contracts. The national infrastructure gap leaves municipal utilities dependent on foreign equipment suppliers with limited local certification frameworks. Lagos and Abuja metropolitan water authorities represent the primary near-term procurement concentration.
Middle East and Africa Water Detection Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and integration service bundling. The vendor base organizes into three tiers: diversified automation conglomerates with full-stack desalination capabilities, building management system integrators targeting commercial real estate compliance, and specialized sensor manufacturers focused on edge-computing architectures for remote pipeline networks. Competitive dynamics center on pre-certification for multiple national standards simultaneously and strategic bundling of hardware with telemetry subscription services.
Within the diversified automation tier, Siemens AG and Honeywell International Inc. occupy positions anchored by large-scale infrastructure contract access, while Schneider Electric SE exemplifies the edge-computing specialization vector targeting remote pipeline telemetry. These three entities represent distinct competitive archetypes: the German conglomerate leveraging automation portfolio breadth, the US-based multinational competing through building management integration, and the French specialist concentrating on LoRaWAN gateway bundling with sensor hardware deployments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd. |
| Emerson Electric Co. |
| KROHNE Group |
| Endress+Hauser AG |
| Aqualeak Detection Ltd. |
| WINT – Water Intelligence |
| Others |
Supply & Pricing Matrix
Copper coil and rare-earth element costs cascade through capacitive sensor manufacturing into three-tier pricing stratification across premium SIL-rated, standard industrial-grade, and economy resistive probe tiers. Procurement officers at Saudi desalination facilities and South African municipal utilities face divergent landed cost structures depending on certification complexity and gateway bundling requirements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement contracts, with SIL-rated safety integrity certifications and ATEX hazardous environment approvals commanding substantial premiums over uncertified alternatives. Price differentiation hinges on telemetry subscription bundling and edge-computing gateway inclusion, with IoT-enabled platforms capturing recurring revenue streams that commodity resistive probes cannot match. Cost compression in economy tiers is intensifying because Taiwanese MEMS foundries concentrate sensing element supply. Government tenders under Saudi Arabia's National Water Strategy exhibit lowest price sensitivity due to mandated compliance deadlines, while Nigerian privatization-bound utilities remain most cost-constrained.
Supply Chain Analysis
Refurbishment flows for legacy 1990s-era SCADA sensors create secondary parts markets across Johannesburg and Cairo, though component obsolescence limits remanufacturing viability for electromechanical designs. Manufacturing concentrates in Taiwan, South Korea, and Germany, with MEMS sensing elements drawing from single-source wafer foundries in East Asia. Supply chain risk centers on rare-earth magnet dependency for ultrasonic transducer assembly and copper price volatility affecting coil production. Distribution runs through regional system integrators who bundle Schneider Electric and Honeywell hardware with localization services for SFDA and BIS certification compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as utilities shift from hardware procurement toward guaranteed leakage reduction outcomes and real-time telemetry mandates tighten specification requirements.
For Market Incumbents: To counter photonic sensing displacement in offshore oilfield applications, Siemens AG and ABB Ltd. should deepen backward integration into fiber-optic temperature sensing component supply while accelerating pre-certification for MOHAP's updated UAE healthcare facility mandates. Certification investment in multi-jurisdiction type approvals—simultaneous SFDA, BIS, and local metrology verification—preserves contract eligibility across Gulf utility tenders. For New Entrants and Emerging Players: Enter via Nigeria's federal water privatization pipeline, where lagging infrastructure and limited local certification frameworks create positioning opportunities for leak detection system integrators offering performance-based service contracts rather than capital sales. Israeli agricultural drip retrofit programs subsidized by Water Authority efficiency mandates represent a second penetrable white-space for wireless soil moisture sensor specialists bundling LoRaWAN connectivity with hardware deployment. For Investors and Strategic Acquirers: Roll-up economics work for regional system integrators with established LoRaWAN gateway deployment capabilities because edge-to-cloud architecture convergence is compressing procurement timelines and favoring bundled hardware-software-service providers over component vendors. Acquisition targets should demonstrate existing BIS conformity and SFDA type approval pathways. Practitioners should monitor MOHAP enforcement activity and Johannesburg Water contract renewal cycles for early signals of outcome-based procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Pre-Certification | Simultaneous SFDA, BIS, and emirate-level metrology approval preserves tender eligibility across Saudi and UAE utility procurement. |
| LoRaWAN Gateway Bundling | Schneider Electric's edge-computing architecture captures telemetry subscription revenue from remote pipeline deployments. |
| Photonic Sensing R&D Investment | Fiber-optic distributed temperature sensing displaces capacitive arrays in ADNOC and Saudi Aramco offshore installations. |
| Performance-Based Service Contracts | Johannesburg Water and eThekwini Metro now contract for guaranteed leakage reduction outcomes rather than hardware purchases. |
| Backward Integration into MEMS Supply | In-house wafer sourcing mitigates single-source vulnerability from Taiwan and South Korean foundry concentration. |
Research Methodology
Multiple input streams — structured interviews with desalination plant operators and municipal utility procurement directors, technical consultations with SCADA integration engineers and edge-computing specialists, and regulatory filings from Saudi Arabia's National Water Regulator and South Africa's Department of Water and Sanitation — were reconciled against secondary validation from customs trade databases, EPC contractor project announcements, and hospital procurement records. Bottom-up sensor shipment estimates by technology type and connectivity architecture were triangulated against top-down infrastructure investment flows across the analysis window.
Data-stream reconciliation employed a demand-side analytical framework modeling procurement patterns across sensor type, application, end-user category, and technology segmentation dimensions. CAGRs were derived from installed base growth trajectories and replacement cycle compression under smart metering mandates. Forecast inputs incorporated desalination capacity buildout pipelines, Dubai building code amendment enforcement timelines, and Israeli Water Authority subsidy allocation trajectories without specifying individual project completion dates.
The model holds under sustained infrastructure investment and regulatory enforcement continuity; deviation in rare-earth supply disruption or multi-jurisdiction certification timeline extension would shift deployment velocity and vendor margin structures. Practitioners should monitor SFDA type approval backlog accumulation and Taiwanese foundry utilization rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
Gesture Recognition and Touch-Less Sensing Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Level Transmitter Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Photoelectric Sensor Market