
 Microwave Imaging Market | 2026-2036
Microwave Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Microwave Imaging Market Analytics
Aftermarket service revenue for legacy radar imaging installations is narrowing as healthcare providers shift capital toward integrated software-hardware platforms. L3Harris Technologies leverages its defense electronics heritage to dominate military-grade synthetic aperture radar contracts. Infineon Technologies AG anchors consumer-facing near-field sensor production through dedicated semiconductor fabrication capacity. Qorvo, Inc. specializes in gallium nitride front-end modules that sustain performance advantages across frequency-domain imaging architectures.
Microwave imaging employs electromagnetic radiation between 300 MHz and 300 GHz to construct tomographic or holographic representations of object interiors without ionizing exposure, with medical systems typically operating near 1-3 GHz for tissue penetration depths exceeding 10 centimeters. The technology serves non-invasive diagnostics, concealed threat detection, and materials characterization through dielectric property mapping. Radar imaging systems capture the dominant share of military and aviation security budgets due to proven long-range detection protocols, while near-field imaging segments expand fastest in breast cancer screening applications where sub-wavelength resolution proves clinically decisive. Software platforms increasingly concentrate margin pools as vendors bundle AI-enhanced reconstruction algorithms with hardware sales.
FDA 510(k) clearance pathways shape product development timelines for medical microwave tomography devices entering the US market, while EMA's Medical Device Regulation imposes clinical evidence requirements that filter smaller European entrants. The EU AI Act adds conformity obligations for diagnostic algorithms integrated into imaging software. China's NMPA accelerates review timelines for innovative medical devices under priority review channels. Stakeholders must monitor how divergent premarket approval standards between FDA and NMPA affect synchronized product launch strategies across major jurisdictions.
Market Dynamics
Software-enabled reconstruction algorithms are capturing margin pools previously held by hardware manufacturers, compressing equipment commoditization timelines and forcing vendors to bundle AI-enhanced analytics with base system sales.
Growth Catalysts
- FDA 510(k) Pathway Clarity:Streamlined premarket notification procedures for microwave tomography devices accelerate US commercialization timelines for breast cancer screening systems.
- Millimeter-Wave Security Mandates:Aviation authorities at Heathrow and Changi airports concentrate procurement demand for portal-based personnel screening systems replacing legacy metal detectors.
- Gallium Nitride Front-End Modules:Qorvo's specialized GaN fabrication sustains performance advantages across frequency-domain architectures, enabling higher-resolution imaging at reduced power consumption.
Market Restraints
- Silicon Wafer Supply Concentration:Taiwan-based foundry capacity constraints create input volatility for semiconductor-dependent RF component manufacturing.
- Clinical Evidence Burden:EMA's Medical Device Regulation imposes prospective trial requirements that filter smaller European entrants from commercializing novel tomography platforms.
- Ionizing Imaging Substitution:Established CT and X-ray modalities retain reimbursement advantages in diagnostic radiology, limiting microwave penetration in hospital procurement cycles.
Strategic Opportunities
- Near-Field Breast Screening:Sub-wavelength resolution capabilities open clinical white space in Germany where EMA guidance now permits microwave tomography alongside mammography in hospital screening programs.
- Dual-Use Defense Conversion:L3Harris leverages synthetic aperture radar heritage to repurpose military-grade signal processing algorithms for civilian security screening applications.
- Integrated Platform Bundling:Vendors capture service revenue by combining hardware sales with subscription-based AI reconstruction software, displacing legacy aftermarket maintenance contracts.
Industry Challenges
- Electromagnetic Simulation Talent Scarcity:Finite-difference time-domain modeling expertise concentrates within defense electronics firms, constraining healthcare-focused product development teams.
- Multi-Jurisdiction Certification Lag:Divergent FDA and NMPA premarket standards force asynchronous launch strategies, fragmenting R&D resource allocation across regulatory tracks.
- Legacy Radar Integration Friction:Healthcare providers face workflow disruption when retrofitting microwave tomography into existing PACS infrastructure and radiologist reading protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microwave Imaging Market |
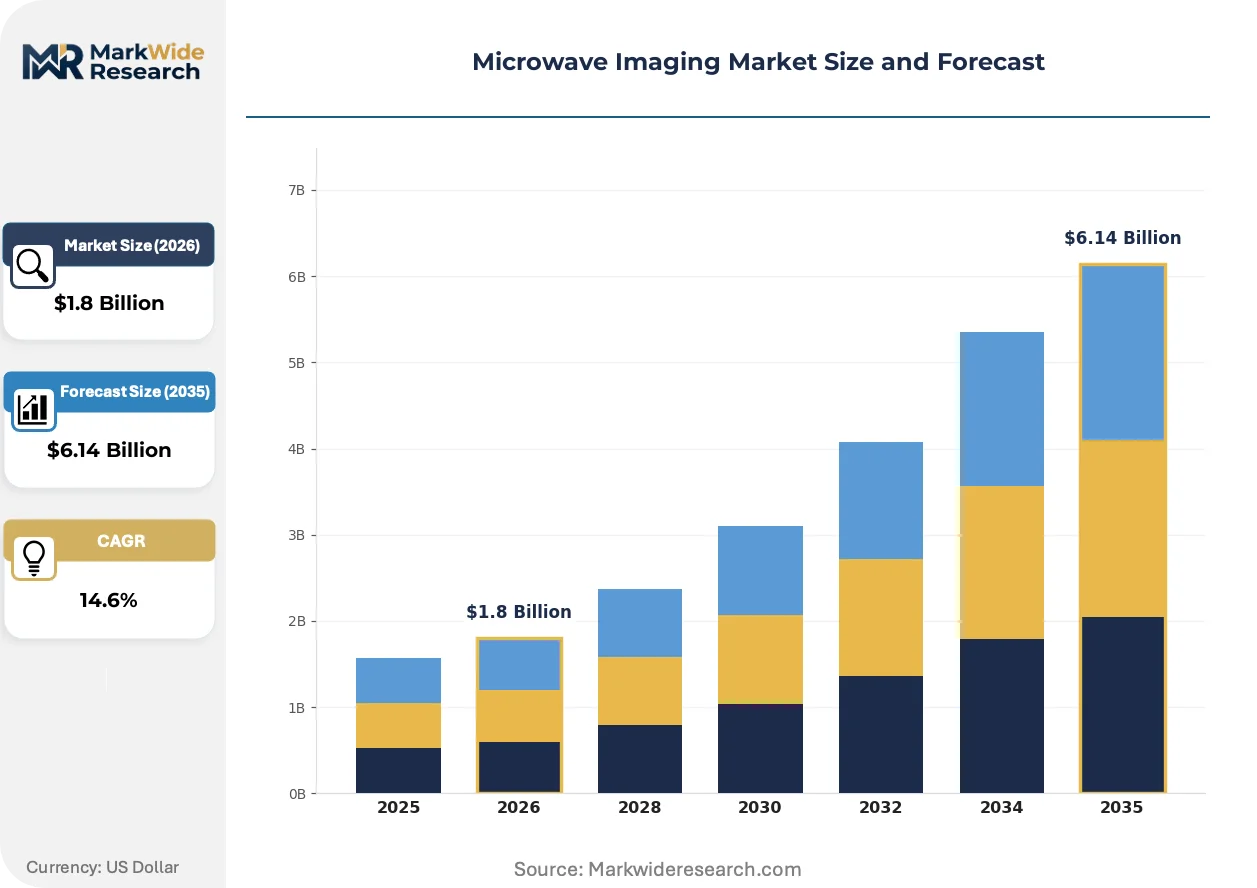
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Systems, Software, Probes, Sensors Application: Medical Imaging, Security Screening, Industrial Testing, Research Technology: Radar Imaging, Near-Field Imaging, Time-Domain Imaging, Frequency-Domain Imaging End User: Healthcare Providers, Military, Manufacturing Plants, Research Institutions |
| Companies Covered | L3Harris Technologies, Inc., Qorvo, Inc., Boeing, NXP Semiconductors N.V., Infineon Technologies AG, Teledyne Technologies Incorporated, Analog Devices, Inc., Northrop Grumman Corporation, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microwave Imaging Market Evolving Landscape
Reconstruction software is displacing hardware as the primary value capture mechanism, while regulatory frameworks in major jurisdictions accelerate review timelines for AI-integrated diagnostic platforms.
Frequency-domain imaging architectures are migrating from laboratory bench configurations toward compact clinical systems. Breast cancer screening programs in German hospitals now deploy portable microwave tomography units alongside fixed mammography suites. This migration is compressing equipment form factors and enabling point-of-care deployment models previously restricted to centralized radiology departments.
EU AI Act conformity obligations now extend to diagnostic algorithms embedded within imaging software platforms. Medical device manufacturers must document training data provenance and algorithmic transparency for CE marking renewal. Breast cancer screening applications face the steepest compliance burden given the Act's high-risk system classification for cancer diagnostics.
Hospital procurement committees now unbundle hardware acquisition from software licensing and reconstruction algorithm subscriptions. German healthcare providers negotiate three-year SaaS contracts for AI-enhanced tomographic reconstruction separate from capital equipment purchases. This unbundling is most visible in academic medical centers where radiology informatics budgets operate independently from imaging capital committees.
Microwave Imaging Market Segmentation
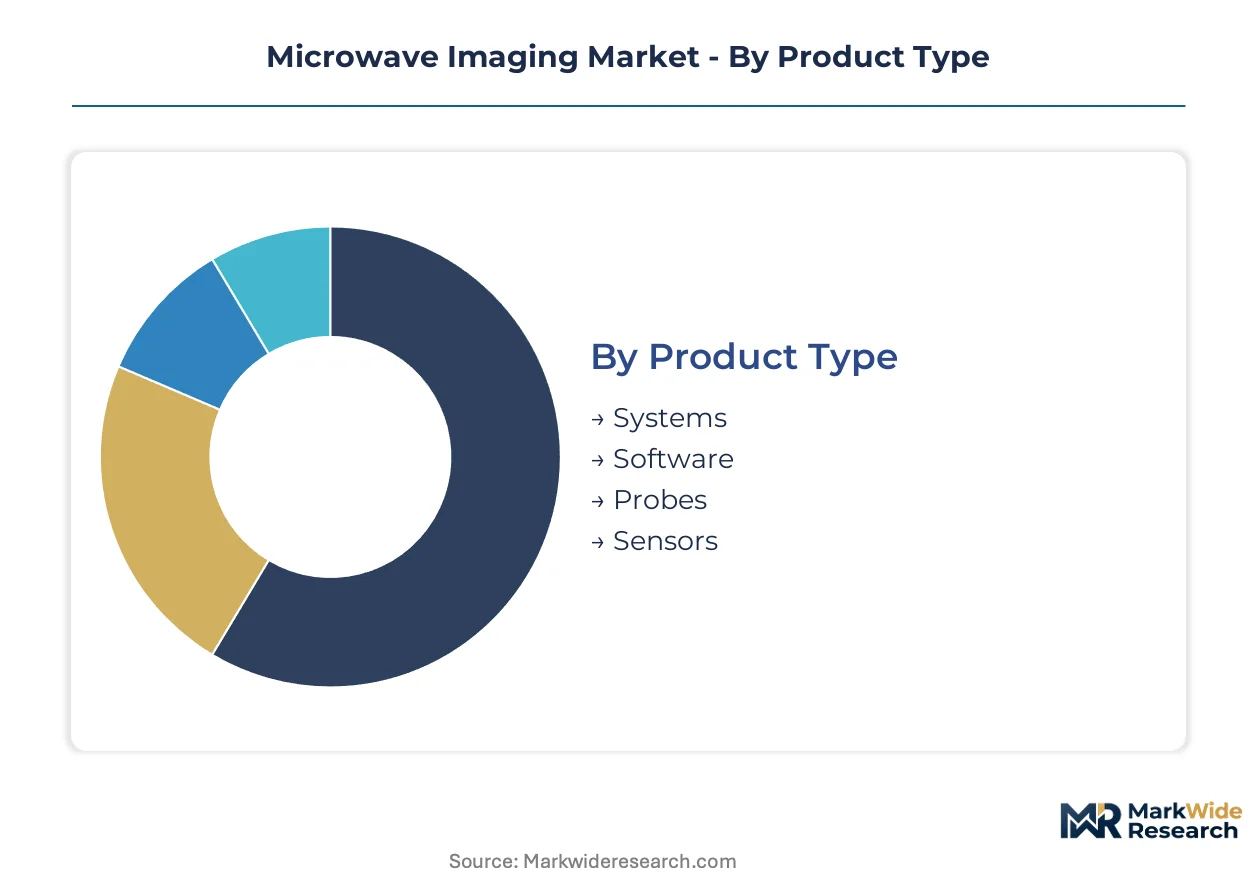
Microwave imaging vendors compete across four distinct axes that determine pricing power, regulatory pathways, and customer lifetime value. Product architecture choices lock buyers into specific software ecosystems, while application focus dictates whether vendors pursue FDA 510(k) clearance or aviation security certifications.
Product Type:
Mature hardware platforms anchor installed base maintenance revenue; emerging software layers capture margin expansion through AI-enhanced reconstruction subscriptions.
- Systems:Integrated hardware-software platforms dominate hospital capital budgets, with German breast cancer screening programs driving procurement of compact tomography units. Workflow integration with existing PACS infrastructure determines vendor selection in academic medical centers.
- Software:Reconstruction algorithms and AI-enhanced analytics now unbundle from hardware sales, with German providers negotiating separate SaaS contracts for tomographic processing. Subscription pricing displaces perpetual licenses as procurement committees separate informatics from capital equipment budgets.
- Probes:Near-field antenna arrays enable portable deployment models for point-of-care diagnostics.
- Sensors:RF front-end components concentrate in defense electronics supply chains.
Systems handle the majority of throughput; Software is expanding most quickly on share.
Application:
Medical and security verticals operate on divergent procurement cycles, with healthcare favoring multi-year capital planning and aviation security responding to regulatory mandate timelines.
- Medical Imaging:Breast cancer screening applications exploit microwave tomography's ionizing-free tissue penetration, with German hospitals now deploying units alongside mammography suites under EMA guidance. Sub-wavelength resolution capabilities open clinical white space where dense breast tissue limits X-ray efficacy.
- Security Screening:Millimeter-wave portal systems replace legacy metal detectors at Heathrow and Changi airports, concentrating procurement demand for personnel screening platforms. Aviation authority mandates compress deployment timelines and favor vendors with established defense electronics heritage.
- Industrial Testing:Dielectric property mapping serves materials characterization in manufacturing quality control.
- Research:Laboratory bench configurations drive early-stage algorithm development and clinical evidence generation.
Medical Imaging commands the dominant revenue pool; Security Screening climbs the fastest on deployment velocity.
Technology:
Frequency-domain architectures concentrate commercial deployment; time-domain approaches remain laboratory-bound despite theoretical resolution advantages.
- Radar Imaging:Synthetic aperture protocols capture dominant military and aviation security budgets through proven long-range detection capabilities. Signal processing algorithms from defense applications transfer to civilian screening platforms, compressing development timelines for dual-use vendors.
- Near-Field Imaging:Sub-wavelength resolution enables breast cancer screening applications where tissue heterogeneity demands precise dielectric mapping. German hospital programs validate clinical utility, creating reference sites for geographic expansion.
- Time-Domain Imaging:Pulse-based architectures offer theoretical advantages in resolution but face commercialization barriers from computational reconstruction complexity.
- Frequency-Domain Imaging:Stepped-frequency approaches dominate compact clinical system designs, balancing resolution with hardware miniaturization constraints.
Radar Imaging absorbs the largest procurement volumes; Near-Field Imaging gains share fastest in clinical validation.
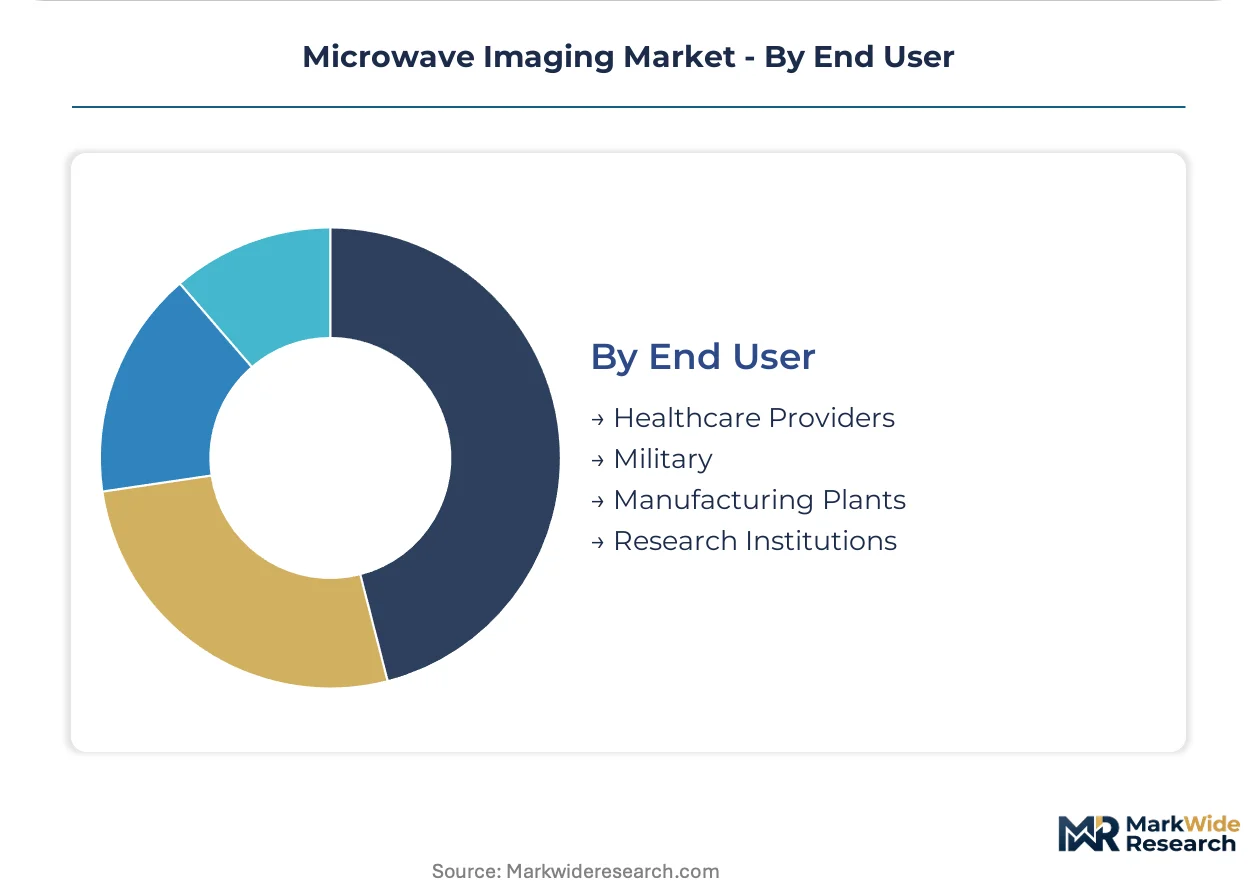
End User:
Healthcare procurement operates through radiology capital committees; military and manufacturing buyers prioritize supply chain security and interoperability certifications.
- Healthcare Providers:Hospital systems in Germany integrate microwave tomography into screening programs, with procurement decisions splitting between radiology informatics and imaging capital committees. EMA Medical Device Regulation compliance filters vendor pools, favoring established medical device manufacturers over emerging entrants.
- Military:Defense electronics budgets sustain synthetic aperture radar development, with signal processing expertise concentrating in contractors with heritage platforms. Dual-use conversion opportunities emerge as civilian security screening demand absorbs military-grade algorithm portfolios.
- Manufacturing Plants:Industrial non-destructive testing applications exploit dielectric contrast for quality control in composite materials.
- Research Institutions:Academic medical centers drive clinical evidence generation and algorithm training data collection for regulatory submission packages.
Healthcare Providers generate the dominant revenue stream; Military end-use shows steepest expansion trajectory through dual-use platform conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aviation security buyers in Singapore demonstrate the lowest price elasticity, accepting premium millimeter-wave portal systems at Changi Airport, while healthcare procurement committees in India negotiate aggressively on hardware costs. German hospital systems occupy the middle ground, balancing clinical evidence requirements against total cost of ownership. Chinese manufacturing plants prioritize unit economics over software subscriptions.
United States
FDA 510(k) clearance pathways accelerate commercialization timelines for breast cancer screening systems entering hospital networks. The agency's streamlined premarket notification procedures compress regulatory lead times versus European counterparts. Boston's academic medical centers drive clinical evidence generation for microwave tomography algorithms, creating reference sites for domestic geographic expansion.
Germany
Hospital screening programs in Bavaria and North Rhine-Westphalia now deploy microwave tomography units alongside mammography suites under EMA guidance. The Medical Device Regulation imposes prospective trial requirements that filter smaller European entrants from commercializing novel platforms. Munich's technical universities partner with medical device manufacturers to validate sub-wavelength resolution capabilities in dense breast tissue applications.
China
NMPA priority review channels accelerate timelines for innovative medical devices targeting domestic hospital procurement cycles. The regulator's accelerated pathways compress premarket approval durations for microwave imaging systems with established clinical evidence packages. Shenzhen's electronics manufacturing clusters supply RF front-end components for compact clinical system designs, enabling cost-competitive domestic production.
Singapore
Changi Airport's aviation security mandates concentrate procurement demand for millimeter-wave portal systems replacing legacy metal detectors. The Civil Aviation Authority of Singapore imposes personnel screening standards that favor vendors with established defense electronics heritage. The city-state's procurement committees accept premium pricing for integrated hardware-software platforms with proven detection protocols.
United Kingdom
Heathrow Airport's security screening deployments drive demand for radar imaging systems with synthetic aperture processing capabilities. The UK Civil Aviation Authority aligns procurement standards with EU aviation security regulations post-Brexit, maintaining certification continuity. London's defense electronics contractors leverage military-grade signal processing expertise for civilian security platform conversion.
Microwave Imaging Market Competitive Landscape
Capability concentration sits with defense electronics heritage players; scale advantage sits with semiconductor fabricators with dedicated RF component capacity. The vendor base stratifies across three tiers: integrated platform providers bundling hardware with AI-enhanced reconstruction software; specialized RF component suppliers capturing front-end module margins; and emerging clinical device entrants navigating regulatory evidence requirements. Dominant competitive moves include dual-use technology conversion from military to civilian applications and subscription-based software licensing displacing perpetual hardware sales.
Within the defense heritage tier, L3Harris Technologies, Inc. and Northrop Grumman Corporation exemplify synthetic aperture radar expertise transferable to civilian security screening. Among semiconductor specialists, Qorvo, Inc. occupies a position representing gallium nitride front-end module fabrication, while Infineon Technologies AG anchors consumer-facing near-field sensor production through captive fabrication capacity. These named entities represent archetypal competitive positions rather than exhaustive market coverage.
| Leading Market Players |
|---|
| L3Harris Technologies, Inc. |
| Qorvo, Inc. |
| Boeing |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| Teledyne Technologies Incorporated |
| Analog Devices, Inc. |
| Northrop Grumman Corporation |
| Thales Group |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Taiwan-based foundry capacity for gallium nitride wafers determines both pricing tier spreads and supply chain shape across microwave imaging component markets. This concentration forces tiered hardware pricing while compressing margins for system integrators lacking captive semiconductor fabrication.
Pricing Analysis
Long-term SaaS contracts for AI reconstruction algorithms now dominate hospital procurement, displacing perpetual software licenses. Three-tier pricing structure across premium, standard, and economy levels separates defense heritage vendors with bundled analytics from emerging hardware-only entrants. Cost compression in economy-tier security screening hardware is intensifying because Chinese RF component suppliers are expanding millimeter-wave module output. Aviation security buyers at Singapore's Changi Airport demonstrate lowest price sensitivity, accepting premium integrated platforms, while Indian hospital procurement committees negotiate aggressively on capital equipment costs.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for RF front-end module sourcing. Manufacturing concentration in Taiwan, South Korea, and China feeds gallium nitride substrate production, silicon wafer fabrication, and compact antenna array assembly. The supply chain draws from specialized semiconductor foundries, defense electronics machine shops, and medical device contract manufacturers. Single-source vulnerability concentrates in GaN-on-SiC epitaxy services. Distribution runs through authorized component distributors serving defense primes, direct OEM relationships for hospital systems, and systems integrators for aviation security deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microwave imaging markets are entering a cyclical recovery phase as aviation security mandates and clinical validation milestones for breast cancer screening converge. Defense budget normalization post-conflict cycles and hospital capital expenditure rebounds supply the cyclical driver.
For Market Incumbents: Harden software platform moats by bundling AI reconstruction subscriptions with hardware sales, displacing legacy maintenance revenue pools. Deepen backward integration into gallium nitride front-end module fabrication to offset Taiwan foundry pricing volatility. Lock in multi-year hospital system partnerships before EMA Medical Device Regulation compliance costs filter smaller European competitors from vendor pools.
For New Entrants and Emerging Players: India's underpenetrated hospital procurement landscape offers white-space expansion for compact microwave tomography units priced below German reference sites. Target point-of-care breast screening deployments in tier-two Chinese cities where NMPA priority review accelerates regulatory timelines. Pursue software-only entry via FDA 510(k) cleared reconstruction algorithms that unbundle from incumbent hardware ecosystems.
For Investors and Strategic Acquirers: EU AI Act high-risk system classification for cancer diagnostics reshapes the acquisition landscape toward algorithm transparency documentation capabilities. Position for five-to-ten year viability through dual-use defense conversion plays and clinical evidence platform assets. Signal to watch: NMPA approval velocity for domestic Chinese microwave tomography devices as indicator of competitive pressure on Western hardware margins.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Reconstruction Software Launch | Captures recurring SaaS revenue from German hospital screening programs under EMA guidance. |
| GaN Front-End Module Backward Integration | Secures supply chain control against Taiwan foundry concentration for defense and security applications. |
| FDA 510(k) Submission Pathway | Accelerates US commercialization timelines for breast cancer screening systems versus European MDR routes. |
| Aviation Security Partnership Expansion | Concentrates procurement demand at Heathrow and Changi airports replacing legacy metal detectors. |
| Dual-Use Defense Technology Conversion | Repurposes military synthetic aperture radar algorithms for civilian security screening platforms. |
Research Methodology
The analysis maps near-field breast screening systems, millimeter-wave security portals, radar imaging platforms, and reconstruction software layers, each validated through hospital procurement managers, aviation security directors, biomedical engineers, and defense electronics program officers. Primary interview intelligence triangulates against FDA 510(k) filing databases, EMA Medical Device Regulation guidance documents, NMPA priority review announcements, and hospital capital expenditure records. Bottom-up equipment shipment tracking reconciles with top-down healthcare and security budget allocation analysis.
Assumption sets held semiconductor foundry capacity constraints and regulatory review timelines fixed while varying hospital capital cycle phases and aviation security mandate implementation rates across the projection horizon. Segmentation dimensions modeled include product architecture, application vertical, frequency-domain versus time-domain technology, and end-user procurement authority. CAGRs derive from equipment replacement cycle analysis and software subscription attach rate trajectories. Industry-specific forecast inputs incorporate GaN module cost curves and clinical evidence generation timelines for microwave tomography.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese RF component suppliers or accelerated FDA breakthrough device designations for AI-integrated platforms would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Trail Camera Market
Imaging
Global Digital Binoculars Market
Imaging
Middle East and Africa IP Camera Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Europe Multi Camera Vision Inspection Systems Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
High-Power Objective Lens Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Latin America IP Camera Market
Imaging
Global in Ceiling Camera Market
Imaging
Thermal Imaging Systems Market
Imaging
Global Waterproof Camera Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Global Thermal Imager Market
Imaging
Silent Scan Technology Market