
 LCD Digital Microscope Market | 2026-2036
LCD Digital Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
LCD Digital Microscope Market Foresight
4K-resolution imaging tiers is reorganizing competitive dynamics across the LCD digital microscope landscape. Carl Zeiss AG leverages its century-long optical heritage to dominate premium research-grade installations. Keyence Corporation anchors its position through integrated software-hardware bundles that reduce customer setup friction. AmScope competes aggressively on value-engineered benchtop systems for educational procurement channels.
An LCD digital microscope integrates a digital image sensor with a liquid-crystal display panel, typically employing CMOS or CCD sensors with 5–20 megapixel resolution and LED ring illumination to deliver real-time magnified visualization without ocular eyepieces. The device serves industrial quality control, clinical diagnostics, and academic instruction by enabling simultaneous multi-user viewing and digital image capture. Bench top configurations command the largest installed base due to their stability for manufacturing inspection workflows, while portable units represent the fastest-expanding category as field microbiology and remote teaching applications multiply. Optical technology retains the dominant revenue share, though digital-native platforms are capturing margin pools through subscription-based image analysis software.
FDA 21 CFR Part 820, ISO 13485, and CE marking under the EU MDR collectively determine market access for clinical-grade LCD digital microscopes, with compliance costs filtering out smaller assemblers from healthcare procurement. The EPA's RoHS enforcement and REACH substance restrictions in Europe further constrain component sourcing for mercury-free illumination modules. Stakeholders must weigh regulatory certification timelines against the pace of sensor resolution upgrades when allocating R&D budgets.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are expanding inline defect inspection capacity, pulling LCD digital microscope demand toward 4K-resolution metrology systems and compressing procurement cycles for sub-10-micron detection workflows.
Growth Catalysts
- FDA 21 CFR Part 820:Medical device manufacturers must maintain validated digital imaging workflows, forcing upgrade cycles from analog optical systems to traceable LCD platforms with audit-ready capture logs.
- Shenzhen-Seoul electronics clusters:Contract manufacturers in these hubs are consolidating supplier qualifications, favoring microscope vendors with localized calibration service networks.
- CMOS sensor maturation:Back-illuminated CMOS architectures now match CCD low-light performance at lower unit cost, accelerating replacement of legacy sensor inventories across educational procurement channels.
Market Restraints
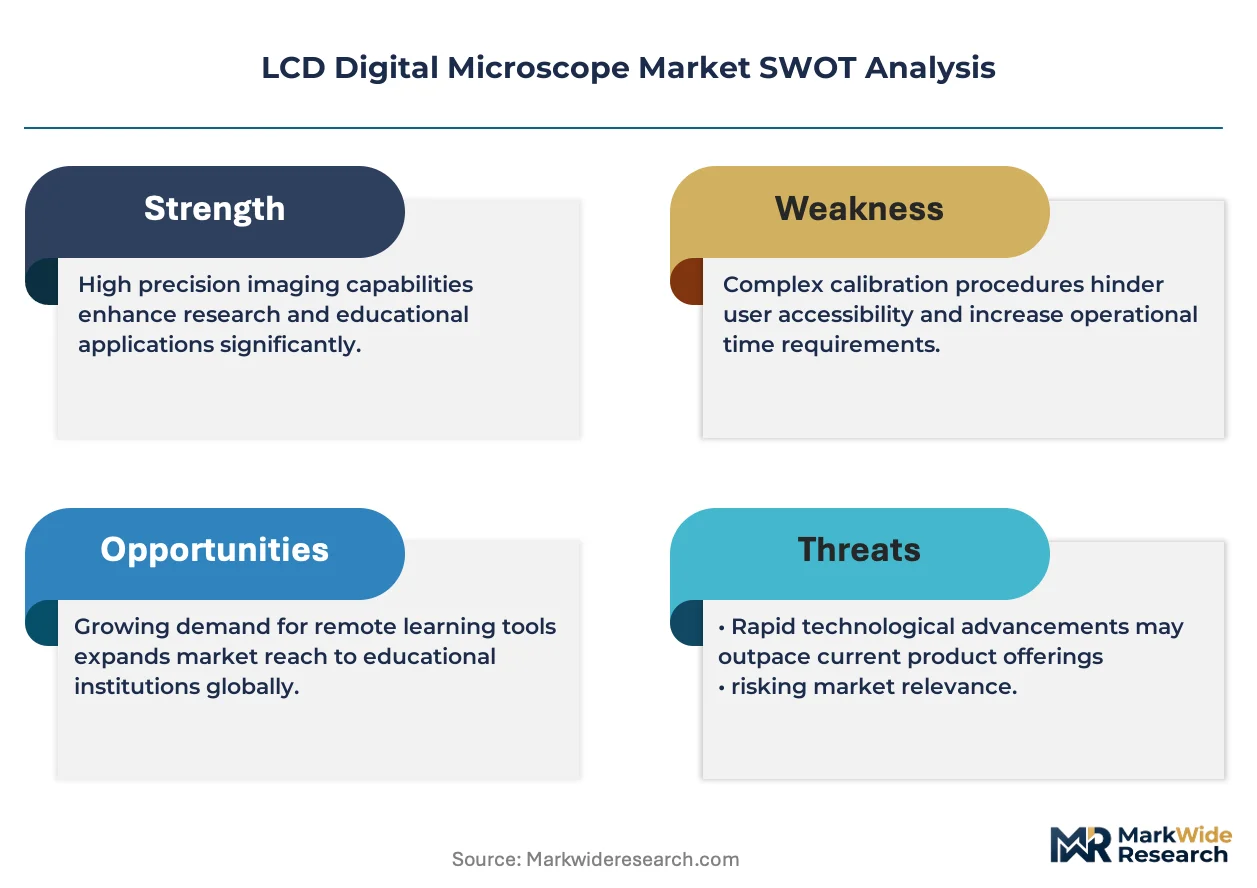
- Optical glass supply concentration:High-dispersion objective lens blanks rely on a narrow German-Japanese supplier base, exposing lead times to geopolitical friction.
- Mercury-free illumination RoHS compliance:EPA and REACH substance restrictions constrain LED phosphor sourcing, adding qualification overhead to module design cycles.
- Smartphone macro photography substitution:Portable 100x clip-on lenses satisfy casual field inspection needs, eroding entry-level portable microscope addressable demand.
Strategic Opportunities
- India BIS certification pathway:Domestic medical device manufacturing incentives under CDSCO harmonization create first-mover advantage for quality-system-ready vendors.
- AI-assisted defect classification:Machine vision algorithms trained on LCD-captured wafer images are converging with edge computing, opening subscription revenue streams.
- Remote teaching infrastructure:Brazilian federal university networks are tendering for streaming-capable benchtop systems to equip distributed microscopy labs.
Industry Challenges
- ISO 13485 auditor scarcity:Medical-grade certification timelines stretch 14-18 months as notified body capacity concentrates in Western Europe.
- Legacy LIMS integration:Manufacturing quality databases require custom API development to ingest 4K image metadata, inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LCD Digital Microscope Market |
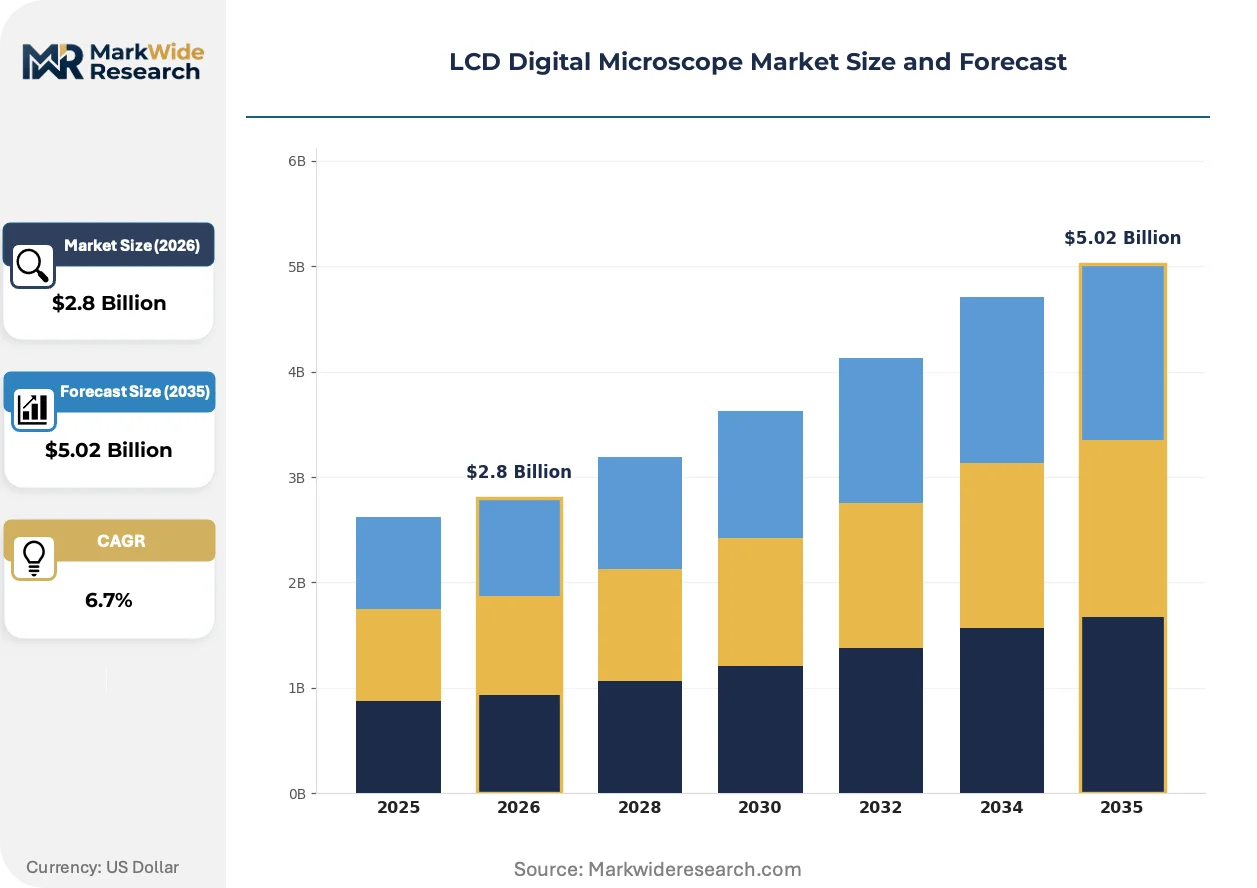
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Bench Top, Handheld, Integrated Technology: Optical, Digital, Laser, Stereo End User: Education, Healthcare, Research, Manufacturing Application: Quality Control, Teaching, Microbiology, Inspection |
| Companies Covered | Carl Zeiss AG, Hirox Co., Ltd., Leica Microsystems, Sunny Optical Technology, AmScope, Olympus Corporation, Celestron LLC, Euromex Microscopes, Keyence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LCD Digital Microscope Market Shifts & Advancements
Computational imaging pipelines are redefining optical performance benchmarks, shifting competitive advantage from hardware specifications to software-defined measurement repeatability.
Structured illumination microscopy is supplanting conventional brightfield techniques in semiconductor failure analysis labs. TSMC and Samsung Foundry process engineers are adopting these systems for sub-20nm node characterization. The technology is compressing the addressable market for research-grade electron microscopy in inline applications.
EU MDR recast and CE marking technical documentation requirements are forcing clinical-grade microscope vendors to maintain post-market surveillance systems. Manufacturers must now track device performance across installed bases for periodic safety updates. In vitro diagnostic workflows face the steepest compliance cost inflation as notified bodies apply stricter clinical evidence standards.
Universities and vocational institutes are unbundling hardware purchases from training service contracts. Procurement officers now negotiate multi-year calibration and educator certification as separate line items. This pattern is most visible in German and Australian technical college systems, where capital budgets are decoupled from operational expenditure approvals.
LCD Digital Microscope Market Segmentation
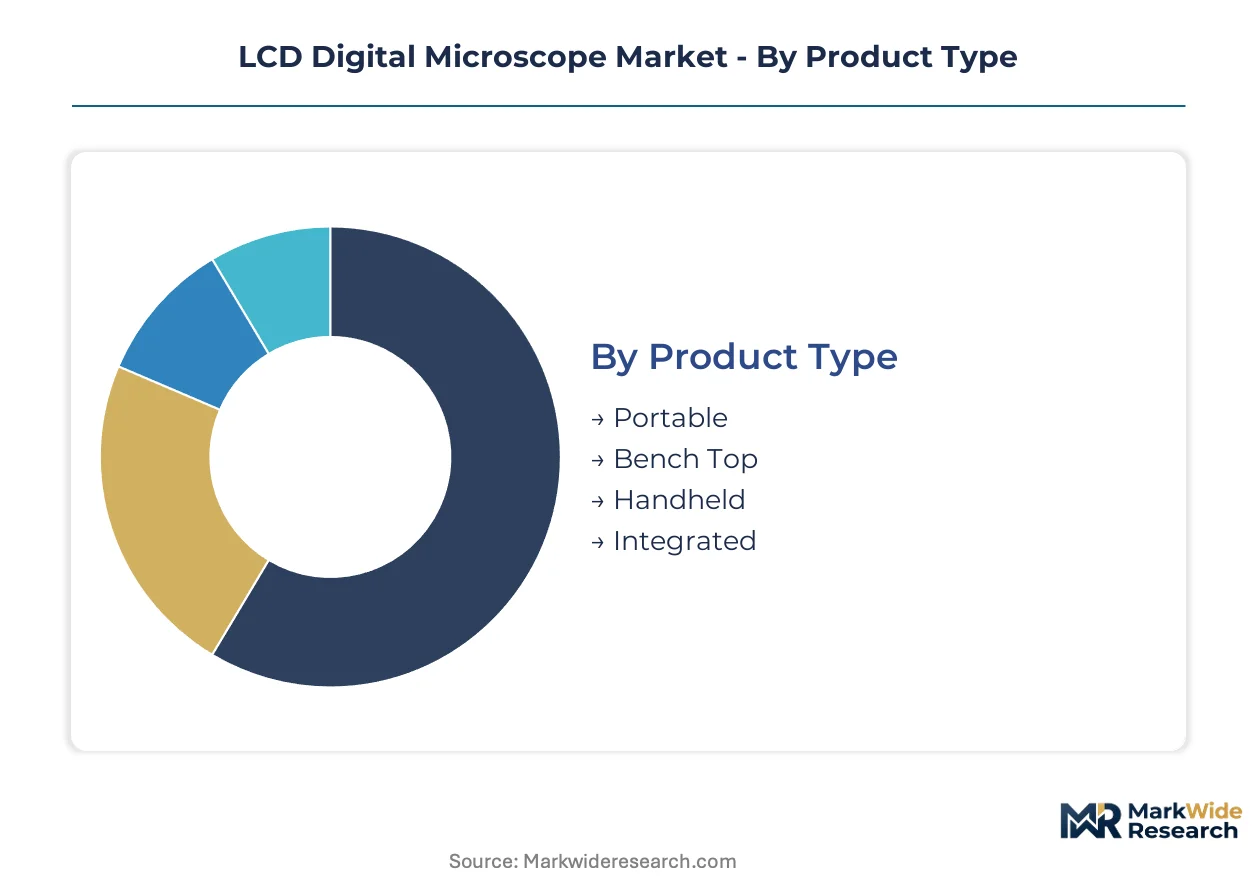
LCD digital microscope segmentation reveals how procurement priorities diverge across precision requirements, mobility constraints, and regulatory exposure. Vendors configure product portfolios around these fault lines to defend margin pools and streamline certification pathways.
Product Type:
Margin pools concentrate in configurations that balance optical stability with software integration, particularly where manufacturing workflows demand validated capture environments.
- Bench Top:These systems anchor laboratory and production floor installations with vibration-dampened stages and integrated LED ring illumination. Taiwan Semiconductor Manufacturing Company and Samsung Foundry fabs in Hsinchu and Pyeongtaek specify these units for inline defect inspection, compressing procurement cycles as sub-10nm node characterization demands intensify.
- Portable:Battery-powered units with wireless image transmission are expanding most quickly for field microbiology deployments and distributed educational networks. Brazilian federal universities tender these systems to equip remote teaching laboratories, though smartphone macro photography clip-ons erode entry-level demand.
- Handheld:Single-operator devices serve rapid diagnostic screening in veterinary and agricultural extension services.
- Integrated:Factory-embedded modules merge with automated handling systems for pharmaceutical packaging inspection lines.
Bench Top holds installed capacity. Portable is rotating up the share rankings.
Technology:
Technology selection tracks the migration from hardware-defined performance toward software-defined measurement repeatability, with sensor architecture determining cost structures.
- Digital:CMOS-native platforms capture margin expansion through subscription-based image analysis software and AI-assisted defect classification algorithms. Back-illuminated sensor architectures now match CCD low-light performance at lower unit cost, accelerating replacement of legacy inventories across educational procurement channels.
- Optical:Conventional brightfield systems retain dominant revenue share in clinical diagnostics where FDA 21 CFR Part 820 traceability requirements favor established capture workflows. High-dispersion objective lens blanks rely on a narrow German-Japanese supplier base, exposing lead times to geopolitical friction.
- Laser:Confocal variants serve semiconductor failure analysis labs demanding sub-micron depth resolution.
- Stereo:Dual-path systems maintain position in electronics assembly rework stations for three-dimensional depth perception.
Optical retains revenue concentration. Digital is climbing the fastest.
End User:
End user segmentation maps directly to regulatory burden intensity, with healthcare and manufacturing procurement subject to extended certification timelines.
- Manufacturing:Contract manufacturers in Shenzhen and Seoul electronics clusters consolidate supplier qualifications, favoring vendors with localized calibration service networks. Quality control workflows demand 4K-resolution metrology systems with audit-ready capture logs for ISO 13485 compliance.
- Healthcare:Clinical diagnostics and in vitro testing face steepest compliance cost inflation under EU MDR recast requirements, with notified bodies applying stricter clinical evidence standards. FDA 21 CFR Part 820 forces upgrade cycles from analog optical systems to traceable LCD platforms.
- Education:Universities and vocational institutes unbundle hardware purchases from training service contracts, negotiating multi-year calibration and educator certification separately.
- Research:Academic laboratories adopt structured illumination microscopy for sub-20nm node characterization, compressing addressable demand for electron microscopy in inline applications.
Manufacturing dominates volume procurement. Healthcare is gaining share fastest.
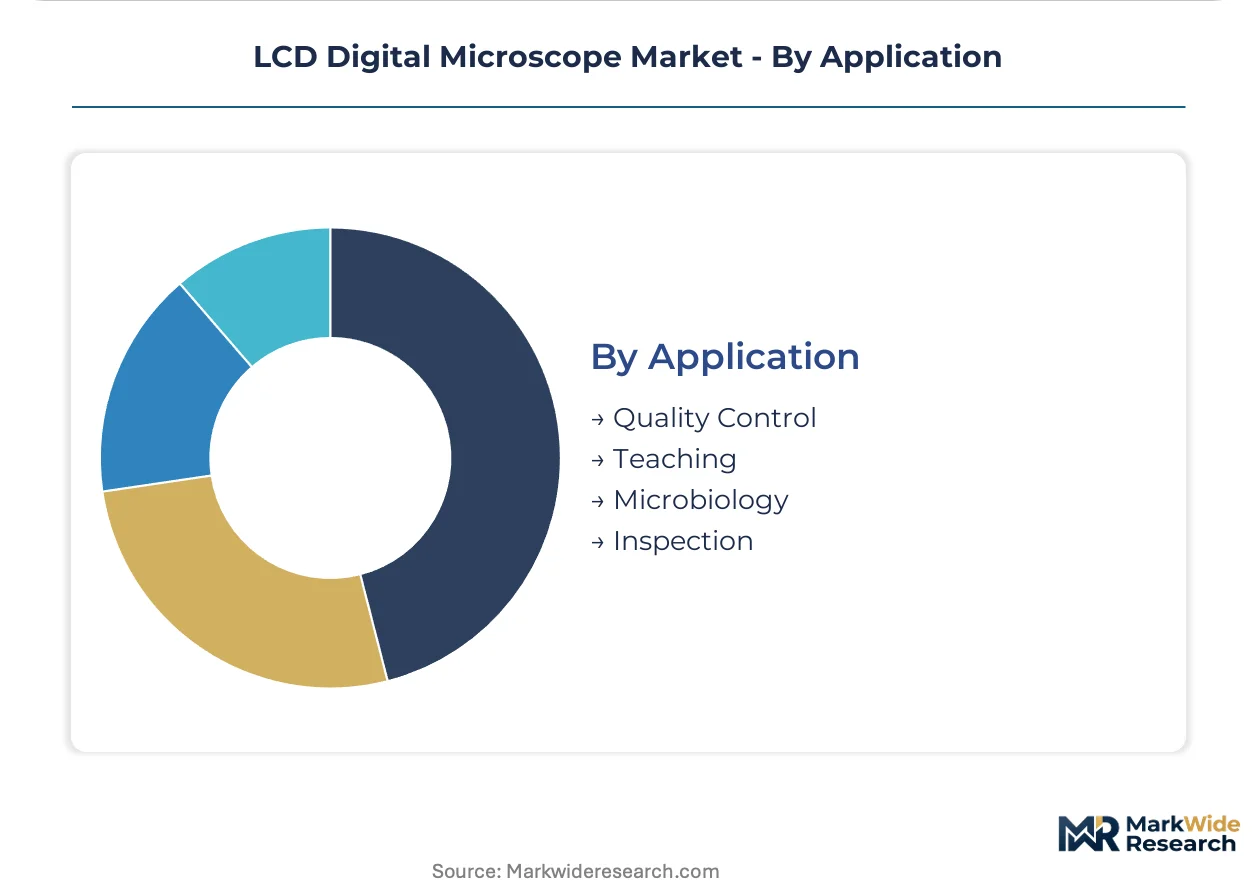
Application:
Application segmentation reveals where computational imaging pipelines displace conventional techniques, shifting competitive advantage from hardware specifications to algorithmic measurement repeatability.
- Quality Control:Semiconductor fabs in Taiwan and South Korea expand inline defect inspection capacity, pulling demand toward 4K-resolution systems. Structured illumination techniques supplant conventional brightfield methods for sub-20nm characterization.
- Teaching:Remote teaching infrastructure investments by Brazilian federal university networks tender for streaming-capable benchtop systems to equip distributed microscopy labs.
- Microbiology:Field applications multiply for portable units in environmental monitoring and agricultural extension services.
- Inspection:Pharmaceutical packaging lines integrate automated handling with embedded microscope modules for continuous verification.
Quality Control commands capital allocation. Teaching is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-dispersion objective lens blanks flow through a narrow German-Japanese supplier corridor, concentrating optical component fabrication in established precision manufacturing zones while final assembly gravitates toward electronics manufacturing clusters in East Asia.
United States
FDA 21 CFR Part 820 compliance requirements drive medical device manufacturers toward validated digital imaging workflows with audit-ready capture logs. The EPA enforces RoHS restrictions on mercury-free illumination modules, constraining LED phosphor sourcing for domestic assemblers. Boston and San Diego biotech corridors specify traceable LCD platforms for in vitro diagnostic workflows.
Germany
EU MDR recast and CE marking technical documentation requirements force clinical-grade microscope vendors to maintain post-market surveillance systems across installed bases. REACH substance restrictions constrain component sourcing for educational procurement channels. Baden-Württemberg precision optics manufacturers anchor high-dispersion objective lens supply for global metrology systems.
China
Contract manufacturers in Shenzhen electronics clusters consolidate supplier qualifications, favoring vendors with localized calibration service networks. NMPA medical device regulations and GB standards determine market access for clinical-grade systems. Yangtze River Delta semiconductor fabs expand inline defect inspection capacity, pulling demand toward 4K-resolution metrology platforms.
South Korea
Samsung Foundry and SK Hynix process engineers in Pyeongtaek and Icheon adopt structured illumination microscopy for sub-20nm node characterization. MFDS medical device quality system requirements align with international harmonization initiatives. Seoul Capital Area metrology budgets compress procurement cycles for sub-10-micron detection workflows.
Japan
METI industrial technology roadmaps prioritize computational imaging pipelines for semiconductor failure analysis applications. PMDA clinical-grade certification timelines extend 14-18 months as notified body capacity concentrates regionally. Nagoya and Osaka precision manufacturing zones supply vibration-dampened stage components for benchtop installations.
LCD Digital Microscope Market Competitive Landscape
Concentration sits with heritage optics specialists and integrated software-hardware bundlers who control premium research-grade installations and reduce customer setup friction respectively. The competitive terrain splits across three strategic archetypes: century-long optical heritage houses dominating validated clinical workflows, integrated platform vendors capturing margin through subscription software, and value-engineered assemblers serving educational procurement channels. Dominant competitive moves include geographic expansion into localized calibration service networks and portfolio diversification toward AI-assisted defect classification algorithms.
Among heritage optics houses, Carl Zeiss AG and Leica Microsystems exemplify the premium research-grade tier where validated capture environments command procurement preference. Keyence Corporation anchors the integrated platform vector with bundled software-hardware configurations that compress deployment timelines for manufacturing quality control workflows. Hirox Co., Ltd. occupies a position within the precision Japanese optical fabricator archetype serving semiconductor failure analysis applications.
| Leading Market Players |
|---|
| Carl Zeiss AG |
| Hirox Co., Ltd. |
| Leica Microsystems |
| Sunny Optical Technology |
| AmScope |
| Olympus Corporation |
| Celestron LLC |
| Euromex Microscopes |
| Keyence Corporation |
| Others |
Supply & Pricing Matrix
Wafer fab capacity utilization above 90% in Hsinchu and Pyeongtaek is compressing procurement cycles for 4K-resolution metrology systems, simultaneously concentrating supplier pricing power and elevating price floors for validated capture environments. This scale-driven dynamic tightens margins for educational procurement channels while reinforcing premium tier positions for FDA 21 CFR Part 820-compliant clinical workflows.
Pricing Analysis
FDA 21 CFR Part 820 dictates the pricing tier structure across the LCD digital microscope landscape, separating validated clinical-grade systems from benchtop educational units. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because smartphone macro photography clip-ons erode entry-level portable demand. Educational procurement channels exhibit highest price sensitivity, while semiconductor fabs in Taiwan and South Korea demonstrate lowest sensitivity due to node characterization imperatives.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication demand, while Germany and Japan supply high-dispersion objective lens blanks for precision metrology systems. Back-illuminated CMOS sensors draw from foundry partners in the Yangtze River Delta, and LED ring illumination modules source phosphor materials constrained by EPA RoHS and REACH substance restrictions. Single-source vulnerability concentrates in the German-Japanese optical glass corridor. Distribution runs through localized calibration service networks in Shenzhen and Seoul electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of ISO 13485-notified body capacity in Western Europe is extending certification timelines to 14-18 months, creating a bottleneck that filters out smaller assemblers and concentrates margin capture among quality-system-ready vendors.
For Market Incumbents: Shield premium research-grade positions by deepening backward integration into high-dispersion objective lens supply through partnerships with Baden-Württemberg precision optics manufacturers. Fortify against AI-native platform entrants by accelerating subscription-based image analysis software deployment to manufacturing quality control workflows in Taiwan and South Korea. For New Entrants and Emerging Players: Post-market surveillance service gaps in EU MDR compliance expose white-space for clinical-grade vendors willing to track device performance across installed bases. Brazilian federal university networks tendering for streaming-capable benchtop systems represent the most penetrable geography. Lead with remote teaching infrastructure bundles that decouple hardware from multi-year calibration contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform vendors bundling software-hardware configurations with AI-assisted defect classification algorithms. Long-term viability across the analysis window favors vendors with validated FDA 21 CFR Part 820 workflows and localized calibration networks in East Asian electronics clusters. Monitor notified body capacity expansion in Western Europe as the inflection signal for certification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Defect Classification Development | Machine vision algorithms trained on LCD-captured wafer images open subscription revenue streams for semiconductor failure analysis labs. |
| Localized Calibration Service Network Expansion | Shenzhen and Seoul electronics clusters consolidate supplier qualifications around vendors with regional service presence. |
| EU MDR Post-Market Surveillance System Buildout | Clinical-grade vendors must track device performance across installed bases for periodic safety updates under recast requirements. |
| Back-Illuminated CMOS Sensor Platform Migration | Educational procurement channels accelerate legacy CCD replacement as CMOS architectures match low-light performance at lower unit cost. |
| Remote Teaching Infrastructure Partnership | Brazilian federal university networks tender for streaming-capable benchtop systems to equip distributed microscopy labs. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with semiconductor process engineers, biomedical equipment procurement managers, clinical laboratory directors, and educational technology coordinators. Secondary validation drew from FDA 21 CFR Part 820 guidance documents, EU MDR technical documentation requirements, SEC filings of publicly traded optics manufacturers, and customs records for high-dispersion objective lens trade flows. Bottom-up unit economics triangulated against top-down market sizing across product type, technology, end user, and application dimensions.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product configuration, sensor architecture, regulatory compliance tier, and geographic manufacturing cluster. CAGRs were derived from slope analysis of historical procurement cycles and projected capacity expansion in Taiwan and South Korea semiconductor fabs. Forecast inputs incorporated back-illuminated CMOS sensor cost curves, notified body certification timeline trajectories, and AI-assisted image analysis software penetration rates.
Material uncertainties — geopolitical friction in optical glass supply, REACH and RoHS substance restriction evolution, and smartphone macro photography substitution thresholds — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization pace and sensor resolution upgrade cycles. Recalibration cycles align with material shifts in semiconductor node characterization demands and notified body capacity availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Cinematographic Camera Market
Imaging
Specific Imaging Solution Market
Imaging
Pico Projector Market
Imaging
High-Resolution 3D X-Ray Microscopy Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
Cooled IR Camera Market
Imaging
Digital Movie Cameras Market
Imaging
Facial Recognition Machine Market
Imaging
North America Digital Camera Market
Imaging
Mobile Imaging Market
Imaging
AI Camera Market
Imaging
Embedded Smart Cameras Market
Imaging
Instaprint Camera Market
Imaging
Camera with Flip Screen Market
Imaging
Europe IP Camera Market
Imaging
India CCTV Camera Market