
 Handheld Fluorescence Imaging Devices Market | 2026-2036
Handheld Fluorescence Imaging Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Fluorescence Imaging Devices Market Analytics
Hospital procurement departments is collapsing the historical dominance of academic medical centers as the primary buyer archetype for handheld fluorescence imaging devices. Stryker leverages its integrated surgical technologies portfolio to anchor hospital system contracts across North American metropolitan markets. Hamamatsu Photonics K.K. competes through deep specialization in photomultiplier tube miniaturization for portable fluorescence detection. Olympus Corporation sustains channel control via its established endoscopy sales infrastructure that extends into fluorescence-guided surgical applications.
Handheld fluorescence imaging devices are compact, battery-powered optical systems that excite fluorescent contrast agents with specific wavelength LEDs and capture emitted light through filtered CMOS or CCD sensors, primarily enabling real-time visualization of tissue perfusion, tumor margins, or lymphatic drainage in clinical and field settings. Near-infrared fluorescence technology dominates current revenue pools due to its superior tissue penetration depth and compatibility with indocyanine green dye, while time-resolved fluorescence represents the fastest-expanding segment as researchers demand quantitative lifetime measurements beyond simple intensity mapping. Healthcare providers constitute the most mature end-user category with established reimbursement frameworks, whereas pharmaceutical companies are emerging as a concentrated margin pool through quality-control applications in biologics manufacturing.
FDA 510(k) clearance requirements and the EU Medical Device Regulation shape product development timelines and clinical evidence standards for manufacturers seeking multi-regional market access. ISO 13485 quality management certification and IEC 60601 electrical safety standards further constrain design choices and supplier qualification processes for handheld optical medical devices. Stakeholders must monitor evolving fluorescence dye labeling requirements from EMA and PMDA, as harmonized contrast agent regulations will determine which device-software combinations achieve broad clinical adoption.
Market Dynamics
Hospital procurement departments are consolidating vendor relationships around integrated surgical platforms, collapsing the historical dominance of academic medical centers as the primary buyer archetype for handheld fluorescence imaging devices.
Growth Catalysts
- FDA 510(k) Streamlining:Accelerated clearance pathways for Class II fluorescence-guided surgery platforms reduce time-to-market for manufacturers targeting US hospital systems.
- Near-Infrared Dye Compatibility:Indocyanine green dye's established reimbursement codes in outpatient surgical settings create immediate clinical utility for compatible devices.
- Integrated Health System Standardization:Multi-hospital networks in the United States are mandating uniform intraoperative imaging protocols across cardiovascular, oncologic, and reconstructive service lines.
Market Restraints
- Photomultiplier Tube Supply Concentration:Japanese and German component specialists control miniaturized PMT manufacturing, creating single-source vulnerability for portable fluorescence detection modules.
- EU MDR Clinical Evidence Burden:Expanded post-market surveillance requirements under the Medical Device Regulation extend certification timelines and inflate regulatory compliance costs for European market entry.
- LED Excitation Source Cost Volatility:Rare earth element pricing fluctuations in near-infrared diode production compress hardware margins for device manufacturers.
Strategic Opportunities
- Pharmaceutical Quality Control Expansion:Biologics manufacturers in Switzerland and Singapore are adopting handheld fluorescence for real-time protein aggregation monitoring during fill-finish operations.
- Time-Resolved Fluorescence Convergence:Integration of picosecond-pulsed laser diodes with CMOS time-gating circuits enables quantitative lifetime imaging beyond intensity mapping.
- Field-Based Military Medicine:Combat casualty assessment protocols are incorporating portable perfusion imaging for triage decisions in austere environments.
Industry Challenges
- ISO 13485 Supplier Qualification:Optical component vendors face extended audit cycles to meet quality management certification for medical device integration.
- Fluorescence Dye Labeling Harmonization:Divergent EMA and PMDA contrast agent regulations complicate device-software combination approvals for multi-regional commercialization.
- Legacy Endoscopy Infrastructure Interoperability:Hospital IT departments struggle to integrate proprietary fluorescence data formats with existing PACS and EMR systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Fluorescence Imaging Devices Market |
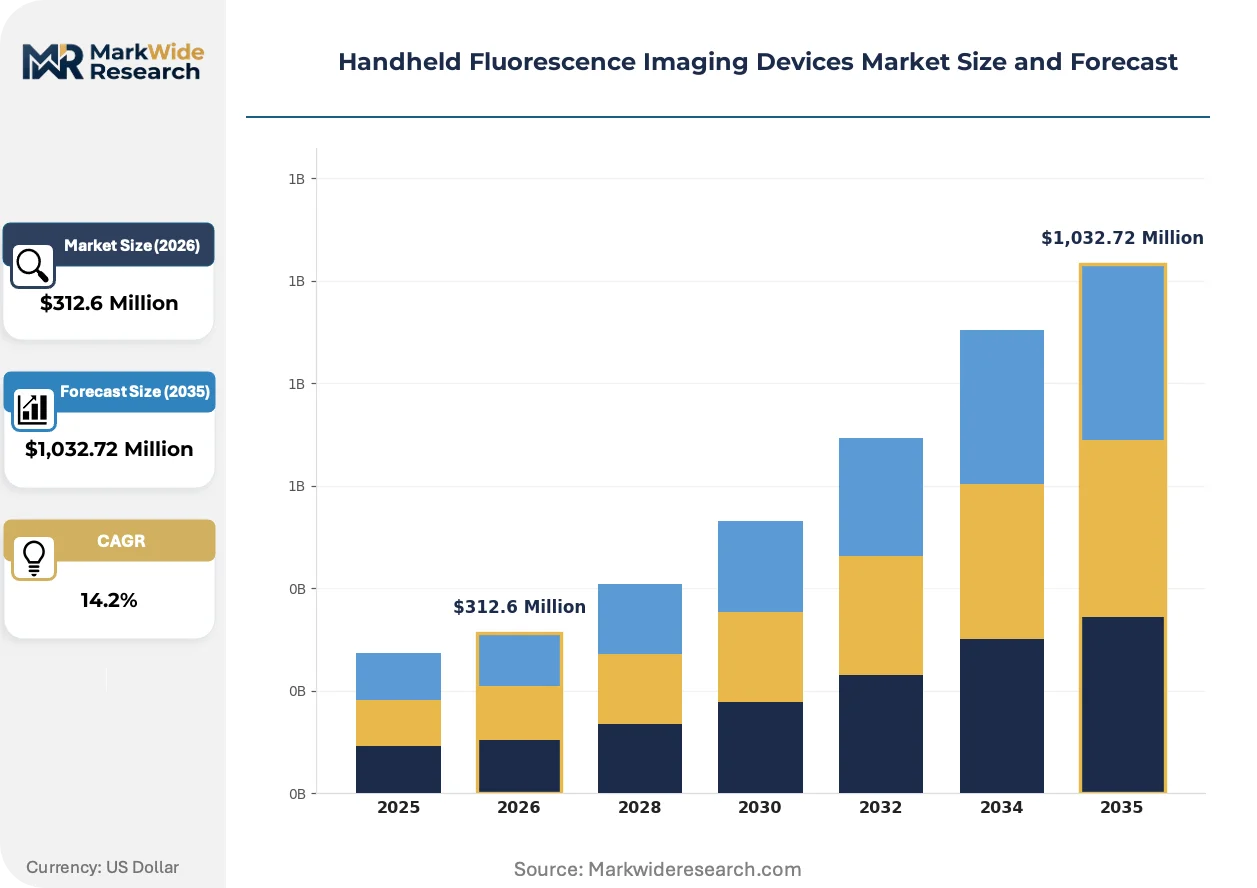
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $1,032.72 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Scanners, Handheld Cameras, Imaging Systems, Detection Modules Application: Medical Diagnostics, Environmental Monitoring, Food Testing, Research Laboratories Technology: Time-Resolved Fluorescence, Near-Infrared Fluorescence, Multiplexing, High-Throughput Screening End User: Healthcare Providers, Research Institutes, Pharmaceutical Companies, Educational Institutions |
| Companies Covered | Stryker, Olympus Corporation, KARL STORZ SE & Co. KG, Hamamatsu Photonics K.K., Fluoptics, Smith & Nephew, Kent Imaging, Shimadzu Corporation, Leica Microsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Fluorescence Imaging Devices Market Evolving Landscape
Device architecture is compressing toward chip-scale integration, reshaping competitive differentiation from optical bench performance to embedded algorithm sophistication and wireless data architecture.
CMOS time-gated sensors with picosecond resolution are replacing legacy CCD architectures in fluorescence lifetime imaging systems. Outpatient surgical centers in the United States are adopting these platforms for lymphatic mapping procedures previously confined to academic hospitals. The technology is miniaturizing optical detection modules to smartphone-attachable form factors, collapsing the addressable market for cart-based intraoperative imaging.
The EU Medical Device Regulation's software-as-medical-device classification is redefining algorithm validation requirements for fluorescence image processing. Manufacturers must now submit clinical evidence for AI-assisted tumor margin detection as part of their conformity assessment. European notified bodies are prioritizing review queues for devices with open-architecture dye compatibility, pressuring proprietary contrast agent lock-in strategies.
Hospital value analysis committees are unbundling capital equipment purchasing from disposable supply contracts. Integrated delivery networks in Texas and California are negotiating direct device procurement while retaining flexibility on dye sourcing. This purchasing autonomy concentrates price negotiation leverage with procurement officers rather than surgeon preference cards.
Handheld Fluorescence Imaging Devices Market Segmentation
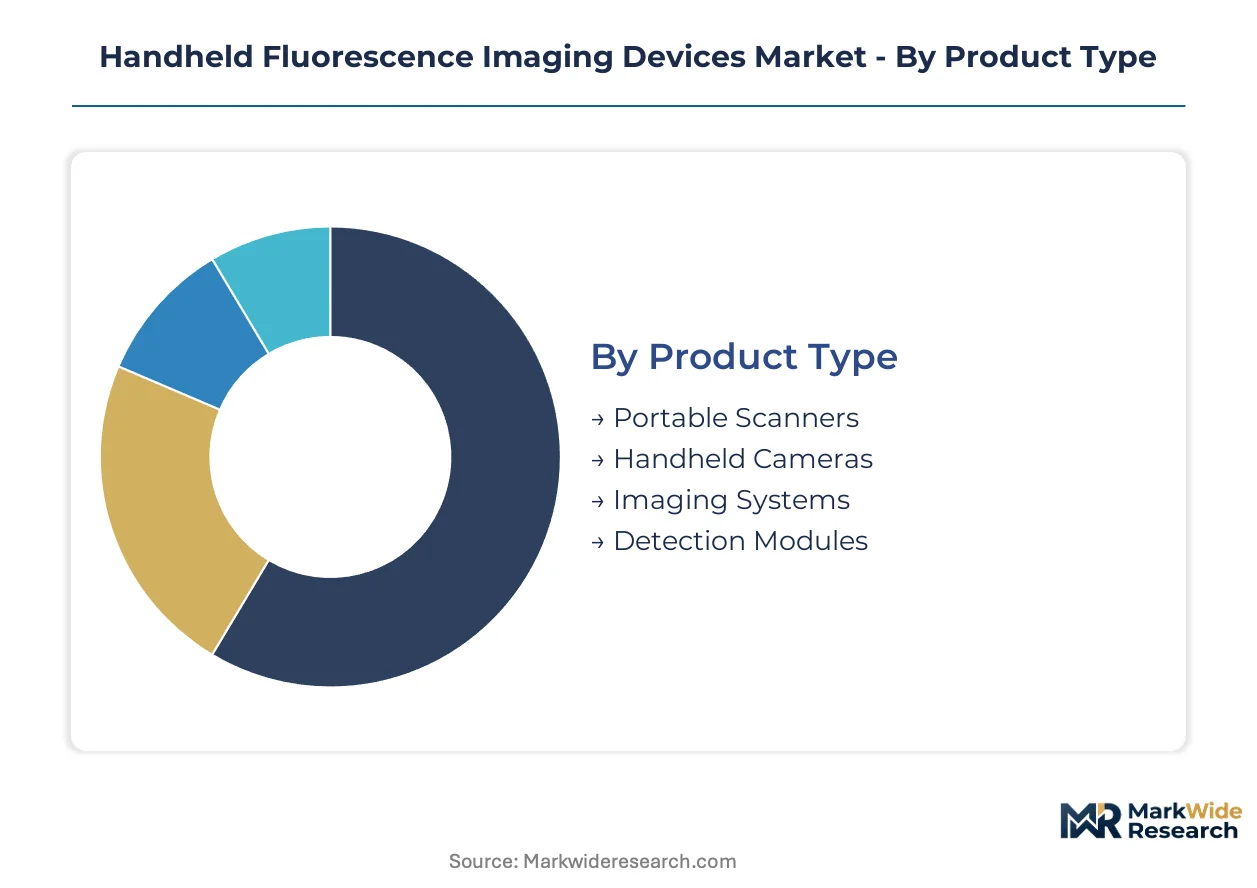
Segmentation in handheld fluorescence imaging reveals how procurement channels fragment across distinct technical specifications and end-use requirements. Each dimension—product architecture, clinical application, detection technology, and buyer type—channels through different regulatory pathways and purchasing authorities.
Product Type:
Hospital procurement departments route capital equipment through group purchasing organizations, while research buyers favor direct manufacturer relationships for portable configurations.
- Handheld Cameras:Battery-powered units with filtered CMOS sensors excite indocyanine green dye for real-time tissue perfusion visualization. Outpatient surgical centers in the United States are standardizing these for lymphatic mapping procedures previously requiring academic hospital infrastructure.
- Portable Scanners:Smartphone-attachable form factors with miniaturized optical benches collapse the addressable market for cart-based intraoperative imaging. Pharmaceutical quality control labs in Switzerland are adopting these for protein aggregation monitoring during biologics manufacturing.
- Imaging Systems:Integrated platforms with embedded algorithm suites for AI-assisted tumor margin detection.
- Detection Modules:OEM components for integration into third-party surgical navigation platforms.
By volume, Handheld Cameras leads. By growth pace, Portable Scanners is climbing the fastest.
Application:
Cost tiers separate reimbursable clinical procedures from research-funded exploratory work and regulatory-mandated safety testing.
- Medical Diagnostics:Intraoperative perfusion assessment and tumor margin delineation command premium pricing through established CPT reimbursement codes. Cardiovascular and oncologic service lines within US integrated health systems are mandating uniform fluorescence-guided protocols across metropolitan hospital networks.
- Research Laboratories:Quantitative lifetime imaging for basic science investigations operates on grant-funded procurement cycles with extended vendor qualification timelines.
- Environmental Monitoring:Field-deployable contaminant detection for water quality assessment.
- Food Testing:Rapid pathogen screening protocols for supply chain safety verification.
Medical Diagnostics captures the dominant revenue share. Research Laboratories shows the steepest expansion trajectory as picosecond-resolution time-gated sensors penetrate academic centers.
Technology:
Maturity curves separate established near-infrared platforms with dye compatibility from emerging quantitative modalities requiring novel clinical evidence.
- Near-Infrared Fluorescence:LED excitation at specific wavelengths with superior tissue penetration depth dominates current procurement. FDA 510(k) clearance pathways for Class II devices with indocyanine green compatibility streamline US market entry for manufacturers targeting hospital systems.
- Time-Resolved Fluorescence:Picosecond-pulsed laser diodes with CMOS time-gating circuits enable quantitative lifetime measurements beyond intensity mapping. EU Medical Device Regulation software-as-medical-device classification is redefining algorithm validation requirements for these platforms.
- Multiplexing:Simultaneous detection of multiple fluorescent reporters for complex tissue characterization.
- High-Throughput Screening:Automated plate-reading configurations for pharmaceutical discovery workflows.
Near-Infrared Fluorescence holds installed base leadership. Time-Resolved Fluorescence is gaining share fastest as researchers demand quantitative capabilities.
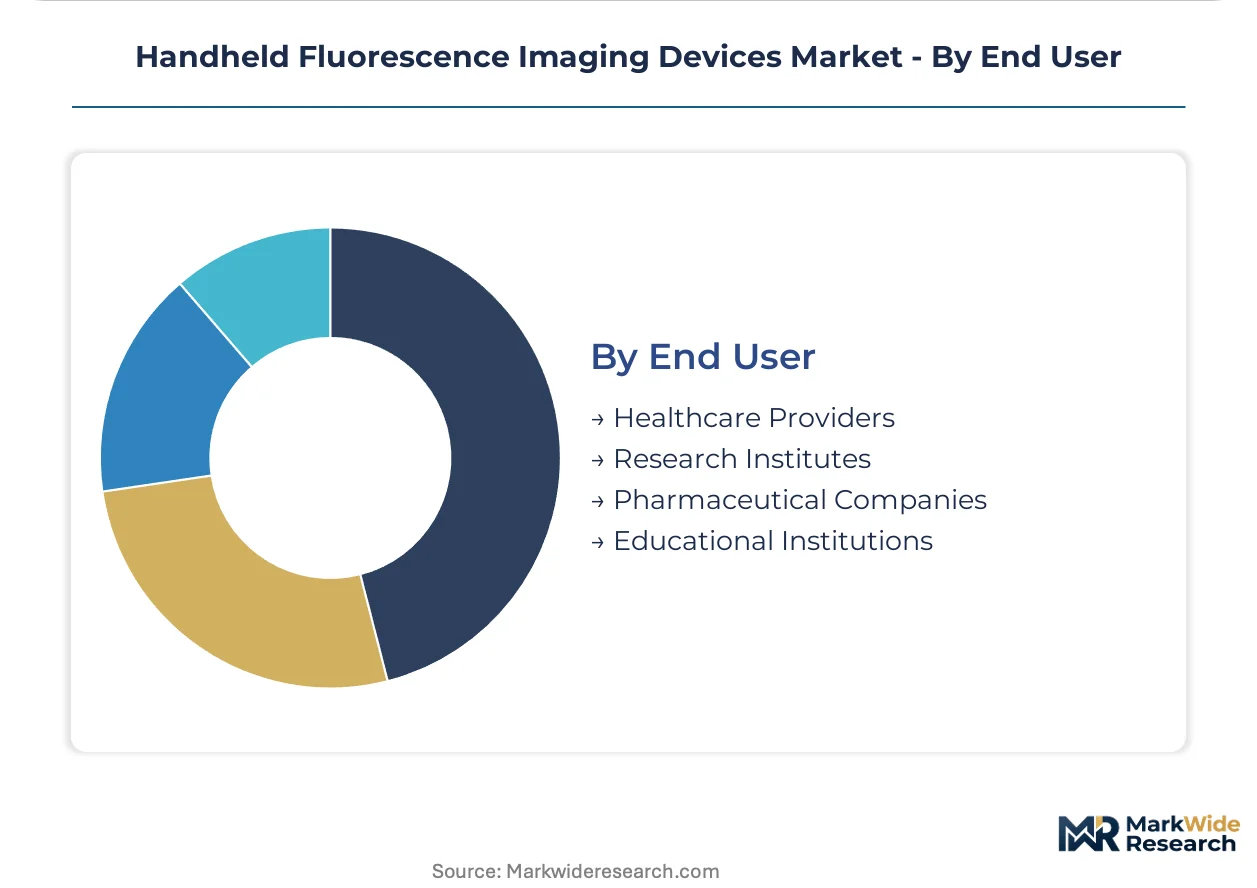
End User:
Customer type determines purchasing autonomy—surgeon preference cards versus procurement officer negotiation leverage versus grant administrator compliance requirements.
- Healthcare Providers:Hospital value analysis committees are unbundling capital equipment from disposable supply contracts. Texas and California integrated delivery networks negotiate direct device procurement while retaining flexibility on dye sourcing.
- Pharmaceutical Companies:Biologics manufacturers in Singapore are adopting handheld fluorescence for real-time quality control during fill-finish operations, creating a concentrated margin pool outside clinical reimbursement frameworks.
- Research Institutes:Academic medical centers with historical dominance in fluorescence imaging procurement.
- Educational Institutions:Training programs for surgical residents and biomedical engineering curricula.
Healthcare Providers represents the largest addressable base. Pharmaceutical Companies is expanding most quickly as manufacturing quality control applications mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German component specialists export miniaturized photomultiplier tubes to US device integrators, anchoring the transatlantic supply corridor for portable fluorescence detection modules. Japanese optical manufacturers supply CMOS time-gating circuits to Swiss pharmaceutical quality control labs. South Korean LED foundries feed near-infrared excitation sources into Chinese assembly operations.
United States
Integrated health systems in Texas and California mandate uniform intraoperative imaging protocols across cardiovascular and oncologic service lines. FDA 510(k) clearance pathways for Class II fluorescence-guided surgery platforms compress regulatory timelines for manufacturers targeting hospital procurement departments. The Greater Boston cluster concentrates academic medical center demand for quantitative lifetime imaging systems.
Germany
Baden-Württemberg hosts precision optics manufacturers supplying miniaturized detection modules for portable scanner integration. EU Medical Device Regulation post-market surveillance requirements extend certification timelines for European market entry. The Munich-Stuttgart corridor anchors pharmaceutical quality control adoption for biologics manufacturing applications.
Japan
PMDA fluorescence dye labeling requirements shape device-software combination approval strategies for multi-regional commercialization. METI industrial technology programs fund picosecond-resolution sensor development for time-resolved fluorescence platforms. The Hamamatsu region concentrates photomultiplier tube miniaturization expertise for battery-powered optical systems.
Switzerland
Swissmedic device regulations align with EU MDR standards while maintaining distinct quality management certification requirements. Basel-area biologics manufacturers deploy handheld fluorescence for real-time protein aggregation monitoring during fill-finish operations. The Zurich-Geneva corridor concentrates pharmaceutical quality control equipment procurement outside clinical reimbursement frameworks.
Singapore
Health Sciences Authority medical device registration pathways attract manufacturers seeking Asia-Pacific commercialization hubs. Biologics manufacturing investments from global pharmaceutical companies generate concentrated demand for portable quality control imaging. The Tuas biomedical manufacturing cluster standardizes handheld fluorescence protocols for fill-finish operation monitoring.
Handheld Fluorescence Imaging Devices Market Competitive Landscape
Player mix skews toward diversified surgical technology conglomerates with integrated platform portfolios. Market structure concentrates around three to five dominant vendors controlling hospital system contracting relationships across North American metropolitan markets. Two strategic archetypes prevail: optical component specialists with deep photonics manufacturing heritage, and diversified medtech conglomerates leveraging surgical workflow integration. Competitive moves center on unbundling capital equipment from disposable supply contracts, and backward integration into proprietary fluorescence dye compatibility ecosystems.
Among diversified surgical technology conglomerates, Stryker and Olympus Corporation occupy positions anchoring integrated health system contracts through established endoscopy sales infrastructure. Hamamatsu Photonics K.K. exemplifies the optical component specialist archetype, representing deep manufacturing heritage in photomultiplier tube miniaturization for portable detection modules. These three entities collectively illustrate the competitive tension between workflow-integrated platform vendors and component-level technology suppliers.
| Leading Market Players |
|---|
| Stryker |
| Olympus Corporation |
| KARL STORZ SE & Co. KG |
| Hamamatsu Photonics K.K. |
| Fluoptics |
| Smith & Nephew |
| Kent Imaging |
| Shimadzu Corporation |
| Leica Microsystems |
| Others |
Value Network & Pricing Analysis
Photomultiplier tube miniaturization scale economies in Hamamatsu and Baden-Württemberg concentrate supply-side leverage among Japanese and German component specialists, compressing price floors for portable fluorescence detection modules while elevating margin capture for integrated device manufacturers with captive optical sourcing.
Pricing Analysis
Next-generation time-resolved fluorescence platforms command 40-60% premiums over near-infrared intensity-mapping systems due to picosecond-resolution CMOS sensor costs and algorithm validation burdens. Three-tier pricing structure across premium, standard, and economy levels separates AI-embedded imaging systems from handheld cameras and smartphone-attachable scanners. Cost compression in the standard tier is intensifying because South Korean LED foundries are expanding near-infrared diode capacity. Pharmaceutical quality control buyers exhibit lowest price sensitivity due to biologics manufacturing margin structures, while outpatient surgical centers in Texas and California negotiate aggressively on capital equipment.
Supply Chain Analysis
Rare earth element processing for near-infrared LED substrates creates single-source vulnerability concentrated in Chinese separation facilities and Malaysian downstream operations. Device assembly draws from Japanese CMOS time-gating circuits, German precision optics, and South Korean excitation sources. Distribution runs through group purchasing organizations for US hospital systems and direct manufacturer relationships for Swiss and Singapore pharmaceutical labs. Tariff exposure on Chinese optical substrates threatens margin stability for battery-powered handheld configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
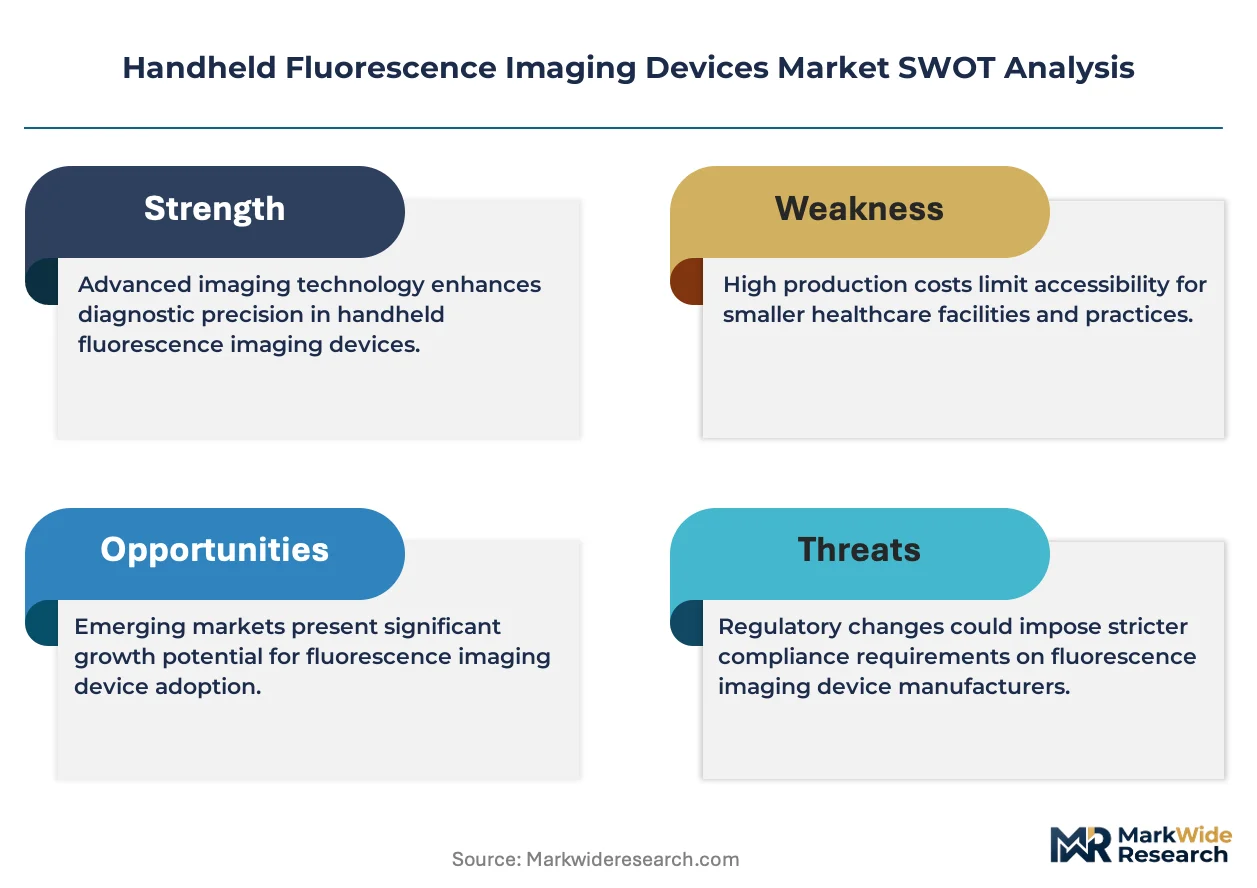
Regulatory entrenchment through FDA 510(k) clearance pathways and EU MDR software-as-medical-device classification creates formidable defensive moats for established fluorescence-guided surgery platform vendors.
For Market Incumbents: Secure hospital system contracting relationships through integrated surgical workflow platforms before portable scanner miniaturization collapses the addressable market for cart-based systems. Backward integration into proprietary fluorescence dye compatibility ecosystems locks in disposable supply revenue streams against unbundling pressure from Texas and California value analysis committees. Prioritize ISO 13485 supplier qualification programs to compress optical component audit cycles. For New Entrants and Emerging Players: FDA 510(k) streamlined review for Class II fluorescence-guided surgery devices offers fastest regulatory on-ramp for capital-constrained entrants targeting US outpatient surgical centers. White-space concentration exists in pharmaceutical quality control applications for Singapore biologics manufacturers and Swiss fill-finish operations. Field-based military medicine protocols for combat casualty assessment represent underdeveloped demand with limited incumbent penetration. Go-to-market through direct relationships with research institutes bypasses GPO procurement consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical quality control equipment suppliers serving biologics manufacturing, where real-time protein aggregation monitoring generates consumable attachment rates exceeding clinical reimbursement frameworks. Long-term viability favors optical component specialists with photomultiplier tube miniaturization heritage and diversified medtech conglomerates with endoscopy sales infrastructure extension. Signal to watch: EU MDR software-as-medical-device classification enforcement accelerating algorithm validation cost burdens for pure-play device vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Stryker and Olympus anchor integrated health system contracts across North American metropolitan markets through established endoscopy sales infrastructure. |
| Software Companion Development | AI-assisted tumor margin detection algorithms face EU MDR software-as-medical-device classification requiring clinical evidence submission. |
| FDA Submission | Accelerated 510(k) clearance pathways for Class II fluorescence-guided surgery platforms compress time-to-market for manufacturers. |
| CE Marking Pathway | European notified bodies prioritize review queues for devices with open-architecture dye compatibility, pressuring proprietary lock-in strategies. |
| Reimbursement Strategy | Indocyanine green dye's established CPT codes in outpatient surgical settings create immediate clinical utility for compatible devices. |
Research Methodology
Cross-validation between primary interviews with hospital procurement managers, biomedical engineers, and GPO contracts specialists and secondary validation through FDA 510(k) filings, EU MDR notified body databases, and hospital procurement records anchors the qualitative findings. Bottom-up demand modeling triangulates against top-down market sizing across product architecture, detection technology, clinical application, and end-user segmentation dimensions.
Sensitivity analysis on near-infrared LED cost volatility and photomultiplier tube supply concentration informs scenario-weighted outputs across the projection horizon. The analytical framework models handheld cameras, portable scanners, imaging systems, and detection modules by near-infrared fluorescence and time-resolved fluorescence technologies, with healthcare providers, pharmaceutical companies, research institutes, and educational institutions as end-user archetypes. CAGRs derive from installed base penetration curves and replacement cycle assumptions calibrated to regulatory approval timelines.
Decision-makers should treat outputs as directional under stable FDA 510(k) throughput and EU MDR notified body capacity assumptions; material deviation in regulatory review timelines or fluorescence dye labeling harmonization would warrant model refresh. Practitioners should keep alternative scenarios live as photomultiplier tube supply diversification and CMOS time-gating circuit second-sourcing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Panoramic Camera Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Photography Equipment Market
Imaging
Live Cell Imaging Market
Imaging
North America IP Camera Market
Imaging
Handheld Imaging Devices Market
Imaging
Pico Projector Market
Imaging
Digital Camera Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Hyperspectral Cameras Market
Imaging
Handheld Imaging Systems Market
Imaging
360-Degree Camera Market
Imaging
Holotomographic Imaging Market
Imaging
Gel Imaging Documentation Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
LCD Digital Microscope Market