
 Chemical Imaging Systems Market | 2026-2036
Chemical Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Imaging Systems Market Analysis
Market Context
Pharmaceutical research is broadening its share of chemical imaging procurement as quality control and material analysis deepen in drug development pipelines. Thermo Fisher Scientific leverages its analytical instrument portfolio to anchor North American laboratory demand. Merck KGaA sustains European market presence through specialized optical coherence systems for pharmaceutical applications. Fujifilm Holdings Corporation competes across Asian healthcare and academia channels with electron microscopy platforms.
Technical Definition and Segment Structure
Chemical imaging systems integrate spectroscopic and microscopic modalities to map spatial distribution of molecular composition, typically operating across wavelength ranges from ultraviolet through thermal infrared with spatial resolution down to sub-micron scales. These platforms serve industrial laboratories by enabling non-destructive identification of contaminants, polymorphs, and chemical gradients in solid and liquid samples. Hyperspectral systems occupy the premium tier where pharmaceutical research demands full-wavelength data cubes for formulation validation. Raman platforms lead quality control deployment due to minimal sample preparation requirements and water-insensitivity. Near-infrared technology dominates food and beverage end users where inline monitoring of moisture and fat content commands scale.
Regulatory Environment
FDA process analytical technology guidance and EMA quality by design frameworks mandate validated chemical imaging for real-time release testing in pharmaceutical manufacturing. EPA environmental monitoring protocols and ISO 17025 laboratory accreditation standards shape instrument calibration requirements and service revenue models. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled spectral interpretation and its implications for software-as-a-service imaging platforms.
Market Dynamics
FDA process analytical technology mandates are compressing validation timelines for pharmaceutical imaging platforms, forcing instrument vendors to embed compliance architectures directly into hardware-software stacks rather than treating certification as a post-sale overlay.
Growth Catalysts
- Hyperspectral adoption:Pharmaceutical research laboratories in Germany and the United States are expanding procurement of full-wavelength data cube systems for polymorph identification and formulation validation.
- EMA quality-by-design frameworks:These regulatory structures mandate validated chemical imaging for real-time release testing, creating instrument replacement cycles across European manufacturing facilities.
- Food safety inspection:Near-infrared platforms are penetrating quality control lines in Japan and the United States for moisture and fat content monitoring without sample destruction.
Market Restraints
- Detector material cost volatility:Indium gallium arsenide and mercury cadmium telluride focal plane array prices fluctuate with semiconductor foundry capacity constraints in Taiwan and South Korea.
- Specialized service engineer scarcity:Raman and Fourier-transform infrared systems require field technicians with dual spectroscopy-electronics training, creating installation and maintenance bottlenecks in secondary markets.
- ISO 17025 accreditation timelines:Laboratory certification processes extend 12-18 months in multiple jurisdictions, delaying revenue recognition for instrument vendors and stretching customer procurement cycles.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO tightening of good manufacturing practice standards is creating first-time demand for process analytical technology-compliant imaging in Mumbai and Hyderabad production clusters.
- Artificial intelligence spectral interpretation:Machine learning algorithms for automated contaminant detection are opening software-as-a-service revenue streams alongside hardware sales.
- Battery materials analysis:Lithium-ion cathode and electrolyte manufacturers in Japan and South Korea are adopting Raman mapping for defect characterization during electrode coating processes.
Industry Challenges
- Cross-functional talent gaps:Chemical imaging system deployment requires teams combining spectroscopy physics, pharmaceutical process engineering, and data science capabilities that rarely coexist in single organizations.
- Legacy LIMS integration:Enterprise laboratory information management systems from the 2010s lack native APIs for hyperspectral data cube ingestion, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Imaging Systems Market |
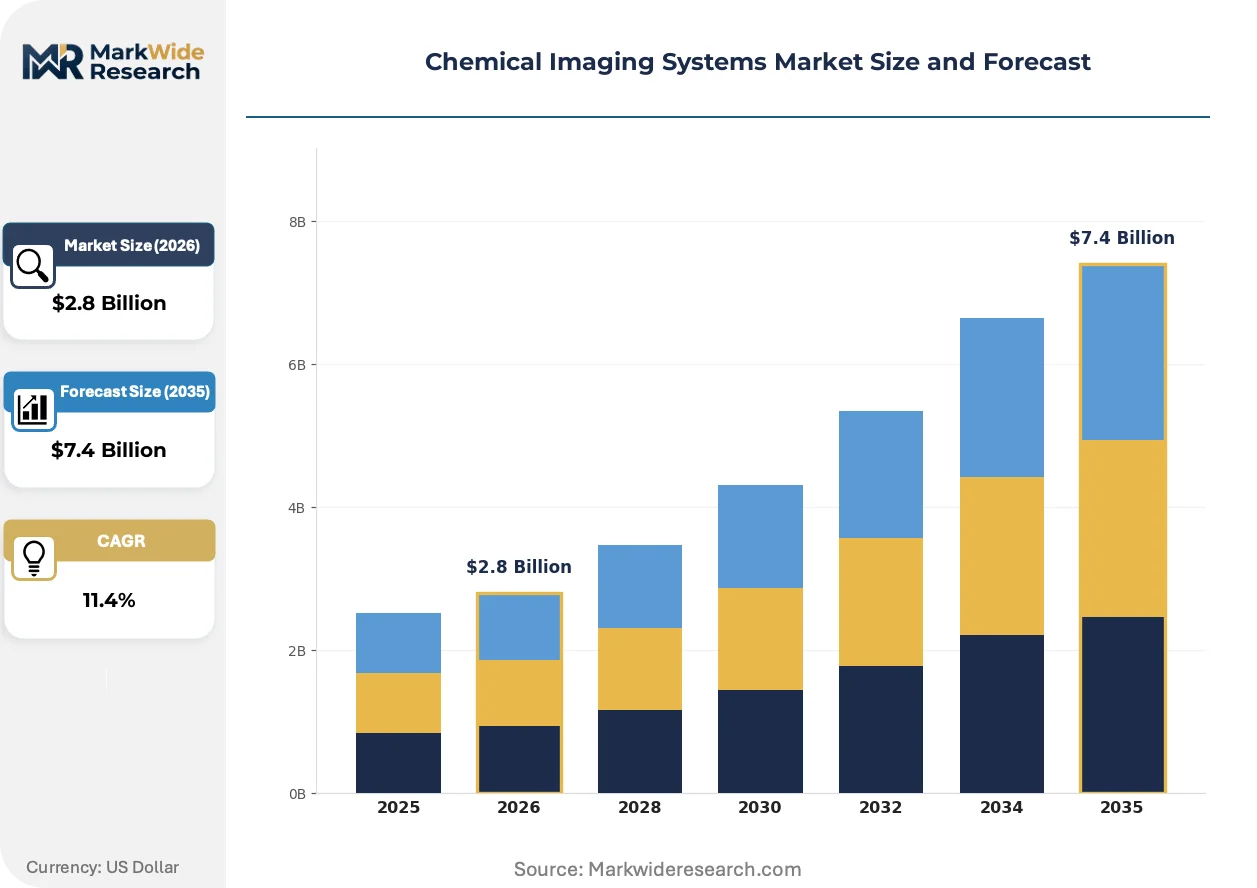
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Near-Infrared, Hyperspectral, Raman, X-Ray Application: Material Analysis, Pharmaceutical Research, Environmental Monitoring, Quality Control End User: Chemical Manufacturing, Food & Beverage, Academia, Healthcare Technology: Optical Coherence, Photon Correlation, Mass Spectrometry, Electron Microscopy |
| Companies Covered | DuPont de Nemours, Merck KGaA, Thermo Fisher Scientific, Shin-Etsu Chemical Co. Ltd., JSR Corporation, BASF SE, Fujifilm Holdings Corporation, Mitsubishi Chemical Holdings Corporation, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Imaging Systems Market Emerging Trajectories
Artificial intelligence-enabled spectral interpretation is compressing the gap between raw data acquisition and actionable quality control decisions, redefining competitive advantage around software architectures rather than optical hardware specifications alone.
Deep learning-based chemometric analysis is consolidating market power around vendors with proprietary training datasets and regulatory-validated algorithm libraries. Pharmaceutical manufacturers in Germany and the United States are adopting these platforms for real-time polymorph screening during crystallization processes. The technology is consolidating smaller regional instrument providers into partnership or acquisition targets as algorithm performance becomes the primary procurement criterion.
REACH substance identification requirements and the EU AI Act's risk classification framework are tightening documentation standards for automated spectral classification systems. Chemical imaging vendors must now maintain algorithm training provenance records and bias audit trails for European pharmaceutical customers. Mid-sized European contract manufacturers are responding by consolidating vendor relationships to reduce compliance documentation overhead.
Service contract unbundling is fragmenting traditional instrument revenue models. Academic research institutions in Japan and the United States are purchasing hardware without maintenance agreements, instead procuring on-demand calibration and repair through third-party metrology specialists. This pattern concentrates in budget-constrained public university systems where capital and operating budgets sit in separate administrative silos.
Chemical Imaging Systems Market Segmentation
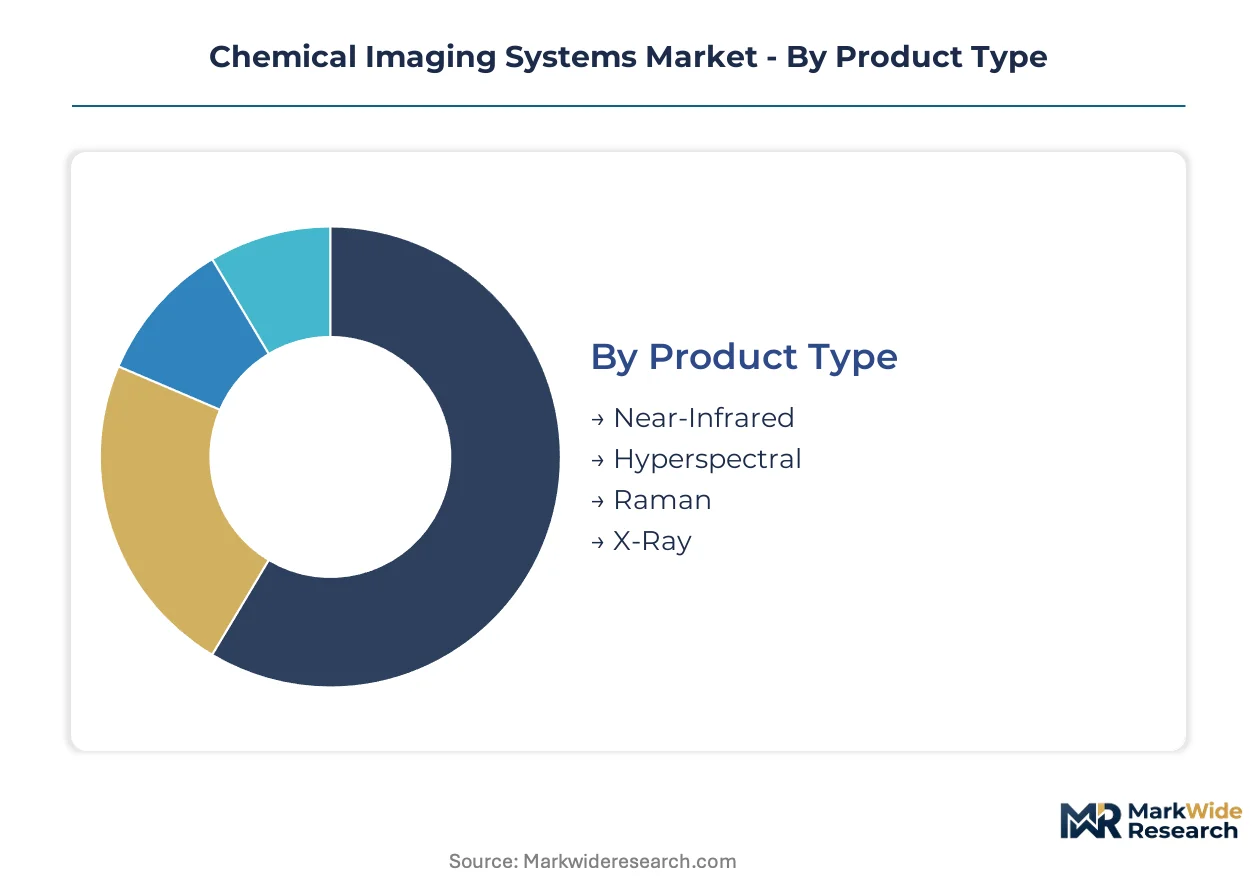
Segmentation in chemical imaging systems reveals how procurement priorities diverge across technical specifications and operational environments. Upgrade cycles and replacement timelines vary sharply between pharmaceutical quality control and academic research installations.
Product Type:
Replacement cycles accelerate where regulatory validation requirements tighten instrument specifications.
- Near-Infrared:These systems employ broadband illumination across 780-2500 nm wavelengths with array detector architectures. Food and beverage manufacturers in the United States deploy inline moisture and fat content monitoring to meet USDA process control standards. Detector material costs fluctuate with semiconductor foundry capacity.
- Hyperspectral:Full-wavelength data cube acquisition enables spatial-spectral mapping across ultraviolet through thermal infrared ranges. Pharmaceutical research laboratories in Germany expand procurement for polymorph identification during crystallization validation under EMA quality-by-design frameworks.
- Raman:Laser-excited vibrational spectroscopy requires minimal sample preparation and remains water-insensitive. Quality control lines favor these platforms for contaminant detection.
- X-Ray:High-energy penetration suits bulk material analysis and dense sample matrices. Industrial laboratories deploy for non-destructive elemental mapping.
Volume placements concentrate in Near-Infrared; the faster expansion belongs to Hyperspectral.
Application:
Cost tiers separate validated manufacturing environments from exploratory research settings.
- Material Analysis:Composition mapping and defect characterization drive demand from battery materials manufacturers. Lithium-ion cathode producers in Japan adopt Raman mapping for electrode coating quality verification.
- Pharmaceutical Research:Formulation development and polymorph screening require sub-micron spatial resolution. FDA process analytical technology mandates compress validation timelines for imaging platform procurement.
- Environmental Monitoring:EPA protocols shape instrument calibration requirements for contaminant detection in soil and water matrices.
- Quality Control:Real-time release testing demands validated spectral interpretation with documented algorithm provenance.
Procurement volumes peak in Quality Control; steepest expansion trajectory appears in Pharmaceutical Research.
End User:
Customer type determines service contract structures and software integration requirements.
- Chemical Manufacturing:Continuous process monitoring demands ruggedized platforms with automated calibration routines. CDSCO tightening of good manufacturing practice standards in India creates first-time demand for compliant imaging in Mumbai production clusters.
- Food & Beverage:Inline spectroscopic inspection replaces destructive sampling for moisture, fat, and protein quantification.
- Academia:Budget-constrained public university systems in Japan and the United States unbundle service contracts, procuring on-demand calibration through third-party metrology specialists.
- Healthcare:Clinical diagnostic applications require regulatory clearance for spectral classification algorithms.
Installed base concentrates in Chemical Manufacturing; Healthcare shows the fastest climb in new placements.
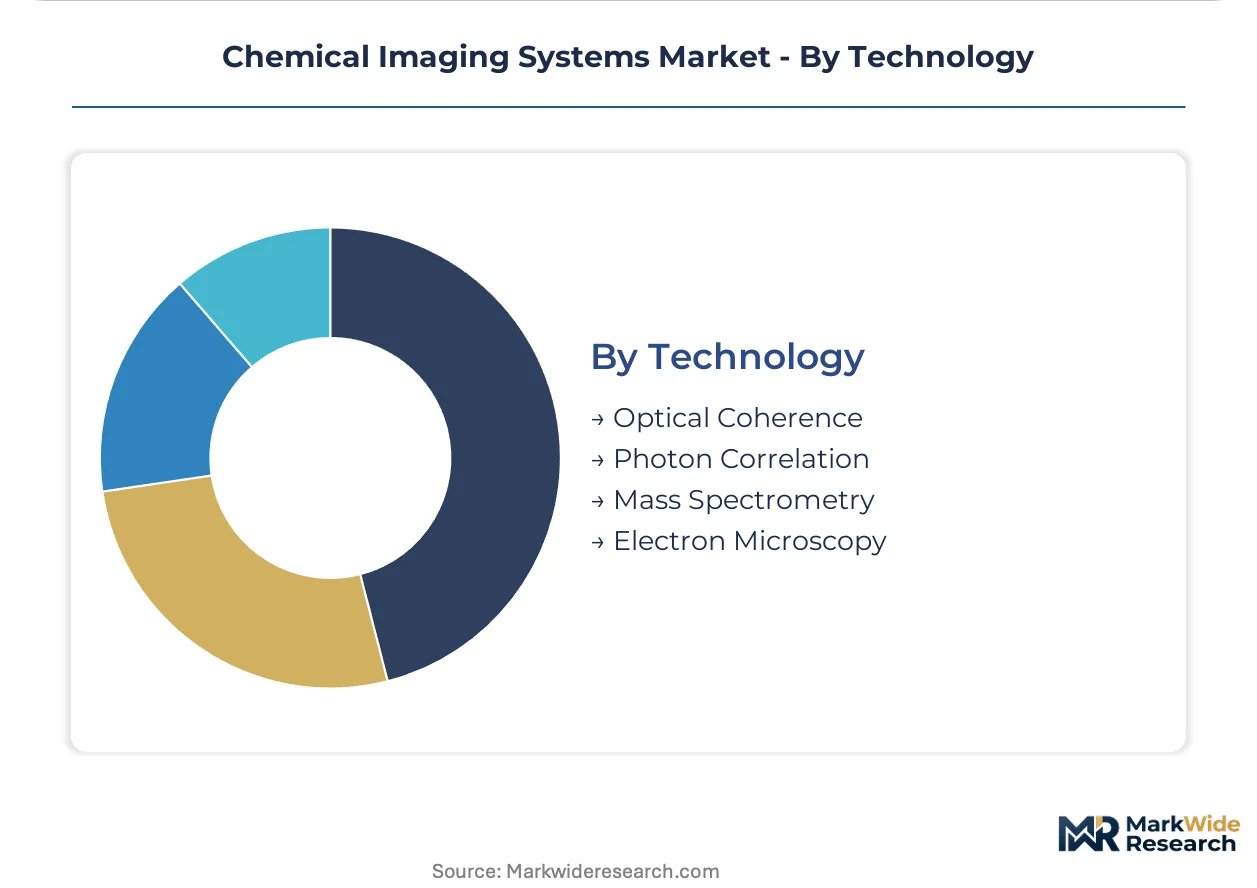
Technology:
Supply concentration in optical component foundries shapes regional availability and lead times.
- Optical Coherence:Interferometric depth-resolved imaging achieves micrometer-scale axial resolution. Merck KGaA sustains European market presence through specialized pharmaceutical application systems.
- Photon Correlation:Dynamic light scattering measures particle size distributions in colloidal suspensions.
- Mass Spectrometry:Ion detection coupled with spatial mapping enables molecular identification at picogram sensitivity.
- Electron Microscopy:Sub-nanometer resolution supports materials science and semiconductor defect analysis. Fujifilm Holdings Corporation competes across Asian academic channels with platform installations.
Revenue concentrates in Electron Microscopy; Optical Coherence gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Japan, and the United States where precision optical component foundries and pharmaceutical manufacturing clusters overlap, while consumption spreads across research laboratories and quality control facilities in multiple industrial economies.
Germany
Pharmaceutical research laboratories in Munich and Frankfurt expand hyperspectral platform procurement for polymorph identification under EMA quality-by-design frameworks. The country's chemical manufacturing base in North Rhine-Westphalia drives inline near-infrared adoption for process analytical technology compliance.
United States
FDA process analytical technology mandates compress validation timelines for imaging platforms deployed across Boston and San Diego biotech corridors. EPA environmental monitoring protocols shape instrument calibration requirements for contaminant detection in soil and water matrices.
Japan
Lithium-ion cathode manufacturers in Osaka and Nagoya adopt Raman mapping for electrode coating defect characterization. METI industrial standards guide spectral interpretation algorithm validation for battery materials analysis applications.
India
CDSCO tightening of good manufacturing practice standards creates first-time demand for compliant imaging in Mumbai and Hyderabad pharmaceutical production clusters. The country's national pharmaceutical regulator mandates validated chemical imaging for real-time release testing in expanded manufacturing facilities.
South Korea
Semiconductor foundry capacity constraints in Gyeonggi Province affect indium gallium arsenide detector availability for hyperspectral systems. Battery electrolyte producers in the Busan-Ulsan corridor deploy Raman platforms for quality verification under national industrial technology standards.
Chemical Imaging Systems Market Vendor Landscape
Top-tier vendors anchor the premium instrument segment, while mid-scale specialists and regional distributors occupy lower price tiers. The vendor base clusters around three strategic archetypes: diversified analytical conglomerates with full spectroscopy portfolios, specialized optical coherence and electron microscopy firms, and component suppliers with captive imaging system divisions. Consolidation pressures intensify as algorithm performance becomes the primary procurement criterion, forcing smaller players toward partnership structures or acquisition.
Among diversified analytical conglomerates, Thermo Fisher Scientific and Merck KGaA exemplify the integrated hardware-software-service model that pharmaceutical manufacturers favor for regulatory compliance. Fujifilm Holdings Corporation occupies a position within the specialized imaging tier, representing the Asian electronics-to-life-sciences pivot that competitors increasingly emulate. These three entities anchor competitive dynamics across their respective home markets while contesting share in third-country research laboratory procurement.
| Leading Market Players |
|---|
| DuPont de Nemours |
| Merck KGaA |
| Thermo Fisher Scientific |
| Shin-Etsu Chemical Co. Ltd. |
| JSR Corporation |
| BASF SE |
| Fujifilm Holdings Corporation |
| Mitsubishi Chemical Holdings Corporation |
| DIC Corporation |
| Others |
Supply Flow & Price Mechanics
Indium gallium arsenide focal plane array pricing volatility cascades through hyperspectral system manufacturing, compressing margins in premium-tier pharmaceutical instruments while forcing tiered pricing stratification across detector-dependent product lines.
Pricing Analysis
Margin tightening in mid-tier Raman platforms reflects semiconductor foundry capacity constraints in Taiwan and South Korea. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from laboratory-grade configurations and entry-level food inspection units. Cost-down pressure on economy-tier near-infrared systems accelerates because academic buyers unbundle service contracts and source third-party calibration. Food and beverage manufacturers exhibit highest price sensitivity due to volume procurement cycles, while pharmaceutical quality control laboratories accept premium pricing for validated algorithm libraries.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States maintain hub-and-spoke patterns for precision optical component fulfillment. Manufacturing draws from Taiwan and South Korea for indium gallium arsenide detectors, Germany for interferometer assemblies, and Japan for electron microscopy electron guns. Single-source vulnerability concentrates in mercury cadmium telluride substrate supply for thermal infrared systems. Distribution runs through authorized technical distributors with certified service engineer networks rather than commodity electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence-enabled spectral interpretation is displacing legacy chemometric software architectures, forcing vendors to restructure R&D allocation toward machine learning development and regulatory-validated algorithm training datasets.
For Market Incumbents: Anticipate algorithm performance becoming the primary procurement criterion by consolidating proprietary training datasets and embedding compliance architectures directly into hardware-software stacks. Defensive moves require acquiring specialized optical coherence firms in European pharmaceutical corridors and expanding captive production of indium gallium arsenide detector arrays to reduce Taiwan foundry dependency. Threat substitution from software-as-a-service imaging platforms demands certification investment in FDA-validated spectral interpretation libraries. For New Entrants and Emerging Players: Budget-constrained academic research institutions in Japanese and United States public university systems represent the most penetrable buyer archetype for unbundled hardware-without-service procurement models. White-space targets include on-demand calibration services for legacy installed bases and lightweight Raman platforms for battery materials analysis in South Korean electrolyte production clusters. Go-to-market execution should leverage third-party metrology specialist partnerships rather than building captive field service organizations. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale optical coherence specialists with pharmaceutical application expertise in German industrial clusters. Long-term viability centers on algorithm-provenance documentation capabilities and EU AI Act compliance infrastructure for automated spectral classification systems. Signal to watch: CDSCO enforcement timelines for good manufacturing practice standards in Indian pharmaceutical manufacturing corridors as first-time demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Library Acquisition | Consolidates training dataset ownership for FDA-validated spectral interpretation in pharmaceutical applications. |
| Backward Integration into Detector Manufacturing | Captures indium gallium arsenide supply chain control against Taiwan foundry capacity volatility. |
| Software-as-a-Service Platform Launch | Opens recurring revenue streams alongside hardware sales through cloud-based spectral interpretation. |
| Joint Venture with Battery Materials Producers | Secures Raman mapping deployment for lithium-ion cathode defect characterization in Japanese manufacturing. |
| Regulatory Certification Program Expansion | Accelerates EMA quality-by-design compliance timelines for European pharmaceutical manufacturing customers. |
Methodological Framework
Document review covered FDA guidance documents, EMA quality-by-design frameworks, EPA environmental monitoring protocols, and ISO 17025 accreditation standards, complemented by interviews with pharmaceutical quality control directors, spectroscopy R&D leads, analytical instrument procurement managers, and third-party metrology service specialists. Secondary validation drew from customs trade data, SEC instrument manufacturer filings, and national pharmaceutical regulator enforcement notices. Bottom-up segment sizing triangulated against top-down market aggregation across product type, application, and end-user dimensions.
Segment-level value outputs derived from pricing stratification analysis, replacement cycle modeling, and regulatory-driven procurement timeline compression across the projection horizon. Modeled dimensions included technology modality, validation tier, geographic regulatory cluster, and service contract structure. CAGRs were derived from instrument shipment trajectory analysis and customer budget cycle patterns. Industry-specific inputs incorporated detector material cost indices and pharmaceutical manufacturing capacity expansion announcements.
Revisions become necessary when semiconductor foundry capacity constraints intensify, regulatory guidance on artificial intelligence-enabled spectral interpretation shifts, or CDSCO enforcement timelines for Indian pharmaceutical manufacturing standards accelerate. Forecasts reflect documented assumptions regarding replacement cycle stability and algorithm validation pathway clarity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Japan Digital X-Ray Market
Imaging
Digital Movie Cameras Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Ultraviolet Transilluminator Imaging Systems Market
Imaging
Multi Camera System Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
AI Camera Market
Imaging
Mobile Camera Module Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Global Image Sensors Market
Imaging
Global Digital Photography Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
North America IP Camera Market
Imaging
Global Computed Radiography Market
Imaging
Event Camera Market