
 Asia Pacific Smartphone Camera Module Market | 2026-2036
Asia Pacific Smartphone Camera Module Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Smartphone Camera Module Market Outlook
Periscope folded-optics technology is rewriting smartphone camera module architecture by enabling 5x-10x optical zoom within sub-10mm z-height constraints. Sunny Optical Technology leverages proprietary prism-stabilization IP to anchor premium supply contracts with Chinese flagship OEMs. Samsung Electro-Mechanics dominates in-house captive demand through backward integration into Galaxy S-series camera systems. LG Innotek competes aggressively on actuator precision for periscope modules sold to Apple and domestic Korean brands.
A smartphone camera module integrates image sensor, lens assembly, voice coil motor, and flexible printed circuit into a compact electro-optical subsystem typically measuring 8x8x5mm; manufacturers bond glass-plastic hybrid lenses using active alignment to achieve sub-micron optical axis tolerances for pixel-dense sensors exceeding 48 MP. Rear triple-camera configurations now generate the dominant revenue pool as OEMs standardize ultrawide-telephoto-main arrays across mid-premium tiers. Resolution demand is migrating toward 64 MP and beyond where pixel-binning algorithms compensate for diminishing per-pixel light capture, while front-camera modules remain structurally constrained by display notch and under-panel integration limits.
China's MIIT enforces GB/T camera performance standards that mandate electromagnetic compatibility and image quality benchmarks for domestically sold modules, while South Korea's MFDS and KCC frameworks regulate near-infrared laser safety in time-of-flight depth sensors increasingly bundled with camera assemblies. India's BIS compulsory registration order for electronic components now covers camera modules, creating compliance barriers for unregistered Chinese suppliers. Stakeholders must monitor how Japan's METI export controls on fluorinated polyimide and photoresist materials reshape lens coating supply security for module makers across the region.
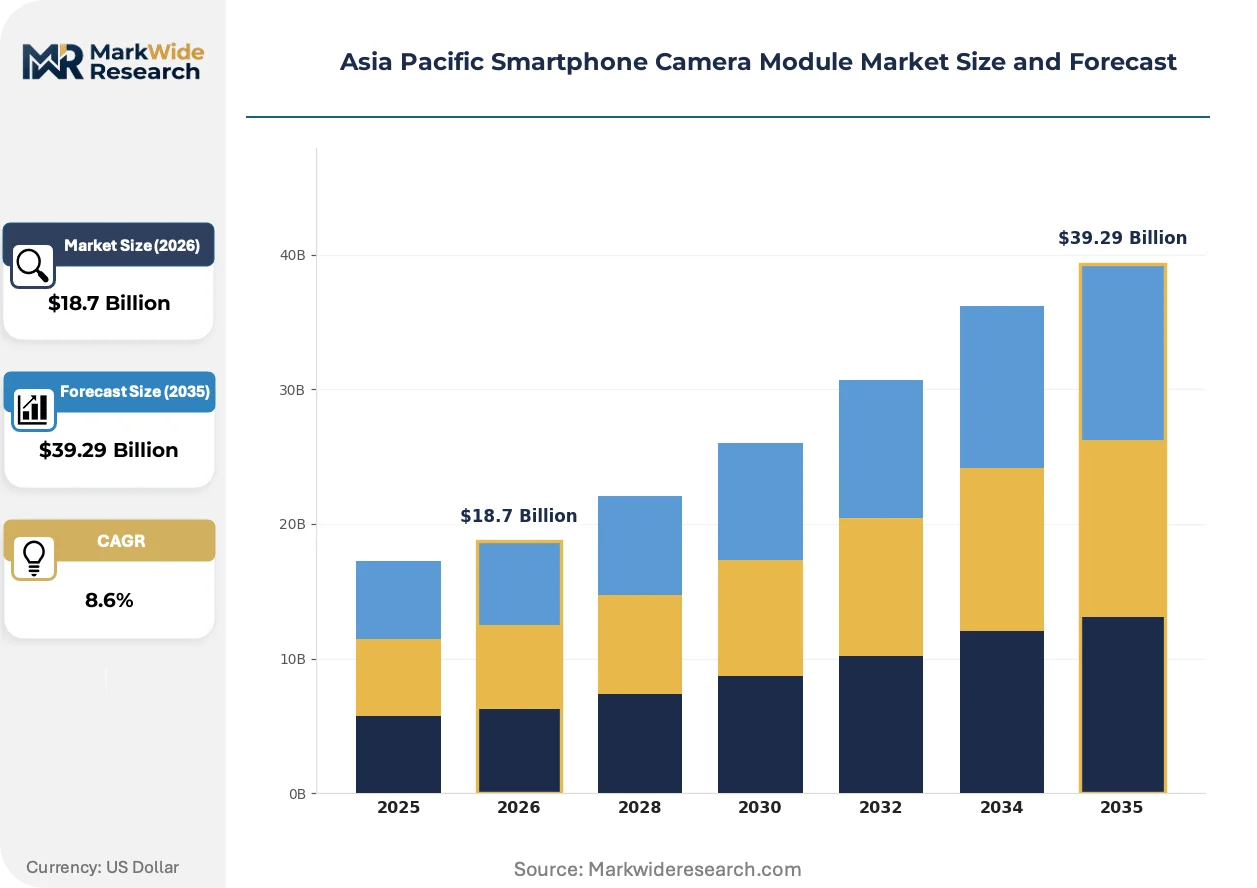
Market Dynamics
Periscope folded-optics technology is compressing module z-heights while multiplying optical zoom capabilities, forcing manufacturers to reconfigure actuator precision and prism-stabilization architectures across flagship supply chains.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for electronics manufacturing are redirecting module assembly investments toward Indian industrial corridors, diversifying regional production footprints beyond traditional coastal hubs.
- Multi-camera arrays for AR:Premium smartphone OEMs in South Korea and China are expanding rear camera counts to enable spatial computing applications, driving actuator and depth-sensor bundling demand.
- GB/T camera performance standards:China's MIIT mandates for electromagnetic compatibility and image quality are accelerating domestic module maker consolidation around certified supply bases.
Market Restraints
- Fluorinated polyimide export controls:Japan's METI restrictions on lens coating materials are creating supply security vulnerabilities for module makers dependent on Japanese chemical inputs.
- Guangdong supply concentration:Lens-to-module vertical clusters in China's southern province concentrate 60-70% of regional capacity, amplifying disruption risks from localized logistics or labor constraints.
- Front-camera form factor limits:Display notch and under-panel integration constraints cap front-module resolution advancement regardless of sensor technology gains.
Strategic Opportunities
- Vietnam module testing infrastructure:Underdeveloped optical calibration and active alignment capabilities in northern Vietnamese industrial zones present first-mover expansion potential for tier-1 suppliers.
- Time-of-flight depth sensor bundling:Near-infrared laser safety regulations under South Korea's MFDS framework are standardizing depth-sensor integration, opening actuator precision contracts for compliant module integrators.
- 64 MP pixel-binning algorithms:Computational photography software layers are enabling mid-tier OEMs to adopt high-resolution sensors without premium lens stacks, expanding addressable module volumes.
Industry Challenges
- Active alignment technician scarcity:Sub-micron optical axis tolerances for 48 MP+ sensors require specialized bonding expertise that outstrips vocational training pipeline output in Guangdong and Gyeonggi-do manufacturing clusters.
- BIS registration timelines:India's compulsory registration order for camera modules creates 4-6 month compliance windows that freeze unregistered Chinese suppliers out of tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Smartphone Camera Module Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Rear Camera, Front Camera, Dual Camera, Triple Camera Resolution: 12 MP, 20 MP, 48 MP, 64 MP Application: Photography, Video Recording, Augmented Reality, Social Media Manufacturer: Sony, Samsung, OmniVision, LG Innotek |
| Companies Covered | OFILM Group, Chicony Electronics Co., Ltd., Sunny Optical Technology, Q Technology, KYOCERA Corporation, LG Innotek, Rayprus Holding Ltd. (Foxconn), MCNEX Co., Ltd., Samsung Electro-Mechanics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Smartphone Camera Module Market Strategic Shifts
Computational photography pipelines are decoupling hardware resolution from output quality, compressing the premium module tier while expanding mid-tier sensor volumes. Three forces are restructuring competitive positioning.
Folded-optics periscope modules are virtualizing traditional telephoto lens stacks by replacing bulky refractive elements with prism-based light-path folding. Chinese flagship OEMs are standardizing 5x-10x optical zoom in sub-10mm z-height configurations. This virtualization is collapsing the historical trade-off between device thinness and zoom capability, forcing lens suppliers to develop hybrid glass-plastic stacks compatible with tight prism tolerances.
India's BIS compulsory registration order for electronic components now extends to camera modules, creating compliance barriers for unregistered Chinese suppliers. The framework mandates electromagnetic compatibility testing and safety certifications that favor established domestic assemblers with in-country testing infrastructure. Mid-tier smartphone brands sourcing from unregistered module makers are most affected, accelerating procurement audits and supplier requalification cycles.
Rear triple-camera configurations have standardized procurement around ultrawide-telephoto-main arrays, compressing module vendor margins through specification convergence. OEMs now specify actuator precision and optical axis tolerances in unified tenders rather than sourcing discrete components, favoring integrators with in-house voice coil motor and flexible printed circuit capabilities. This consolidation is most visible in China's Guangdong province, where vertical clusters dominate regional supply relationships.
Asia Pacific Smartphone Camera Module Market Segmentation
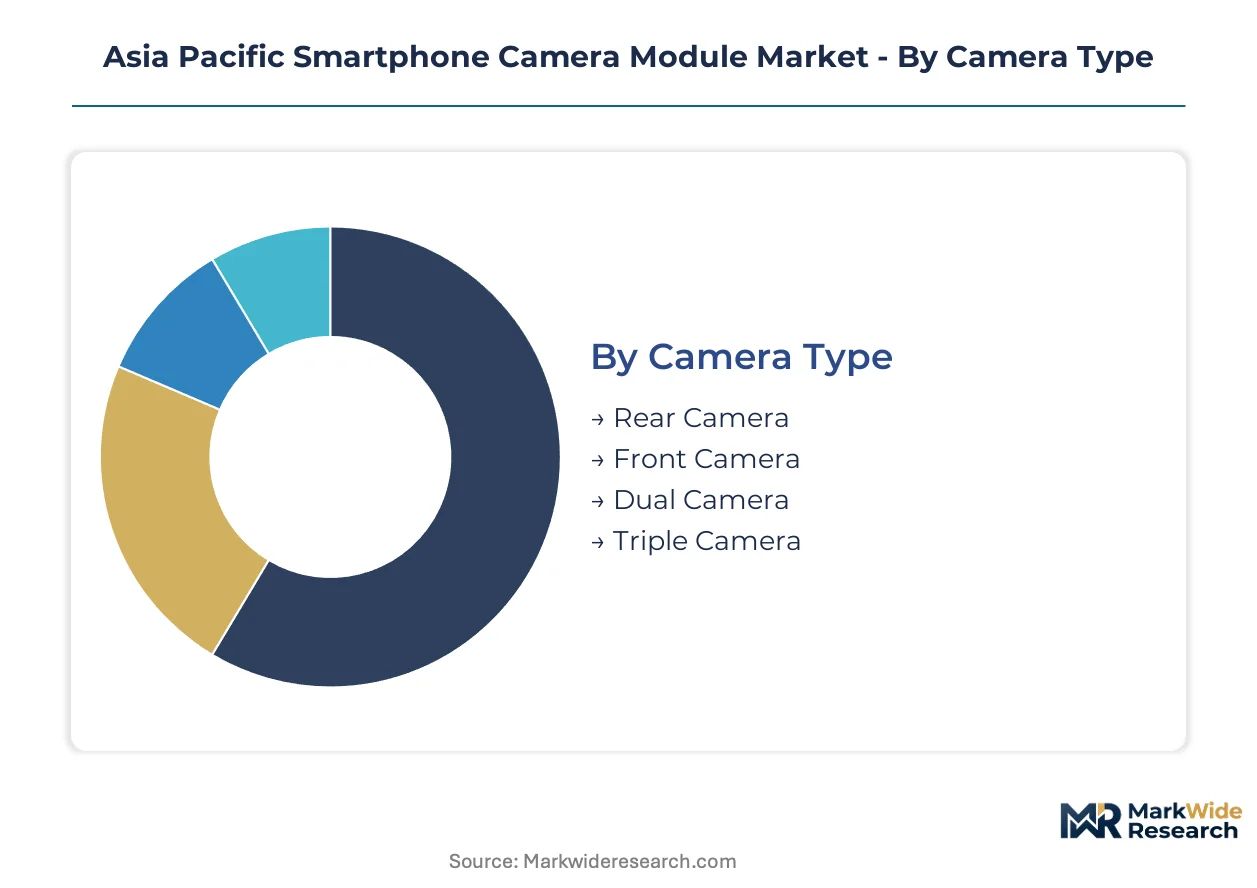
Camera module segmentation in Asia Pacific reflects divergent technical requirements across smartphone tiers. Rear-facing arrays command premium actuator precision and optical stack complexity, while front modules face tighter integration constraints against display boundaries.
Camera Type:
Application use cases split sharply between imaging fidelity demands and spatial computing requirements.
- Rear Camera:Dominant electro-optical subsystem incorporating image sensor, hybrid lens stack, voice coil motor, and flexible printed circuit in 8x8x5mm form factors. Guangdong province vertical clusters concentrate procurement for 48 MP+ configurations where active alignment achieves sub-micron tolerances.
- Triple Camera:Ultrawide-telephoto-main arrays now standard across mid-premium tiers, bundling three discrete modules with unified actuator specifications. South Korean flagship OEMs are expanding these configurations for augmented reality depth mapping.
- Front Camera:Structurally constrained by display notch and under-panel integration limits regardless of sensor gains.
- Dual Camera:Receding to entry-tier smartphones as triple arrays achieve cost parity.
Rear Camera holds installed capacity. Triple Camera is rotating up the share rankings.
Resolution:
Pixel density trajectories reflect computational photography's decoupling of hardware from output quality.
- 48 MP:Threshold where pixel-binning algorithms compensate for diminishing per-pixel light capture, enabling mid-tier OEMs to spec premium sensor footprints without matching lens stack costs. China's MIIT GB/T standards accelerate certified supply base consolidation around this tier.
- 64 MP:Computational photography pipelines compress premium module differentiation while expanding addressable volumes for algorithm-capable integrators.
- 12 MP:Front-module staple where display integration constraints override resolution competition.
- 20 MP:Transitional tier losing procurement share to binning-capable higher densities.
48 MP anchors current procurement volumes. 64 MP is climbing the fastest.
Application:
End-use functionality determines bundling requirements for depth sensors and stabilization actuators.
- Photography:Core demand driver specifying optical axis tolerances and hybrid glass-plastic lens compatibility with periscope prism architectures.
- Augmented Reality:Multi-camera arrays with time-of-flight depth sensors trigger South Korea MFDS near-infrared laser safety compliance requirements.
- Video Recording:Voice coil motor precision for optical image stabilization dominates module selection criteria.
- Social Media:Front-camera optimization for portrait segmentation algorithms.
Photography maintains design-in prevalence. Augmented Reality is gaining specification priority.
Manufacturer:
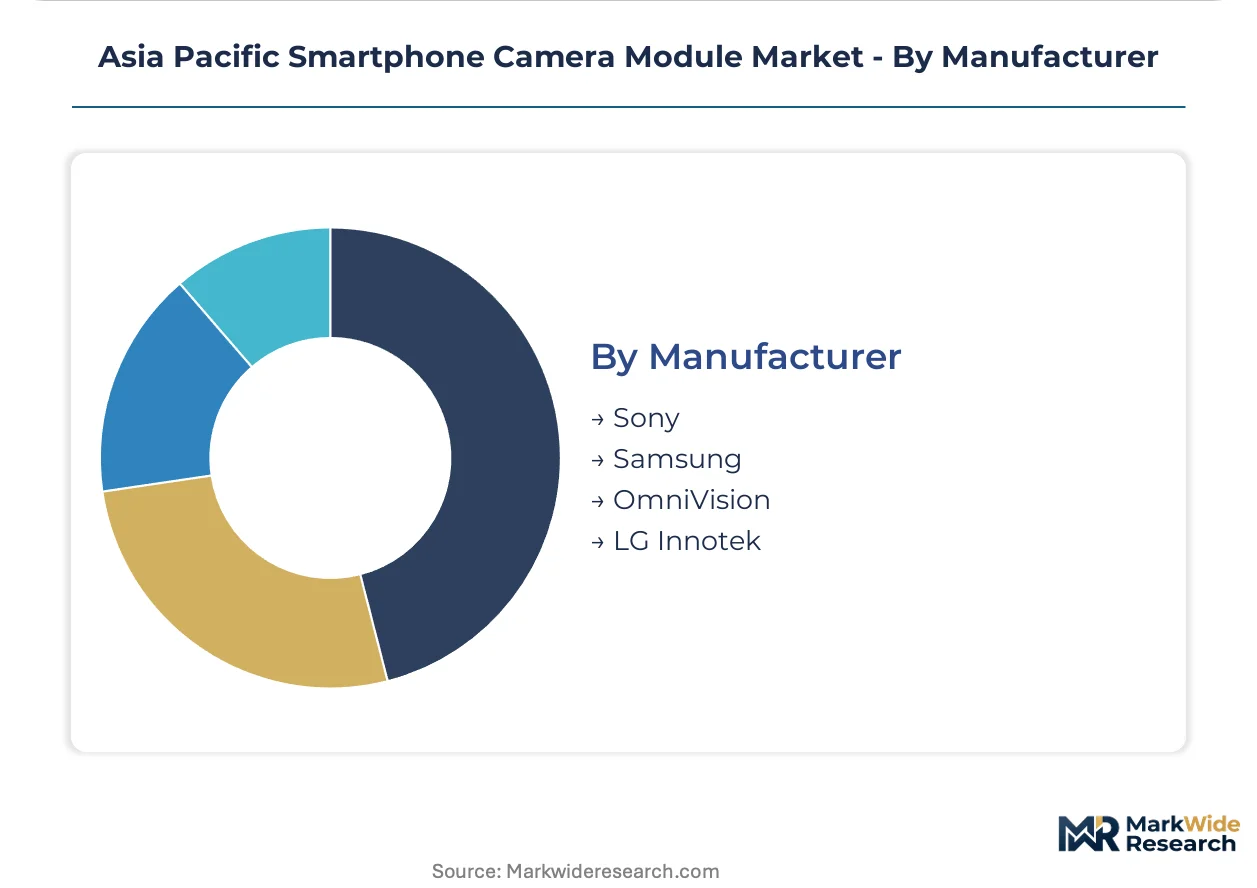
Supply concentration reflects captive integration strategies versus merchant market positioning.
- Samsung:Backward integration into Galaxy S-series camera systems dominates in-house captive demand across South Korean production.
- LG Innotek:Actuator precision specialization for periscope modules sold to Apple and domestic Korean brands.
- Sony:Image sensor leadership without module-level integration.
- OmniVision:Mid-tier sensor positioning for cost-optimized smartphone platforms.
Samsung holds captive supply scale. LG Innotek is expanding merchant market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium smartphone OEMs in South Korea and China drive periscope module procurement, while India's PLI scheme redirects assembly investments toward South Asian industrial corridors. Component buyers concentrate in vertically integrated manufacturing clusters across four national markets.
China
Guangdong province hosts lens-to-module vertical clusters that dominate regional supply capacity for 48 MP+ active alignment production. MIIT enforces GB/T camera performance standards mandating electromagnetic compatibility and image quality benchmarks for domestically sold modules. Shenzhen and Dongguan manufacturing zones concentrate 60-70% of Asia Pacific module assembly capacity.
South Korea
Seoul Capital Area anchors captive demand through Samsung Electro-Mechanics backward integration into Galaxy S-series camera systems. MFDS and KCC frameworks regulate near-infrared laser safety in time-of-flight depth sensors bundled with multi-camera arrays. Gyeonggi-do manufacturing clusters specialize in actuator precision for periscope modules supplied to Apple and domestic brands.
India
Mid-premium smartphone brands source module assemblies from requalified supplier bases following BIS compulsory registration order implementation. The PLI scheme for electronics manufacturing draws assembly investments away from traditional coastal hubs toward Indian industrial corridors. Tamil Nadu and Karnataka industrial zones attract testing infrastructure for electromagnetic compliance certification.
Japan
Fluorinated polyimide and photoresist suppliers face METI export controls that reshape lens coating supply security for module makers across Asia Pacific. Kanto region chemical manufacturers maintain critical inputs for hybrid glass-plastic lens stacks. Nagoya-area precision optics clusters supply prism-stabilization components for periscope architectures.
Vietnam
Northern Vietnamese industrial zones present first-mover expansion potential for tier-1 suppliers seeking underdeveloped optical calibration and active alignment capabilities. Bac Ninh and Hai Phong manufacturing corridors attract module testing infrastructure investments from Chinese and Korean parent companies. The region offers alternative assembly locations outside Guangdong concentration risk zones.
Asia Pacific Smartphone Camera Module Market Competitive Environment
Channel-controlling players compete with product-specialist players across three structural tiers. Samsung Electro-Mechanics dominates captive supply through in-house Galaxy S-series integration, while merchant-market specialists compete on actuator precision and prism-stabilization IP. Strategic archetypes include vertically integrated flagship OEM suppliers, independent precision-actuator specialists, and emerging India-registered assemblers. Competitive moves center on backward integration into voice coil motor production and geographic diversification toward PLI-compliant Indian manufacturing.
Within the precision-optics specialist tier, Sunny Optical Technology and LG Innotek exemplify divergent market positioning. Sunny Optical Technology occupies a position as a Chinese flagship OEM supplier leveraging proprietary prism-stabilization IP. LG Innotek anchors Korean merchant-market supply for periscope actuator precision. Among diversified electronics conglomerates, Samsung Electro-Mechanics represents captive-integration archetype control over Galaxy S-series camera systems. OFILM Group sits within the independent module assembler category serving multiple OEM platforms.
| Leading Market Players |
|---|
| OFILM Group |
| Chicony Electronics Co., Ltd. |
| Sunny Optical Technology |
| Q Technology |
| KYOCERA Corporation |
| LG Innotek |
| Rayprus Holding Ltd. (Foxconn) |
| MCNEX Co., Ltd. |
| Samsung Electro-Mechanics |
| Others |
Value Chain & Pricing Dynamics
Japan's METI export controls on fluorinated polyimide and photoresist materials compress both pricing tier spreads and supply chain configuration, forcing module makers to absorb coating cost volatility or pivot to alternative lens stack chemistries while Guangdong concentration risk amplifies downstream margin pressure.
Pricing Analysis
Cost-plus contracts with fluorinated polyimide indexation dominate procurement between Japanese chemical suppliers and Chinese module integrators. Pricing stratifies across premium periscope modules with proprietary prism-stabilization IP, standard triple-camera arrays with unified actuator specifications, and economy dual-camera configurations for entry-tier smartphones. Cost compression in mid-premium tiers intensifies as 64 MP pixel-binning algorithms enable sensor spec inflation without matching lens stack investments. Entry-tier OEMs exhibit highest price sensitivity, while South Korean flagship manufacturers prioritize actuator precision over unit cost.
Supply Chain Analysis
Tariff exposure between China and India dominates supply chain risk calculus as BIS registration timelines freeze unregistered suppliers from tender participation. Module assembly concentrates in China's Guangdong province, South Korea's Gyeonggi-do corridor, and emerging Tamil Nadu industrial zones in India. Critical inputs draw from Japanese fluorinated polyimide suppliers, Korean voice coil motor specialists, and Chinese glass-plastic hybrid lens foundries. Distribution runs through vertically integrated flagship OEM captive channels and merchant-market integrators serving mid-tier brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where India's BIS compulsory registration and China's GB/T certification standards create switching costs that lock in compliant suppliers while excluding marginal competitors.
For Market Incumbents: Build captive integration moats through backward integration into voice coil motor production and in-house active alignment capabilities that outstrip vocational training pipeline output in Guangdong. Samsung Electro-Mechanics and LG Innotek should consolidate actuator precision advantages as emerging Indian assemblers threaten merchant-market share. Priority lever: expand testing infrastructure in PLI-compliant Indian corridors before BIS registration windows close for competitors. For New Entrants and Emerging Players: Northern Vietnamese industrial zones in Bac Ninh and Hai Phong represent the most penetrable entry point for tier-1 suppliers seeking underdeveloped optical calibration capabilities outside Guangdong concentration risk. Mid-tier smartphone brands requalifying supplier bases after BIS implementation create procurement audit windows for registered assemblers with electromagnetic compliance certification. Go-to-market angle: position as India-registered alternative to frozen Chinese suppliers during 4-6 month compliance gaps. For Investors and Strategic Acquirers: India's BIS enforcement reshapes the acquisition landscape toward registered domestic assemblers with in-country testing infrastructure. Long-term viability across the projection horizon hinges on regulatory compliance depth rather than pure manufacturing scale. Acquisition target archetype: precision-actuator specialists with periscope module IP and existing BIS certification. Signal to watch: PLI scheme disbursement acceleration indicating sustained assembly investment redirection toward South Asian industrial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Voice Coil Motors | Captive actuator production locks in Samsung Electro-Mechanics' Galaxy S-series supply security against merchant-market encroachment. |
| India BIS Registration Acceleration | Early compliance certification opens tender access for module assemblers as Chinese competitors face 4-6 month exclusion windows. |
| Periscope Prism-Stabilization IP Development | Proprietary optical path folding technology anchors premium supply contracts with Chinese flagship OEMs standardizing 5x-10x zoom. |
| Vietnam Active Alignment Infrastructure Buildout | First-mover optical calibration capabilities in Bac Ninh capture module testing demand diverting from Guangdong risk zones. |
| 64 MP Pixel-Binning Algorithm Licensing | Computational photography software layers expand addressable mid-tier volumes without requiring premium lens stack investments. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with camera module procurement directors, smartphone OEM platform engineers, optical component R&D leads, and India BIS compliance officers; alongside secondary validation through MIIT GB/T certification databases, Korean MFDS laser safety filings, SEC 10-K disclosures from listed component suppliers, and customs trade records for fluorinated polyimide shipments. Bottom-up module shipment aggregation and top-down smartphone production estimates were triangulated against regional active alignment capacity data.
Forecast inputs considered camera type segmentation across rear-facing, triple-array, front-facing, and dual configurations; resolution tiers spanning 12 MP through 64 MP plus; and application demand split between photography, augmented reality, video recording, and social media optimization. CAGRs were derived from installed capacity expansion trajectories in Guangdong, Gyeonggi-do, Tamil Nadu, and emerging Vietnamese industrial zones, cross-referenced against periscope adoption curves in Chinese and South Korean flagship lineups.
Macroeconomic conditions sit as an overlay; deviation in smartphone replacement cycles, export control enforcement intensity, or PLI scheme disbursement pacing would shift the trajectory. Forecasts reflect documented assumptions on periscope z-height compression limits and pixel-binning algorithm penetration rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Gige Camera Market
Imaging
X-Ray Microscopes Market
Imaging
Global Trail Camera Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Automotive Compact Camera Module Market
Imaging
Industrial Camera Market
Imaging
Chemiluminescence Imaging Market
Imaging
Digital Image Processing Market
Imaging
Global Automotive Imaging Market
Imaging
Digital Movie Cameras Market
Imaging
360-Degree Camera Market
Imaging
India CCTV Camera Market
Imaging
Brazil Surveillance Analog Camera Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
Camera Lens Market