
 Machine Vision System and Services Market | 2026-2036
Machine Vision System and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Vision System and Services Market Foresight
China's Yangtze River Delta manufacturing belt is reconfiguring regional supply dynamics for machine vision hardware. Cognex Corporation leverages its North American R&D base to sustain technology leadership in 3D vision applications. Keyence Corporation anchors its competitive position through direct sales control across Japanese and Southeast Asian factory automation markets. Basler AG specializes in high-resolution camera systems for European semiconductor inspection, occupying a defensible niche against vertically integrated rivals.
Machine vision systems and services encompass integrated hardware-software platforms that capture, process, and analyze visual data using sensors operating at frame rates exceeding 500 fps and resolutions up to 45 megapixels, primarily enabling automated quality assurance and robotic guidance in production environments. Camera systems and AI vision represent the fastest-expanding technology pairing, with AI vision creating new margin pools through deep learning-based defect classification while camera systems face commoditization pressure in standard 2D configurations. Quality control applications retain the largest revenue share across automotive end users, though robotics applications in electronics manufacturing demonstrate the steepest growth trajectory as cobot deployments accelerate.
FDA validation requirements for medical device vision inspection and EU machinery directives enforced by national regulators shape product certification pathways, while China's GB standards for industrial automation equipment govern market access for imported systems. ISO 10218 safety standards for robotic systems indirectly mandate vision system redundancy in collaborative robot workstations. Stakeholders must monitor divergence between EU AI Act risk classifications and China's algorithmic governance rules, as these frameworks will determine which AI vision architectures achieve cross-border deployability.
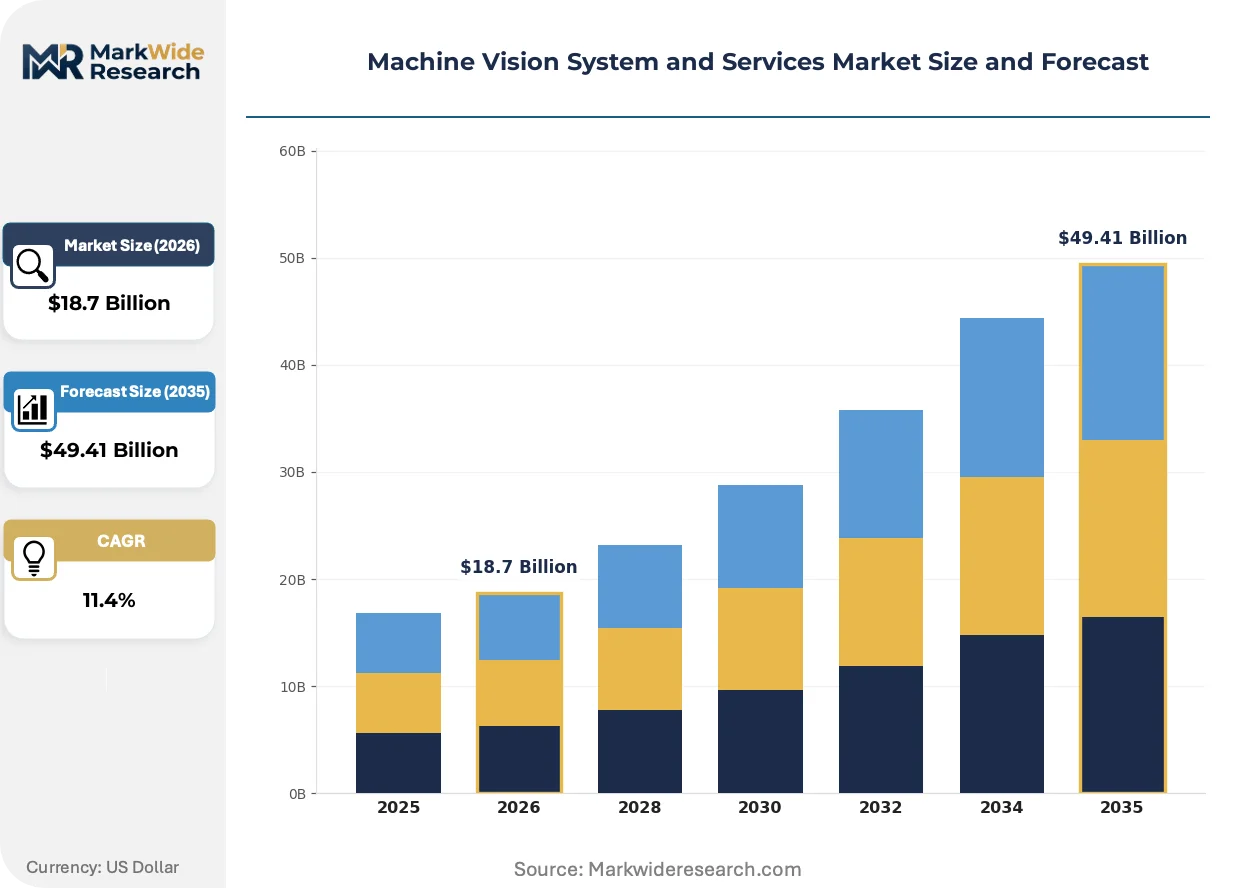
Market Dynamics
AI vision architectures are compressing traditional 2D camera margins while creating premium pricing tiers for deep learning-enabled defect classification systems in automotive and electronics manufacturing.
Growth Catalysts
- EU Machinery Safety Directives:German automotive manufacturers are expanding quality control deployments to meet stricter CE marking requirements for collaborative robot workstations.
- Embedded Vision:Electronics assembly plants in China's Yangtze River Delta are driving procurement for AI vision systems enabling real-time robotic guidance.
- METI Smart Factory Standards:Japan's factory automation sector is accelerating vision system adoption under METI-led digital transformation mandates.
Market Restraints
- Sensor Supply Concentration:High-resolution CMOS image sensor production concentrates among Korean and Japanese foundries, creating input cost volatility for camera system manufacturers.
- Technical Limitation:Deep learning vision systems require labeled training datasets that remain scarce for niche defect categories in semiconductor inspection.
- Regulatory Friction:Divergence between EU AI Act risk classifications and China's algorithmic governance rules complicates cross-border deployment of AI vision platforms.
Strategic Opportunities
- Underpenetrated Geography:India's electronics manufacturing clusters under the PLI scheme present untapped demand for quality control vision systems in mobile phone assembly.
- Technology Convergence:Integration of 3D vision with collaborative robot controllers is opening new application spaces in small-batch automotive component handling.
- Regulatory Tailwind:FDA validation requirements for medical device vision inspection are creating certified-system premium tiers in pharmaceutical packaging.
Industry Challenges
- Deep Learning Engineering Talent:Shortage of computer vision specialists capable of deploying production-grade neural networks for defect detection is constraining system integrator capacity.
- ISO 10218 Compliance Timelines:Safety certification for vision-guided collaborative robot workstations extends deployment cycles by 6-12 months.
- Legacy PLC Integration:Retrofitting AI vision systems into existing factory automation architectures requires custom protocol gateways that inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Vision System and Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Lighting Systems, Software, Processors Application: Quality Control, Automated Inspection, Robotics, Data Analysis End User: Manufacturing, Electronics, Food & Beverage, Automotive Technology: 2D Vision, 3D Vision, Embedded Vision, AI Vision |
| Companies Covered | Cognex Corporation, Keyence Corporation, Omron Corporation, Basler AG, Teledyne Technologies Inc., National Instruments Corporation, Sick AG, Allied Vision Technologies, LMI Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Vision System and Services Market Shifts & Advancements
Deep learning inference at the edge is restructuring how manufacturers deploy quality control, shifting processing from centralized servers to camera-embedded neural accelerators.
Hyperspectral imaging is collapsing the distinction between material composition analysis and surface defect detection. Automotive battery manufacturers are adopting these sensors for electrode coating inspection at line speeds exceeding 500 fps. The technology is collapsing traditional metrology into single-pass vision workflows that previously required separate laboratory analysis.
EU AI Act risk classifications are forcing AI vision vendors to document training data provenance and model performance benchmarks. High-risk applications in medical device inspection now require conformity assessments that extend certification timelines. German automotive suppliers are responding by segregating AI vision architectures into EU-deployable and non-EU variants.
Buying committees in electronics manufacturing are unbundling hardware procurement from software licensing and integration services. Tier-one contract manufacturers are negotiating direct camera supply agreements while sourcing AI vision software from specialized vendors. This pattern is most visible in China's eastern manufacturing corridor, where Foxconn and Luxshare deployment models are being emulated by mid-tier assemblers.
Machine Vision System and Services Market Segmentation
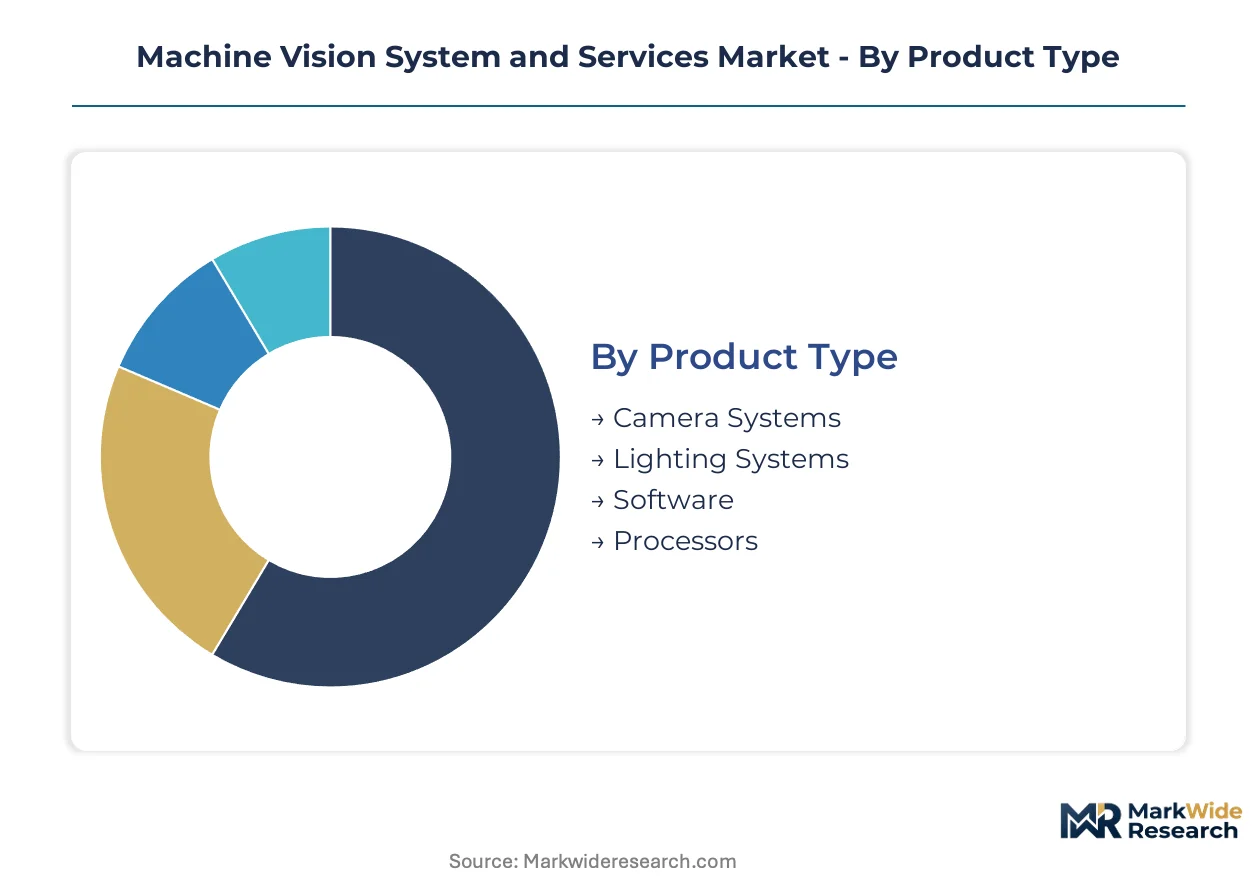
Machine vision procurement patterns diverge sharply across hardware, software, and service layers. Cycle times for camera systems compress as sensor commoditization accelerates, while AI vision software retains pricing power through specialized training requirements.
Product Type:
Camera systems turn inventory fastest at 6-9 month replacement cycles, while software licenses lock in multi-year enterprise agreements with annual maintenance renewals.
- Camera Systems:CMOS and CCD sensor assemblies delivering frame rates exceeding 500 fps at resolutions up to 45 megapixels. German automotive manufacturers drive premium demand for high-speed line scan configurations under EU machinery safety directives.
- Software:Deep learning-based defect classification platforms requiring labeled training datasets and neural network optimization. Electronics assembly plants in China's Yangtze River Delta procure these separately from hardware, unbundling traditional integrated offerings.
- Lighting Systems:Structured LED arrays and strobing illumination for consistent image capture in variable factory conditions.
- Processors:Edge-computing neural accelerators embedded directly into camera housings for real-time inference.
Camera systems anchor the volume base while software gains share at the steepest rate.
Application:
Cost tiers separate mission-critical quality control from exploratory data analysis deployments, with the former commanding 3-5x per-unit investment.
- Quality Control:Automated pass-fail determination for dimensional tolerance and surface defect detection in production environments. Automotive battery manufacturers deploy these at electrode coating lines exceeding 500 fps throughput requirements.
- Robotics:Vision-guided path planning and object manipulation for collaborative robot workstations. Japan's METI-led smart factory standards accelerate procurement for pick-and-place operations in small-batch component handling.
- Automated Inspection:In-line verification systems replacing manual sampling with 100% coverage protocols.
- Data Analysis:Post-process image archiving and trend extraction for process optimization rather than real-time intervention.
Quality control absorbs the largest capital allocation while robotics climbs the fastest.
End User:
Volume concentration tracks manufacturing automation maturity, with electronics and automotive leading capital deployment intensity per facility.
- Manufacturing:General industrial automation spanning discrete and process production environments. China's eastern manufacturing corridor dominates procurement for embedded vision in multi-product assembly lines.
- Electronics:Semiconductor wafer inspection and printed circuit board assembly verification. Foxconn and Luxshare deployment models in China's Yangtze River Delta drive unbundled hardware-software procurement patterns.
- Automotive:Powertrain component measurement and paint surface defect detection. German OEMs expand deployments under stricter CE marking requirements for collaborative workstations.
- Food & Beverage:Packaging integrity verification and foreign object detection at high-speed filling lines.
Manufacturing provides the broadest installed base while electronics expands most quickly.
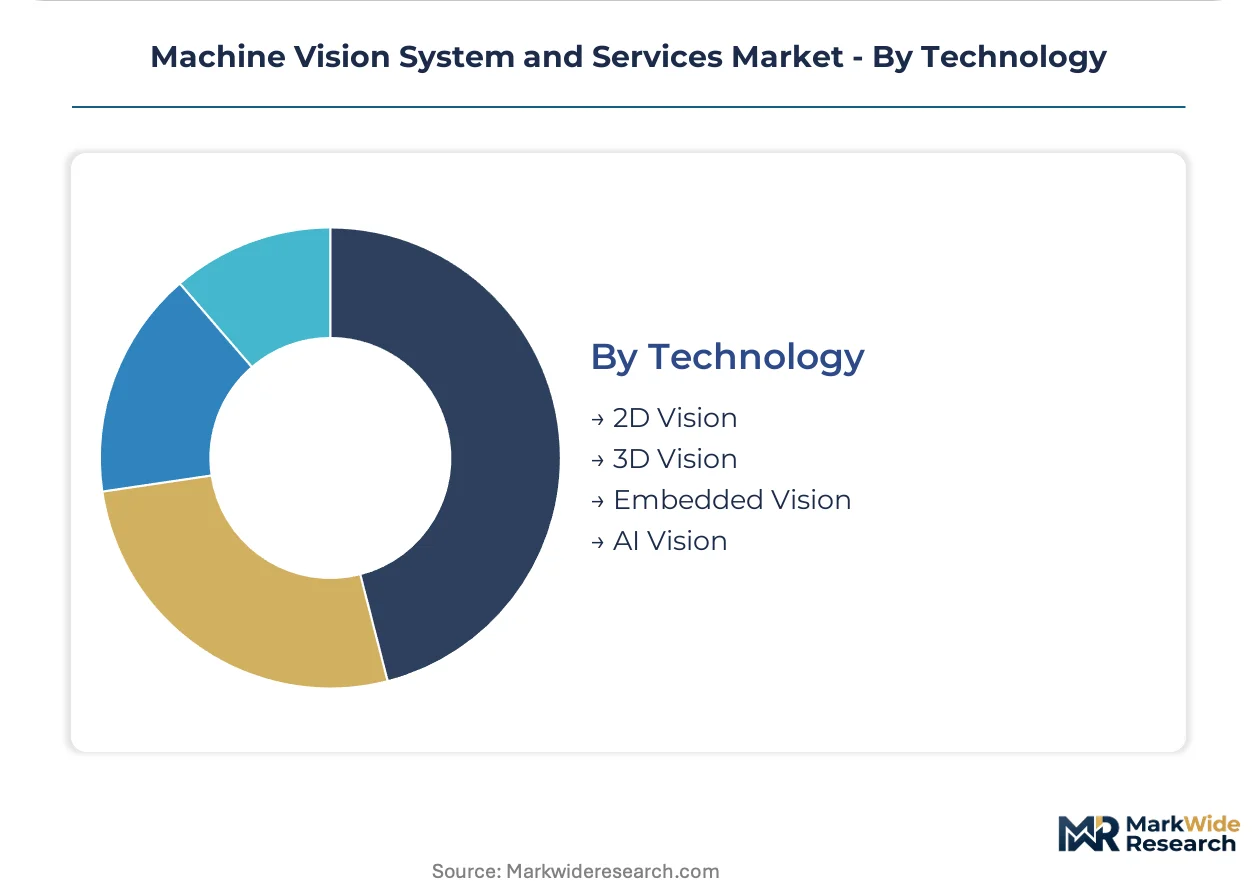
Technology:
Margin structures invert between mature 2D configurations and emerging AI architectures, with the latter capturing 40-60% gross margins versus commoditized hardware.
- AI Vision:Deep learning inference platforms for defect classification without explicit rule-based programming. FDA validation requirements for medical device inspection create certified-system premium tiers in pharmaceutical packaging.
- 3D Vision:Stereo camera and structured light systems capturing depth information for robotic guidance. Integration with collaborative robot controllers opens application spaces in small-batch automotive component handling.
- 2D Vision:Traditional area scan and line scan configurations for dimensional measurement and presence-absence detection.
- Embedded Vision:Camera-processor integration eliminating external PC dependencies for space-constrained installations.
2D vision retains the largest installed base while AI vision captures margin expansion fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CMOS image sensor fabrication concentrates in South Korean and Japanese foundries, creating supply chain leverage that shapes procurement costs for camera system manufacturers worldwide. Demand clusters concentrate in three manufacturing corridors where automotive and electronics production density drives vision system deployment intensity.
Germany
German automotive OEMs are expanding 3D vision deployments for collaborative robot workstations under stricter CE marking requirements. The EU Machinery Directive enforces functional safety documentation for vision-guided cobot installations. Stuttgart and Munich production clusters anchor procurement for high-speed line scan configurations in powertrain component inspection.
China
Electronics contract manufacturers in the Yangtze River Delta are unbundling hardware from software procurement for AI vision systems. GB standards for industrial automation equipment govern import certification for foreign vision platforms. Foxconn and Luxshare deployment models in Shenzhen and Suzhou are being replicated by mid-tier assemblers seeking defect detection capabilities.
Japan
Factory automation suppliers are accelerating embedded vision adoption under METI-led smart factory digital transformation mandates. JIS standards for robotic systems indirectly require vision redundancy in collaborative workstations. Nagoya and Osaka industrial corridors concentrate procurement for pick-and-place robotic guidance in small-batch component handling.
United States
Medical device manufacturers are procuring FDA-validated vision inspection systems for pharmaceutical packaging lines. FDA 21 CFR Part 11 compliance requirements extend certification timelines for AI vision platforms in high-risk applications. Boston and Minneapolis medical technology clusters drive demand for certified-system premium tiers in sterile packaging verification.
India
Electronics manufacturing clusters under the PLI scheme are generating new demand for quality control vision systems in mobile phone assembly. BIS certification requirements for industrial equipment create regulatory friction for imported camera systems. Tamil Nadu and Karnataka production corridors concentrate greenfield deployments for surface mount technology inspection lines.
Machine Vision System and Services Market Competitive Landscape
Technology specialists and diversified automation conglomerates split the market into distinct competitive spheres with divergent margin structures. Camera hardware vendors face commoditization pressure in standard 2D configurations while AI vision software providers capture premium pricing through specialized training requirements. Three archetypes dominate: sensor-integrated platform vendors, pure-play software specialists, and vertically integrated factory automation suppliers. Competitive moves concentrate on strategic partnerships for edge AI acceleration and geographic expansion into underpenetrated electronics manufacturing corridors.
Within the diversified automation tier, Cognex Corporation and Keyence Corporation exemplify contrasting geographic anchoring strategies. Cognex leverages its North American R&D concentration for 3D vision technology leadership. Keyence maintains direct sales control across Japanese and Southeast Asian factory automation markets. Basler AG occupies a defensible specialist position in European semiconductor inspection applications.
| Leading Market Players |
|---|
| Cognex Corporation |
| Keyence Corporation |
| Omron Corporation |
| Basler AG |
| Teledyne Technologies Inc. |
| National Instruments Corporation |
| Sick AG |
| Allied Vision Technologies |
| LMI Technologies |
| Others |
Supply & Pricing Matrix
Korean and Japanese CMOS foundry concentration feeds directly into margin distribution across camera system tiers, with sensor cost volatility compressing hardware margins while AI vision software captures value through specialized training datasets and certification premiums.
Pricing Analysis
EU AI Act risk classifications dictate the pricing tier structure across medical device and automotive inspection applications. FDA-validated systems for pharmaceutical packaging command certified-system premiums, while standard 2D configurations face commoditization. Pricing stratifies across premium certified tiers, performance-calibrated mid-market offerings, and economy sensor bundles. Cost compression in standard camera hardware intensifies because of sensor oversupply cycles, though embedded vision with neural accelerators resists erosion. Electronics contract manufacturers in China's Yangtze River Delta exhibit highest price sensitivity, unbundling hardware procurement from software licensing to arbitrage component costs.
Supply Chain Analysis
Foxconn, Luxshare, and comparable electronics contract manufacturers concentrate procurement leverage for embedded vision systems across China's eastern manufacturing corridor. CMOS image sensor fabrication draws from South Korean and Japanese foundries, while LED illumination components and neural accelerator chips source from Taiwan and mainland China facilities. Single-source vulnerability in high-resolution sensor supply creates exposure to foundry allocation decisions during capacity crunches. Distribution runs through direct sales channels for Japanese factory automation markets, regional system integrators for European automotive deployments, and unbundled hardware-software procurement for Chinese electronics assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep learning inference at the edge is disrupting traditional hardware-software bundling, with EU AI Act documentation requirements and FDA validation pathways creating defensible premium tiers for compliant architectures.
For Market Incumbents: Entrench technology leadership in 3D vision applications through R&D concentration in North American and German engineering clusters. Secure sensor supply agreements with Korean and Japanese foundries to buffer input cost volatility. Invest in EU-deployable AI vision architectures with documented training data provenance to defend against regulatory fragmentation risks from divergent algorithmic governance rules. For New Entrants and Emerging Players: Pursue white-space opportunities in India's electronics manufacturing clusters under the PLI scheme, where quality control vision systems for mobile phone assembly remain underpenetrated. Target pharmaceutical packaging applications requiring FDA-validated inspection systems, where certification barriers limit incumbent expansion. Deploy partnership-based go-to-market models with regional system integrators to circumvent direct sales infrastructure gaps. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed machine vision software specialists possessing deep learning engineering talent and vertical-specific training datasets. Long-term viability hinges on cross-border deployability of AI architectures across EU and Chinese regulatory frameworks. Monitor divergence between EU AI Act conformity assessment timelines and China's algorithmic governance implementation as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Acceleration Partnership | Camera-processor integration eliminates external PC dependencies for space-constrained robotic installations. |
| Regulatory Certification Investment | FDA validation pathways create premium tiers in pharmaceutical packaging inspection applications. |
| Geographic Expansion into India | PLI scheme electronics clusters generate greenfield demand for surface mount technology inspection. |
| Backward Integration into Sensor Supply | In-house CMOS sourcing buffers Korean and Japanese foundry allocation volatility. |
| 3D Vision Platform Integration | Stereo camera and structured light systems open small-batch automotive component handling applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with vision system integrators, plant engineers at automotive and electronics facilities, and procurement leads at contract manufacturers; and secondary validation through SEC filings of listed automation suppliers, EU machinery directive documentation, FDA 510(k) clearance databases, and Chinese GB standard certification records. Bottom-up triangulation across component shipment data and top-down reconciliation against end-user capital expenditure disclosures anchored volume estimates.
Forecast inputs span product type segmentation across camera systems, software, and processors; application segmentation across quality control, robotics, and automated inspection; and technology segmentation distinguishing AI vision, 3D vision, and embedded architectures. CAGRs were derived from regression analysis of historical procurement patterns projected against regulatory mandate implementation timelines and smart factory digital transformation spending trajectories. Model sensitivity incorporated sensor supply concentration risks and cross-border AI deployability constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed AI vision entrants or state-subsidized Chinese camera manufacturers would shift outcomes beyond modeled ranges. Quarterly review of EU AI Act conformity assessment volumes, FDA validation submission rates, and Korean foundry capacity allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Image Signal Processor Market
Imaging
PET Imaging Systems Market
Imaging
Global Optical Preclinical Imaging Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Global Waterproof Camera Market
Imaging
Computer Aided Detection Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
Global CMOS Image Sensors Market
Imaging
Digital Image Processing Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Industrial Computed Tomography Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Micro-Magnetic Resonance Imaging Market