
 Hyperspectral Imaging Market | 2026-2036
Hyperspectral Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Hyperspectral Imaging Market Intelligence
The gap between research-grade and industrial-grade hyperspectral hardware is rebalancing as volume manufacturing drives unit costs downward for line-integrated systems while laboratory instruments retain premium positioning. Specim Spectral Imaging Ltd leverages its Finnish manufacturing base to dominate airborne and ground-based platforms for environmental and defense clients. Headwall Photonics differentiates through proprietary aberration-corrected optical designs that sustain performance in harsh field conditions. Corning Incorporated anchors the supply chain with advanced optical materials and integrated sensor substrates.
Hyperspectral imaging captures contiguous narrow spectral bands across ultraviolet through shortwave infrared wavelengths, typically generating data cubes with spatial dimensions exceeding one million pixels and spectral resolution finer than ten nanometers. Camera systems command the largest installed base, though software solutions and embedded processing devices are expanding fastest as edge-computing architectures reduce downstream bandwidth burdens. Defense and agriculture represent the most mature application segments with established procurement channels, while food quality assessment offers concentrated margin pools where real-time contaminant detection commands premium pricing. Imaging sensors and hyperspectral sensors lead technology investment, with data processing algorithms representing the fastest-growing layer as manufacturers compete on classification speed and accuracy.
The European Space Agency and national defense procurement offices shape demand through satellite payload specifications and aerial reconnaissance standards, while FDA guidelines in the United States drive food safety inspection protocols that favor hyperspectral verification over destructive sampling. REACH compliance and CE marking requirements in Europe constrain material choices for optical coatings and sensor housings, filtering out suppliers lacking certified supply chains. Stakeholders must monitor how export control classifications for dual-use spectral technologies reshape competitive access to defense and geospatial intelligence markets.
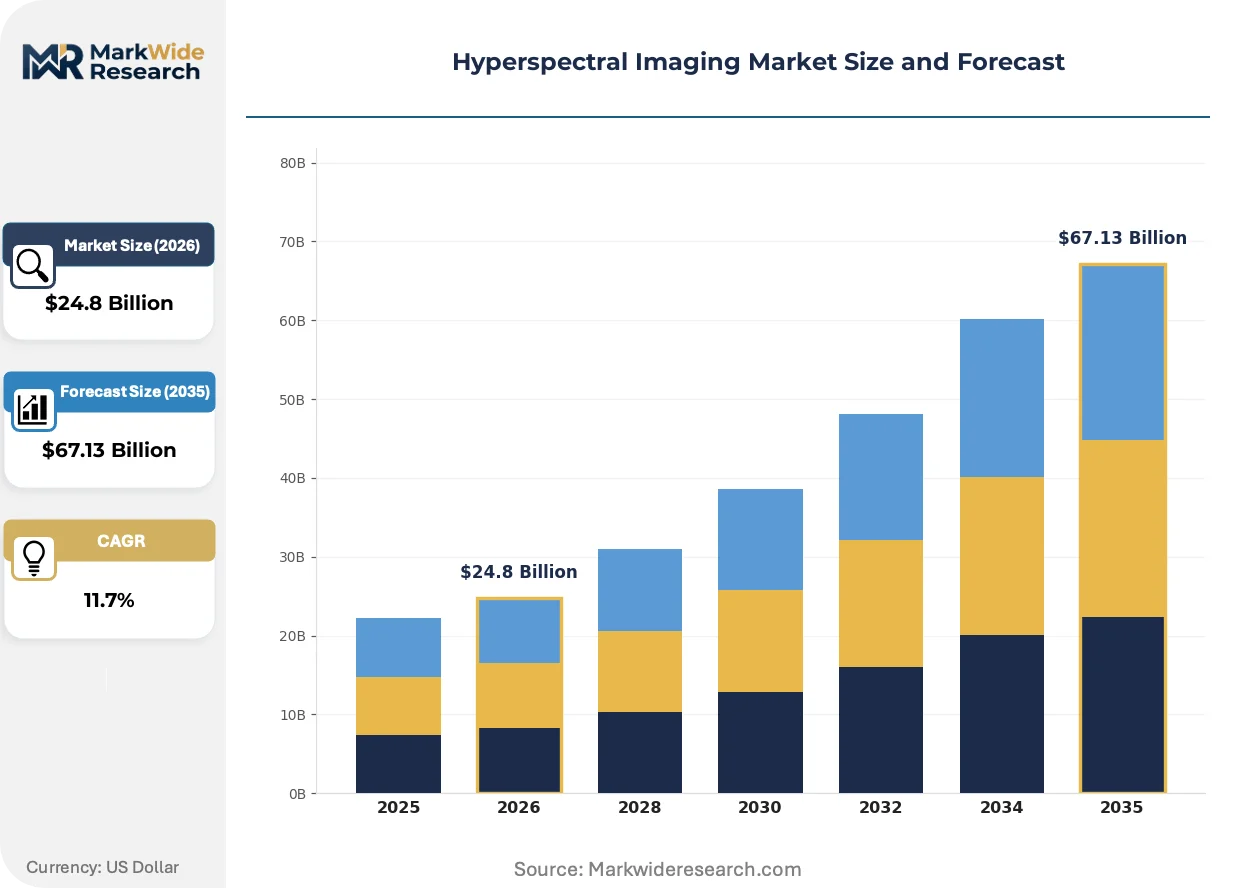
Market Dynamics
Volume manufacturing of line-integrated hyperspectral systems is compressing unit costs and eroding the traditional premium gap between research-grade and industrial-grade hardware. This cost convergence is accelerating adoption across semiconductor inspection lines and food processing facilities that previously deferred capital deployment.
Growth Catalysts
- EU Green Deal frameworks:The European Union's chemical reduction mandates are accelerating demand for non-contact optical inspection technologies that eliminate destructive sampling protocols in agricultural and environmental monitoring applications.
- Precision agriculture expansion:United States farming operations are deploying airborne hyperspectral systems for real-time crop stress detection, creating sustained procurement pull from aerial survey service providers and equipment lessors.
- Machine vision integration:Germany's industrial automation corridor is embedding hyperspectral modules directly into semiconductor and food processing production lines, normalizing inline spectral classification as a standard quality control layer.
Market Restraints
- Optical materials concentration:Advanced sensor substrates and specialized optical coatings rely on supply chains dominated by a narrow base of materials suppliers, creating vulnerability to export control disruptions.
- Data bandwidth limitations:Hyperspectral data cubes exceeding one million spatial pixels with sub-ten-nanometer spectral resolution impose transmission and storage burdens that constrain real-time edge deployment.
- REACH compliance friction:European chemical safety regulations constrain material choices for optical coatings and sensor housings, filtering out uncertified suppliers and extending qualification timelines.
Strategic Opportunities
- FDA food safety protocols:United States regulatory guidelines favor hyperspectral verification over destructive sampling in contamination detection, opening premium-priced service contracts with protein processing and produce distribution facilities.
- Edge computing convergence:Embedded processing architectures combined with hyperspectral sensors are reducing downstream bandwidth requirements, enabling deployment in bandwidth-constrained field environments and remote agricultural zones.
- Defense dual-use access:Satellite payload specifications from the European Space Agency and national defense procurement offices create certified supplier pathways that can extend into commercial geospatial intelligence markets.
Industry Challenges
- Spectral data science talent scarcity:The intersection of optical physics, machine learning classification, and domain-specific agronomy or materials science expertise remains poorly served by conventional university pipelines.
- CE marking certification timelines:European conformity assessment procedures for optical equipment and embedded software extend time-to-revenue for hardware startups and module suppliers.
- Legacy system integration complexity:Food processing and semiconductor fabrication lines operate on proprietary control architectures that resist seamless insertion of spectral inspection modules without custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hyperspectral Imaging Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $67.13 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Systems, Software Solutions, Processing Devices, Accessories Application: Agriculture, Environmental Monitoring, Food Quality Assessment, Defense End User: Research Institutions, Government Agencies, Industrial Manufacturers, Healthcare Providers Technology: Imaging Sensors, Data Processing Algorithms, Hyperspectral Sensors, Spectrometers |
| Companies Covered | Specim Spectral Imaging Ltd, Corning Incorporated, Headwall Photonics, Resonon Inc., BaySpec Inc., XIMEA GmbH, Imec, Norsk Elektro Optikk, Surface Optics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hyperspectral Imaging Market Strategic Shifts & Innovations
Computational spectral imaging and embedded neural processing are collapsing the traditional separation between data acquisition and real-time classification. These advances are compressing decision cycles from hours to milliseconds.
Snapshot mosaic sensor architectures are electrifying the competitive landscape for portable and drone-mounted hyperspectral systems. Agricultural service providers in the United States and environmental monitoring agencies are adopting these solid-state designs at accelerating pace. The technology is electrifying price-performance benchmarks across the airborne platform segment and displacing mechanical scanning mechanisms in weight-constrained deployments.
The European Union's F-Gas Regulation is tightening restrictions on fluorinated greenhouse gases used in precision optics manufacturing. This policy compression is redirecting capital toward non-contact inspection technologies that eliminate chemical etching and coating processes. Semiconductor fabrication equipment suppliers in Germany and the Netherlands are responding by qualifying hyperspectral modules for inline contamination detection that bypasses traditional wet chemistry protocols.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized food processors and specialty crop operations. Leasing arrangements bundled with algorithm updates and calibration maintenance are capturing preference from buyers seeking to avoid spectral data science staffing requirements. This shift concentrates most visibly in California's Central Valley agricultural technology cluster and the Netherlands' greenhouse automation sector.
Hyperspectral Imaging Market Segmentation
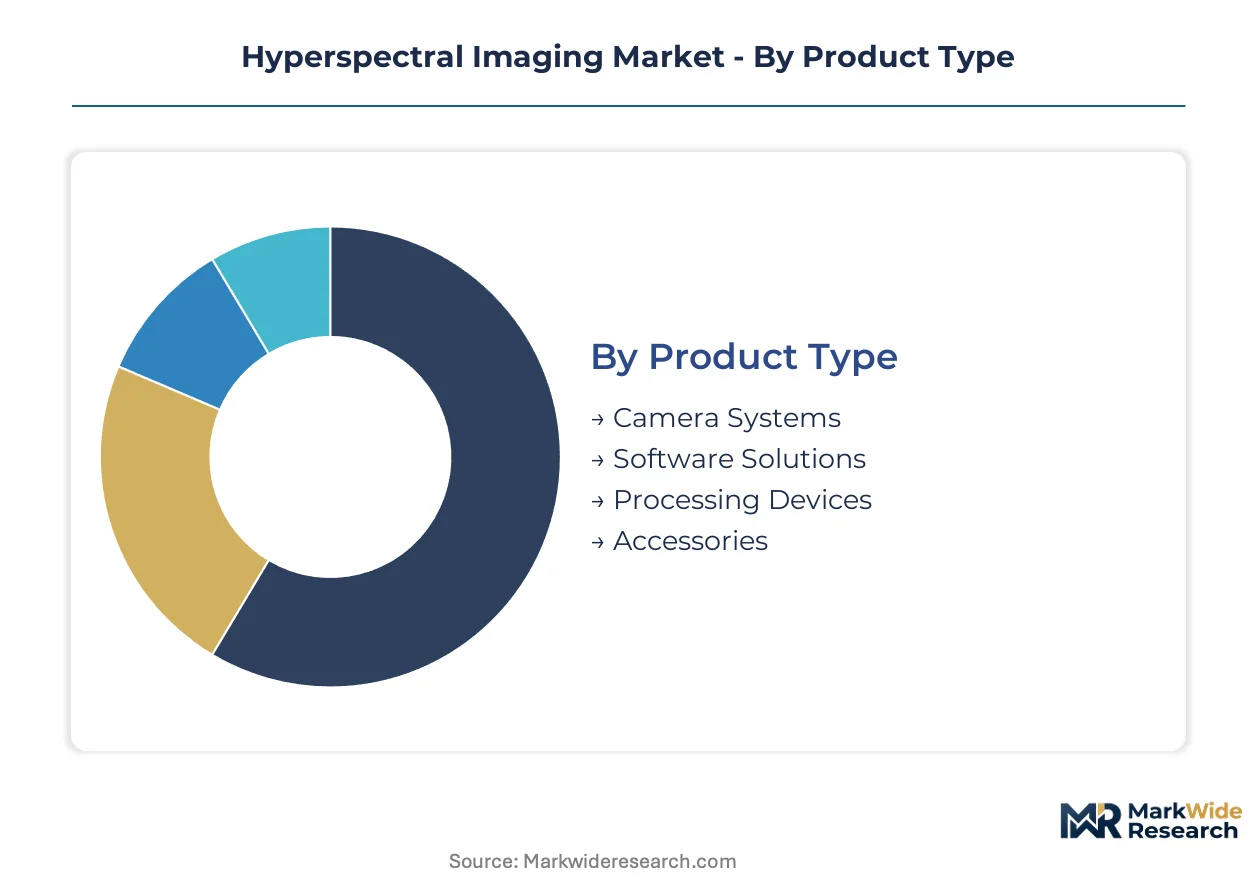
Hyperspectral imaging markets fragment across hardware, software, and service layers with divergent margin profiles and procurement cycles. Understanding segment boundaries reveals where capital concentrates versus where growth accelerates.
Product Type:
Resolution and integration depth define competitive positioning across hardware and software categories.
- Camera Systems:Pushbroom and snapshot mosaic architectures dominate airborne and industrial line-integrated deployments. Semiconductor fabrication lines in Germany and aerial survey providers across the United States sustain procurement volume for aberration-corrected optical designs.
- Software Solutions:Classification algorithms and spectral unmixing tools extract actionable intelligence from raw data cubes. Edge-computing architectures are compressing deployment timelines for agricultural stress detection and food contamination screening.
- Processing Devices:Embedded neural processors enable real-time spectral classification at the sensor node. These units reduce downstream bandwidth burdens for bandwidth-constrained field environments.
- Accessories:Calibration targets, illumination sources, and mounting hardware complete system configurations.
Camera systems lead on scale; software solutions lead on momentum.
Application:
End-use maturity varies sharply between established procurement channels and emerging verification protocols.
- Agriculture:Crop stress detection and precision input mapping drive airborne hyperspectral adoption. California's Central Valley and the Netherlands' greenhouse automation sector concentrate equipment-as-a-service contracting.
- Environmental Monitoring:Wetland assessment and pollution tracking applications deploy ground-based and satellite-mounted platforms. ESA payload specifications shape technical requirements for European deployments.
- Food Quality Assessment:Real-time contaminant detection commands premium pricing where FDA protocols favor spectral verification over destructive sampling. Protein processing facilities in the United States represent concentrated margin pools.
- Defense:Aerial reconnaissance and satellite intelligence sustain established procurement channels with dual-use technology controls.
Defense leads on scale; food quality assessment leads on momentum.
End User:
Procurement authority and technical staffing determine adoption velocity across institutional categories.
- Research Institutions:Universities and national laboratories drive specifications for research-grade instrumentation with premium positioning retained for laboratory configurations.
- Government Agencies:Defense procurement offices and environmental regulators shape demand through satellite payload specifications and aerial survey standards.
- Industrial Manufacturers:Semiconductor and food processing lines embed hyperspectral modules for inline quality control, normalizing spectral classification as standard protocol.
- Healthcare Providers:Pathology and surgical guidance applications represent emerging demand with regulatory qualification timelines.
Industrial manufacturers lead on scale; healthcare providers lead on momentum.
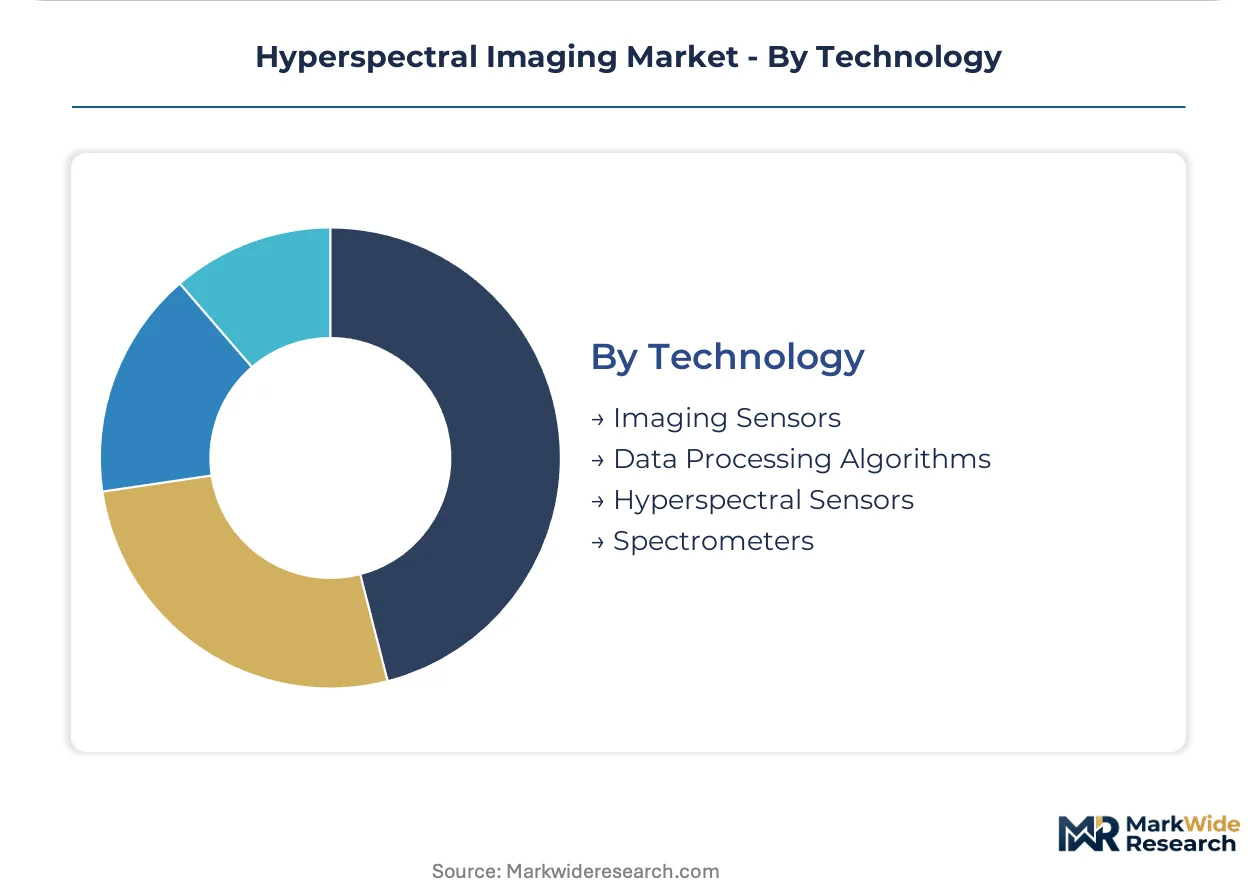
Technology:
Investment layers stack from physical sensing through computational extraction.
- Imaging Sensors:CMOS and InGaAs focal plane arrays capture contiguous narrow spectral bands with spatial dimensions exceeding one million pixels.
- Data Processing Algorithms:Machine learning classification and spectral unmixing represent the layer gaining share fastest as manufacturers compete on speed and accuracy.
- Hyperspectral Sensors:Integrated optical and detector subsystems anchor system performance with supply concentration in advanced substrate materials.
- Spectrometers:Dispersive and Fourier-transform instruments serve laboratory and portable applications with mechanical scanning mechanisms.
Imaging sensors lead on scale; data processing algorithms lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial automation corridor embeds hyperspectral modules at scale, while the United States concentrates airborne deployment for agricultural surveillance. Regulatory frameworks and procurement specifications diverge sharply across these demand centers.
United States
Precision agriculture operations deploy airborne hyperspectral systems for real-time crop stress detection across California's Central Valley. FDA food safety protocols favor spectral verification over destructive sampling in protein processing facilities. The FAA regulates commercial drone operations that carry spectral payloads for agricultural survey contracts.
Germany
Machine vision integrators embed hyperspectral modules into semiconductor and food processing production lines along the Baden-Württemberg automation corridor. The EU Green Deal and F-Gas Regulation accelerate demand for non-contact optical inspection that eliminates chemical etching protocols. Munich and Stuttgart host concentrated equipment qualification facilities serving pan-European industrial clients.
Netherlands
Greenhouse automation specialists in Westland and Aalsmeer adopt equipment-as-a-service contracting for crop monitoring systems. REACH compliance requirements constrain material choices for optical coatings and sensor housings. Wageningen University's research cluster shapes spectral algorithm specifications for European environmental monitoring agencies.
Finland
Environmental and defense clients source airborne and ground-based platforms from manufacturing bases near Helsinki. ESA satellite payload specifications influence technical requirements for spectral instrumentation. Oulu's photonics cluster supports supply chain integration for Nordic defense procurement channels.
China
Domestic semiconductor fabrication lines pilot inline hyperspectral inspection for contamination detection. MIIT standards govern machine vision integration in advanced manufacturing facilities. Shanghai and Shenzhen concentrate system integrators serving domestic food safety inspection protocols.
Hyperspectral Imaging Market Key Industry Players
Top-tier vendors anchor defense and environmental procurement channels, while mid-tier specialists occupy industrial automation niches. The vendor base stratifies across three tiers: research-grade instrument manufacturers, line-integrated module suppliers, and software-centric analytics providers. Optical design specialists and sensor substrate fabricators represent distinct strategic archetypes. Competitive moves concentrate on aberration-corrected optical IP licensing and embedded neural processing partnerships.
Among Nordic spectral imaging specialists, Specim Spectral Imaging Ltd and Norsk Elektro Optikk occupy positions within the environmental and defense procurement tier. Corning Incorporated anchors supply chain concentration through advanced optical materials and integrated sensor substrates. These three exemplify the geographic clustering around Finnish and US manufacturing bases that shapes competitive access to ESA and defense certification pathways.
| Leading Market Players |
|---|
| Specim Spectral Imaging Ltd |
| Corning Incorporated |
| Headwall Photonics |
| Resonon Inc. |
| BaySpec Inc. |
| XIMEA GmbH |
| Imec |
| Norsk Elektro Optikk |
| Surface Optics Corporation |
| Others |
Cost & Logistics Intelligence
InGaAs wafer price indices cascade through hyperspectral sensor manufacturing into three-tier pricing structures across premium, standard, and economy levels. REACH compliance costs in Europe and F-Gas Regulation restrictions amplify dispersion between certified and uncertified supplier tiers.
Pricing Analysis
Capacity additions in China's semiconductor fabrication zones are reshaping price floors for CMOS and InGaAs focal plane arrays. Three-tier pricing structure across premium, standard, and economy levels separates ESA-certified defense suppliers from industrial module vendors and uncertified aftermarket entrants. Price differentiation hinges on optical aberration correction performance and CE marking certification status. Cost compression in airborne camera systems is intensifying because snapshot mosaic architectures displace mechanical scanning mechanisms. Research institutions exhibit lowest price sensitivity; mid-sized food processors show highest elasticity, favoring equipment-as-a-service contracting to avoid spectral data science staffing costs.
Supply Chain Analysis
Freight cost volatility for precision optical substrates complicates inventory positioning between Finnish manufacturing bases and German industrial automation corridors. Supply concentration centers on Finland, Germany, and the United States for aberration-corrected optical designs and integrated sensor substrates. Raw material dependencies draw from specialty glass substrates, rare-earth doped coatings, and InGaAs wafer supply. Single-source vulnerability persists for advanced optical materials dominated by Corning Incorporated's proprietary formulations. Distribution runs through machine vision integrators in Baden-Württemberg, aerial survey service providers in California's Central Valley, and defense procurement offices in Munich and Helsinki.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Germany's automation corridor labor costs and Finland's photonics cluster regulatory certification speed. The EU Green Deal chemical reduction mandates create cost differentials favoring non-contact optical inspection deployment in European facilities versus chemical-dependent alternatives elsewhere.
For Market Incumbents: Cement aberration-corrected optical IP licensing positions through exclusive partnerships with ESA satellite payload contractors. Lock in long-term supply agreements for InGaAs wafers before export control classifications tighten. Capacity expansion in Finnish manufacturing bases preserves access to Nordic defense procurement channels threatened by emerging Chinese semiconductor inspection module suppliers.
For New Entrants and Emerging Players: Mid-sized California specialty crop operations represent the most penetrable buyer archetype for equipment-as-a-service models that bundle hardware leasing with algorithm updates. Target Netherlands greenhouse automation specialists seeking REACH-compliant crop monitoring alternatives to chemical-based protocols. Pursue go-to-market angles through Wageningen University research cluster endorsements that shape European environmental agency specifications.
For Investors and Strategic Acquirers: Asymmetric upside sits with embedded neural processing module suppliers serving bandwidth-constrained agricultural field deployments. Long-term viability over the projection horizon favors acquisition targets combining spectral unmixing algorithm IP with FDA food safety inspection certifications. Watch ESA satellite payload specification releases as inflection indicators for defense procurement channel access expansion into commercial geospatial intelligence markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Aberration-Corrected Optical IP Licensing | Headwall Photonics and Specim leverage proprietary designs to sustain performance premiums in harsh field conditions. |
| Equipment-as-a-Service Contracting | California Central Valley agricultural technology clusters adopt bundled leasing to avoid spectral data science staffing. |
| Embedded Neural Processing Integration | Edge-computing architectures reduce downstream bandwidth burdens for remote agricultural zones and defense reconnaissance. |
| REACH-Compliant Supply Chain Qualification | European chemical safety regulations filter out uncertified coating suppliers and extend hardware startup time-to-revenue. |
| ESA Satellite Payload Certification | Finnish manufacturing bases near Helsinki anchor competitive access to dual-use defense and geospatial intelligence markets. |
Research Approach
Coverage spans the United States, Germany, Netherlands, Finland, and China, with primary inputs from each region's demand centers. The analysis combines structured interviews with machine vision integrators, semiconductor fabrication equipment procurement leads, aerial survey service providers, and defense procurement officers with secondary validation. Secondary sources include ESA satellite payload specifications, FDA food safety inspection protocols, EU Green Deal implementation documents, MIIT machine vision standards, and customs records for hyperspectral camera system trade flows. Bottom-up unit deployment estimates triangulate against top-down market value reconstructions.
Rate-of-change decomposition separates volume effects from price-mix shifts across the projection horizon. The analytical framework models segmentation dimensions spanning camera system architectures, software deployment models, application maturity tiers, and regional regulatory clusters. CAGRs derive from fitted growth curves calibrated to procurement cycle data and technology substitution elasticities. Industry-specific forecast inputs include FAA drone payload regulation evolution and semiconductor fabrication line automation capex cycles.
Underlying measurement precision varies by segment; defense and agriculture applications carry tighter precision than emerging healthcare pathology deployments. Forecasts reflect documented assumptions about ESA procurement continuity, REACH compliance timeline stability, and export control classification trajectories for dual-use spectral technologies. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Phosphor Screen Scanner Market
Imaging
Global Panoramic Camera Market
Imaging
X-Ray Systems Market
Imaging
APAC Image Sensors Market
Imaging
Camera with Flip Screen Market
Imaging
Photoconductor Drums Market
Imaging
Japan Digital X-Ray Market
Imaging
Low-Light Imaging Market
Imaging
Machine Vision System and Services Market
Imaging
Europe Industrial Computed Tomography Market
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
IP Camera Market
Imaging
Frame Grabber Market
Imaging
Latin America IP Camera Market
Imaging
Photo Kiosk Market
Imaging
High-Power Objective Lens Market