
 Biophotonics Market | 2026-2036
Biophotonics Market Size, Share, and Industry Trends Forecast 2026-2036
Biophotonics Market Intelligence
Platform licensing revenue is reshaping competitive economics in biophotonics as instrument makers monetize software and assay protocols beyond hardware sales. Thermo Fisher Scientific leverages its life sciences distribution network to bundle photonic detection systems with reagent workflows. Hamamatsu Photonics sustains dominance in photomultiplier tubes and avalanche photodiodes that power high-sensitivity imaging platforms. Carl Zeiss specializes in multiphoton microscopy architectures for deep-tissue neuroscience applications.
Biophotonics encompasses the generation, manipulation, and detection of light for biological and medical applications, spanning wavelengths from ultraviolet through near-infrared with typical power densities below tissue-damage thresholds for diagnostic modalities. Its primary purpose centers on non-invasive visualization, biochemical sensing, and targeted therapeutic activation within living systems. Imaging Systems command substantial installed-base value as hospitals replace legacy modalities with integrated photonic platforms combining fluorescence and optical coherence tomography. Detectors represent the fastest-expanding component category as Raman spectroscopy and multiphoton microscopy drive demand for higher quantum efficiency and faster readout speeds. Light Sources remain technically mature though supercontinuum laser adoption creates upgrade cycles in research laboratories.
FDA device classification rules and the EU MDR framework govern clinical market access for photonic diagnostic and therapeutic systems, with FDA 510(k) pathways shaping product development timelines for US commercialization. ISO 13485 quality management standards and IEC 60601 electrical safety requirements constrain supplier qualification, favoring manufacturers with established medical device regulatory infrastructure. Stakeholders must monitor reimbursement coding decisions for novel photonic procedures as these determine hospital purchasing authority and adoption velocity.
Market Dynamics
Platform licensing economics are restructuring value capture in biophotonics as hardware margins compress and recurring revenue from software modules, assay protocols, and cloud-based analytics becomes the primary profit engine. This shift favors incumbents with installed-base scale and penalizes pure-play device manufacturers lacking digital infrastructure.
Growth Catalysts
- NIH funding mechanisms:Sustained federal research allocations in the United States accelerate translation of laboratory photonic innovations into clinical prototypes. Academic medical centers channel these resources toward oncology and neuroscience applications.
- Optical coherence tomography integration:Ophthalmology departments in tertiary hospitals are replacing standalone fundus cameras with multimodal photonic platforms. This upgrade cycle expands the addressable hardware base.
- FDA 510(k) pathway efficiency:Streamlined clearance procedures for photonic diagnostic devices reduce regulatory uncertainty. Venture capital flows more predictably toward pre-commercial stage ventures as a result.
Market Restraints
- Photomultiplier tube supply concentration:Japanese and German suppliers dominate high-sensitivity detector manufacturing. Disruptions to these specialized component sources stall instrument production timelines.
- Supercontinuum laser input costs:Rare-earth-doped fiber and precision optics for broadband light sources exhibit price volatility. System integrators face margin pressure when absorbing these fluctuations.
- EU MDR technical documentation burdens:Enhanced clinical evidence requirements for photonic therapeutic devices extend time-to-certification. Smaller manufacturers lack resources to navigate expanded conformity assessment procedures.
Strategic Opportunities
- Point-of-care Raman spectroscopy:Miniaturized handheld devices for bacterial identification and tissue characterization remain underdeployed in rural and ambulatory settings. Regulatory sandbox programs in select US states could accelerate pilot deployments.
- Photonic-CRISPR convergence:Optogenetic control of gene editing workflows creates novel research tool categories. Academic spinouts are patenting light-activated guide RNA architectures.
- India PLI scheme for medical devices:Production-linked incentives for domestic manufacturing of diagnostic equipment attract contract manufacturers. Photonic module assembly is migrating to specialized economic zones near Bengaluru and Hyderabad.
Industry Challenges
- Computational biophotonics talent scarcity:The intersection of optical physics, machine learning, and clinical validation requires hybrid skill sets. Universities produce insufficient graduates trained in inverse problem solving for image reconstruction.
- Legacy PACS integration complexity:Hospital IT departments resist photonic imaging platforms that lack seamless connectivity to existing radiology archives. Vendors must dedicate substantial engineering resources to DICOM conformance testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biophotonics Market |
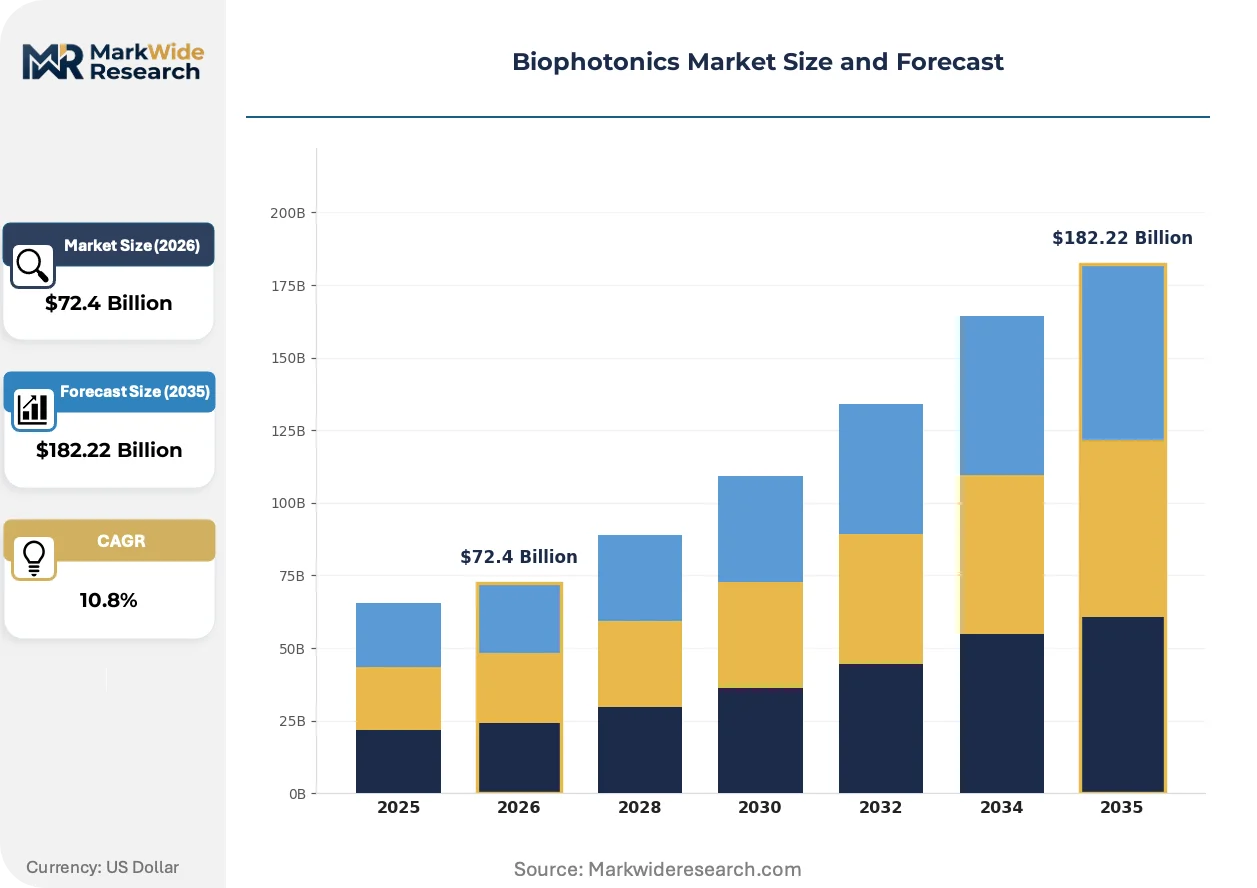
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $182.22 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Sources, Detectors, Imaging Systems, Sensors Application: Medical Imaging, Diagnostics, Therapeutics, Drug Discovery Technology: Fluorescence, Raman Spectroscopy, Optical Coherence Tomography, Multiphoton Microscopy End User: Hospitals, Research Laboratories, Pharmaceutical Companies, Academic Institutions |
| Companies Covered | Olympus Corporation, IPG Photonics, Thermo Fisher Scientific, Danaher, IDEX, Carl Zeiss, Becton Dickinson, Oxford Instruments, Hamamatsu Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biophotonics Market Strategic Shifts & Innovations
Photonic system architectures are fragmenting into modular, software-defined platforms that decouple hardware acquisition from capability upgrades. This transformation is compressing replacement cycles and expanding the competitive field beyond traditional instrument manufacturers.
Supercontinuum laser technology is migrating from research laboratory exclusivity into clinical and industrial biophotonics workflows. Dermatology clinics in Germany and the United States are adopting these broadband sources for multi-spectral tissue analysis. The technology is migrating from boutique research supply toward standardized OEM subsystems, enabling smaller device developers to field competitive products without internal laser engineering.
EU MDR recast requirements are forcing photonic device manufacturers to rebuild quality management systems around post-market surveillance and clinical follow-up. Notified body capacity constraints have created certification bottlenecks extending eighteen to thirty-six months. Class IIa and IIb photonic therapeutic systems face the steepest compliance cost escalation, with some firms withdrawing legacy products rather than absorbing documentation burdens.
Hospital procurement departments are unbundling service contracts from capital equipment purchases in photonic imaging categories. Tertiary medical centers in the United States now negotiate software maintenance, training, and uptime guarantees through separate RFP processes. This fragmentation favors vendors with transparent cost accounting and penalizes those with opaque bundled pricing structures.
Biophotonics Market Segmentation
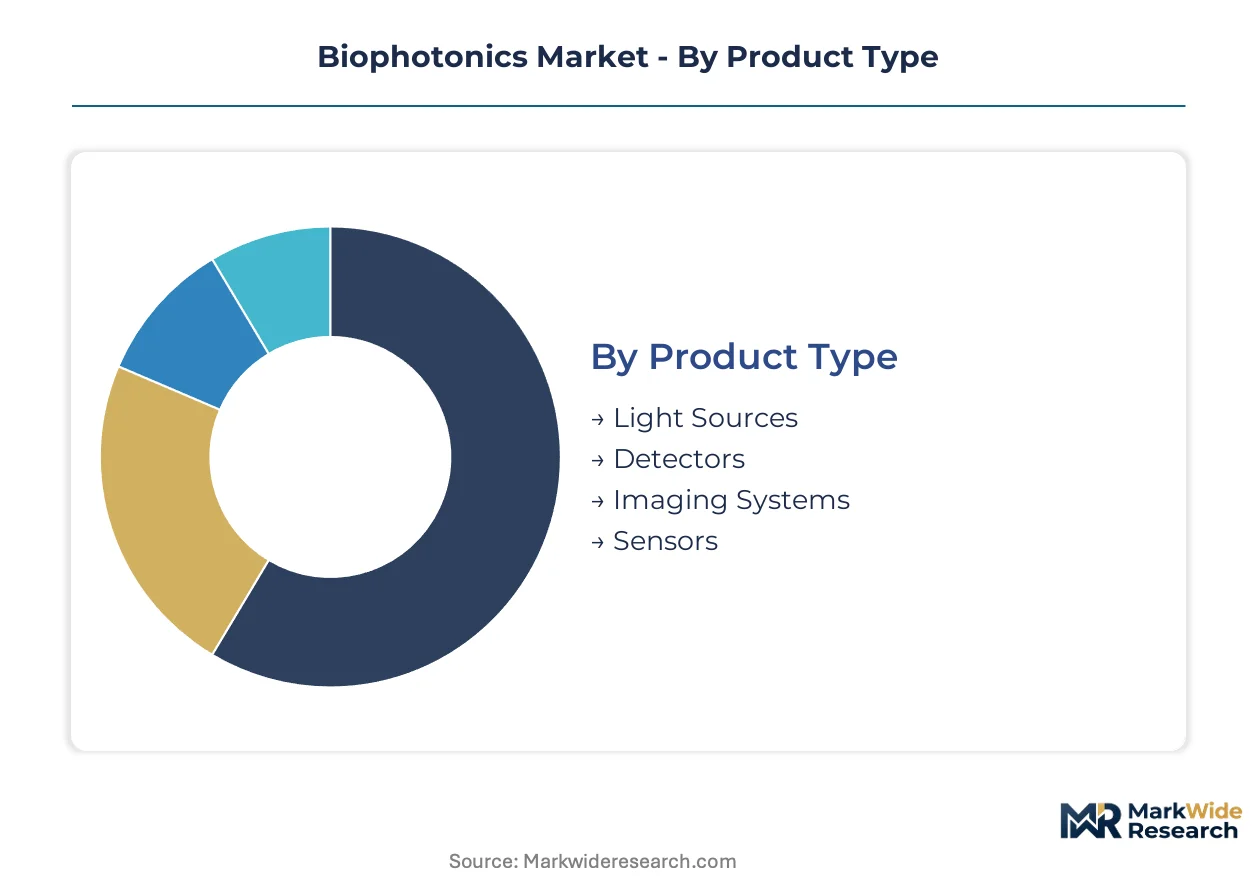
Biophotonics segmentation reveals divergent service intensity across hardware categories, with imaging platforms demanding multi-year calibration contracts while consumable-driven segments rely on recurring reagent revenue. Understanding these structural differences enables precise resource allocation across product development and commercial operations.
Product Type:
After-sales service intensity varies dramatically across hardware categories, with imaging systems requiring field engineers for optical alignment and detectors needing periodic quantum efficiency recertification.
- Light Sources:Supercontinuum lasers and solid-state emitters provide tunable illumination across ultraviolet through near-infrared wavelengths. Demand concentrates in German dermatology clinics upgrading to multi-spectral analysis platforms, driven by broadband diagnostic capabilities that reduce tissue biopsy requirements. By volume, Imaging Systems leads. By growth pace, Detectors is ahead.
- Detectors:Photomultiplier tubes and avalanche photodiodes convert optical signals into measurable electrical outputs with single-photon sensitivity. Academic medical centers in the United States drive procurement for multiphoton microscopy suites, constrained by concentrated Japanese and German supply chains that extend lead times during capacity constraints.
- Imaging Systems:Integrated platforms combining fluorescence, optical coherence tomography, and confocal architectures dominate hospital capital budgets.
- Sensors:Fiber-optic and planar waveguide devices enable point-of-care biochemical detection with minimal sample volumes.
Margin structures favor segments with embedded software licensing over pure hardware plays.
Application:
Customer acquisition costs diverge across clinical versus research use cases, with hospital procurement cycles extending 18-24 months versus 6-9 months for academic laboratories.
- Medical Imaging:Non-invasive visualization of tissue morphology and function using photonic contrast mechanisms. Ophthalmology departments at tertiary hospitals in the United States replace standalone fundus cameras with multimodal platforms, propelled by FDA 510(k) pathway efficiencies that compress regulatory timelines.
- Diagnostics:Biochemical sensing and pathogen identification through optical spectroscopy and interferometric methods. Rural clinics in India deploy handheld Raman devices for bacterial screening, supported by production-linked incentive schemes that reduce import dependency for photonic module assembly.
- Therapeutics:Light-activated drug delivery and photodynamic tumor ablation require precise dosimetry control systems.
- Drug Discovery:High-throughput screening platforms accelerate pharmaceutical candidate evaluation using automated optical readouts.
Therapeutics commands premium pricing but faces steepest EU MDR compliance burdens; Drug Discovery offers volume scalability with lower per-unit margins.
Technology:
Intellectual property density varies by modality, with Raman spectroscopy patent thickets constraining new entrants while open-source multiphoton architectures lower barriers.
- Fluorescence:Molecular emission imaging using exogenous dyes or genetically encoded reporters for cellular and tissue visualization. Neuroscience research laboratories in Germany adopt genetically targeted calcium indicators, constrained by computational biophotonics talent scarcity that delays custom assay development timelines.
- Raman Spectroscopy:Inelastic light scattering reveals molecular composition without exogenous labeling. Point-of-care bacterial identification in ambulatory settings drives miniaturization demand, though reimbursement coding uncertainty for novel photonic procedures limits hospital purchasing authority.
- Optical Coherence Tomography:Interferometric depth-resolved imaging achieves micrometer-scale resolution in translucent tissues.
- Multiphoton Microscopy:Nonlinear optical excitation enables deep-tissue imaging with reduced phototoxicity.
Optical Coherence Tomography holds largest installed base; Multiphoton Microscopy shows steepest expansion trajectory in neuroscience applications.
End User:
Budget authority and decision-making velocity differ markedly across institutional types, with pharmaceutical companies consolidating vendor relationships while academic institutions fragment procurement.
- Hospitals:Clinical departments with capital equipment budgets and service contract negotiation authority. Tertiary medical centers in the United States unbundle software maintenance from hardware purchases through separate RFP processes, favoring vendors with transparent cost accounting over opaque bundled pricing structures.
- Research Laboratories:Academic and government facilities with grant-funded equipment acquisition. NIH funding mechanisms accelerate translation of photonic innovations into clinical prototypes, though legacy PACS integration complexity consumes substantial vendor engineering resources for DICOM conformance testing.
- Pharmaceutical Companies:Drug developers integrating photonic platforms into high-throughput screening workflows.
- Academic Institutions:Universities with core imaging facilities serving multiple investigator groups.
Hospitals generate highest per-account revenue; Academic Institutions provide volume through shared core facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Photomultiplier tube fabrication concentrates in Japan and Germany, while supercontinuum laser assembly migrates toward Indian production-linked incentive zones. NIH funding in the United States and EU MDR compliance costs in Europe reshape regional competitive positioning.
United States
Academic medical centers in Boston and San Francisco drive multiphoton microscopy procurement for neuroscience research. FDA 510(k) pathway efficiencies compress regulatory timelines for photonic diagnostic devices. NIH funding mechanisms channel federal resources toward oncology and clinical translation at Stanford University and Massachusetts General Hospital.
Germany
Dermatology clinics in Munich and Hamburg adopt supercontinuum lasers for multi-spectral tissue analysis platforms. EU MDR technical documentation requirements extend certification timelines for Class IIb therapeutic systems. Precision optics manufacturing clusters in Jena and Oberkochen supply broadband light source components.
Japan
Hamamatsu and Hamamatsu City manufacturing bases dominate high-sensitivity photomultiplier tube production for global instrument makers. METI industrial policy supports photonics commercialization through academic-industry partnerships. Tokyo and Osaka academic laboratories drive avalanche photodiode demand for confocal microscopy suites.
India
Production-linked incentive schemes for medical devices attract contract manufacturers to Bengaluru and Hyderabad economic zones. CDSCO regulatory pathways for diagnostic equipment streamline import substitution for photonic module assembly. Rural clinics in Maharashtra deploy handheld Raman devices for point-of-care bacterial screening.
United Kingdom
Oxford and Cambridge research laboratories patent light-activated guide RNA architectures for photonic-CRISPR convergence. MHRA post-Brexit device regulations create parallel conformity assessment tracks for photonic therapeutic systems. London hospital procurement departments unbundle software maintenance contracts from capital equipment purchases.
Biophotonics Market Key Industry Players
Vertically integrated conglomerates and specialized component suppliers split the market between platform economics and discrete technology dominance. Thermo Fisher Scientific and Danaher exemplify the life sciences conglomerate archetype, bundling photonic detection with reagent workflows. Carl Zeiss and Olympus Corporation represent the precision optics specialist archetype, controlling multiphoton microscopy architectures. Competitive moves concentrate on platform licensing revenue capture and detector supply chain security.
Within the precision optics tier, Carl Zeiss and Olympus Corporation anchor German and Japanese manufacturing heritage respectively. Hamamatsu Photonics occupies a position exemplifying component supply concentration in photomultiplier tubes. Thermo Fisher Scientific represents the North American distribution-scale archetype, leveraging life sciences networks for integrated workflow sales.
| Leading Market Players |
|---|
| Olympus Corporation |
| IPG Photonics |
| Thermo Fisher Scientific |
| Danaher |
| IDEX |
| Carl Zeiss |
| Becton Dickinson |
| Oxford Instruments |
| Hamamatsu Photonics |
| Others |
Cost & Logistics Intelligence
Undercapacity in Japanese photomultiplier tube fabrication constrains detector availability while elevating pricing power for Hamamatsu and select German suppliers, compressing margins for system integrators dependent on single-source components.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing tier structure across photonic diagnostic platforms, separating premium-certified multiphoton microscopy suites from standard ophthalmology OCT systems and economy-tier point-of-care sensors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification depth and bundled software maintenance duration. Cost compression in the economy tier is intensifying because Indian contract manufacturers absorb module assembly under PLI schemes. Academic medical centers exhibit highest price sensitivity due to grant-funded procurement cycles, while pharmaceutical companies show least sensitivity given high-throughput screening volume requirements.
Supply Chain Analysis
Extended payment terms from German precision optics clusters to Japanese photomultiplier tube foundries stabilize working capital for tier-one instrument makers. Component sourcing draws from Japan, Germany, and India for detectors, broadband laser optics, and contract assembly respectively. Rare-earth-doped fiber and precision fused silica substrates constitute critical raw material dependencies. Single-source vulnerability in avalanche photodiode metallization creates exposure to Hamamatsu capacity allocation decisions. Distribution runs through life sciences conglomerate networks for bundled workflow sales and specialized photonics distributors for research laboratory procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The intersection of optical physics, machine learning, and clinical validation creates acute talent scarcity, constraining product development velocity for vendors lacking captive computational biophotonics expertise.
For Market Incumbents: Harden detector supply security through backward integration into photomultiplier tube testing and calibration capabilities, or through exclusive offtake agreements with Hamamatsu and German suppliers facing undercapacity. Fortify platform licensing revenue by unbundling software maintenance from hardware purchases to match US hospital procurement department RFP fragmentation. EU MDR recast requirements threaten legacy therapeutic system margins; prioritize ISO 13485 quality management reinvestment over price competition in Class IIb segments. For New Entrants and Emerging Players: Build out point-of-care Raman spectroscopy deployments in Indian rural clinics and US ambulatory settings where regulatory sandbox programs reduce time-to-pilot. Photonic-CRISPR convergence architectures offer white-space patenting opportunities with lower incumbent IP density than fluorescence microscopy. Pursue OEM subsystem partnerships with German dermatology clinics adopting supercontinuum lasers rather than competing directly against Carl Zeiss multiphoton platforms. For Investors and Strategic Acquirers: Capital is best deployed toward modular software-defined platform developers with installed-base scale and recurring assay protocol revenue, rather than pure-play hardware manufacturers facing margin compression. Long-term viability across the projection horizon favors vendors with digital infrastructure and transparent cost accounting for unbundled procurement. Monitor NIH funding allocation shifts toward oncology and neuroscience as inflection indicators for academic medical center capital equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Optimization | Streamlined clearance compresses regulatory timelines for photonic diagnostic ventures seeking US commercialization. |
| Platform Licensing Revenue Capture | Software and assay protocol monetization beyond hardware sales transforms profit economics for instrument makers. |
| Detector Supply Chain Security | Exclusive offtake agreements with Japanese and German suppliers mitigate photomultiplier tube concentration risk. |
| EU MDR Quality System Reinvestment | Post-market surveillance infrastructure rebuilds enable sustained market access for Class IIb therapeutic systems. |
| Point-of-Care Miniaturization | Handheld Raman device deployment in Indian rural clinics leverages PLI scheme manufacturing incentives. |
Research Approach
The analysis maps light sources, detectors, imaging systems, and sensors, each validated through biomedical engineers, hospital purchasing committees, GPO contracts managers, and academic laboratory directors. Primary interviews with these stakeholders combined trade data from customs records, SEC filings from life sciences conglomerates, NIH funding disclosure databases, and EU MDR notified body certification registers. Bottom-up instrument shipment tracking and top-down addressable market sizing were triangulated against reimbursement coding decisions and hospital capital budget surveys.
Assumptions around FDA 510(k) pathway efficiency, EU MDR notified body capacity constraints, and NIH funding continuity were held fixed across the modeling period, while supercontinuum laser cost curves and photomultiplier tube lead times were varied. Segmentation dimensions modeled include product hardware category, clinical versus research application, optical modality technology, and end-user institutional type with regional regulatory cluster overlay. CAGRs were derived from installed-base replacement cycle analysis and grant funding velocity projections, incorporating ophthalmology OCT upgrade rates and multiphoton microscopy neuroscience adoption curves as biophotonics-specific inputs.
Stress conditions across NIH appropriation volatility, EU MDR certification timeline extension, and photomultiplier tube supply disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions; macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Europe Hyperspectral Imaging Market
Imaging
SDI Camera Market
Imaging
Microwave Imaging Market
Imaging
North America Image Sensors Market
Imaging
Handheld Imaging Systems Market
Imaging
Global in Ceiling Camera Market
Imaging
Camera with Flip Screen Market
Imaging
Europe Image Sensors Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Software-Defined Camera (SDC) Market
Imaging
Computational Photography Market
Imaging
Photoacoustic Tomography Market
Imaging
Handheld Imaging Devices Market
Imaging
Digitizer Market
Imaging
Uncooled Infrared Camera Market
Imaging
Multimodal Imaging Market