
 Video Processing Solutions Market | 2026-2036
Video Processing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Video Processing Solutions Market Analytics
GDPR is hardening data residency requirements for video processing workflows that handle viewer metadata and content distribution logs across European territories. Akamai Technologies leverages its globally distributed edge network to compete on low-latency transcoding delivery. Ateme specializes in software-defined video compression, while MediaKind anchors broadcast-grade processing for satellite and terrestrial operators.
Video processing solutions encompass hardware, software, and cloud-based systems that ingest, encode, transcode, package, and deliver video content across IP networks, typically supporting H.264, HEVC, AV1, and VVC codecs at resolutions from SD through 8K. These systems serve broadcasters, streaming platforms, security operators, and enterprises requiring real-time or file-based transformation of video assets for distribution, storage, or analytics. Cloud-based deployments are capturing the fastest expansion as media companies and enterprises abandon capital-intensive on-premise infrastructure for elastic, usage-priced encoding farms. Hardware segments remain dominant in live broadcast and low-latency gaming applications where ASIC and FPGA acceleration outperforms general-purpose compute. GPU-based processing is displacing CPU-centric workflows in AI-driven content analysis and personalization pipelines.
FCC regulations in the United States mandate closed captioning, audio description, and emergency alert compatibility, shaping product roadmaps for domestic vendors. The EUs GDPR and pending AI Act impose strict constraints on automated content recognition and viewer profiling, forcing architecture redesigns for European deployments. Stakeholders must weigh the trade-off between edge localization for regulatory compliance and centralized cloud scale for unit economics as sovereignty requirements fragment processing architectures.
Market Dynamics
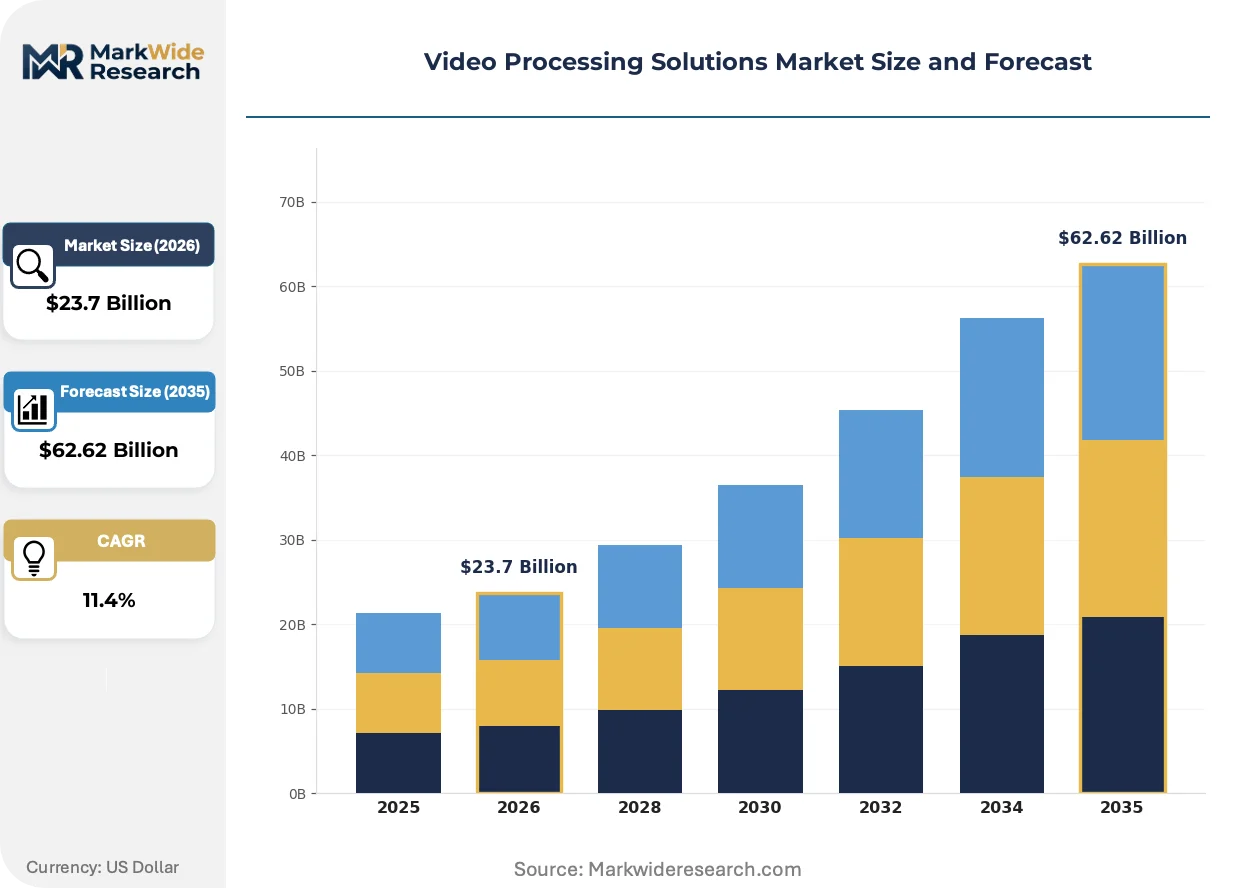
Cloud-native encoding farms are compressing capital cycles for broadcasters while FCC spectrum reallocation forces IP workflow migration, creating a bifurcation between elastic cloud scale and low-latency hardware acceleration.
Growth Catalysts
- Regulatory Mandates:The FCC's spectrum reallocation orders in the United States are compelling broadcasters to retire legacy SDI infrastructure and deploy IP-based video processing pipelines.
- Codec Evolution:AV1 and VVC adoption by streaming platforms is driving replacement cycles for encoding hardware and software licensing across distribution networks.
- Edge Computing:Media hubs in Los Angeles and New York are deploying localized transcoding nodes to reduce backhaul costs for live sports and news workflows.
Market Restraints
- Input Cost Volatility:FPGA and ASIC fabrication costs fluctuate with semiconductor foundry capacity constraints, squeezing margins for hardware-accelerated encoding appliances.
- Supply Concentration:Advanced GPU clusters for AI-driven content analysis concentrate in hyperscaler data centers, limiting independent vendor access to training infrastructure.
- Regulatory Friction:GDPR data residency rules fragment processing architectures across European territories, preventing unified cloud scale economics.
Strategic Opportunities
- Underpenetrated Verticals:Security and surveillance operators in India represent nascent demand for real-time video analytics and edge encoding solutions.
- Technology Convergence:Synthesis of computer vision AI with real-time transcoding enables automated content moderation and dynamic ad insertion pipelines.
- Regulatory Tailwind:The EU AI Act's transparency requirements for automated content recognition create compliance service opportunities for European deployments.
Industry Challenges
- Skill Scarcity:Broadcast engineers with hybrid IP/SDI expertise are retiring faster than cloud-native DevOps specialists can replace them, creating operational bottlenecks.
- Integration Complexity:Hybrid cloud-on-premise architectures require custom orchestration layers that extend deployment timelines and inflate professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Processing Solutions Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $62.62 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Service, Cloud-based Application: Broadcast, Security, Entertainment, Gaming Technology: AI, FPGA, ASIC, GPU End User: Media Companies, Enterprises, Government, Education |
| Companies Covered | Akamai Technologies, Ateme, Morpho, Inc., Synamedia, Vantrix Corporation, MediaKind, Imagine Communications, The MathWorks, Inc., Base Media Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Processing Solutions Market Evolving Landscape
Software-defined video compression is dissolving the boundary between broadcast and streaming infrastructure, while AI-driven personalization pipelines are consuming GPU resources at unprecedented scale.
AV1 encoding is rewriting cost structures for streaming distribution. Media companies are deploying royalty-free codecs to escape HEVC patent pool complexity. The technology is compressing bitrate requirements by thirty to fifty percent versus H.264, enabling 4K delivery over constrained last-mile connections.
The EU AI Act is imposing documentation burdens on automated content recognition systems deployed in European territories. Vendors must maintain audit trails for training data and model decisions. French and German broadcasters are front-loading compliance engineering to avoid deployment freezes.
Usage-priced encoding farms are displacing perpetual license models for transcoding software. Broadcasters in the United States are adopting elastic cloud contracts that scale with live event volume. Sports leagues and news networks are driving this shift during election cycles and championship seasons.
Video Processing Solutions Market Segmentation
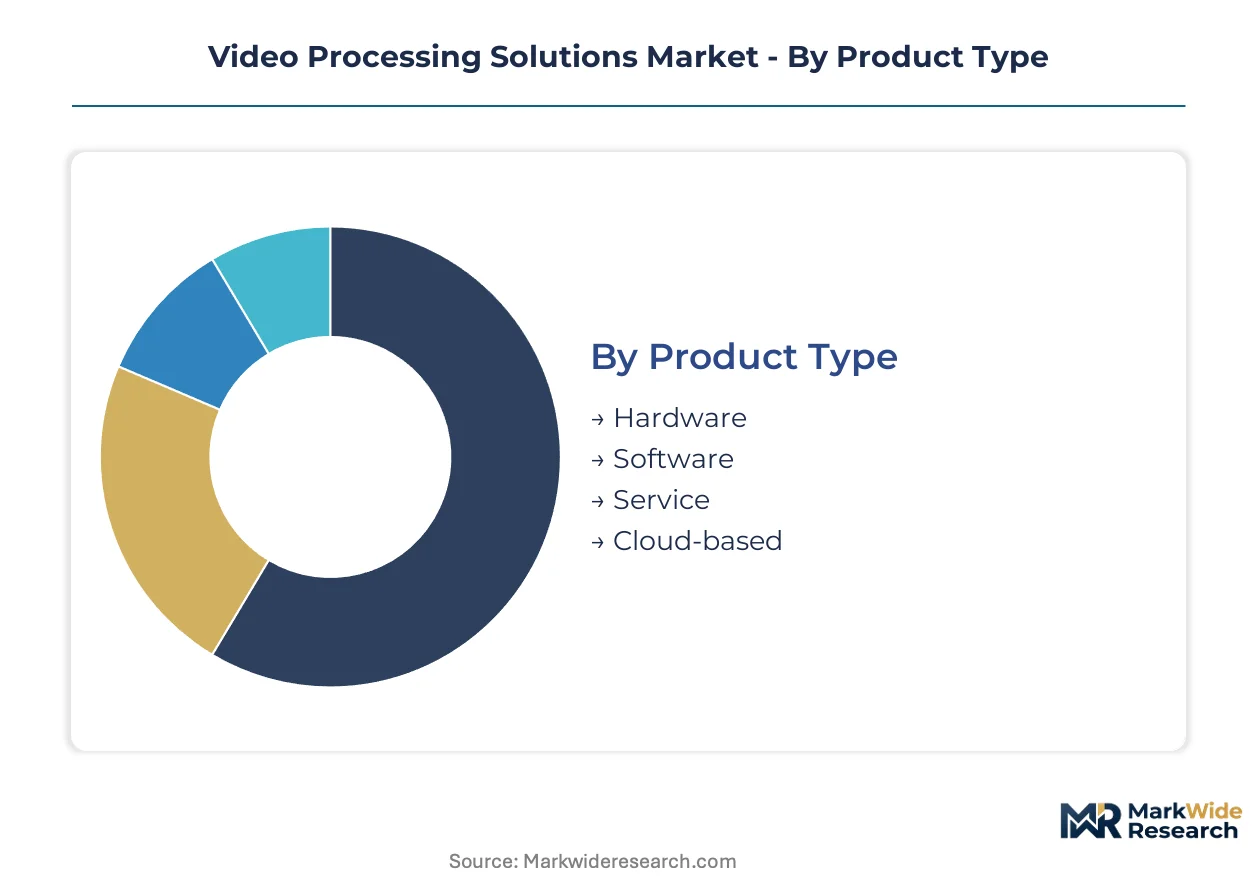
Codec certification requirements and broadcast compliance standards fragment procurement decisions across video processing segments. Buyers weigh FCC mandates against EBU technical specifications when selecting encoding infrastructure for multi-territory distribution.
Product Type:
FCC Part 73 broadcast certification applies to hardware encoders deployed in US terrestrial transmission chains. Software and cloud-based solutions face lighter equipment authorization but heavier GDPR scrutiny for viewer data handling.
- Hardware:ASIC and FPGA-based appliances deliver deterministic latency for live broadcast workflows. Demand concentrates among US broadcasters replacing SDI infrastructure under FCC spectrum reallocation orders, with Los Angeles and New York media hubs driving enterprise-scale deployments.
- Cloud-based:Elastic encoding farms scale with live event volume through usage-priced contracts. Streaming platforms in the United States are abandoning capital-intensive on-premise infrastructure for these deployments, compressing procurement cycles during election and sports seasons.
- Software:Perpetual license models persist in European deployments where data residency requirements favor on-premise control over viewer metadata.
- Service:Managed transcoding operations address skill scarcity among broadcast engineers with hybrid IP/SDI expertise.
Leading the category by volume: Hardware. Growing fastest: Cloud-based.
Application:
Cost tiering separates premium broadcast-grade processing from volume-optimized streaming encoding, with security applications commanding specialized analytics premiums.
- Broadcast:Real-time encoding with closed captioning and emergency alert compatibility mandated by FCC regulations. US broadcasters invest heavily in IP-based workflows to meet spectrum reallocation deadlines.
- Entertainment:AV1 and VVC adoption by streaming platforms drives replacement cycles for encoding infrastructure across distribution networks.
- Security:Edge encoding with computer vision AI for real-time analytics. Indian surveillance operators represent nascent demand for these integrated solutions.
- Gaming:Low-latency hardware acceleration outperforms general-purpose compute for interactive streaming requirements.
Dominant by revenue: Broadcast. Expanding most quickly: Security.
Technology:
GPU clusters concentrate in hyperscaler data centers, limiting independent vendor access to AI training infrastructure for content analysis pipelines.
- AI:Machine learning pipelines consume GPU resources at unprecedented scale for automated content moderation and dynamic ad insertion. GDPR and pending EU AI Act constraints force architecture redesigns for European deployments.
- GPU:Parallel processing architectures displace CPU-centric workflows in personalization and analytics pipelines. Supply concentration in hyperscaler facilities creates procurement bottlenecks for independent vendors.
- FPGA:Reconfigurable logic balances flexibility with acceleration for evolving codec standards.
- ASIC:Fixed-function designs optimize unit economics for high-volume encoding at mature codec specifications.
Highest deployment share: GPU. Steepest expansion trajectory: AI.
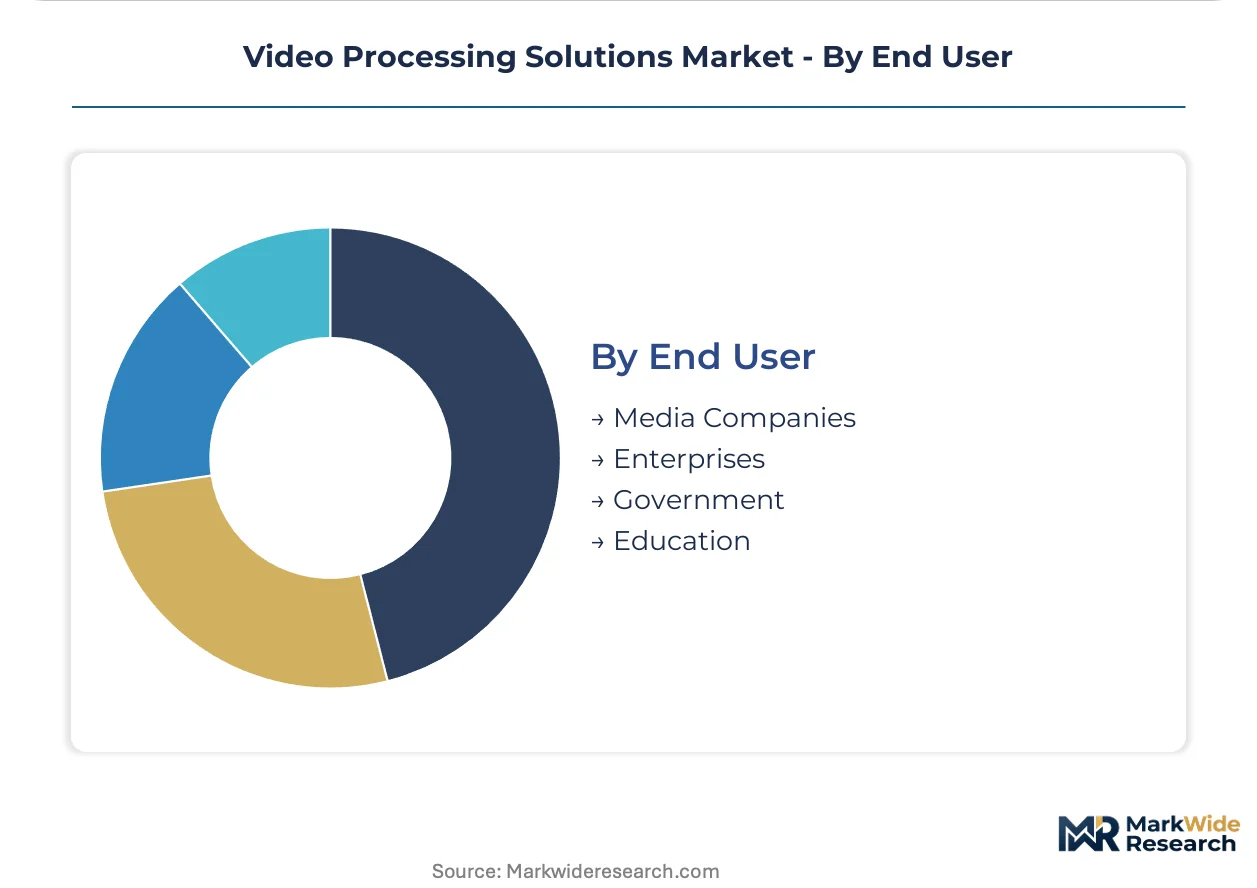
End User:
Customer procurement maturity separates media companies with broadcast engineering heritage from cloud-native enterprise adopters.
- Media Companies:Broadcasters and streaming platforms demand real-time encoding and transcoding infrastructure with hybrid cloud-on-premise orchestration. Integration complexity extends deployment timelines and inflates professional services costs.
- Enterprises:Corporate video communications and training platforms adopt elastic cloud contracts that scale with organizational needs.
- Government:Surveillance and public safety applications require edge-localized processing for data sovereignty compliance.
- Education:Lecture capture and remote learning platforms prioritize cost-efficient software encoding over hardware acceleration.
Largest installed base: Media Companies. Gaining share fastest: Enterprises.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Media technology special economic zones in Los Angeles and New York concentrate North American video processing investment, while Singapore's MediaCorp hub and Dubai Media City anchor Asian and Middle Eastern infrastructure buildouts respectively.
United States
FCC spectrum reallocation mandates are compelling broadcasters to retire SDI infrastructure for IP-based workflows. The FCC's Part 73 broadcast certification shapes encoder procurement for terrestrial transmission chains. Los Angeles and New York media hubs drive enterprise-scale deployments across hybrid cloud-native and on-premise architectures.
Germany
GDPR data residency requirements fragment processing architectures across European territories, favoring on-premise control over viewer metadata. The EU AI Act imposes documentation burdens on automated content recognition systems. Berlin and Munich broadcast engineering clusters front-load compliance engineering to avoid deployment freezes.
India
Security and surveillance operators represent nascent demand for real-time video analytics and edge encoding solutions. TRAI regulations shape content distribution network architectures for streaming platforms. Mumbai and Bangalore technology corridors concentrate domestic media infrastructure investment.
Japan
Broadcast-grade processing for satellite and terrestrial operators maintains hardware encoder demand amid codec evolution. METI industrial policy supports domestic semiconductor fabrication for FPGA acceleration. Tokyo and Osaka media technology districts anchor regional encoding infrastructure procurement.
United Arab Emirates
Dubai Media City and Abu Dhabi production zones attract international streaming platform regional headquarters requiring localized transcoding nodes. Data sovereignty requirements favor edge-localized processing over centralized cloud scale. Saudi Arabia's neighboring media investments create competitive infrastructure pressure across the Gulf.
Video Processing Solutions Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across video processing infrastructure tiers. The vendor base organizes around three strategic archetypes: CDN operators with globally distributed edge networks, software-defined compression specialists, and broadcast-grade hardware fabricators. M&A activity concentrates on codec technology acquisitions and cloud infrastructure consolidation. Strategic partnerships between semiconductor foundries and encoding appliance manufacturers reshape supply security.
Among US-based technology providers, Akamai Technologies occupies a position within the distributed edge network archetype, while MediaKind represents broadcast-grade processing specialization for satellite operators. Ateme exemplifies the software-defined compression tier with its focus on evolving codec standards. These three anchors illustrate how competitive positioning fragments across infrastructure layers rather than consolidating around integrated stacks.
| Leading Market Players |
|---|
| Akamai Technologies |
| Ateme |
| Morpho, Inc. |
| Synamedia |
| Vantrix Corporation |
| MediaKind |
| Imagine Communications |
| The MathWorks, Inc. |
| Base Media Cloud |
| Others |
Value Network & Pricing Analysis
FCC Part 73 broadcast certification mandates gate qualified supply access for US terrestrial transmission chains, with certified hardware encoders commanding premium-tier pricing over uncertified alternatives. Buyers face compressed procurement cycles during spectrum reallocation deadlines, amplifying price premiums for rapid-deployment inventory while spot-market cloud encoding services compete on usage-priced elasticity.
Pricing Analysis
Short lead-time premiums dominate hardware encoder procurement as US broadcasters race FCC spectrum reallocation deadlines, while spot inventory of cloud encoding credits trades at discount to reserved capacity. Three-tier pricing structure across broadcast-certified, enterprise-grade, and developer-tier solutions separates FCC-compliant hardware from SaaS elasticity and open-source tooling. Price differentiation hinges on certification tier and volume commitment scale. Pricing pressure stems from hyperscaler cloud encoding farms compressing margins for on-premise appliance vendors. Mid-market streaming platforms exhibit highest price sensitivity, while major broadcast networks prioritize compliance assurance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale broadcaster demand for FPGA and ASIC acceleration appliances, while value-added distributors serve mid-tier streaming platform procurement. Taiwan, South Korea, and the United States concentrate advanced semiconductor fabrication for encoding hardware. Raw material dependencies center on silicon wafers, advanced packaging substrates, and GPU clusters for AI-driven content analysis. Single-source vulnerability in TSMC's leading-edge foundry capacity creates supply risk for broadcast-grade encoding appliances. Distribution runs through direct OEM relationships for tier-1 broadcasters and cloud marketplace integrations for elastic encoding services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into GPU cluster ownership and edge node deployment is reshaping competitive positioning, with players pursuing captive control over AI training infrastructure and localized transcoding capacity to escape hyperscaler dependency.
For Market Incumbents: Lock in broadcast certification moats by accelerating FCC Part 73 compliance engineering ahead of spectrum reallocation deadlines. Deepen backward integration into FPGA design partnerships with Taiwan Semiconductor Manufacturing to secure foundry allocation against fabless entrant competition. Channel control through managed service bundling defends against hyperscaler cloud encoding erosion.
For New Entrants and Emerging Players: Indian security and surveillance operators represent the most penetrable buyer archetype for edge encoding solutions with integrated computer vision AI. Municipal smart city contracts in Mumbai and Bangalore technology corridors offer white-space entry with lower certification barriers than US broadcast tiers. Go-to-market through system integrators familiar with TRAI content distribution regulations accelerates local trust formation.
For Investors and Strategic Acquirers: EU AI Act enforcement actions against non-compliant automated content recognition deployments are the leading indicator that compliance-engineering capabilities will command acquisition premiums. Long-term viability favors targets with hybrid cloud-on-premise orchestration expertise and European data residency architecture. Monitor French and German broadcaster procurement freezes as early signals of regulatory-driven vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Codec Technology Acquisition | AV1 and VVC patent portfolios enable royalty-free positioning against HEVC pool complexity. |
| Edge Node Deployment | Localized transcoding in Los Angeles and New York media hubs reduces backhaul costs for live workflows. |
| AI Compliance Engineering | EU AI Act documentation capabilities unlock European broadcaster procurement cycles. |
| Cloud Infrastructure Partnership | Hyperscaler alliances provide GPU cluster access for AI-driven personalization pipelines. |
| Managed Service Transition | Usage-priced encoding farms address skill scarcity among retiring broadcast engineers. |
Research Methodology
Document review covered FCC spectrum reallocation orders, EMA regulatory guidance on AI Act implementation, and hyperscaler capex disclosures, complemented by interviews with broadcast engineering directors, streaming platform CTOs, and semiconductor procurement leads. Secondary validation drew from SEC 10-K filings of encoding appliance vendors, TRAI content distribution network filings, and customs data on FPGA import volumes. Bottom-up and top-down triangulation cross-referenced deployment counts with infrastructure spending estimates.
Historical capacity expansion patterns were cross-referenced against expert panel input on codec transition timelines across the projection horizon. Segmentation dimensions modeled include product type, application vertical, technology architecture, and end-user procurement maturity. CAGRs were derived from elasticity-adjusted deployment trajectories. Industry-specific forecast inputs incorporated FCC mandate compliance deadlines and EU AI Act enforcement phased implementation.
Revisions become necessary when semiconductor foundry capacity constraints intensify, GDPR enforcement patterns shift data residency requirements, or AV1 adoption accelerates beyond HEVC replacement baselines. Practitioners should monitor hyperscaler encoding pricing announcements, European regulatory guidance publications, and Indian smart city procurement tenders for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
AI-Based Fever Detection Camera Market
Imaging
Biophotonics Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
2D and 3D Machine Vision Systems Market
Imaging
Infrared Imaging Market
Imaging
360-Degree Camera Market
Imaging
Global Broadcast Cameras Market
Imaging
IR Camera Market
Imaging
CMOS Camera Market
Imaging
APAC Thermal Imaging Systems Market
Imaging
Global 3D Imaging Market
Imaging
Photography Equipment Market
Imaging
X-Ray Market
Imaging
Webcam Market
Imaging
India CCTV Camera Market