
 Algainp Epitaxial Wafers Market | 2026-2036
Algainp Epitaxial Wafers Market Size, Share, and Industry Trends Forecast 2026-2036
Algainp Epitaxial Wafers Market Insights
Direct procurement channels between epitaxial wafer foundries and LED chip makers is reshaping how AlGaInP supply contracts are negotiated and fulfilled. IQE plc leverages its multi-site MOCVD capacity to sustain long-term supply agreements with tier-one photonics customers. Sumitomo Electric Industries anchors Japanese domestic demand through captive production of high-brightness LED substrates. Shin-Etsu Chemical differentiates via vertical control over raw gallium and indium sourcing.
AlGaInP epitaxial wafers consist of aluminum-gallium-indium-phosphide layers grown on GaAs substrates, engineered with bandgaps between 1.9 and 2.3 eV to emit red-to-yellow visible light for solid-state illumination and optical signaling. MOCVD technology dominates commercial production due to precise compositional grading and thickness control at the monolayer scale. Thin Wafers command expanding share in micro-LED transfer applications where substrate removal reduces pixel pitch. LED applications occupy the largest value pool, though Lasers segment exhibits the fastest structural growth driven by automotive lidar and facial recognition modules.
Japan's METI enforces JIS standards on compound semiconductor material traceability, while China's MIIT mandates domestic sourcing ratios for critical optoelectronic substrates under national technology self-sufficiency programs. REACH compliance in Europe restricts cadmium and lead content in downstream LED packages, indirectly elevating AlGaInP wafer purity specifications. Stakeholders must monitor how regional subsidy regimes for domestic epitaxial capacity reshape competitive access rules and qualification timelines.
Market Dynamics
Micro-LED transfer technology is collapsing substrate thickness requirements, forcing foundries to reconfigure MOCVD growth parameters and substrate removal processes for sub-50-micron architectures.
Growth Catalysts
- Automotive lidar deployment:Tier-one suppliers are qualifying AlGaInP edge-emitting lasers for 1550nm wavelength modules. NHTSA mandates for pedestrian detection systems accelerate component validation timelines.
- China's dual carbon goals:MEE efficiency mandates for display manufacturing elevate demand for high-luminance red emitters that reduce power consumption in large-format screens.
- Thin-wafer micro-LED architectures:Substrate removal processes enabling sub-20-micron pixel pitches are penetrating consumer electronics prototyping labs.
Market Restraints
- Raw gallium price volatility:Electrolytic grade gallium spot markets swing with semiconductor and photovoltaic demand cycles, compressing foundry margins during allocation periods.
- GaAs substrate supply concentration:Three Japanese suppliers control 80% of semi-insulating GaAs wafer capacity for epitaxial growth, creating single-source vulnerability.
- Indium phosphide substitution threat:InP-based red emitters are displacing AlGaInP in telecom applications above 2.0 eV bandgap requirements.
Strategic Opportunities
- India PLI scheme for compound semiconductors:Domestic epitaxial capacity subsidies under the Ministry of Electronics and IT attract foundry joint ventures for LED and laser applications.
- AR/VR near-eye display micro-LEDs:Sub-10-micron red pixels for full-color waveguide engines remain underpenetrated, with only prototype volumes shipping.
- EU Green Deal material traceability:REACH-compliant supply chain documentation creates premium positioning for foundries with certified conflict-free indium sourcing.
Industry Challenges
- MOCVD reactor operator scarcity:Monolayer-precision growth engineering requires 5-7 year apprenticeship pipelines that outpace university compound semiconductor program output.
- Micro-LED mass transfer yield:Laser lift-off and stamp-based pick-and-place processes for thin wafers struggle with sub-99.9% placement accuracy at production speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Algainp Epitaxial Wafers Market |
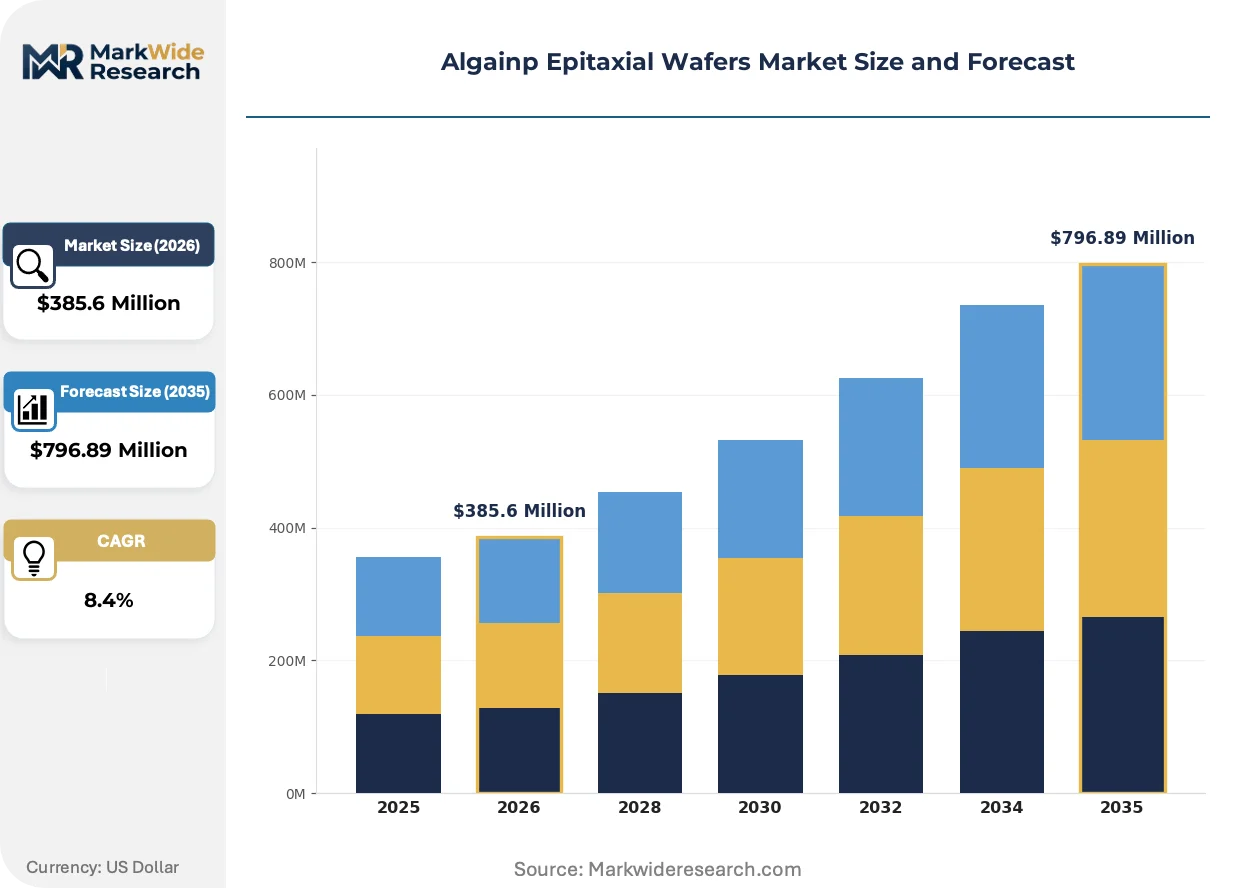
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Wafers, Thin Wafers, Patterned Wafers, SOS Wafers End User: Consumer Electronics, Telecommunications, Automotive, Aerospace Application: LEDs, Lasers, Photovoltaics, Sensors Technology: MOCVD, CVD, LPCVD, PECVD |
| Companies Covered | IQE plc, Sumitomo Electric Industries, Shin-Etsu Chemical, Epistar Corporation, Visual Photonics Epitaxy Co., Ltd., PAM-XIAMEN, Xiamen Powerway Advanced Material Co., Ltd., Atecom Technology, San'an Optoelectronics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Algainp Epitaxial Wafers Market Trends and Innovations
Wafer-scale processing advances and regulatory material constraints are converging to redefine epitaxial specifications across display and sensing applications.
Atomic layer etching for substrate thinning is collapsing the boundary between epitaxial growth and post-processing foundry services. Display panel makers in Taiwan and South Korea are integrating these capabilities in-house, compressing the traditional merchant wafer supply chain. The technology is collapsing foundry margins on standard-thickness products while creating premium tiers for sub-20-micron architectures.
REACH restrictions on cadmium and lead in downstream LED packages are tightening purity specifications for aluminum, gallium, and indium precursor materials. ECHA substance evaluation protocols now require full lot traceability from metal refining through MOCVD deposition. European automotive lighting suppliers are qualifying foundries with certified contaminant testing to preempt supply disruption.
Direct long-term contracts between LED chip designers and epitaxial foundries are displacing spot market procurement for high-brightness applications. Tier-one consumer electronics brands in Japan and South Korea are locking 3-5 year wafer supply agreements to secure capacity for micro-LED roadmaps. This pattern concentrates procurement leverage with vertically integrated device makers, marginalizing merchant distributors in the value chain.
Algainp Epitaxial Wafers Market Segmentation
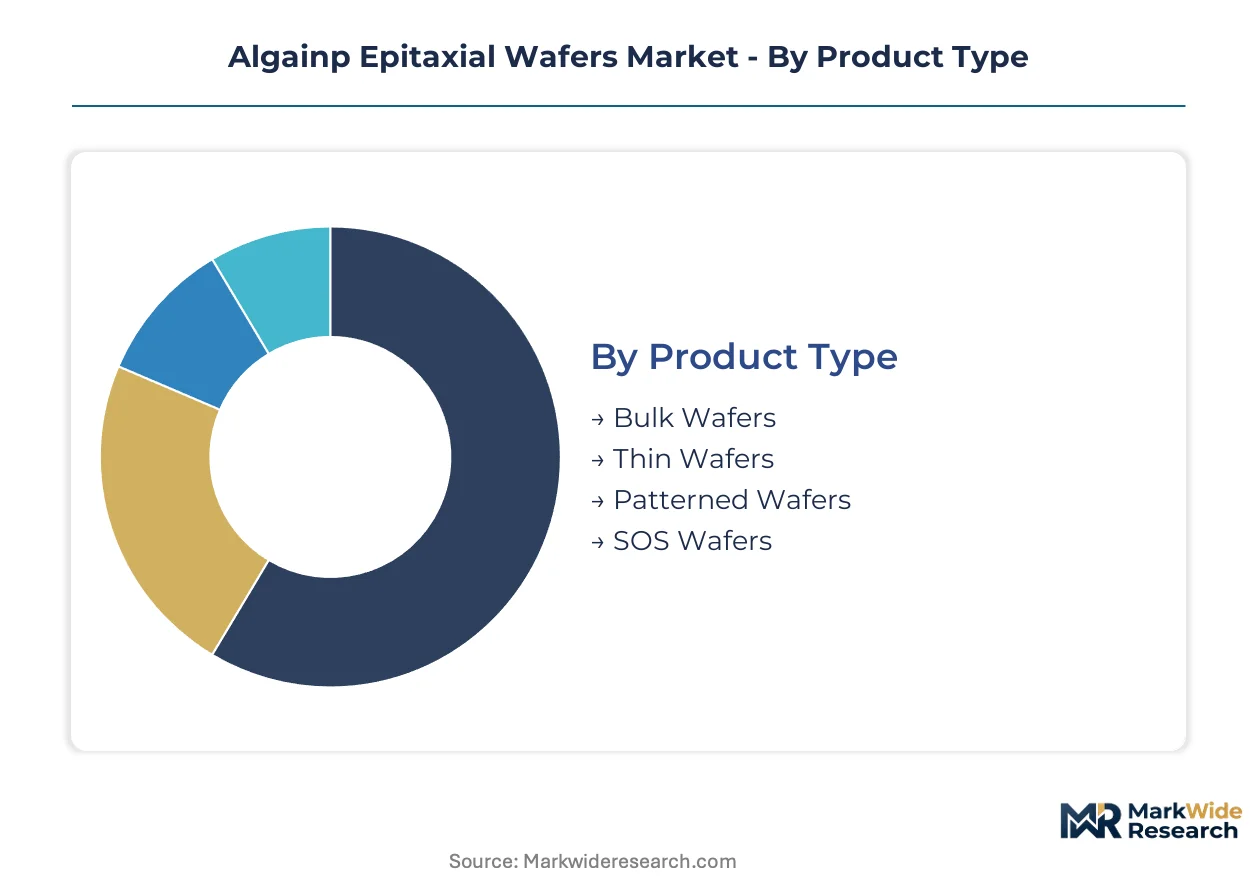
Epitaxial wafer procurement patterns diverge sharply across product architectures and deposition technologies. Cycle times from MOCVD growth to device qualification stretch from weeks for standard bulk formats to months for sub-20-micron thin wafer stacks.
Product Type:
Thin wafers turn inventory fastest in micro-LED prototyping labs, while bulk formats linger in long-haul LED backlighting contracts.
- Thin Wafers:Substrate-removed architectures below 50 microns enable sub-20-micron pixel pitches for near-eye displays. Taiwan and South Korea panel makers are qualifying these for AR waveguide engines, though laser lift-off yields remain below production thresholds.
- Bulk Wafers:Standard-thickness GaAs substrates with full epitaxial stacks dominate high-brightness LED foundry output. China's display manufacturing clusters absorb the largest volumes under MEE efficiency mandates for large-format screens.
- Patterned Wafers:Pre-etched surface geometries for selective area growth in photonic integrated circuits.
- SOS Wafers:Silicon-on-sapphire configurations for RF device isolation in telecommunications infrastructure.
Bulk wafers dominate installed base. Thin wafers are where expansion concentrates.
End User:
Automotive qualification cycles stretch longest, while consumer electronics refresh rates compress procurement windows to quarterly rhythms.
- Automotive:Tier-one lidar suppliers are validating AlGaInP edge-emitting lasers for 1550nm pedestrian detection modules. NHTSA mandates are compressing component validation timelines for domestic US and Japanese vehicle programs.
- Consumer Electronics:Smartphone and tablet backlighting drives recurring demand for red-to-yellow emitters. Japanese and South Korean device makers are locking multi-year supply agreements to secure micro-LED roadmaps.
- Telecommunications:Optical fiber signal amplification and datacenter interconnects.
- Aerospace:Radiation-hardened optical sensors and satellite communication arrays.
Consumer electronics commands volume share. Automotive is climbing the fastest.
Application:
LED applications amortize equipment costs across the longest production runs, while laser qualification batches fragment capacity allocation.
- LEDs:Red-to-yellow solid-state illumination for display backlights, automotive lighting, and general illumination. China's dual carbon goals are elevating demand for high-luminance red emitters that reduce power consumption in large-format screens.
- Lasers:Edge-emitting and vertical-cavity surface-emitting architectures for lidar, facial recognition, and optical sensing. Automotive qualification programs in Japan and Germany are driving the steepest expansion trajectory.
- Photovoltaics:Multi-junction solar cell stacks for satellite power systems.
- Sensors:Proximity detection and ambient light measurement in mobile devices.
LEDs anchor revenue concentration. Lasers represent the fastest-growing trajectory.
Technology:
Deposition method selection locks foundries into specific precursor supply chains and reactor maintenance schedules.
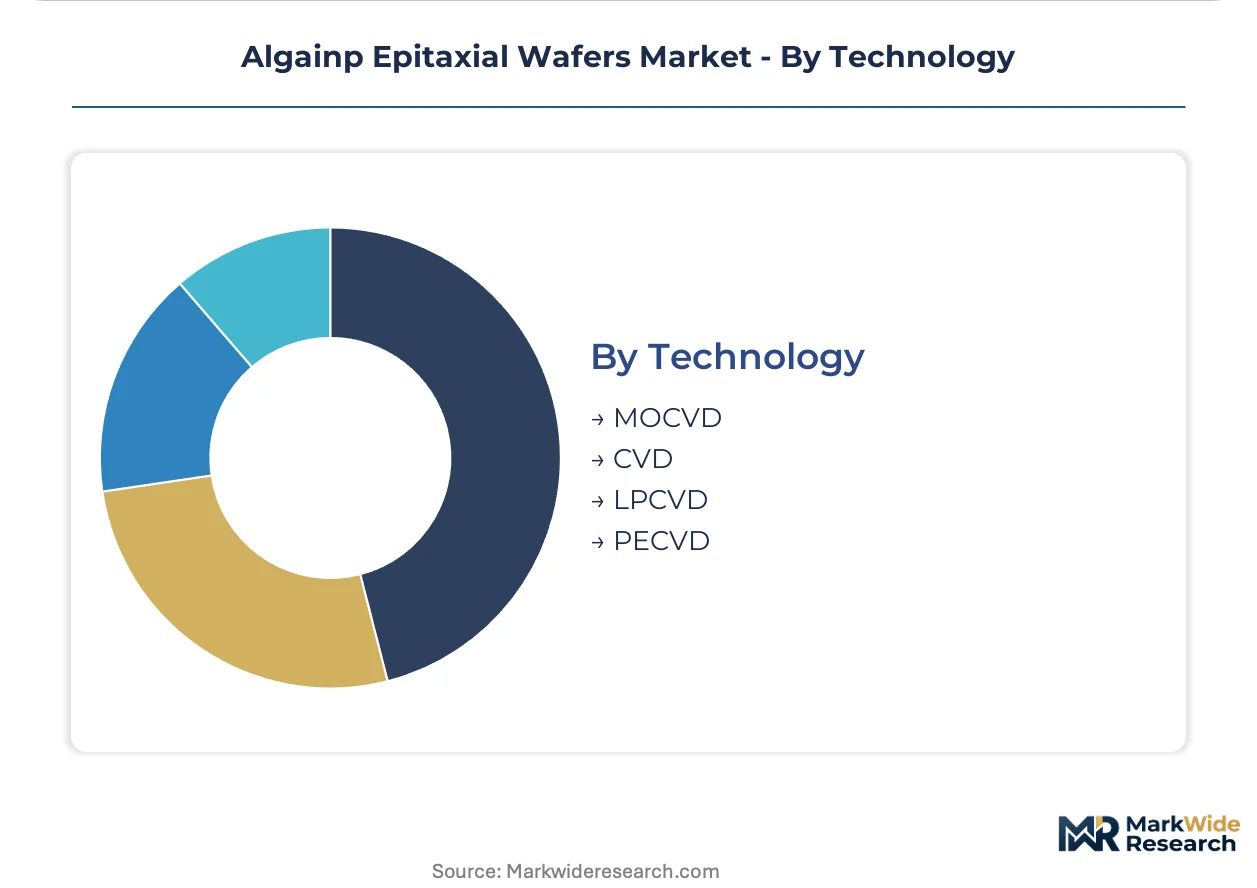
- MOCVD:Metal-organic chemical vapor deposition enables monolayer-precision compositional grading for high-brightness emitters. IQE plc and Sumitomo Electric Industries anchor capacity concentration in the UK and Japan.
- CVD:Conventional chemical vapor deposition for thicker, less graded epitaxial stacks.
- LPCVD:Low-pressure configurations for reduced defect density in research quantities.
- PECVD:Plasma-enhanced deposition for lower-temperature processing of temperature-sensitive substrates.
MOCVD commands commercial scale. PECVD is gaining share in temperature-constrained applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT mandates on domestic sourcing ratios anchor China's position as the dominant geography for AlGaInP epitaxial wafer demand. Japan's METI enforces material traceability standards that constrain supply chain flexibility. South Korean display manufacturers are locking multi-year procurement agreements to secure micro-LED roadmaps.
China
MEE efficiency mandates for display manufacturing drive demand for high-luminance red emitters in large-format screens. The dual carbon goals elevate material purity requirements for LED backlighting applications. Manufacturing clusters in Shenzhen and Dongguan absorb the largest wafer volumes under national technology self-sufficiency programs.
Japan
Domestic automotive lidar qualification programs accelerate component validation timelines for edge-emitting lasers. METI enforces JIS standards on compound semiconductor material traceability through the supply chain. Tokyo and Osaka house captive production facilities serving tier-one photonics customers.
South Korea
Consumer electronics brands are securing 3-5 year wafer supply agreements for micro-LED display roadmaps. MFDS oversight of optoelectronic material imports creates compliance checkpoints for foreign suppliers. Seoul and Suwon host integrated panel makers developing sub-20-micron pixel architectures.
Taiwan
Micro-LED prototyping labs are qualifying thin wafer stacks for AR waveguide engines. The country's national semiconductor regulator monitors precursor material imports for display foundries. Hsinchu Science Park concentrates MOCVD capacity serving international LED chip designers.
United States
NHTSA mandates for pedestrian detection systems compress automotive lidar component validation timelines. EPA oversight of gallium refining operations affects precursor material availability for domestic foundries. California and Texas host design centers qualifying AlGaInP lasers for 1550nm wavelength modules.
Algainp Epitaxial Wafers Market Competitive Landscape
Merchant foundries and vertically integrated chemical conglomerates split the market into competing supply models. Three Japanese suppliers control the majority of semi-insulating GaAs substrate capacity, creating structural concentration upstream. Strategic archetypes include multi-site MOCVD operators, captive producers of high-brightness substrates, and vertically integrated raw material controllers. Capacity expansion and long-term supply agreement locking represent the dominant competitive moves reshaping procurement relationships.
Among UK-based epitaxial specialists, IQE plc occupies a position exemplifying multi-site MOCVD capacity deployment. Sumitomo Electric Industries anchors the Japanese domestic market through captive production architectures. Shin-Etsu Chemical represents vertical control over raw gallium and indium sourcing, a model that insulates against electrolytic grade metal price volatility.
| Leading Market Players |
|---|
| IQE plc |
| Sumitomo Electric Industries |
| Shin-Etsu Chemical |
| Epistar Corporation |
| Visual Photonics Epitaxy Co., Ltd. |
| PAM-XIAMEN |
| Xiamen Powerway Advanced Material Co., Ltd. |
| Atecom Technology |
| San'an Optoelectronics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Chinese MOCVD foundries during display manufacturing downturns compresses spot pricing for standard-thickness bulk wafers while tightening availability for sub-20-micron thin architectures. This utilization asymmetry forces buyers into longer-term contracts to secure premium capacity, reshaping how procurement leverage distributes across merchant and captive supply models.
Pricing Analysis
East Asian price spreads between Japanese-sourced and Chinese-sourced epitaxial stacks reflect purity-grade differentiation and METI traceability certification premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by MOCVD reactor vintage and precursor lot documentation. Cost compression in standard bulk formats intensifies as Chinese domestic capacity expands under MIIT self-sufficiency mandates. Consumer electronics backlighting procurement teams exhibit highest price sensitivity, while automotive lidar qualification programs prioritize certified supply continuity over unit economics.
Supply Chain Analysis
Electrolytic gallium refining capacity concentrates in China and Japan, with indium extraction tethered to zinc mining operations in Canada and South Korea. High-purity aluminum precursor and semi-insulating GaAs substrate supply draws from Japanese and German specialty chemical producers. Single-source vulnerability pervades the GaAs substrate tier, where three Japanese suppliers anchor 80% of semi-insulating capacity. Distribution runs through direct long-term contracts between epitaxial foundries and LED chip designers, displacing merchant distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-LED transfer technology is collapsing substrate thickness requirements, creating a high-growth disruption window as display roadmaps pivot toward sub-20-micron architectures and NHTSA lidar mandates accelerate automotive laser qualification.
For Market Incumbents: Build captive precursor supply moats through backward integration into high-purity gallium refining or indium sourcing partnerships. Secure multi-year supply agreements with tier-one consumer electronics brands before micro-LED roadmaps lock capacity. Defend against InP-based red emitter substitution by accelerating MOCVD process yields for sub-50-micron architectures. For New Entrants and Emerging Players: Establish a beachhead in thin-wafer micro-LED prototyping services for Taiwan and South Korea panel makers, where laser lift-off yield challenges delay incumbent scale-up. Target India's PLI-subsidized compound semiconductor foundry joint ventures as the most penetrable geography. Lead with atomic layer etching capabilities that compress the boundary between epitaxial growth and post-processing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among multi-site MOCVD operators with locked 3-5 year photonics supply agreements. Five-to-ten year viability favors foundries with certified REACH-compliant supply chain documentation and conflict-free indium traceability. Monitor NHTSA pedestrian detection mandate implementation timelines as the inflection signal for automotive lidar laser demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement Locking | IQE plc and Sumitomo Electric Industries anchor capacity concentration through multi-year photonics contracts. |
| Backward Integration into Precursor Refining | Shin-Etsu Chemical insulates margins against electrolytic gallium spot volatility through captive metal sourcing. |
| Micro-LED Thin Wafer Process Development | Taiwan and South Korea panel makers integrate atomic layer etching to collapse substrate removal bottlenecks. |
| India PLI Joint Venture Formation | Domestic epitaxial capacity subsidies under Ministry of Electronics and IT attract foundry partnerships for LED applications. |
| REACH-Compliant Supply Chain Certification | European automotive lighting suppliers qualify foundries with full lot traceability from metal refining through MOCVD deposition. |
Research Methodology
The analysis maps MOCVD reactor capacity deployment, thin-wafer substrate removal yields, and laser diode qualification pipelines, each validated through epitaxial foundry operations directors, LED chip procurement managers, automotive tier-one component engineers, and display panel technology strategists. Primary interview data triangulates against customs trade records for gallium and indium precursor movements, SEC filings from publicly traded compound semiconductor specialists, METI and MIIT regulatory disclosure databases, and MOCVD equipment vendor order backlogs. Bottom-up wafer volume estimates reconcile with top-down display manufacturing capacity absorption models.
Assumptions held fixed include MEE efficiency mandate enforcement timelines and NHTSA pedestrian detection system phase-in schedules, while variables tested include raw gallium price volatility bands and micro-LED mass transfer yield improvement trajectories. Segmentation dimensions span product architecture, deposition technology, end-use industry, and regional manufacturing cluster. CAGRs derive from installed base replacement cycles and emerging application penetration curves, incorporating automotive lidar adoption rates and AR/VR near-eye display micro-LED roadmap commitments as industry-specific demand drivers.
Stress conditions across electrolytic gallium allocation periods, GaAs substrate supply disruptions, and InP substitution acceleration in telecom applications were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and technology yield improvement trajectories. Cross-checking against EIA critical minerals market reports and SEMI equipment spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optoelectronics
Optoelectronic Transducers Market
Optoelectronics
Optical Emission Spectroscopy Market
Optoelectronics
Asia-Pacific Optoelectronics Market
Optoelectronics
Global Indium Phosphide (Inp) Wafers Market
Optoelectronics
China Optoelectronics Market
Optoelectronics
Electro-Optical/Infrared (EO/IR) Systems Market
Optoelectronics
China Optical Detector Market
Optoelectronics
Opto-Electronics Device Market
Optoelectronics
Thermophotovoltaics Market
Optoelectronics
Optical Pulse Sensor Market
Optoelectronics
Quantum Dot Lasers Market
Optoelectronics
Ingaas Avalanche Photodiode Market
Optoelectronics
EPON ONU Market
Optoelectronics
Heterojunction Solar Cell Market
Optoelectronics
United States Optoelectronics Market
Optoelectronics
Light Projector Market