
 PET Imaging Systems Market | 2026-2036
PET Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
PET Imaging Systems Market Analytics
A shortage of qualified nuclear medicine technologists and radiochemists is reorganizing how hospitals plan PET fleet expansions, forcing equipment vendors to prioritize automated radiopharmaceutical synthesis compatibility and simplified operator workflows. Siemens Healthineers anchors its position through proprietary digital detector architectures that reduce scan times and staffing burdens. GE Healthcare leverages integrated theranostics platforms linking diagnostic PET with lutetium-177 therapy planning. Philips differentiates via ambulatory imaging partnerships that extend PET access beyond major academic centers.
PET imaging systems detect positron-emitting radiotracer distributions using coincidence photon detection, with modern platforms achieving sub-5 mm spatial resolution through lutetium-based scintillation crystals or semiconductor photon-counting detectors; these systems primarily enable metabolic and molecular visualization for disease characterization, treatment planning, and therapy response assessment. Hybrid PET/CT configurations dominate installed bases and replacement cycles, while PET/MRI gains traction in neurology and pediatric oncology where soft-tissue contrast and reduced radiation exposure carry premium value. Photon-counting technology represents the fastest-growing technology segment, though time-of-flight systems still command the largest revenue pool due to proven clinical validation and established reimbursement codes.
The FDA governs device premarket approval and radiopharmaceutical IND/NDA pathways, while the Nuclear Regulatory Commission enforces dose calibration and technologist certification standards that directly shape equipment operability requirements and site qualification timelines. European regulators including EMA and national competent authorities enforce MDR conformity and REACH-compliant materials standards that affect detector crystal sourcing and vendor market access. Stakeholders must monitor whether CMS creates distinct reimbursement tiers for photon-counting versus conventional PET acquisitions, as this determination will redirect hospital capital planning across integrated delivery networks.
Market Dynamics
Photon-counting detector architectures are compressing scan times while simultaneously intensifying workforce pressure, as hospitals must upgrade fleets to capture CMS reimbursement advantages without expanding nuclear medicine technologist headcount.
Growth Catalysts
- 21st Century Cures Act:The FDA's accelerated radiopharmaceutical approval framework compresses IND-to-NDA timelines, enabling faster equipment procurement cycles for theranostics-capable PET platforms.
- Theranostics integration:Lutetium-177 therapy planning workflows now require diagnostic PET compatibility, pulling hospitals toward hybrid imaging investments that bridge staging and treatment monitoring.
- Medicare reimbursement:CMS coverage determinations for PET-directed biopsies and theranostics procedures direct capital allocation toward digital detector platforms in United States academic medical centers.
Market Restraints
- Lutetium oxyorthosilicate crystal supply:Detector manufacturing concentrates among limited crystal growers, exposing vendors to price volatility and qualification delays for new scintillation materials.
- NRC certification requirements:Nuclear Regulatory Commission technologist standards and site qualification timelines extend installation cycles, constraining fleet expansion velocity regardless of equipment availability.
- Photon-counting validation gaps:Established reimbursement codes favor time-of-flight systems, forcing hospitals to absorb financial risk for unproven photon-counting clinical economics.
Strategic Opportunities
- Ambulatory imaging networks:Partnership models extending PET access beyond major academic centers unlock volume in community oncology settings previously served by referral-dependent workflows.
- PET/MRI hybrid platforms:Neurology and pediatric oncology applications where soft-tissue contrast and radiation reduction carry premium value represent underpenetrated clinical segments.
- Automated radiochemistry:Synthesis module integration addresses technologist shortages while enabling decentralized tracer production for same-day scheduling flexibility.
Industry Challenges
- Nuclear medicine technologist pipeline:Training program capacity constraints limit workforce expansion, forcing sites to prioritize workflow automation over scanner count growth.
- Legacy system integration:PACS and EMR connectivity requirements complicate digital detector upgrades, extending deployment timelines and inflating total cost of ownership.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET Imaging Systems Market |
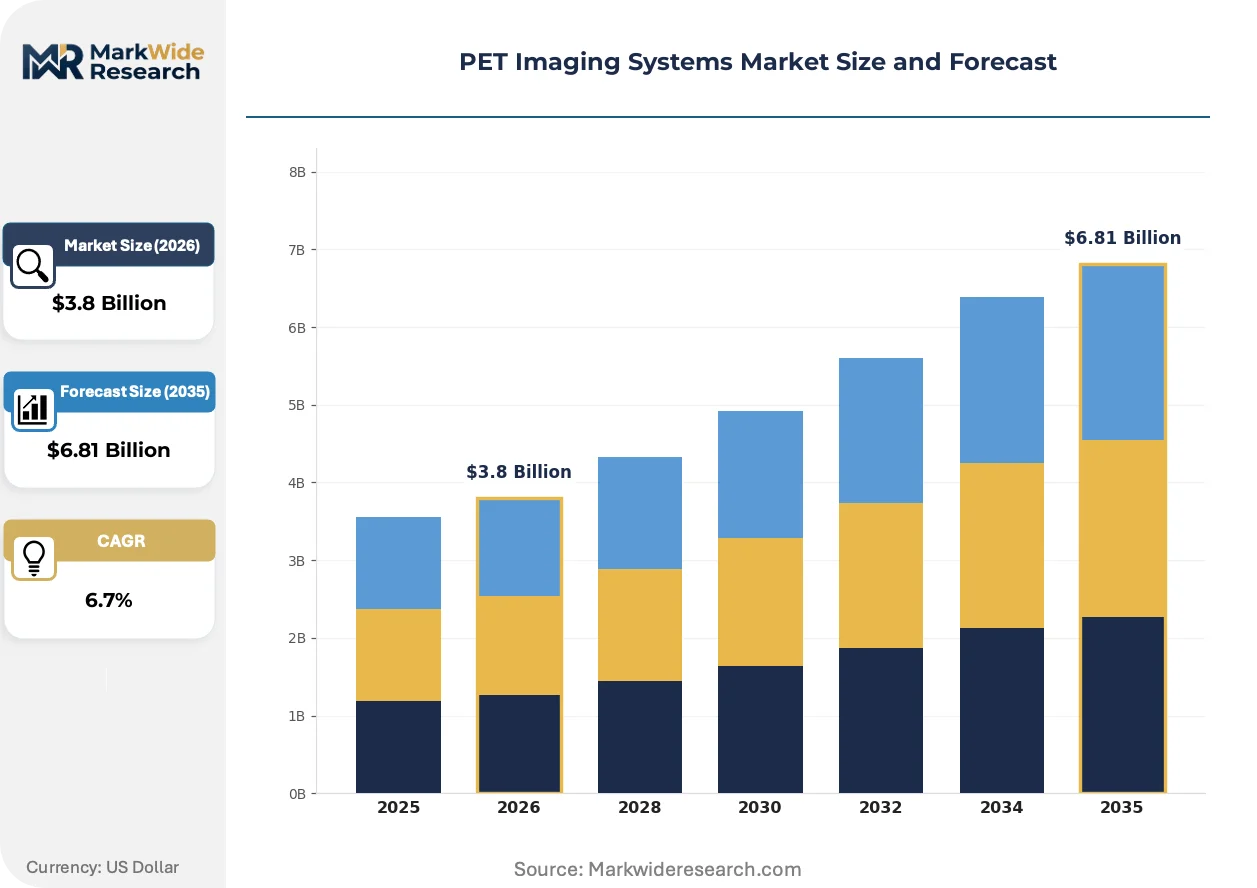
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: RS PET, Digital PET, Hybrid PET/CT, PET/MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Technology: Time-of-Flight, Continuous Wave, Photon Counting, Scintillation Application: Oncology, Cardiology, Neurology, Infectious Diseases |
| Companies Covered | GE Healthcare, Siemens Healthineers AG, Koninklijke Philips N.V., Canon Medical Systems Corporation, United Imaging Healthcare Co., Ltd., Bruker, Mediso Ltd., MinFound Medical Systems Co., Ltd., Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET Imaging Systems Market Evolving Landscape
Equipment architectures and service delivery models are diverging as vendors respond to workforce constraints, reimbursement uncertainty, and the theranostics transition reshaping clinical utility expectations.
Photon-counting semiconductor detectors is bifurcating the installed base between premium digital platforms and conventional scintillation systems. Academic medical centers in the United States and Germany are prioritizing these architectures for reduced scan times and lower staffing burdens. The technology is bifurcating vendor competitive positions around proprietary detector intellectual property rather than conventional gantry engineering.
EMA's Medical Device Regulation enforcement is tightening conformity assessment requirements for PET system software and AI-assisted reconstruction algorithms. European notified bodies now demand clinical validation documentation that extends approval timelines for algorithm-heavy platforms. Vendors are responding by segregating EU and non-EU product configurations, complicating global manufacturing scale.
Service contracting structures are unbundling preventive maintenance from software subscription fees as hospitals resist bundled pricing for capabilities they cannot fully deploy. Integrated delivery networks in the United States are negotiating à la carte service tiers tied to actual uptime guarantees rather than standard manufacturer terms. This fragmentation is most visible among mid-sized community hospitals lacking in-house biomedical engineering depth.
PET Imaging Systems Market Segmentation
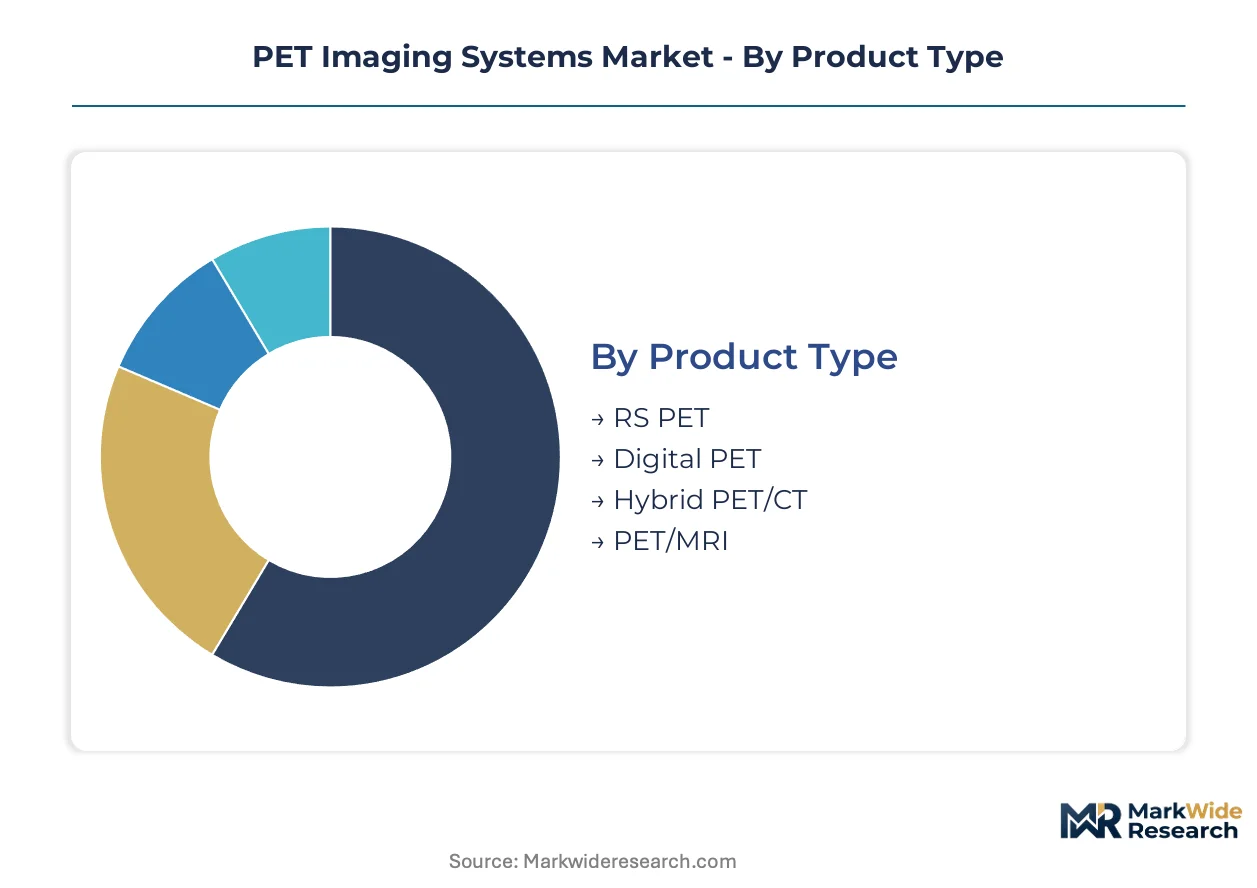
PET imaging systems fragment across four distinct dimensions that determine procurement patterns, reimbursement pathways, and vendor competitive positioning. Each segmentation layer reveals how capital allocation flows through academic medical centers versus community settings, and which detector architectures capture upgrade cycles.
Product Type:
Product type segmentation channels through academic medical centers for hybrid platforms and community hospitals for standalone digital systems, with RS PET serving price-sensitive entry markets.
- Digital PET:Semiconductor photon-counting detectors achieve sub-5 mm spatial resolution with reduced scan times. Siemens Healthineers and GE Healthcare concentrate demand in United States academic medical centers where CMS reimbursement for shorter procedures offsets capital premiums.
- Hybrid PET/CT:Integrated metabolic-anatomical imaging dominates oncology staging workflows through lutetium-based scintillation crystals. Germany and Japan anchor installed base expansion as national health systems standardize hybrid configurations for radiotherapy planning.
- RS PET:Ring-based scintillation systems serve emerging markets and budget-constrained community hospitals with established time-of-flight performance.
- PET/MRI:Soft-tissue contrast without ionizing radiation drives pediatric oncology and neurology demand in specialized centers.
Hybrid PET/CT dominates installed base. Digital PET is where expansion concentrates.
End User:
End user segmentation stratifies by capital depth and procedure volume, with integrated delivery networks centralizing PET fleet ownership while ambulatory partnerships extend reach.
- Hospitals:Academic medical centers in the United States and Germany deploy multi-scanner fleets with theranostics capability. Medicare reimbursement for PET-directed biopsies and lutetium-177 therapy planning drives capital allocation toward digital detector platforms.
- Diagnostic Centers:High-throughput independent imaging facilities concentrate in suburban United States markets and German metropolitan regions. Workflow automation and same-day scheduling flexibility determine vendor selection as technologist shortages constrain headcount expansion.
- Research Institutions:National laboratories and university medical centers validate novel radiotracers under FDA's 21st Century Cures Act framework.
- Imaging Clinics:Community-based facilities access PET through vendor partnership models and mobile scanner deployments.
Hospitals command capital expenditure volume. Diagnostic centers are gaining share fastest.
Technology:
Technology segmentation reflects a transition from established scintillation architectures toward semiconductor detectors, with reimbursement codes lagging hardware innovation.
- Photon Counting:Cadmium-zinc-telluride and silicon photomultiplier arrays enable direct energy measurement with improved signal-to-noise ratios. United States academic centers absorb financial risk for unproven clinical economics while awaiting CMS coverage determinations.
- Time-of-Flight:Lutetium oxyorthosilicate crystals with silicon photomultiplier readout deliver proven performance at established reimbursement levels. Germany and Japan maintain replacement cycle demand for incremental gantry improvements.
- Continuous Wave:Solid-state detector architectures serve specialized research applications requiring extended dynamic range.
- Scintillation:Conventional bismuth germanate and sodium iodide systems persist in legacy installed bases and emerging markets.
Time-of-Flight anchors revenue pools. Photon Counting shows steepest expansion trajectory.
Application:
Application segmentation channels radiotracer development investment and determines hybrid platform configuration, with oncology commanding radiopharmaceutical pipeline priority.
- Oncology:FDG-PET for staging and response assessment, plus PSMA and DOTATATE tracers for theranostics. United States academic medical centers integrate diagnostic PET with lutetium-177 therapy planning, compressing procurement timelines under FDA accelerated approval pathways.
- Neurology:Amyloid and tau imaging for Alzheimer's disease drives PET/MRI adoption where soft-tissue contrast carries premium value. Germany and Japan concentrate dementia imaging volume as aging demographics expand eligible populations.
- Cardiology:Myocardial perfusion and viability assessment serves coronary artery disease management in hospital-based programs.
- Infectious Diseases:FDG-PET for occult infection localization and treatment monitoring addresses antibiotic stewardship priorities.
Oncology dominates procedure volume. Neurology is where platform differentiation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States deploy photon-counting platforms for theranostics workflows, while German hospitals emphasize hybrid PET/CT standardization and Japanese institutions prioritize neurology applications with PET/MRI configurations.
United States
Medicare reimbursement for PET-directed biopsies and lutetium-177 therapy planning concentrates capital allocation in academic medical centers. The FDA's 21st Century Cures Act accelerates radiopharmaceutical approvals, compressing procurement timelines for theranostics-capable systems. Major installations cluster in Boston, Houston, and the Research Triangle.
Germany
National health system standardization for radiotherapy planning drives hybrid PET/CT fleet expansion across university hospitals. EMA Medical Device Regulation enforcement tightens software validation requirements for AI-assisted reconstruction algorithms. Munich and Heidelberg anchor detector technology development clusters.
Japan
Aging demographics expand dementia imaging volume for amyloid and tau PET tracers in neurology departments. PMDA regulatory pathways govern radiopharmaceutical IND submissions alongside METI industrial standards for semiconductor detector manufacturing. Osaka and Tokyo concentrate pediatric oncology PET/MRI installations.
China
Domestic equipment procurement policies favor local manufacturers for hospital infrastructure modernization under national health reform programs. NMPA device registration requirements and dual carbon energy efficiency targets shape detector technology selection criteria. Shanghai and Beijing lead photon-counting platform validation partnerships.
United Kingdom
NHS England cancer strategy mandates PET/CT availability for staging pathways, directing capital toward digital detector replacements. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR conformity timelines for software-heavy platforms. London and Manchester dominate theranostics service development.
PET Imaging Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with consolidated detector intellectual property holdings distinguishing premium positioning from volume-oriented configurations. Siemens Healthineers and GE Healthcare anchor the upper tier through proprietary digital architectures and theranostics integration, while mid-scale Asian manufacturers compete on acquisition cost for emerging market access. Strategic archetypes separate full-platform integrators, component specialists, and regional system assemblers. Competitive moves concentrate on radiopharmaceutical synthesis module partnerships and service contract unbundling.
Among diversified health technology conglomerates, GE Healthcare and Siemens Healthineers occupy positions defined by detector technology ownership and integrated theranostics workflows, while Koninklijke Philips N.V. exemplifies the ambulatory partnership model extending PET access beyond academic centers. United Imaging Healthcare Co., Ltd. represents the scale-driven domestic Chinese tier competing on procurement policy alignment. Canon Medical Systems Corporation and Shimadzu Corporation anchor Japanese precision equipment specialization.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| United Imaging Healthcare Co., Ltd. |
| Bruker |
| Mediso Ltd. |
| MinFound Medical Systems Co., Ltd. |
| Shimadzu Corporation |
| Others |
Value Network & Pricing Analysis
Detector crystal manufacturing scale economies in Japan and Germany concentrate supply among three qualified growers, compressing price floors for lutetium oxyorthosilicate arrays while elevating premiums for photon-counting semiconductor alternatives. Academic medical centers absorb these cost structures through bundled service contracts that unbundle preventive maintenance from software subscriptions.
Pricing Analysis
Long-term offtake agreements dominate capital equipment procurement, with United States academic medical centers locking five-year service tiers against photon-counting platform investments. Price differentiation rests on detector architecture certification and CMS reimbursement tier alignment, with digital platforms commanding premiums where shorter scan times justify staffing cost offsets. Cost compression in conventional time-of-flight systems is intensifying because Asian manufacturers compete on acquisition cost for emerging market access. Community hospitals exhibit highest price sensitivity, while integrated delivery networks prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Extended lead times for cadmium-zinc-telluride wafers and silicon photomultiplier arrays stretch eighteen to twenty-four months, constraining photon-counting platform rollout velocity. Manufacturing concentrates in Japan, Germany, and the United States for scintillation crystals and semiconductor detectors, with China scaling domestic production under NMPA localization policies. Supply chain vulnerability centers on single-source dependencies for lutetium oxyorthosilicate ingot growth. Distribution runs through direct vendor-hospital contracting for premium platforms and regional distributor networks for mid-tier configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET imaging systems sit in early-cycle expansion as theranostics integration and photon-counting validation create dual adoption tailwinds for hybrid platform procurement.
For Market Incumbents: Consolidate detector intellectual property positions through exclusive crystal growth partnerships and proprietary semiconductor foundry arrangements. Lock academic medical center relationships via integrated theranostics workflows before reimbursement codes stabilize. Vertical integration into automated radiochemistry modules addresses technologist scarcity while raising switching costs for installed base retention.
For New Entrants and Emerging Players: Anchor in ambulatory imaging partnerships and mobile scanner deployments that extend PET access beyond major academic centers. White-space concentrates in community oncology settings and pediatric neurology clinics lacking capital depth for multi-scanner fleets. Service-based revenue models with uptime guarantees penetrate price-sensitive segments faster than capital sales approaches.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with unbundled software subscription tiers and preventive maintenance contracts. Long-term viability favors platforms with validated photon-counting clinical economics and CMS reimbursement pathway clarity. Acquisition targets should demonstrate installed base density in United States academic medical centers with theranostics capability. The signal to watch is CMS coverage determination timing for photon-counting versus conventional PET acquisitions.
| Strategic Initiative | Industry Significance |
|---|---|
| Detector IP Consolidation | Exclusive lutetium crystal supply agreements lock Siemens and GE into premium positioning against Asian cost competitors. |
| Theranostics Platform Integration | Diagnostic PET compatibility with lutetium-177 therapy planning compresses hospital procurement cycles under FDA accelerated pathways. |
| Ambulatory Partnership Expansion | Philips mobile scanner deployments extend PET access to community oncology settings previously dependent on academic referrals. |
| Automated Radiochemistry Investment | Synthesis module integration addresses NRC technologist certification constraints while enabling same-day scheduling flexibility. |
| Service Contract Unbundling | À la carte preventive maintenance tiers respond to integrated delivery network resistance against bundled software pricing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with nuclear medicine technologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and NRC certification standards. Bottom-up scanner shipment estimates triangulated against top-down capital expenditure surveys across United States academic medical centers and German university hospitals.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, end user, detector technology, and clinical application, with theranostics capability treated as a cross-cutting demand accelerant. CAGRs derived from installed base replacement cycles, radiopharmaceutical pipeline progression under FDA's 21st Century Cures Act, and CMS coverage determination timelines for photon-counting acquisitions. Forecast inputs incorporated nuclear medicine technologist training pipeline constraints and lutetium oxyorthosilicate crystal supply elasticity.
Decision-makers should treat outputs as directional under assumptions of stable Medicare reimbursement policy and continued FDA radiopharmaceutical acceleration; material deviation in CMS photon-counting coverage or NRC workforce certification standards would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
North America Image Sensors Market
Imaging
IP Camera Market
Imaging
Facial Recognition Machine Market
Imaging
Latin America IP Camera Market
Imaging
Middle East and Africa Hyperspectral Imaging Systems Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Thermal Imaging Market
Imaging
Industrial Camera Market
Imaging
Sub-Micrometer Computed Tomography Market
Imaging
SDI Camera Market
Imaging
Acoustic Microscopy Market
Imaging
Multimodal Imaging Market
Imaging
Video Capture Card Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Handheld Retinal Scanners Market
Imaging
Silent Scan Technology Market