
 Asia-Pacific Surgical Visualization Products Market | 2026-2036
Asia-Pacific Surgical Visualization Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Surgical Visualization Products Market Outlook
Japan's PMDA revised software-as-medical-device guidelines in 2023, a regulatory inflection that is repositioning the cost-of-entry calculus for visualization software developers. Olympus Corporation leverages its domestic manufacturing footprint to sustain rapid regulatory turnaround. Stryker anchors its Asia-Pacific presence through specialized endoscope servicing networks across Australian and South Korean hospitals. Smith & Nephew differentiates via high-definition arthroscopy systems tailored to sports medicine demand in Singapore and Malaysia.
Asia-Pacific surgical visualization products encompass endoscopes, imaging systems, visualization software, and surgical displays engineered to transmit, process, and render real-time anatomical imagery during operative procedures, typically operating at 1080p to 4K resolution with latency below 40 milliseconds to preserve surgical precision. These systems serve primarily to extend visual access through minimally invasive ports while reducing tissue trauma and operative duration. Endoscopes retain the largest installed base across the region, though augmented reality modules represent the fastest-expanding technology segment as Japanese and South Korean teaching hospitals integrate holographic navigation. Visualization software commands disproportionate margin pools relative to hardware due to recurring license structures and regulatory update dependencies.
China's NMPA, Japan's PMDA, and Australia's TGA collectively enforce divergent electromagnetic compatibility and biocompatibility standards that fragment product certification pathways and extend time-to-market for multinational manufacturers. India's CDSCO has accelerated medical device rule harmonization with ASEAN technical reference standards, easing import pathways for Korean and Japanese suppliers. Stakeholders must monitor which regulatory body first mandates AI-assisted image interpretation standards, as this jurisdiction will likely set the template for regional compliance convergence.
Market Dynamics
Japan's PMDA software-as-medical-device guideline revision in 2023 is compressing time-to-market timelines for visualization software developers while simultaneously elevating compliance costs, forcing regional players to restructure R&D footprints around domestic clinical validation requirements.
Growth Catalysts
- Laparoscopic procedure volumes:Hospital surgical departments across India are expanding minimally invasive suites, creating hardware refresh cycles for endoscope and imaging system suppliers.
- CDSCO-ASEAN harmonization:India's medical device regulator has aligned technical reference standards with ASEAN frameworks, reducing import documentation burdens for Korean and Japanese manufacturers.
- Augmented reality modules:Teaching hospitals in South Korea and Japan are integrating holographic navigation overlays into existing visualization stacks, expanding the addressable software market.
Market Restraints
- Electromagnetic compatibility fragmentation:Divergent EMC testing requirements across China's NMPA, Japan's PMDA, and Australia's TGA force redundant certification cycles that extend product launch timelines by twelve to eighteen months.
- Display panel supply concentration:Premium surgical monitor panels concentrate among three Korean and Taiwanese component suppliers, exposing finished goods manufacturers to allocation risk during semiconductor demand surges.
- Biocompatibility material costs:Medical-grade polymers for endoscope housings face price volatility tied to specialty chemical feedstock availability.
Strategic Opportunities
- Secondary city hospital penetration:China's tier-two and tier-three municipal hospital networks remain underpenetrated for 4K visualization systems, offering volume expansion outside saturated Beijing and Shanghai procurement pools.
- AI-assisted image interpretation:The first regional regulator to mandate AI diagnostic overlays will establish the compliance template that competitors must follow, creating first-mover advantage for pre-positioned software developers.
- Subscription software licensing:Visualization software vendors are migrating from perpetual licenses to recurring revenue models, capturing margin pools through regulatory update dependencies and feature expansion.
Industry Challenges
- Legacy system integration:Japanese tertiary hospitals operate aging PACS infrastructure that requires costly middleware development to interface with modern 4K visualization hardware.
- Specialized technician scarcity:Endoscope repair and calibration expertise concentrates among a limited pool of factory-trained service engineers, constraining aftermarket service expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Surgical Visualization Products Market |
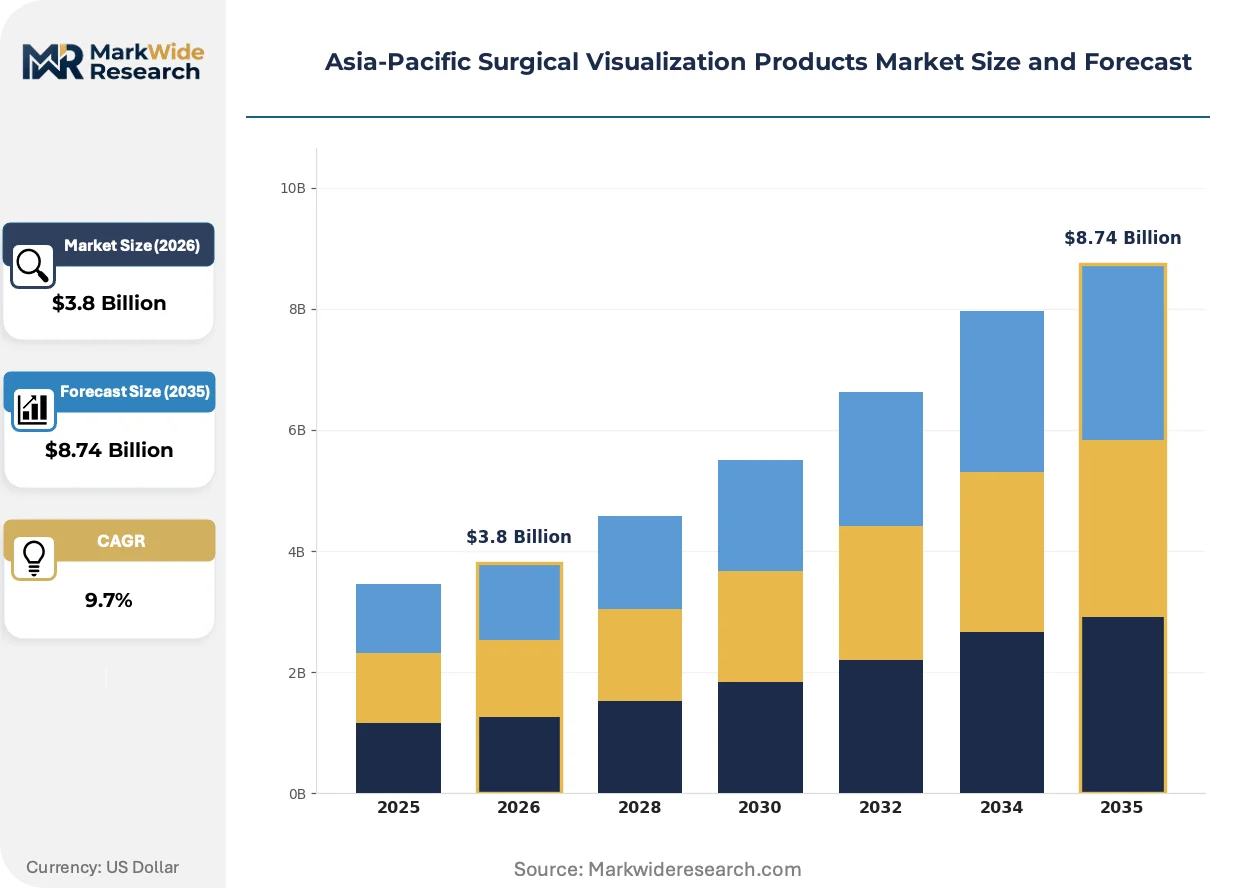
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Imaging Systems, Visualization Software, Surgical Displays Application: Minimally Invasive Surgery, Diagnostics, Education, Surgical Training Technology: 3D Imaging, Video Integration, High Definition, Augmented Reality End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions |
| Companies Covered | Boston Scientific Corporation, FUJIFILM Asia Pacific Pte. Ltd., Stryker, Olympus Corporation, HOYA Corporation, Smith & Nephew, Alcon Inc., KARL STORZ, GE Healthcare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Surgical Visualization Products Market Strategic Shifts
Holographic navigation overlays are penetrating Asia-Pacific teaching hospitals at accelerating pace, while regulatory software classification frameworks are forcing business model restructuring across the visualization value chain.
4K imaging systems is converging with augmented reality spatial computing platforms to enable real-time anatomical projection during laparoscopic procedures. Tertiary surgical centers in Osaka and Seoul are piloting these integrated stacks for complex hepatobiliary operations. The convergence is compressing the traditional hardware-software boundary, forcing vendors to restructure development teams around unified product architectures rather than discrete device categories.
Japan's PMDA revised its SaMD guidance to require continuous post-market surveillance for AI-enabled visualization features. The industrial consequence elevates ongoing compliance costs for software developers while creating regulatory moats against smaller competitors. South Korean manufacturers are responding by establishing captive clinical validation facilities in Tokyo to accelerate turnaround on software updates.
Hospital procurement committees are unbundling after-sales service contracts from hardware purchases, shifting toward multi-vendor maintenance agreements managed by third-party clinical engineering firms. This pattern disrupts the traditional lock-in model that visualization manufacturers relied upon for recurring revenue. The shift is most visible in Singapore's public hospital cluster, where centralized procurement has standardized service vendor qualification criteria across previously siloed departments.
Asia-Pacific Surgical Visualization Products Market Segmentation
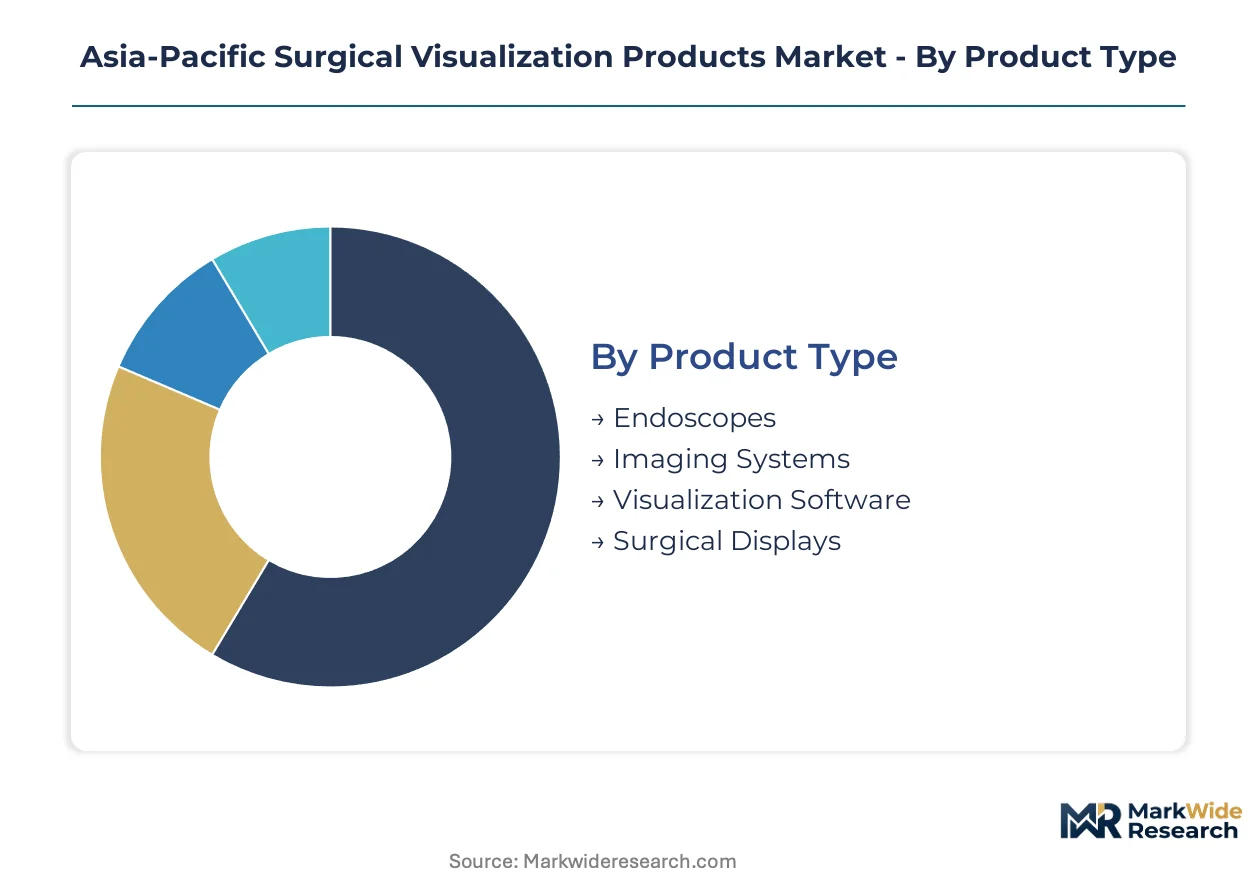
Product architecture, clinical workflow integration, and capital deployment cycles fragment the Asia-Pacific surgical visualization landscape into distinct procurement tiers. Each segmentation dimension carries divergent margin profiles and regulatory exposure, reshaping how vendors structure their regional go-to-market strategies.
Product Type:
Hospital capital committees weight upfront hardware investment against recurring software licensing obligations when allocating procurement budgets across visualization portfolios.
- Endoscopes:Fiber-optic and video endoscopes constitute the foundational visualization hardware with rigid, flexible, and capsule variants serving distinct anatomical access requirements. Japan's tertiary hospital network sustains replacement demand as aging Olympus and Pentax installed bases reach end-of-life cycles.
- Imaging Systems:Camera control units, light sources, and image processors operate at 1080p through 4K resolution with sub-40 millisecond latency specifications. Chinese municipal hospitals in tier-two cities are refreshing legacy standard-definition stacks, creating volume concentration outside saturated Beijing procurement pools.
- Visualization Software:Image processing algorithms, PACS integration modules, and AI-assisted diagnostic overlays command recurring license structures. PMDA's 2023 SaMD guidance elevates compliance costs while creating regulatory moats against smaller competitors.
- Surgical Displays:Medical-grade monitors with brightness calibration and color consistency protocols complete the visualization chain. Panel supply concentrates among Korean and Taiwanese component suppliers, exposing finished goods manufacturers to allocation risk.
Volume sits with endoscopes; growth tilts toward visualization software.
Application:
Clinical use case determines performance specification thresholds and reimbursement pathway alignment across national health systems.
- Minimally Invasive Surgery:Laparoscopic, arthroscopic, and endoscopic procedures demand real-time anatomical rendering with minimal motion artifact. Indian hospital surgical departments are expanding MIS suites, creating hardware refresh cycles for endoscope and imaging system suppliers.
- Diagnostics:Endoscopic biopsy and screening protocols prioritize image clarity for histopathological correlation. Japan's aging demographic sustains colorectal and gastric cancer screening volumes through national insurance reimbursement.
- Education:Teaching hospital networks require multi-view broadcasting and recording capabilities for surgical observation. South Korean academic medical centers are integrating holographic navigation overlays into existing visualization stacks.
- Surgical Training:Simulation environments and recorded case libraries support resident skill acquisition. Singapore's centralized public hospital procurement has standardized training infrastructure qualification criteria across previously siloed departments.
Revenue concentrates in minimally invasive surgery; education applications are expanding most quickly.
Technology:
Resolution tier and spatial computing capability stratify pricing architecture and integration complexity for hospital IT departments.
- 3D Imaging:Stereoscopic visualization systems render depth perception for complex laparoscopic suturing and dissection. Australian teaching hospitals are piloting 3D stacks for hepatobiliary operations.
- Video Integration:Multi-source routing and picture-in-picture compositing enable simultaneous endoscope and ultrasound display. Legacy PACS infrastructure in Japanese tertiary hospitals requires costly middleware development for interoperability.
- High Definition:1080p and 4K resolution standards dominate current installed bases with established reimbursement pathways. China's NMPA tightened imaging device registration rules, forcing manufacturers to localize clinical validation for 4K system approvals.
- Augmented Reality:Holographic navigation overlays project preoperative imaging onto live surgical fields. Osaka and Seoul tertiary centers are piloting AR-integrated stacks, representing the steepest expansion trajectory in the technology portfolio.
High definition captures current volume; augmented reality commands forward investment.
End User:
Capital availability and procedure volume density determine specification tier and service contract structure across facility types.
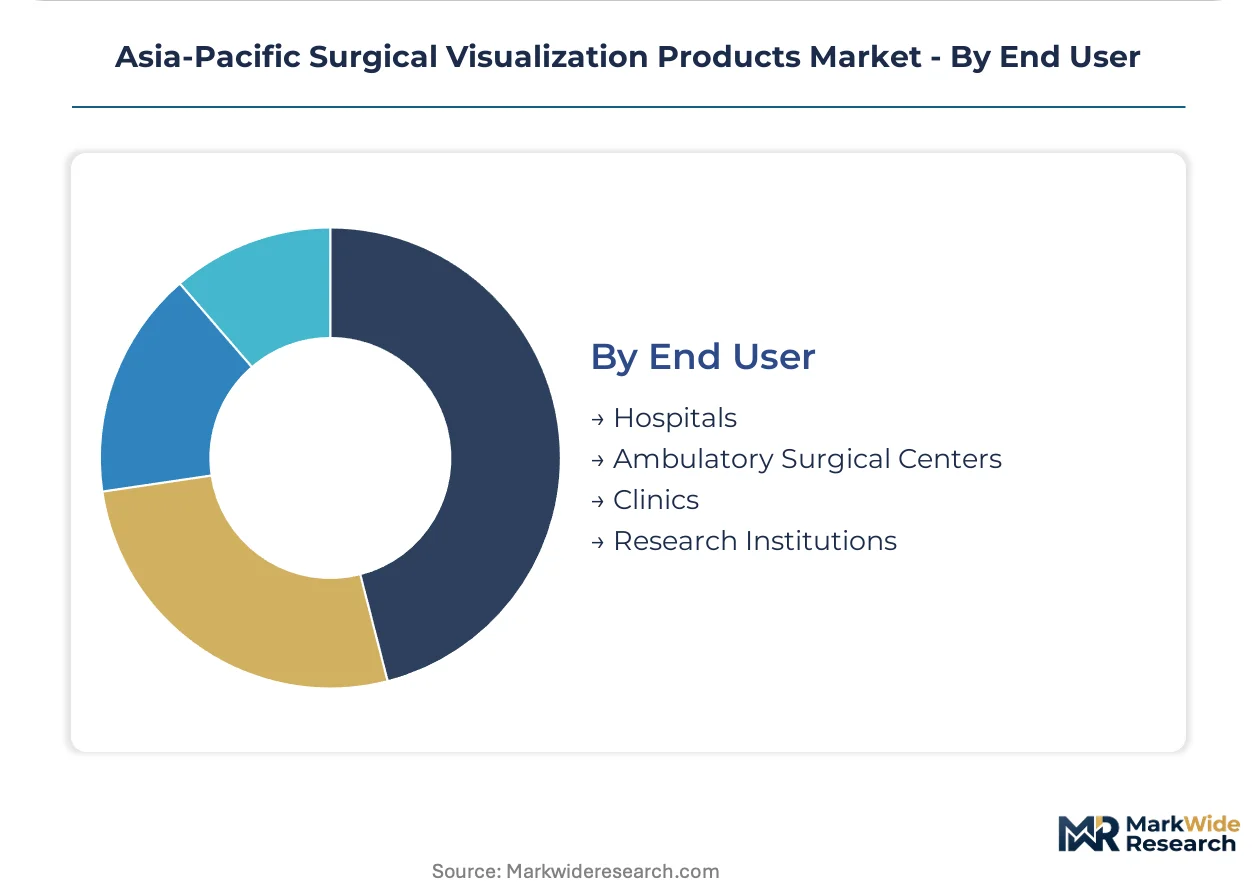
- Hospitals:Tertiary and secondary acute care facilities operate the majority of installed visualization systems with comprehensive service agreements. Australia's TGA enforces electromagnetic compatibility standards that extend product launch timelines for multinational suppliers.
- Ambulatory Surgical Centers:Freestanding procedure facilities prioritize compact, mobile visualization configurations for high-throughput cataract and arthroscopy cases. Malaysian and Thai ASC networks are expanding outpatient MIS capacity.
- Clinics:Specialist diagnostic and minor procedure settings deploy flexible endoscope systems with simplified processing workflows. India's CDSCO-ASEAN harmonization reduces import documentation burdens for Korean and Japanese manufacturers serving clinic segments.
- Research Institutions:Academic and translational research centers drive early adoption of experimental imaging modalities. South Korean manufacturers are establishing captive clinical validation facilities in Tokyo to accelerate software update turnaround for research partnerships.
Procurement volume aggregates in hospitals; research institutions set technology direction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port and South Korea's Incheon Free Economic Zone are concentrating surgical visualization manufacturing investment through duty exemptions and streamlined customs processing for medical device components.
China
Secondary city hospital networks in Chengdu and Wuhan are driving 4K imaging system procurement as municipal health bureaus modernize surgical suites outside saturated Beijing and Shanghai markets. NMPA tightened imaging device registration rules in 2023, forcing manufacturers to localize clinical validation for product approvals. The Yangtze River Delta cluster around Shanghai hosts concentrated endoscope assembly operations serving domestic replacement demand.
Japan
Aging PACS infrastructure across tertiary hospitals in Osaka and Nagoya is forcing costly middleware development to interface with modern 4K visualization hardware. PMDA revised software-as-medical-device guidelines in 2023, compressing time-to-market timelines while elevating compliance costs for visualization software developers. Tokyo's Kanto region anchors domestic manufacturing footprints that sustain rapid regulatory turnaround for regional players.
India
Laparoscopic procedure volumes are expanding across hospital surgical departments in Mumbai and Delhi, creating hardware refresh cycles for endoscope and imaging system suppliers. CDSCO accelerated medical device rule harmonization with ASEAN technical reference standards, easing import pathways for Korean and Japanese suppliers. Maharashtra's Mumbai-Pune corridor concentrates private hospital chain procurement committees driving minimally invasive suite expansion.
South Korea
Teaching hospitals in Seoul are integrating holographic navigation overlays into existing visualization stacks, expanding the addressable software market for augmented reality modules. MFDS maintains electromagnetic compatibility standards aligned with international frameworks, reducing redundant certification burdens for domestic manufacturers. The Seoul Capital Area hosts academic medical centers piloting AR-integrated stacks for complex hepatobiliary operations.
Australia
Specialized endoscope servicing networks anchor aftermarket presence across Sydney and Melbourne hospital systems, sustaining recurring revenue streams for visualization hardware suppliers. TGA enforces electromagnetic compatibility standards that extend product launch timelines for multinational manufacturers. New South Wales hosts tertiary teaching hospitals piloting 3D imaging stacks for hepatobiliary surgical training programs.
Asia-Pacific Surgical Visualization Products Market Competitive Environment
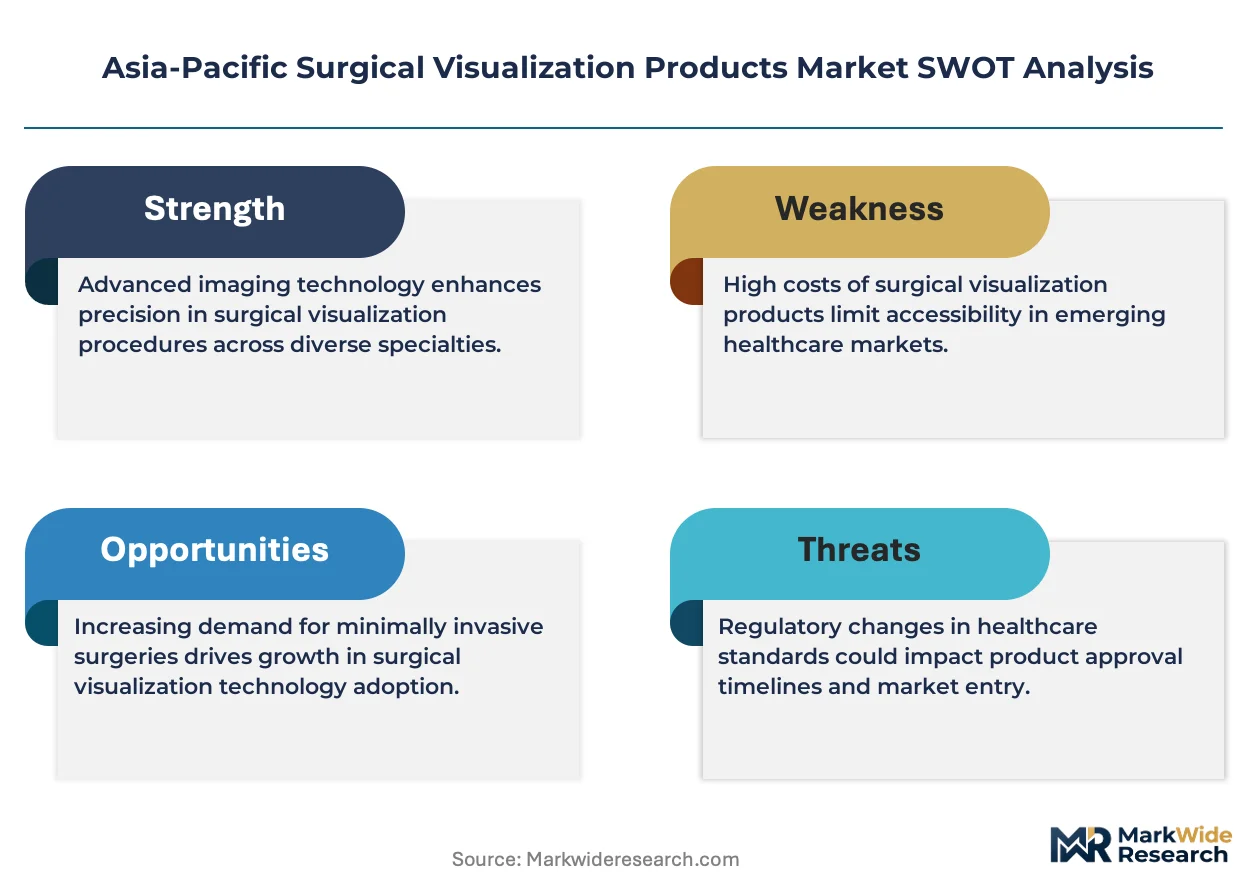
Diversified conglomerates compete with focused pure-play specialists across the Asia-Pacific surgical visualization landscape. The market structure tilts toward consolidation among established medical device conglomerates with endoscope manufacturing heritage, while software-focused entrants face elevated regulatory barriers. Three archetypes dominate: diversified imaging conglomerates with captive supply chains, specialized endoscope manufacturers with deep servicing networks, and software developers restructuring around subscription licensing models. Competitive dynamics center on regulatory turnaround speed and aftermarket service contract capture.
Among diversified imaging conglomerates, Olympus Corporation and FUJIFILM Asia Pacific Pte. Ltd. occupy positions exemplifying domestic manufacturing footprint advantages in Japan. Stryker represents the specialized servicing network archetype, anchoring regional presence through clinical engineering relationships. These three entities illustrate how scale and regulatory proximity reshape competitive positioning across divergent national approval pathways.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| FUJIFILM Asia Pacific Pte. Ltd. |
| Stryker |
| Olympus Corporation |
| HOYA Corporation |
| Smith & Nephew |
| Alcon Inc. |
| KARL STORZ |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Japan's METI carbon neutrality roadmap for medical device manufacturing gates qualified supply access and premium-tier pricing eligibility for surgical visualization producers seeking procurement contracts with tertiary hospital networks across the Asia-Pacific region.
Pricing Analysis
Short lead-time premiums command pricing separation from spot inventory discounts across surgical visualization procurement cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by PMDA certification grade and bundled after-sales service scope. Cost compression in economy-tier imaging systems is intensifying because Chinese municipal hospitals consolidate volume purchasing through provincial procurement platforms. Ambulatory surgical centers in Malaysia and Thailand exhibit highest price sensitivity; Japanese teaching hospitals demonstrate lowest sensitivity due to reimbursement-aligned capital budgets.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from hospital system GPOs, while specialized distributors serve clinic and ASC segments with lower volume thresholds. Panel supply concentrates in South Korea and Taiwan; endoscope assembly clusters center on Japan's Kanto region and China's Yangtze River Delta. Medical-grade polymers for endoscope housings, precision optical glass for lens systems, and semiconductor image sensors constitute critical input dependencies. Single-source vulnerability in Korean and Taiwanese display panel suppliers exposes finished goods manufacturers to allocation risk during semiconductor demand surges. Distribution runs through authorized service networks for regulatory compliance maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around regulatory compliance scale as PMDA's software-as-medical-device guidance forces subscale developers toward acquisition or exit.
For Market Incumbents: To counter holographic navigation overlay entrants from South Korean software developers, deepen backward integration into medical-grade polymer supply and establish captive clinical validation facilities in Tokyo to compress regulatory turnaround timelines for AI-enabled visualization features. For New Entrants and Emerging Players: Begin with China's tier-two municipal hospital networks in Chengdu and Wuhan, where 4K imaging system penetration remains below Beijing and Shanghai saturation levels, and pursue software-only licensing models to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: PMDA's first-mover mandate on AI-assisted image interpretation standards is the leading indicator that software-focused targets with pre-positioned compliance infrastructure will command acquisition premiums; prioritize developers with established Tokyo validation partnerships and recurring license revenue architecture over hardware-dependent manufacturers across a long-term viability window.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA SaMD Compliance Investment | Establishes regulatory moats against subscale competitors in Japan's visualization software segment. |
| Captive Clinical Validation Facility | Accelerates software update turnaround for South Korean manufacturers serving Japanese teaching hospitals. |
| Secondary City Hospital Penetration | Captures volume expansion outside saturated Beijing and Shanghai procurement pools in China's tier-two networks. |
| Subscription Licensing Migration | Captures margin pools through regulatory update dependencies and feature expansion in visualization software. |
| Specialized Servicing Network Expansion | Anchors aftermarket presence across Australian and South Korean hospital systems for hardware suppliers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific surgical visualization products market assessment. Primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at visualization device manufacturers combined with secondary validation from PMDA guidance documents, NMPA registration databases, CDSCO harmonization circulars, and customs import records. Bottom-up installed base modeling and top-down healthcare capital expenditure triangulation reconciled volume estimates.
Data-stream reconciliation across product type, application, technology tier, resolution specification, and end-user facility scale produced segmented forecasts across the projection horizon. CAGRs derived from procedure volume growth correlations, replacement cycle analysis, and regulatory approval timeline assumptions. AI-enabled feature penetration rates and holographic navigation overlay adoption curves in Japanese and South Korean teaching hospitals served as technology-specific forecast inputs.
Underlying measurement precision varies by segment; high-definition imaging systems carry tighter precision than augmented reality modules where pilot deployment data remains sparse. Forecasts reflect assumptions regarding regulatory harmonization progress, semiconductor supply stabilization, and hospital capital budget trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Neurology Ultrasonic Aspirators Market
Medical Devices
Laser Therapy Devices Market
Medical Devices
Global Interventional Neurology Devices Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Global Cryotherapy Market
Medical Devices
Epilepsy Treatment Devices Market
Medical Devices
Soft Tissue Market
Medical Devices
United Kingdom Drug Delivery Devices Market
Medical Devices
Clear Aligners Market
Medical Devices
Bandage Contact Lenses Market
Medical Devices
Prefilled Glass Syringes Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Vascular Boot Market
Medical Devices
Cryoablation System Market