
 US Gadolinium-Based Contrast Media Market | 2026-2036
US Gadolinium-Based Contrast Media Market Size, Share, and Industry Trends Forecast 2026-2036
US Gadolinium-Based Contrast Media Market Intelligence
Hospital procurement consortiums is rewriting how contrast media contracts are negotiated across integrated delivery networks. Bayer AG leverages its vertically integrated pharmaceutical manufacturing to sustain volume commitments with large health systems. GE Healthcare anchors its position through direct equipment-contrast bundling with MRI installations. Bracco Diagnostic, Inc. competes on specialized formulations for high-field 3 Tesla scanners.
Gadolinium-based contrast media comprises paramagnetic chelate compounds containing gadolinium ions, formulated with ligand structures such as macrocyclic or linear architectures to enhance proton relaxation in magnetic resonance imaging. These agents shorten T1 relaxation times in tissues, producing positive contrast enhancement that enables radiologists to distinguish pathological from normal anatomy. Intravenous gadolinium dominates current utilization due to its established efficacy in vascular and oncologic imaging, while gadobutrol formulations command premium positioning in cardiac and neuroimaging protocols. Magnetic resonance imaging applications absorb the largest share of volume, though oncology represents the fastest-expanding indication as precision staging requirements intensify.
The FDA governs premarket approval and post-market surveillance of gadolinium agents through its Center for Drug Evaluation and Research, while the American College of Radiology maintains practice parameters that directly influence institutional purchasing decisions. State-level pharmacy boards and hospital formulary committees layer additional constraints on agent selection, particularly regarding macrocyclic versus linear chelate preferences. Stakeholders must track evolving retention risk labeling and reimbursement alignment between contrast-enhanced MRI and competing modalities such as PET-CT.
Market Dynamics
FDA's ongoing review of gadolinium retention in brain tissue is compressing formulary preferences toward macrocyclic chelate architectures, forcing manufacturers to restructure clinical trial portfolios and relabeling strategies around deposition risk profiles.
Growth Catalysts
- Oncology Imaging Intensification:Precision staging requirements at academic medical centers are expanding gadolinium-enhanced MRI protocols for tumor characterization and treatment monitoring.
- Cardiac MRI Protocol Expansion:Gadobutrol formulations are gaining traction in cardiac imaging suites as non-invasive alternatives to catheter-based angiography for ventricular function assessment.
- Integrated Delivery Network Consolidation:Hospital procurement consortiums across the Northeast corridor are standardizing contrast media contracts to secure volume pricing and supply security.
Market Restraints
- Gadolinium Retention Liability:Linear chelate agents face escalating safety scrutiny from the FDA's Center for Drug Evaluation and Research, restricting their use in pediatric and renal-impaired populations.
- Raw Material Concentration:Rare earth processing for pharmaceutical-grade gadolinium concentrates in limited overseas refining facilities, exposing supply chains to geopolitical disruption.
- Substitute Modality Competition:PET-CT systems with novel radiotracers are displacing contrast-enhanced MRI in certain oncologic staging applications where metabolic activity mapping proves superior.
Strategic Opportunities
- Macrocyclic Formulation Premiumization:Safety-profile differentiation around gadolinium deposition creates pricing power for macrocyclic architectures in neuroimaging protocols.
- Equipment-Contrast Bundling:MRI scanner manufacturers can deepen installed base loyalty through captive supply agreements for contrast media replenishment.
- Outpatient Imaging Center Penetration:Freestanding diagnostic facilities in Texas and Florida represent underpenetrated channels beyond traditional hospital networks.
Industry Challenges
- Formulary Committee Navigation:Hospital pharmacy and therapeutics committees impose multi-layered review cycles for new agent adoption, extending sales cycles by 12-18 months.
- Legacy System Integration:Contrast injector compatibility with existing MRI suites requires expensive retrofitting or complete replacement of power injector fleets.
- Retention Study Documentation:Post-market surveillance obligations for deposition data collection strain pharmacovigilance resources and delay label expansion submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Gadolinium-Based Contrast Media Market |
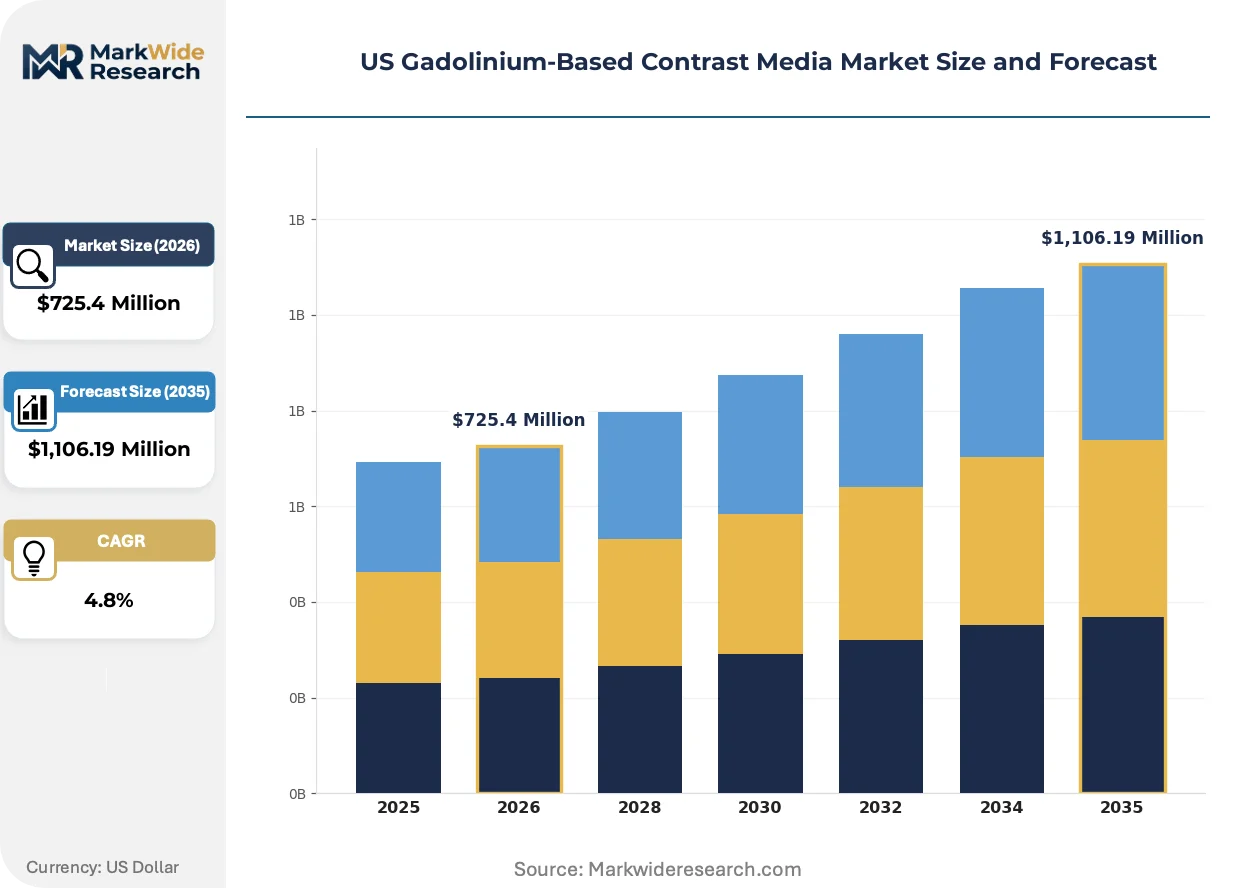
| Market Size in 2026 | $725.4 Million |
| Market Size in 2035 | $1,106.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intravenous Gadolinium, Oral Gadolinium, Gadobutrol, Gadopentetate Application: Magnetic Resonance Imaging, Interventional Procedures, Oncology, Neurology Delivery Mode: Injectable, Infusion, Diagnostic Kit, Single-Dose Vials End User: Hospitals, Imaging Centers, Research Institutes, Outpatient Clinics |
| Companies Covered | Bayer AG, GE Healthcare, Bracco Diagnostic, Inc., Guerbet, Lantheus Medical Imaging, Inc., Trivitron Healthcare, Nano Therapeutics Pvt. Ltd., CMC Contrast AB, IMAX Diagnostic Imaging, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Gadolinium-Based Contrast Media Market Strategic Shifts & Innovations
Formulation chemistry and procurement architecture are undergoing parallel transformation as safety evidence and buyer concentration reshape competitive positioning in contrast media.
Macrocyclic gadolinium chelates are displacing linear architectures in neuroimaging protocols due to their kinetic stability and reduced tissue deposition risk. Academic medical centers in Boston and New York metropolitan networks are migrating from linear to macrocyclic agents for all non-urgent brain imaging. This shift is compressing margins on legacy linear formulations while creating volume premiums for macrocyclic suppliers with validated retention data.
The FDA's retention risk labeling requirements are forcing manufacturers to fund long-term deposition studies across pediatric and adult cohorts. This regulatory friction is elevating compliance costs and extending approval timelines for new molecular entities. High-field 3 Tesla scanner installations are most affected, as these systems amplify signal from even trace retained gadolinium, intensifying radiologist scrutiny of agent selection.
Hospital procurement consortiums are consolidating contrast media purchasing across integrated delivery networks, displacing individual hospital formulary autonomy. Group purchasing organizations now negotiate multi-year supply agreements with penalty clauses for volume shortfalls. This concentration is most visible in the Northeast corridor, where Boston and New York hospital systems have standardized on single-source macrocyclic contracts with direct-to-site distribution.
US Gadolinium-Based Contrast Media Market Segmentation
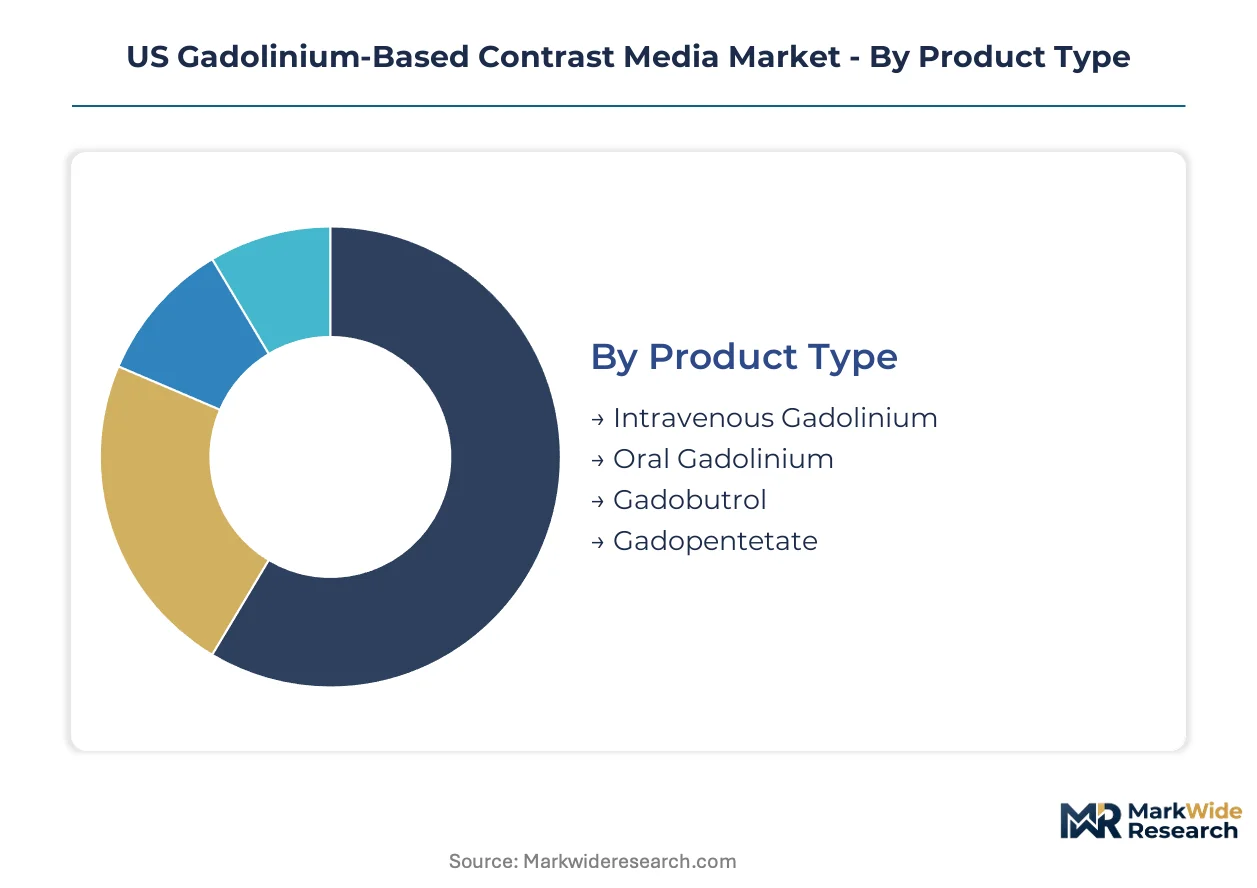
Segmentation in the US gadolinium-based contrast media market reveals how clinical protocols, procurement economics, and safety profiles intersect to determine product selection. Understanding these dimensions helps stakeholders anticipate formulary shifts and channel migration across the forecast window.
Product Type:
Mature intravenous formulations dominate current utilization while newer macrocyclic architectures reshape safety-driven purchasing.
- Intravenous Gadolinium:Linear and macrocyclic chelates administered through peripheral IV access serve as the workhorse for vascular and body imaging. Hospital networks in Boston and New York metropolitan areas concentrate demand here, though FDA retention labeling is compressing linear agent share.
- Gadobutrol:This macrocyclic agent delivers higher gadolinium concentration per milliliter, enabling reduced injection volumes for cardiac and neuroimaging protocols. Academic medical centers migrating to 3 Tesla scanners favor gadobutrol for its kinetic stability and lower deposition risk profile.
- Oral Gadolinium:Enteric formulations for gastrointestinal tract visualization occupy a narrow niche in pelvic and abdominal MRI protocols.
- Gadopentetate:The original linear chelate faces contracting utilization as pharmacy and therapeutics committees restrict its use in pediatric and renal-impaired populations.
Intravenous gadolinium handles the majority of throughput; gadobutrol is expanding most quickly on share as macrocyclic preference hardens.
Application:
Clinical utility spans diagnostic confirmation through interventional guidance, with oncology staging commanding the steepest protocol expansion.
- Oncology:Precision tumor characterization and treatment response monitoring at academic medical centers drive gadolinium-enhanced MRI adoption. The Northeast corridor's integrated delivery networks are standardizing contrast protocols across their cancer centers to ensure staging consistency.
- Magnetic Resonance Imaging:General diagnostic MRI absorbs the largest absolute volume of contrast media, spanning neurologic, musculoskeletal, and abdominal indications. Outpatient imaging centers in Texas and Florida represent underpenetrated volume opportunity for routine MRI enhancement.
- Neurology:Brain and spinal cord imaging demands macrocyclic agents exclusively at leading institutions due to retention risk sensitivity.
- Interventional Procedures:MRI-guided biopsies and thermal ablations require real-time contrast visualization, creating demand for rapid-injection formulations.
Magnetic resonance imaging anchors volume throughput; oncology registers the steepest expansion trajectory as staging requirements intensify.
Delivery Mode:
Administrative efficiency and waste reduction are reshaping packaging preferences across hospital and outpatient settings.
- Injectable:Prefilled syringes and power-injector-compatible vials dominate high-throughput hospital environments where workflow standardization reduces preparation error.
- Single-Dose Vials:Unit-dose packaging eliminates multi-dose vial contamination risk and supports Joint Commission compliance for medication safety.
- Infusion:Extended administration protocols serve specialized cardiac MRI and research applications requiring controlled gadolinium delivery.
- Diagnostic Kit:Co-packaged contrast with saline flushes and injection supplies simplifies procurement for smaller imaging centers.
Injectable formats command the largest share of institutional purchasing; single-dose vials are climbing fastest as safety protocols tighten.
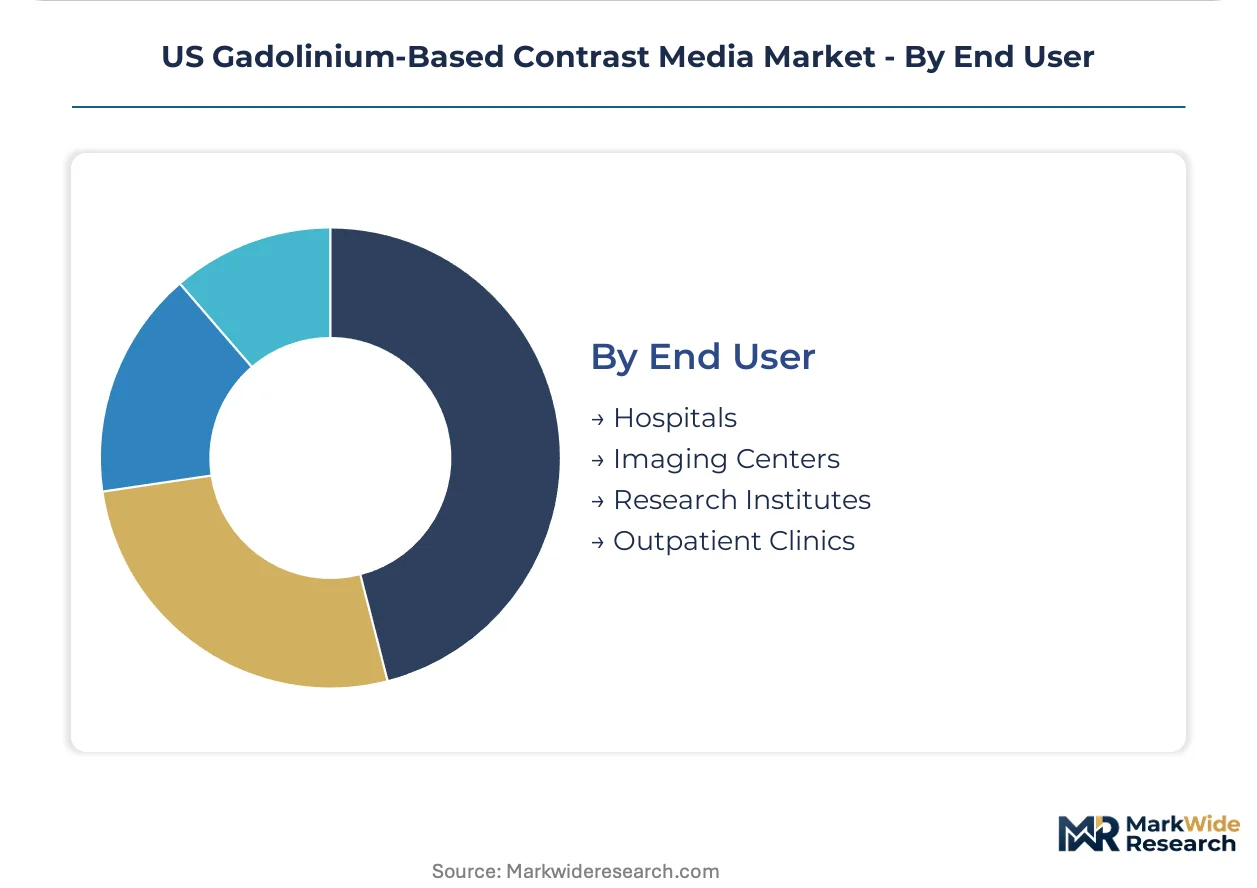
End User:
Channel structure reflects the consolidation of imaging services and the migration of routine MRI to outpatient settings.
- Hospitals:Academic medical centers and community hospital systems in the Northeast corridor concentrate the most sophisticated gadolinium-enhanced protocols. These institutions negotiate multi-year supply agreements through procurement consortiums with volume commitment clauses.
- Imaging Centers:Freestanding diagnostic facilities in Texas and Florida are expanding MRI capacity to capture commercially insured volumes shifting from hospital-based settings.
- Outpatient Clinics:Physician-owned practices and urgent care networks with on-site MRI represent emerging contrast demand as point-of-care imaging proliferates.
- Research Institutes:Clinical trial imaging cores and academic research programs require specialized formulations with documented batch consistency for longitudinal studies.
Hospitals handle the majority of throughput; imaging centers are gaining share fastest as site-of-service economics shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor rail infrastructure and Port of New York and New Jersey distribution networks concentrate pharmaceutical-grade contrast media logistics for the entire US market.
Northeast Corridor
Academic medical centers in Boston and New York metropolitan hospital networks drive macrocyclic agent demand for neuroimaging protocols. FDA retention risk labeling from the Center for Drug Evaluation and Research accelerates formulary shifts away from linear chelates. Massachusetts General Hospital and Memorial Sloan Kettering Cancer Center anchor procurement consortium standardization across integrated delivery networks.
Southeast
Freestanding imaging centers in Florida and Georgia expand MRI capacity to capture commercially insured volumes shifting from hospital-based settings. State pharmacy boards in Florida impose additional constraints on gadolinium agent selection beyond federal requirements. The Miami-Fort Lauderdale corridor concentrates outpatient diagnostic facility construction for cardiac and oncologic imaging.
Texas Triangle
Houston Methodist and MD Anderson Cancer Center systems intensify gadolinium-enhanced MRI protocols for precision oncology staging. Texas state Medicaid reimbursement policies influence contrast media purchasing decisions across safety-net hospitals. The Dallas-Fort Worth metroplex anchors independent imaging center expansion for routine MRI enhancement.
Pacific Coast
UCLA Health and Stanford Medicine systems pioneer 3 Tesla scanner installations requiring high-concentration gadobutrol formulations. California's Office of Statewide Health Planning and Development reviews MRI suite expansion permits with contrast waste disposal requirements. The San Francisco Bay Area concentrates research institute demand for specialized formulations with documented batch consistency.
Midwest
Cleveland Clinic and Mayo Clinic systems standardize contrast protocols across multi-state integrated delivery networks. Illinois state pharmacy regulations govern multi-dose vial usage in hospital settings. The Chicago metropolitan area anchors distribution warehousing for contrast media replenishment throughout the Great Lakes region.
US Gadolinium-Based Contrast Media Market Key Industry Players
On the supply side, the industry is consolidated around vertically integrated pharmaceutical manufacturers and diagnostic imaging equipment producers. Three strategic archetypes dominate: diversified chemical-pharmaceutical conglomerates with captive rare earth processing, imaging equipment manufacturers bundling contrast with scanner installations, and specialized contrast media formulators competing on safety-profile differentiation. M&A activity targets formulation technology assets, while strategic partnerships lock in multi-year supply agreements with procurement consortiums.
Within the diversified pharmaceutical tier, Bayer AG anchors European-origin supply capabilities through its vertically integrated manufacturing infrastructure. GE Healthcare exemplifies equipment-contrast bundling strategies, leveraging MRI scanner installed bases to secure replenishment contracts. Bracco Diagnostic, Inc. occupies a position as a specialized formulator competing on macrocyclic architectures for high-field scanner applications.
| Leading Market Players |
|---|
| Bayer AG |
| GE Healthcare |
| Bracco Diagnostic, Inc. |
| Guerbet |
| Lantheus Medical Imaging, Inc. |
| Trivitron Healthcare |
| Nano Therapeutics Pvt. Ltd. |
| CMC Contrast AB |
| IMAX Diagnostic Imaging |
| Others |
Cost & Logistics Intelligence
Undercapacity in pharmaceutical-grade gadolinium refining facilities outside the United States drives dual behavior: suppliers prioritize long-term offtake contracts with integrated delivery networks while hospital procurement consortiums exploit volume commitments to compress per-dose pricing. This utilization squeeze tightens margins on legacy linear formulations and elevates premiums for macrocyclic agents with validated retention profiles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs institutional purchasing, with macrocyclic gadobutrol formulations commanding premium positioning against linear gadopentetate and economy intravenous alternatives. Price differentiation hinges on FDA retention-risk labeling tier and contract volume scale, with Northeast corridor hospital systems leveraging multi-year agreements for steeper discounts. Cost compression in standard linear tiers is intensifying because pharmacy and therapeutics committees restrict their use in pediatric populations. Outpatient imaging centers in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Boston and New York metropolitan networks prioritize safety-profile differentiation over unit cost.
Supply Chain Analysis
Upstream feedstock for pharmaceutical-grade gadolinium draws from rare earth processing facilities concentrated in China, Malaysia, and limited European refining sites, creating geographic vulnerability to export restriction protocols. Active pharmaceutical ingredient production rests on specialized ligand chemistry inputs and chelation manufacturing equipment sourced from Germany and Japan. Single-source vulnerability in overseas refining exposes US distributors to geopolitical disruption and tariff exposure. Distribution runs through pharmaceutical-grade cold-chain logistics anchored at the Port of New York and New Jersey, with direct-to-site replenishment contracts bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FDA regulatory entrenchment around retention-risk labeling creates formidable switching costs for hospital formulary committees. Incumbents leverage multi-year procurement consortium agreements and equipment-contrast bundling to lock out challengers.
For Market Incumbents: Insulate market position by deepening backward integration into rare earth refining partnerships that secure pharmaceutical-grade gadolinium supply against geopolitical disruption. Expand captive supply agreements with high-field 3 Tesla scanner installations to anchor replenishment contracts. Priority defensive investment targets macrocyclic formulation R&D to extend safety-profile differentiation as FDA labeling requirements tighten.
For New Entrants and Emerging Players: Freestanding outpatient imaging centers in Texas and Florida represent the most penetrable entry point for specialty macrocyclic formulations, as these facilities operate outside integrated delivery network procurement consortiums. Diagnostic kit packaging for smaller imaging centers offers a channel with lower formulary committee friction. Go-to-market execution should emphasize rapid-injection compatibility and saline flush bundling to reduce workflow disruption.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized contrast media formulators with validated macrocyclic retention data and established GPO contracts. Long-term viability over the projection horizon favors acquisition targets with FDA-approved deposition studies and direct distribution infrastructure. The signal to watch as inflection indicator is CMS reimbursement alignment between contrast-enhanced MRI and competing PET-CT modalities.
| Strategic Initiative | Industry Significance |
|---|---|
| Macrocyclic Formulation Development | FDA retention-risk labeling accelerates formulary preference toward kinetic-stable architectures in neuroimaging protocols. |
| Equipment-Contrast Bundling | MRI scanner manufacturers secure installed base loyalty through captive replenishment contracts with hospital systems. |
| Procurement Consortium Penetration | Group purchasing organization standardization in the Northeast corridor locks in multi-year volume commitments. |
| Direct-to-Site Distribution | Bypassing wholesale channels reduces cold-chain breakage and enables just-in-time inventory for high-throughput centers. |
| Post-Market Surveillance Investment | Long-term deposition data collection satisfies FDA pharmacovigilance requirements and supports label expansion submissions. |
Research Approach
Desk research of FDA retention-risk labeling archives, CMS reimbursement databases, and hospital procurement consortium contracts preceded structured interviews with formulary committee directors, GPO contracts managers, radiology department heads, and contrast media manufacturing executives. Primary fieldwork across the Northeast corridor, Texas Triangle, and Pacific Coast markets validated secondary findings on macrocyclic migration patterns. Bottom-up volume modeling triangulated against top-down pharmaceutical manufacturing capacity assessments.
Assumptions held fixed across the modeling period include FDA regulatory trajectory on retention-risk labeling, continued integrated delivery network consolidation pace, and rare earth supply chain geographic concentration. The analytical framework segmented volume and value outputs by product architecture, clinical application, delivery format, and end-user channel. CAGRs derived from institution-level protocol expansion rates weighted by scanner installation forecasts and formulary shift velocity. Industry-specific inputs incorporated power-injector fleet replacement cycles and contrast waste disposal regulatory compliance costs.
Practitioners should monitor FDA Center for Drug Evaluation and Research guidance revisions and CMS site-of-service reimbursement adjustments for early signals of forecast deviation. Material shifts in rare earth export restriction protocols or breakthrough PET-CT radiotracer approvals would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
AI-Assisted Radiology Market
Medical Imaging
Preclinical Ultrasound Systems Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
South America MRI Market
Medical Imaging
Brazil Mammography Market
Medical Imaging
Argentina Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Medical X-Ray Market