
 South Africa Mammography Market | 2026-2036
South Africa Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Mammography Market Analytics
Private hospital chains is collapsing the historical dominance of public-sector tenders as the primary buyer archetype in South Africa's mammography procurement landscape. Hologic Inc. leverages its installed base of digital systems to sustain recurring service revenue across Netcare and Mediclinic facilities. Siemens Healthineers anchors its position through direct technical support infrastructure in Johannesburg and Cape Town. CapeRay Medical (Pty) Ltd competes on localized manufacturing and shorter replacement-part lead times for provincial health departments.
Mammography encompasses X-ray imaging systems designed to detect breast tissue abnormalities, utilizing low-dose ionizing radiation with specialized compression paddles and high-resolution detector arrays to generate diagnostic images for early cancer identification. Digital Mammography dominates current procurement flows due to superior image storage and transmission capabilities, while 3D Mammography captures expanding interest among private diagnostic imaging centers seeking differentiation through tomographic slice resolution. Software Solutions within the technology dimension represents a concentrated margin pool as AI-enhanced image analysis commands premium pricing from facilities prioritizing radiologist workflow efficiency.
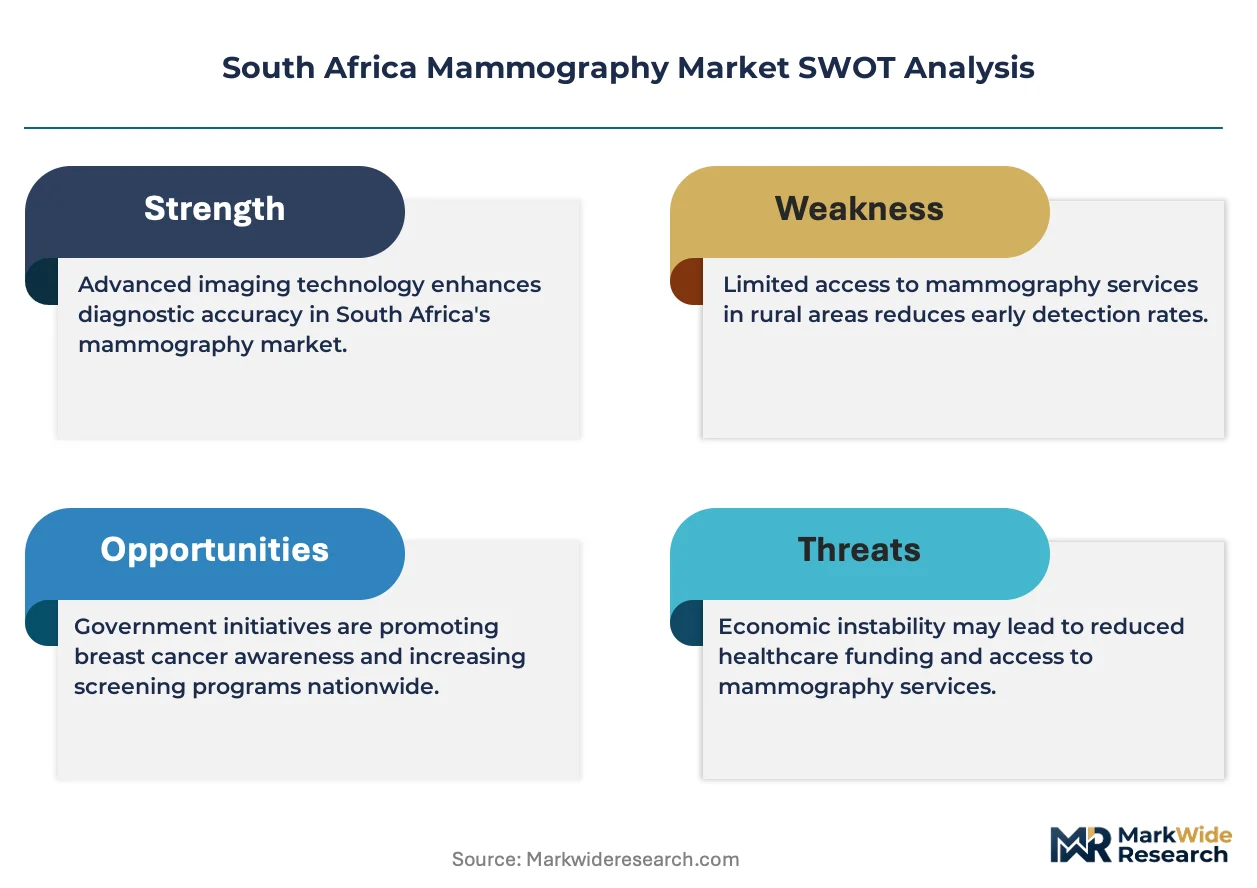
SAHPRA registration requirements and ISO 13485 quality management standards govern device market access, with compliance timelines extending procurement cycles for international manufacturers. The South African Bureau of Standards (SABS) mandates electrical safety and radiation emission protocols that influence product configuration for local deployment. Stakeholders must monitor SAHPRA's evolving software-as-medical-device classification guidelines, which will determine whether AI imaging analysis modules require separate regulatory submission pathways.
Market Dynamics
Private hospital consolidation across Gauteng and Western Cape provinces is restructuring procurement authority away from fragmented public-sector tender boards, concentrating purchasing power within integrated oncology networks that negotiate enterprise-wide equipment and service agreements.
Growth Catalysts
- SAHPRA Registration Pathways:Streamlined medical device approval timelines for digital mammography systems accelerate product launches for manufacturers meeting ISO 13485 standards.
- Urban Oncology Network Expansion:Netcare and Mediclinic facilities are scaling breast cancer screening programs across metropolitan Johannesburg and Cape Town corridors.
- AI-Enhanced Image Analysis:Machine learning algorithms for lesion detection reduce radiologist reading times and expand diagnostic throughput in high-volume centers.
Market Restraints
- Import Dependency:Detector arrays and X-ray tubes sourced from European and East Asian suppliers expose procurement timelines to shipping bottlenecks and currency volatility.
- SAHPRA Compliance Costs:Registration fees and quality management system audits impose fixed costs that disadvantage smaller provincial health departments with limited capital budgets.
- Technical Workforce Scarcity:Biomedical engineers trained in digital imaging system maintenance remain concentrated in private urban facilities, leaving rural installations underserved.
Strategic Opportunities
- Eastern Cape Underpenetration:Port Elizabeth and East London diagnostic centers operate below equipment saturation thresholds relative to breast cancer incidence rates.
- Software-as-Medical-Device Classification:SAHPRA's evolving guidance on AI modules creates first-mover advantages for vendors submitting standalone algorithm registrations.
- Mobile Screening Units:Trailer-mounted digital systems enable outreach programs targeting peri-urban and township populations outside fixed hospital networks.
Industry Challenges
- Radiologist Training Pipeline:Fellowship programs in breast imaging produce fewer than fifteen specialists annually, constraining diagnostic capacity expansion regardless of equipment availability.
- Legacy Analog System Integration:Provincial health departments retain film-based mammography infrastructure requiring parallel maintenance protocols during phased digital transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Mammography Market |
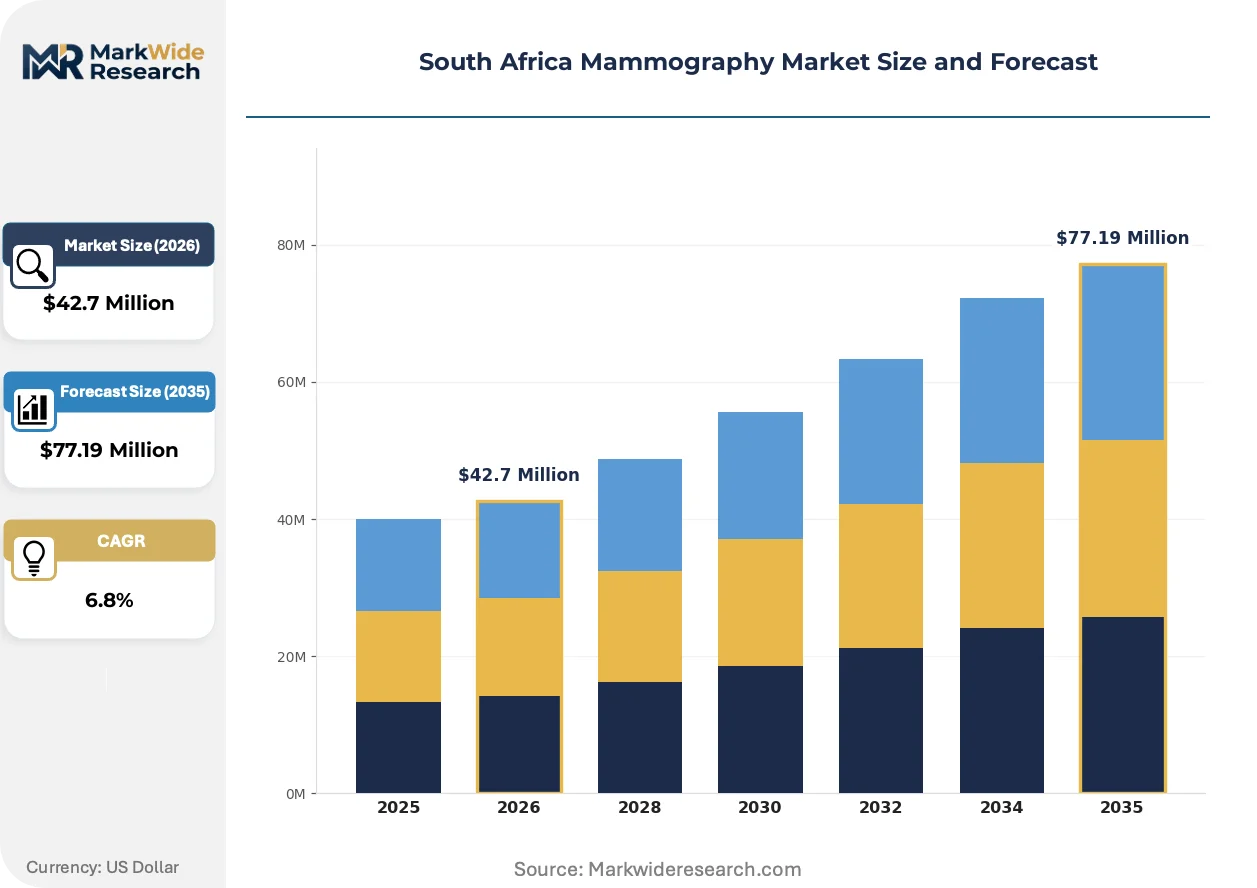
| Market Size in 2026 | $42.7 Million |
| Market Size in 2035 | $77.19 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Mammography, Screen Film Mammography, 3D Mammography, Contrast-Enhanced Mammography End User: Hospitals, Diagnostic Imaging Centers, Outpatient Clinics, Research Institutions Technology: Screening Technology, Imaging Technology, Software Solutions, AI Imaging Analysis Application: Screening, Diagnostic, Follow-Up, Research |
| Companies Covered | Hologic Inc., Siemens Healthineers, GE Healthcare, Fujifilm Holdings Corporation, Philips Healthcare, Planmed Oy, Konica Minolta Inc., Canon Medical Systems Inc., CapeRay Medical (Pty) Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Mammography Market Evolving Landscape
Digital detector technology and artificial intelligence applications are compressing examination times while elevating lesion detection sensitivity, reshaping capital allocation priorities across South African imaging networks.
Tomosynthesis systems with synthesized 2D imaging capability are supplanting conventional full-field digital mammography in premium private diagnostic centers. Mediclinic and Netcare facilities in Sandton and Cape Town CBD are prioritizing these units for competitive differentiation. The technology is compressing recall rates from screening callbacks and redirecting capital toward software-intensive configurations rather than hardware-only replacements.
SAHPRA's draft software-as-medical-device classification guidelines are forcing vendors to separate AI algorithm submissions from hardware registrations. International manufacturers must now prepare standalone technical documentation for image analysis modules. Private diagnostic chains are delaying procurement decisions pending clarity on whether existing installed bases require retroactive compliance assessments.
Consolidated purchasing through hospital group procurement offices is displacing individual facility tender processes. Netcare's centralized sourcing function negotiates enterprise-wide service agreements covering detector replacements and software upgrades. This concentration is most visible in Gauteng, where three procurement offices now coordinate equipment decisions across seventeen imaging sites.
South Africa Mammography Market Segmentation
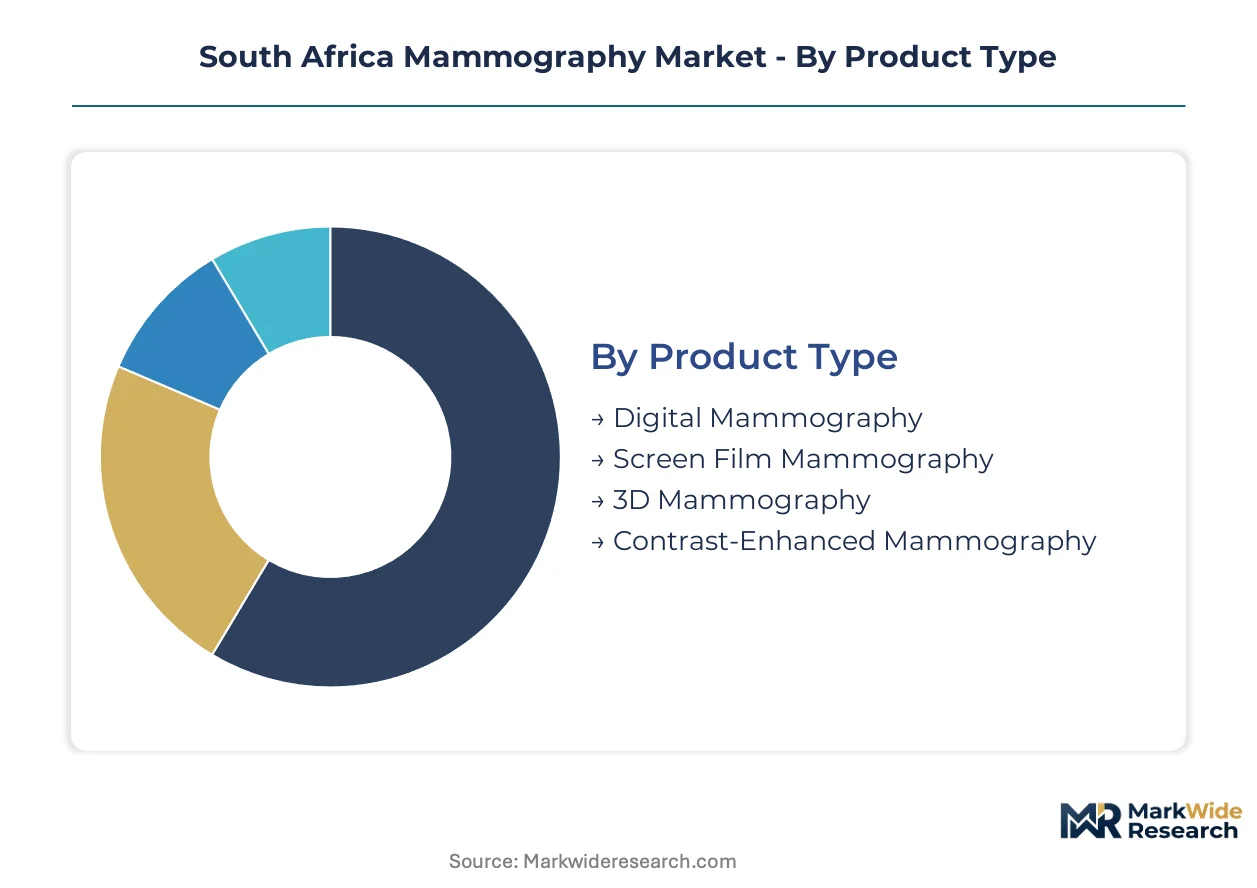
Mammography procurement in South Africa splits across distinct equipment generations and service delivery models. Understanding these divisions clarifies why private hospital chains concentrate investment in digital and tomographic systems while public-sector facilities manage mixed analog-digital estates.
Product Type:
Private hospital procurement offices in Gauteng and Western Cape direct capital toward digital detector arrays, while provincial health departments balance replacement timelines across film-based infrastructure.
- Digital Mammography:Flat-panel detector systems with direct radiography capture dominate procurement flows at Netcare and Mediclinic facilities. Demand concentrates in Sandton and Cape Town CBD corridors where screening program expansion requires high-throughput image acquisition and PACS integration.
- 3D Mammography:Tomosynthesis units with synthesized 2D capability command premium positioning in private diagnostic networks. Mediclinic Southern Africa has prioritized these systems for competitive differentiation, compressing recall rates from screening callbacks.
- Screen Film Mammography:Analog cassette-based systems persist in Eastern Cape and Limpopo provincial hospitals awaiting phased digital transition funding.
- Contrast-Enhanced Mammography:Dual-energy subtraction systems for dense breast tissue evaluation see limited deployment at academic medical centers in Johannesburg and Cape Town.
By volume, Digital Mammography leads. By expansion trajectory, 3D Mammography is climbing the fastest.
End User:
Consolidated purchasing authority now rests with integrated hospital group procurement offices rather than individual facility managers, reshaping vendor engagement patterns.
- Hospitals:Tertiary and secondary facilities with dedicated breast imaging suites generate the highest equipment utilization rates. Netcare's centralized sourcing function negotiates enterprise-wide service agreements covering detector replacements across seventeen Gauteng imaging sites.
- Diagnostic Imaging Centers:Independent radiology practices in metropolitan corridors seek tomographic differentiation to capture referral volumes from private practitioners. Cape Town's Atlantic Seaboard cluster exhibits particular concentration of 3D-capable centers.
- Outpatient Clinics:Limited-service facilities in peri-urban townships rely on mobile screening unit partnerships for access to digital systems.
- Research Institutions:University-affiliated oncology units in Johannesburg and Cape Town deploy specialized protocols for clinical trial imaging endpoints.
Hospitals absorb the majority of capital expenditure. Diagnostic Imaging Centers are gaining share fastest through specialist radiologist partnerships.
Technology:
Software-intensive configurations now capture margin pools previously concentrated in hardware sales, particularly as SAHPRA clarifies algorithm registration pathways.
- Software Solutions:PACS integration modules and workflow management platforms command recurring licensing revenue from high-volume centers. Premium pricing attaches to radiologist efficiency tools that compress reporting turnaround times.
- AI Imaging Analysis:Machine learning algorithms for lesion detection and density assessment represent the steepest expansion trajectory. SAHPRA's draft software-as-medical-device classification guidelines are forcing vendors to prepare standalone technical documentation separate from hardware registrations.
- Screening Technology:Automated exposure control and compression optimization systems standard across digital detector platforms.
- Imaging Technology:Detector array specifications and X-ray tube configurations differentiated by manufacturer platform.
Imaging Technology underpins installed base maintenance. AI Imaging Analysis is expanding most quickly pending regulatory clarity.
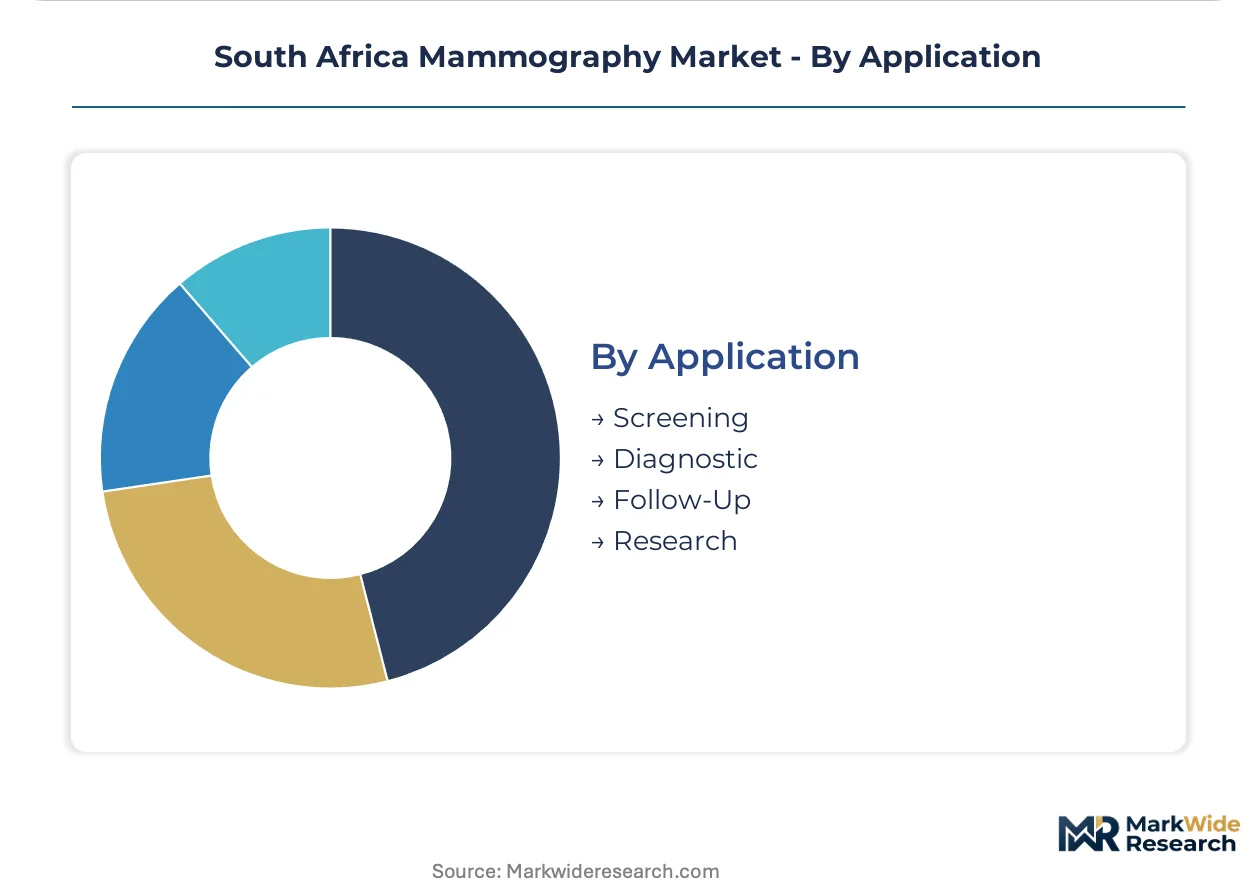
Application:
Reimbursement differentiation between screening and diagnostic protocols influences equipment specification decisions at procurement stage.
- Screening:Asymptomatic population programs drive volume throughput requirements. Netcare and Mediclinic scaling across metropolitan corridors prioritizes systems with rapid image acquisition and low recall rates.
- Diagnostic:Symptomatic patient workups require higher resolution specifications and biopsy guidance compatibility. Urban oncology networks configure dedicated diagnostic suites with tomosynthesis and contrast capability.
- Follow-Up:Surveillance imaging for prior findings generates recurring demand at established breast imaging centers.
- Research:Clinical trial endpoints and academic protocols require specialized phantom calibration and image quality assurance documentation.
Screening commands the largest examination volume. Diagnostic applications are climbing fastest through symptomatic referral expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Private hospital chains concentrate procurement authority across Gauteng and Western Cape, redirecting capital flows away from fragmented public-sector tender boards toward integrated oncology networks with enterprise-wide equipment agreements.
Gauteng Province
Netcare and Mediclinic facilities drive equipment utilization through metropolitan Johannesburg and Pretoria corridors. SAHPRA registration requirements govern all device deployments, extending procurement timelines for international manufacturers. Sandton and Rosebank clusters host the densest concentration of 3D-capable diagnostic suites.
Western Cape
Mediclinic Southern Africa anchors screening program expansion across Cape Town CBD and Atlantic Seaboard. The provincial health department maintains parallel procurement streams for public hospital digital transitions. Stellenbosch and Somerset West corridors exhibit fastest diagnostic center growth.
KwaZulu-Natal
Durban metropolitan networks lag Gauteng and Western Cape in tomography penetration, presenting equipment replacement opportunities. SAHPRA compliance costs weigh more heavily on provincial health department capital budgets. Pietermaritzburg and Richards Bay installations rely on mobile screening partnerships.
Eastern Cape
Port Elizabeth and East London diagnostic centers operate below equipment saturation thresholds relative to breast cancer incidence rates. The provincial health department manages mixed analog-digital estates awaiting phased transition funding. Mthatha and Queenstown rural installations face technical workforce scarcity.
South Africa Mammography Market Competitive Landscape
Player mix skews toward multinational imaging system manufacturers with established service infrastructure. Market structure concentrates around three to four dominant international suppliers commanding premium positioning through direct technical support networks. Two strategic archetypes prevail: integrated diagnostics conglomerates with full modality portfolios, and specialized breast imaging vendors with software-intensive configurations. Competitive moves center on enterprise-wide service agreement consolidation and AI algorithm regulatory pre-positioning ahead of SAHPRA software classification clarity.
Among North American and European manufacturers, Hologic Inc., Siemens Healthineers, and CapeRay Medical (Pty) Ltd occupy distinct archetype positions. Hologic represents the installed-base leverage model, sustaining recurring revenue through digital system service contracts. Siemens Healthineers anchors the direct infrastructure archetype with technical support presence in Johannesburg and Cape Town. CapeRay Medical exemplifies localized manufacturing specialization, competing on shorter replacement-part lead times for provincial health departments.
| Leading Market Players |
|---|
| Hologic Inc. |
| Siemens Healthineers |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Philips Healthcare |
| Planmed Oy |
| Konica Minolta Inc. |
| Canon Medical Systems Inc. |
| CapeRay Medical (Pty) Ltd |
| Others |
Value Network & Pricing Analysis
Long-term service contracts with annual indexation clauses lock in detector replacement schedules and software licensing fees for Netcare and Mediclinic procurement offices, binding price visibility to equipment uptime guarantees across Gauteng and Western Cape installations. These agreements concentrate purchasing leverage within consolidated hospital groups while exposing provincial health departments to spot-market volatility for analog-to-digital transition funding.
Pricing Analysis
Cost-plus contracts with euro-denominated indexation govern international manufacturer pricing to South African private hospital chains. Pricing stratifies across premium 3D tomosynthesis configurations, standard full-field digital systems, and economy-tier analog replacements for public-sector facilities. Price differentiation hinges on SAHPRA registration tier and bundled technical support coverage. Cost compression in the economy tier intensifies because CapeRay Medical's localized assembly shortens replacement-part lead times for provincial tenders. Provincial health departments exhibit highest price sensitivity due to fixed capital budgets, while private diagnostic centers in Sandton and Cape Town CBD prioritize throughput specifications over unit cost.
Supply Chain Analysis
Rotterdam port congestion and Suez Canal routing irregularities choke detector array deliveries from German and Dutch manufacturing hubs to Johannesburg distribution centers. South African procurement draws from Germany, the Netherlands, and Japan for flat-panel detectors, X-ray tubes, and high-voltage generators. Supply chain risk centers on single-source vulnerability for amorphous selenium detector substrates. Distribution runs through manufacturer-direct technical support infrastructure in Johannesburg and Cape Town, with spare parts warehousing at OR Tambo logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment manufacturers face substitution pressure from AI-native software vendors seeking standalone algorithm registration pathways under SAHPRA's evolving classification framework. Defense of installed-base revenue requires strategic repositioning.
For Market Incumbents: Fortify enterprise-wide service agreements with Netcare and Mediclinic by embedding predictive maintenance modules and compressed detector replacement SLAs. Deepen backward integration into software companion development for radiologist workflow efficiency, neutralizing pure-play AI vendors before SAHPRA clarifies standalone algorithm registration requirements. Prioritize certification investment in ISO 13485 quality management extensions to accelerate approval timelines for integrated hardware-software submissions.
For New Entrants and Emerging Players: Anchor in Eastern Cape mobile screening partnerships where equipment saturation gaps persist relative to breast cancer incidence in Port Elizabeth and East London corridors. Target diagnostic imaging centers in KwaZulu-Natal's Durban metropolitan network, which lags Gauteng and Western Cape in tomography penetration. Pursue go-to-market positioning through trailer-mounted system leasing with per-screen revenue sharing, bypassing upfront capital barriers for peri-urban township clinics.
For Investors and Strategic Acquirers: Regional service specialists with captive biomedical engineering capabilities and SAHPRA pre-certification track records represent the most defensible acquisition profile. Long-term viability hinges on software-intensive margin pools expanding faster than hardware replacement cycles. Watch SAHPRA's final software-as-medical-device classification guidance as the inflection signal determining whether AI modules require separate regulatory submissions and retroactive compliance assessments for installed bases.
| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Pre-Certification Investment | Accelerates product launch timelines for manufacturers meeting ISO 13485 standards ahead of competitors. |
| Hospital System Partnership | Netcare's centralized sourcing function consolidates procurement authority across seventeen Gauteng imaging sites. |
| Software Companion Development | AI-enhanced image analysis modules command premium licensing fees from high-volume diagnostic centers. |
| Mobile Screening Unit Deployment | Trailer-mounted digital systems unlock peri-urban and township populations outside fixed hospital networks. |
| Reimbursement Strategy | Screening program expansion at Mediclinic Southern Africa scales breast cancer detection across Cape Town corridors. |
Research Methodology
A spread of perspectives from hospital procurement managers, biomedical engineers, radiologists, and SAHPRA regulatory affairs specialists converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with Netcare and Mediclinic sourcing executives, provincial health department equipment planners, and CapeRay Medical technical directors. Secondary validation drew from SAHPRA medical device registration databases, South African Bureau of Standards electrical safety protocols, hospital procurement contract disclosures, and GPO service agreement records. Bottom-up equipment installation tracking and top-down healthcare expenditure modeling were triangulated to cross-verify volume and value estimates.
Segmentation dimensions modeled include product type across digital, 3D tomosynthesis, and analog system generations; end user categories spanning hospital chains, diagnostic imaging centers, and mobile screening partnerships; and technology tiers separating hardware platforms from AI imaging analysis software. CAGRs were derived from regression analysis of historical procurement flows projected across the analysis window, incorporating SAHPRA approval timeline distributions and private hospital expansion capex schedules as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable SAHPRA regulatory timelines and sustained private hospital consolidation in Gauteng and Western Cape; material deviation in software classification guidance or provincial funding allocations would warrant model refresh. Practitioners should keep alternative scenarios live as AI-native vendor competitive positioning and Eastern Cape digital transition funding timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Interventional Radiology Market
Medical Imaging
AI Fetal Ultrasound View Detection Software Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
India Nuclear Imaging Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
Contrast Media Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Fluorescence Microscopy Market
Medical Imaging
Global Mini C-Arm Market