
 South America Fluoroscopy Market | 2026-2036
South America Fluoroscopy Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fluoroscopy Market Analytics
Market Context
Brazilian public hospital procurement is broadening access to fluoroscopy systems across the Sistema Único de Saúde network. Siemens Healthineers leverages its installed base of angiography suites to sustain service contract renewals throughout the Mercosur region. GE Healthcare anchors its position through localized refurbishment programs that extend equipment lifecycles in cost-constrained facilities. Koninklijke Philips NV competes on integrated cardiovascular workflow solutions that combine fluoroscopy with hemodynamic monitoring.
Technical Definition and Segments
Fluoroscopy employs continuous X-ray beam passage through the patient to generate real-time moving images, with modern systems operating at 15-30 frames per second and incorporating flat-panel detectors to replace legacy image intensifiers for superior dose efficiency and spatial resolution. Fixed fluoroscopy systems dominate capital expenditure budgets in Brazil and Argentina due to their essential role in cardiac catheterization laboratories, while mobile C-Arms represent the fastest-expanding product category as ambulatory surgical centers proliferate across Colombia and Chile. Digital subtraction angiography technology commands premium positioning in the technology segment because neurovascular and peripheral vascular interventions require precise vessel visualization against bony anatomical backgrounds.
Regulatory Environment
ANVISA governs medical device registration and post-market surveillance for fluoroscopy equipment in Brazil, while Argentina's national pharmaceutical regulator and Colombia's INVIMA enforce comparable technical standards for radiation-emitting diagnostic systems. These frameworks mandate ionizing radiation safety protocols, software validation for image processing algorithms, and clinical evidence requirements that shape product development priorities and market entry timelines for manufacturers. Stakeholders must monitor evolving reimbursement classifications for interventional fluoroscopy procedures as health technology assessment bodies across the region recalibrate coverage decisions based on comparative effectiveness data.
Market Dynamics
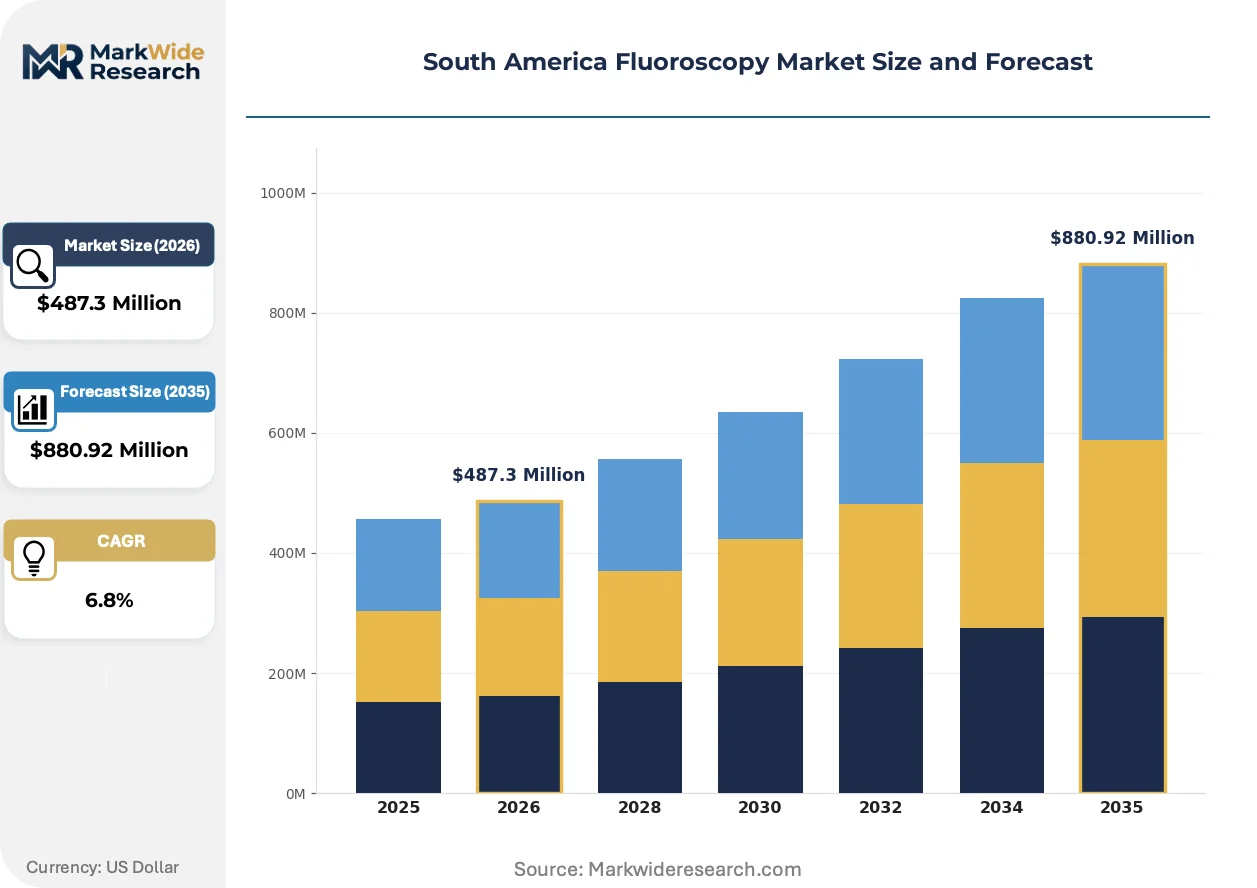
Flat-panel detector technology is compressing equipment replacement cycles across South American hospital networks, while ANVISA's streamlined registration pathways accelerate competitive entry for digital imaging platforms.
Growth Catalysts
- Cardiovascular procedure volumes:Brazilian public hospitals are expanding interventional radiology suites to accommodate rising cardiac catheterization demand within the Sistema Único de Saúde network.
- ANVISA registration reform:Updated medical device approval pathways are shortening market entry timelines for fluoroscopy manufacturers targeting Brazil.
- Ambulatory surgical center proliferation:Colombia and Chile are witnessing rapid mobile C-Arm deployment as outpatient surgical facilities multiply.
Market Restraints
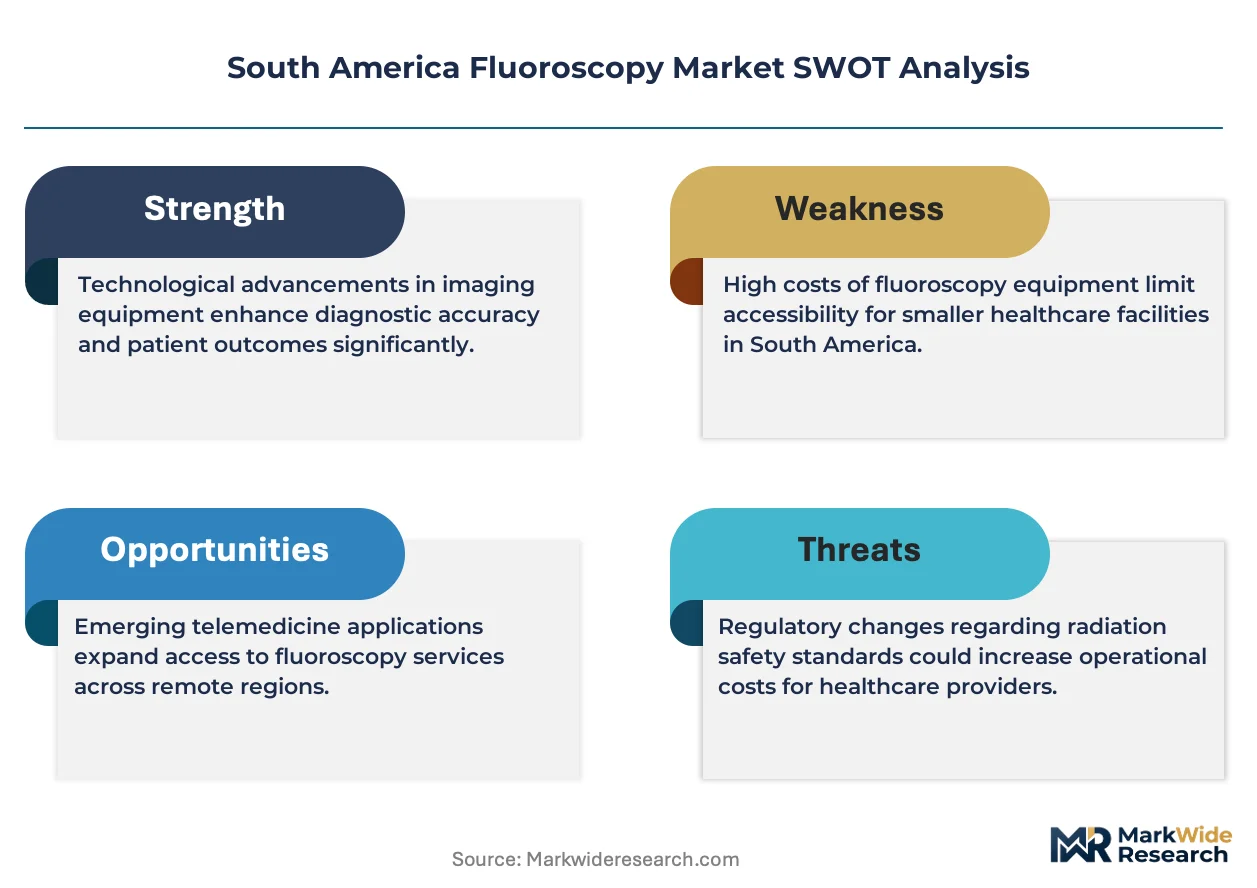
- Import dependency for core components:Flat-panel detectors and high-voltage generators concentrate supply in East Asian manufacturing clusters, exposing South American assemblers to currency volatility and shipping disruptions.
- Radiation safety compliance costs:Ionizing radiation protocols mandated by Argentina's national pharmaceutical regulator impose substantial facility retrofit burdens on older installations.
- Extended capital equipment lifecycles:Refurbishment programs extend usable life of legacy image intensifier systems, deferring replacement demand.
Strategic Opportunities
- Peru and Ecuador market development:These Andean markets remain underpenetrated for digital subtraction angiography systems, creating first-mover positioning potential.
- Integrated cardiovascular workflows:Convergence of fluoroscopy with hemodynamic monitoring platforms opens premium positioning in tertiary care institutions.
- Telemedicine-linked remote diagnostics:Regulatory frameworks for teleradiology are expanding reimbursement eligibility for image-guided procedures performed with remote specialist support.
Industry Challenges
- Interventional radiologist training pipelines:Brazil's Southeast region concentrates qualified specialists, leaving northern and central states with critical workforce gaps for complex fluoroscopy-guided procedures.
- Legacy system integration complexity:Hospitals with mixed-vendor installed bases face substantial IT interoperability hurdles when deploying new digital platforms alongside existing PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fluoroscopy Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Fluoroscopy, Mobile Fluoroscopy, C-Arms, Digital Fluoroscopy End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Specialty Clinics Technology: X-Ray Imaging, Digital Subtraction Angiography, Computed Radiography, Image Intensification Application: Surgical Guidance, Pain Management, Gastrointestinal Studies, Cardiovascular Imaging |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips NV, Canon Medical Systems Corporation, Shimadzu Medical, Hologic Inc, Carestream Health, Hitachi Medical Systems, Orthoscan Inc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fluoroscopy Market Evolving Landscape
Digital imaging architecture is fundamentally restructuring competitive positioning in South American fluoroscopy, with three interconnected developments reshaping equipment procurement and clinical deployment patterns.
Flat-panel detector technology is consolidating market share from legacy image intensifier systems by delivering superior dose efficiency and spatial resolution at 15-30 frames per second. Brazilian tertiary care institutions are prioritizing this transition for cardiac catheterization laboratories, compressing the viable lifespan of analog-equipped suites and forcing accelerated capital planning cycles.
ANVISA's updated medical device registration framework is tightening post-market surveillance requirements for software-validated image processing algorithms. This regulatory evolution elevates compliance burdens for manufacturers while creating competitive moats for established platforms with proven clinical evidence portfolios, particularly affecting neurovascular intervention system categories.
Service contract unbundling is fragmenting traditional vendor-captive maintenance relationships in Argentine and Colombian hospital networks. Independent third-party technical service providers are capturing preventive maintenance revenue streams, compressing OEM margins and forcing equipment manufacturers to reposition around consumables and software subscription models.
South America Fluoroscopy Market Segmentation
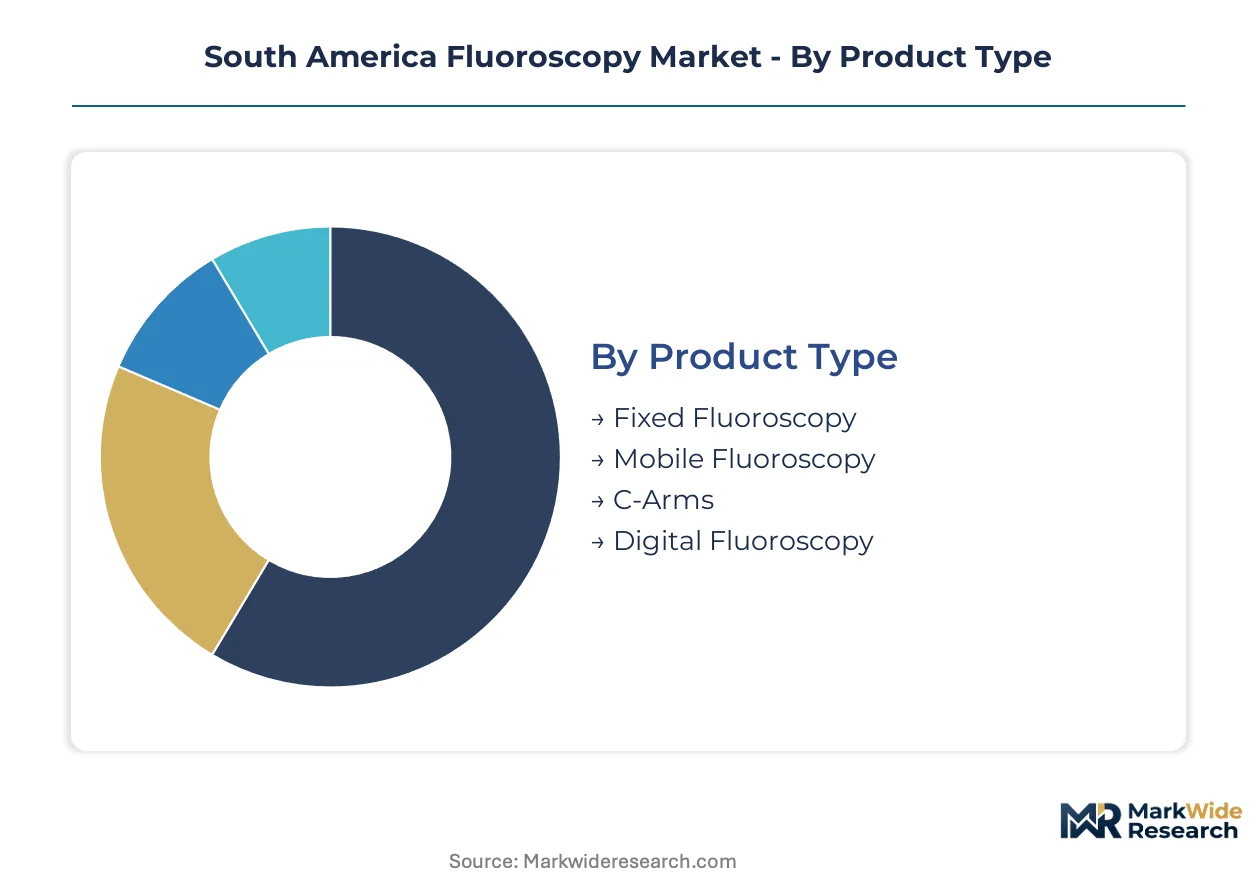
Fluoroscopy equipment procurement across South America follows distinct technical and clinical pathways that shape vendor positioning. Segmentation reveals where ANVISA registration requirements concentrate compliance investment and which installation types command premium pricing in Brazilian tertiary care networks.
Product Type:
ANVISA registration pathways differentiate these segments by radiation output classification and software validation requirements, with fixed installations facing the most stringent post-market surveillance protocols.
- Fixed Fluoroscopy:Permanently installed systems with integrated patient tables and dedicated control rooms operate at higher power outputs for complex interventional procedures. São Paulo's tertiary cardiac catheterization laboratories anchor regional demand as public hospital expansion within Sistema Único de Saúde prioritizes these capital-intensive suites.
- Mobile Fluoroscopy:Transportable units on wheeled bases deliver intermediate imaging capability for multi-procedure rooms and emergency departments. Colombian ambulatory surgical centers are absorbing these systems fastest as outpatient facility construction accelerates in Bogotá and Medellín.
- C-Arms:Articulated C-shaped gantries provide flexible positioning for orthopedic and trauma applications.
- Digital Fluoroscopy:Flat-panel detector-based systems replacing analog architectures across Brazilian hospital networks.
Leading the category by volume: Fixed Fluoroscopy. Growing fastest: Mobile Fluoroscopy.
End User:
Procurement authority and reimbursement pathways split these segments between centralized public tenders and private capital deployment.
- Hospitals:Brazilian public hospitals dominate capital expenditure through Sistema Único de Saúde network expansion, with Southeast region institutions commanding the largest procurement volumes. ANVISA registration compliance costs concentrate here due to mandatory radiation safety officer staffing and quality management system documentation.
- Diagnostic Centers:Specialized imaging facilities in Argentina's Buenos Aires province and Brazil's São Paulo state concentrate outpatient fluoroscopy for gastrointestinal and musculoskeletal studies.
- Outpatient Clinics:Smaller procedural facilities in Chile and Colombia deploying mobile systems for limited intervention volumes.
- Specialty Clinics:Cardiovascular and pain management focused practices with targeted equipment needs.
Procurement value concentrates in Hospitals. Patient throughput per unit peaks at Diagnostic Centers.
Technology:
Regulatory frameworks in Brazil and Argentina mandate distinct clinical evidence packages for software-driven image processing versus legacy hardware architectures.
- Digital Subtraction Angiography:Advanced image processing algorithms subtract bone and soft tissue signals to isolate contrast-filled vasculature in real-time. Neurovascular intervention suites in Brazilian tertiary institutions require this capability, with ANVISA demanding extensive software validation documentation for algorithm-driven dose modulation features.
- X-Ray Imaging:Fundamental continuous radiation exposure generating real-time anatomical visualization without advanced processing.
- Computed Radiography:Photostimulable phosphor plate systems bridging analog and fully digital workflows.
- Image Intensification:Vacuum tube-based electron multiplication technology being displaced by flat-panel detectors across South American replacement cycles.
Technology transition favors Digital Subtraction Angiography for premium positioning. Steepest decline trajectory: Image Intensification.
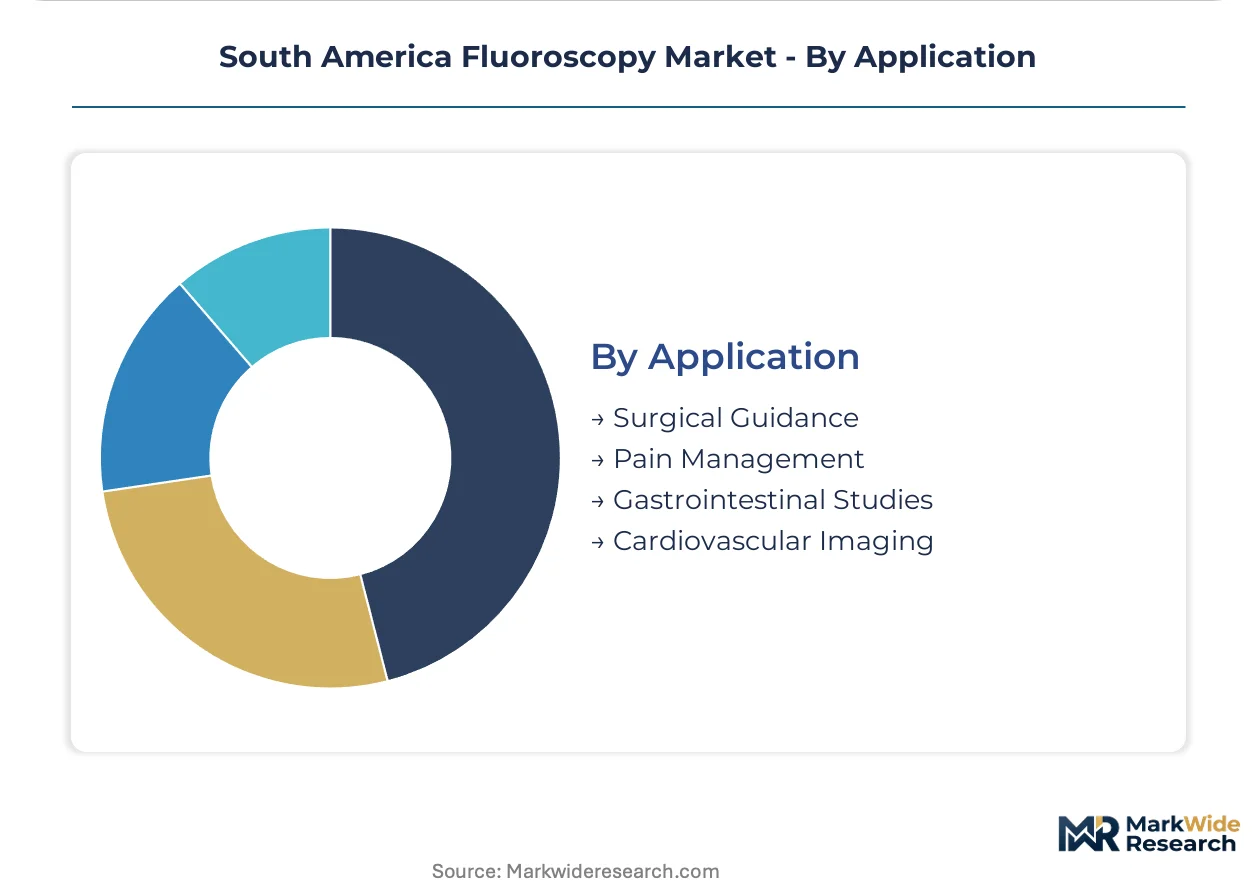
Application:
Reimbursement classifications and procedure volume growth differentiate clinical use cases across public and private payment systems.
- Cardiovascular Imaging:Real-time guidance for cardiac catheterization, structural heart interventions, and peripheral vascular procedures. Brazilian public hospital expansion of interventional radiology suites targets this application specifically, with procedure volumes rising fastest in Southeast region metropolitan centers.
- Surgical Guidance:Orthopedic, trauma, and general surgery visualization requiring flexible C-Arm positioning.
- Pain Management:Fluoroscopy-directed spinal injections and nerve blocks in outpatient settings.
- Gastrointestinal Studies:Barium swallow, enema, and motility assessment procedures declining in volume as endoscopy displaces diagnostic fluoroscopy.
Procedure volume leadership: Cardiovascular Imaging. Fastest volume expansion: Pain Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Flat-panel detector supply chains from East Asian manufacturing clusters feed fluoroscopy assembly operations serving Brazilian and Argentine hospital networks. Currency volatility and shipping disruptions expose South American distributors to component shortage risks. São Paulo's tertiary care institutions anchor regional demand concentration.
Brazil
ANVISA's streamlined medical device registration pathways are accelerating digital imaging platform approvals for manufacturers targeting the Sistema Único de Saúde network. Southeast region public hospitals command the largest procurement volumes as interventional radiology suite expansion proceeds. São Paulo metropolitan cardiac catheterization laboratories drive fixed fluoroscopy replacement cycles.
Argentina
The national pharmaceutical regulator enforces ionizing radiation safety protocols that impose substantial facility retrofit burdens on legacy image intensifier installations. Buenos Aires province diagnostic centers concentrate outpatient fluoroscopy demand for gastrointestinal studies. Cost-constrained facilities extend equipment lifecycles through localized refurbishment programs.
Colombia
INVIMA governs radiation-emitting diagnostic system standards comparable to Brazilian and Argentine frameworks. Bogotá and Medellín ambulatory surgical centers absorb mobile fluoroscopy systems fastest as outpatient facility construction accelerates. Private capital deployment distinguishes procurement from centralized public tender structures.
Chile
Health technology assessment bodies recalibrate reimbursement classifications for interventional fluoroscopy procedures based on comparative effectiveness data. Santiago metropolitan clinics deploy mobile C-Arms for limited intervention volumes in pain management applications. Regulatory frameworks for teleradiology expand reimbursement eligibility for remote specialist-supported procedures.
Peru
Andean market underpenetration for digital subtraction angiography systems creates first-mover positioning potential for neurovascular intervention platforms. Lima-based tertiary institutions lack qualified interventional radiologist density found in Brazilian Southeast networks. National pharmaceutical regulator technical standards for radiation safety compliance remain less stringent than Mercosur counterparts.
South America Fluoroscopy Market Competitive Landscape
Global majors compete with regional champions across service contract and refurbishment program dimensions in South American fluoroscopy. Siemens Healthineers leverages installed base density to sustain recurring revenue streams throughout Mercosur. Three archetypes dominate: integrated cardiovascular workflow providers, refurbishment-focused lifecycle extenders, and mobile C-Arm specialists. Strategic moves concentrate on service contract unbundling and software subscription model transitions.
Among German-origin diversified health technology conglomerates, Siemens Healthineers anchors premium-tier positioning through angiography suite density. GE Healthcare exemplifies the refurbishment archetype with lifecycle extension programs for cost-constrained facilities. Koninklijke Philips NV represents integrated cardiovascular workflow convergence combining fluoroscopy with hemodynamic monitoring platforms. These three occupy distinct competitive vectors rather than direct overlap.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Shimadzu Medical |
| Hologic Inc |
| Carestream Health |
| Hitachi Medical Systems |
| Orthoscan Inc |
| Others |
Value Network & Pricing Analysis
Interventional radiologist concentration in Brazil's Southeast region compresses labor-cost differentials into pricing-tier spreads, with São Paulo's tertiary institutions absorbing premium-tier fixed fluoroscopy systems while northern states face 15-25% equipment cost escalations due to specialist scarcity and extended installation timelines.
Pricing Analysis
Service contract unbundling defines competitive positioning, with manufacturers separating preventive maintenance from software subscription tiers to retain margin. Premium-mid-economy pricing differentiation rests on flat-panel detector resolution grades and ANVISA software validation certification levels. Cost compression in economy-tier mobile C-Arms intensifies because third-party technical providers capture aftermarket revenue. Public hospital procurement committees within Sistema Único de Saúde exhibit highest price sensitivity, while private cardiovascular centers in São Paulo tolerate premium positioning for integrated hemodynamic monitoring bundles.
Supply Chain Analysis
Regional distribution centers in São Paulo and Buenos Aires operate hub-and-spoke patterns radiating into Andean markets. Flat-panel detectors and high-voltage generators draw from South Korean, Japanese, and Chinese manufacturing clusters. Xenon gas for image intensifier legacy systems and tungsten-rhenium X-ray tube filaments represent critical input dependencies. Single-source vulnerability for amorphous silicon detector substrates exposes Brazilian assemblers to shipping disruption. Distribution runs through authorized dealer networks with mandatory ANVISA import licensing for radiation-emitting components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into flat-panel detector sourcing represents the decisive vertical-integration race, with manufacturers securing captive supply from East Asian substrate foundries to insulate margin structures from currency volatility and logistics chokepoints.
For Market Incumbents: Anchor installed base density through multi-year service contract extensions that bundle software algorithm updates with preventive maintenance, countering third-party technical provider encroachment in Argentine and Colombian hospital networks. Deepen backward integration into amorphous silicon detector substrate sourcing to reduce exposure to single-source East Asian supply concentration.
For New Entrants and Emerging Players: Independent service organizations offer partnership pathways into fragmented aftermarket maintenance revenue, bypassing OEM-captive relationships in Chilean and Colombian ambulatory surgical centers. Digital subtraction angiography penetration in Peruvian and Ecuadorian neurovascular suites remains the most penetrable geography. Position through teleradiology-linked remote diagnostics platforms that exploit expanding reimbursement frameworks for image-guided procedures with specialist support.
For Investors and Strategic Acquirers: The window for entry favors mid-cap mobile C-Arm specialists with established INVIMA registration portfolios and Bogotá distribution infrastructure. Long-term viability hinges on software subscription transition completion and hemodynamic monitoring integration capability. Monitor ANVISA post-market surveillance enforcement intensity as inflection indicator for compliance cost escalation and competitive moat widening.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Subscription Transition | Unbundled service contracts in Argentina shift revenue from hardware to algorithm-driven dose modulation platforms. |
| Flat-Panel Detector Backward Integration | Captive amorphous silicon substrate sourcing insulates Brazilian assemblers from East Asian logistics disruption. |
| Teleradiology Platform Development | Remote specialist support expands reimbursement eligibility for interventional procedures in Chilean metropolitan clinics. |
| ANVISA Registration Acceleration | Streamlined pathways compress market entry timelines for digital imaging platforms targeting Sistema Único de Saúde. |
| Integrated Cardiovascular Workflow Convergence | Hemodynamic monitoring bundling commands premium positioning in São Paulo tertiary cardiac catheterization laboratories. |
Research Methodology
Document review covered ANVISA medical device registration filings, INVIMA radiation safety protocols, and Sistema Único de Saúde procurement tender databases, complemented by interviews with biomedical engineers at Brazilian tertiary hospitals, interventional radiologists in São Paulo metropolitan centers, GPO contracts managers, and aftermarket service technicians across Mercosur. Secondary validation drew from hospital capital expenditure records, customs import data for fluoroscopy components, and trade association equipment shipment reports. Bottom-up and top-down triangulation cross-checked manufacturer shipment disclosures against facility-level installation tracking.
Segmentation outputs across product type, end user, technology, and application dimensions were modeled over the projection horizon. CAGRs were derived from equipment replacement cycle compression rates and procedure volume elasticity to installed base expansion. Forecast inputs incorporated ANVISA registration timeline acceleration effects, flat-panel detector price erosion curves, and interventional radiologist workforce pipeline constraints in Brazil's northern states.
Caveats apply where ANVISA post-market surveillance enforcement intensity, East Asian component supply disruption, or Brazilian real currency volatility could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global Image Guided Therapy System Market
Medical Imaging
Industrial Radiography Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
China Mammography Market
Medical Imaging
Meningitis Imaging Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
X-Ray Film Market
Medical Imaging
Breast Imaging Equipment Market
Medical Imaging
Precision Cancer Imaging Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Medical Imaging Informatics Market
Medical Imaging
France Digital X-Ray Devices Market