
 Europe Medical Imaging Market | 2026-2036
Europe Medical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Imaging Market Intelligence
A shift toward decentralized care within specialty clinics and diagnostic centers is reorganizing equipment procurement priorities across Europe. Siemens Healthineers dominates the high-end MRI segment, particularly within its home market of Germany. Philips Healthcare competes strongly with its specialized ultrasound and integrated digital solutions, while GE Healthcare leverages its extensive service network across the continent.
Europe's medical imaging sector encompasses technologies that produce visual representations of internal body structures for clinical analysis. These systems, ranging from MRI machines utilizing strong magnetic fields to X-ray systems employing ionizing radiation, are essential for non-invasive diagnosis. While CT Scanners and MRI Machines constitute major capital investments for large hospitals, the market for ultrasound devices is expanding rapidly within smaller specialty clinics. Cardiology Diagnostics and Oncology Screening remain the principal applications driving technological innovation and system upgrades.
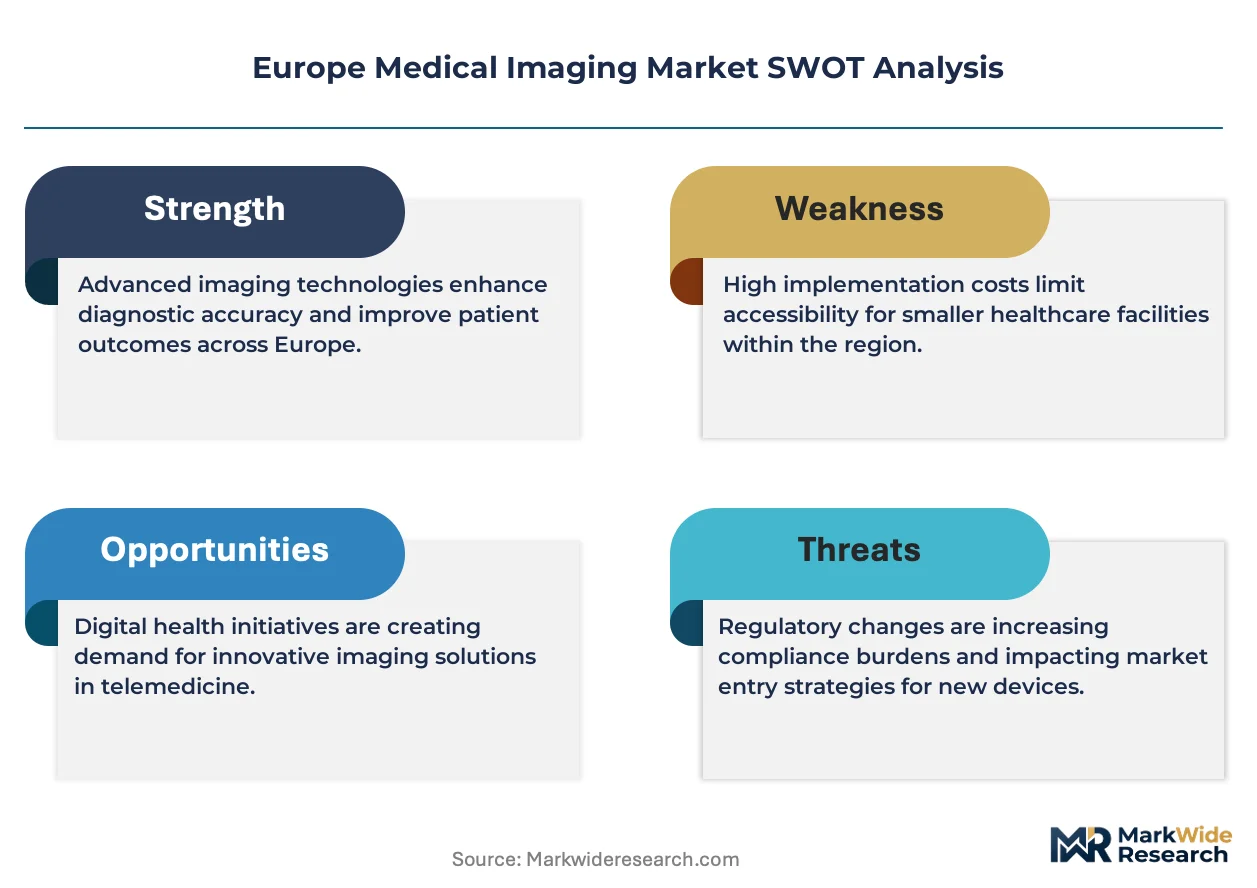
The European Union's Medical Device Regulation (MDR) mandates stringent clinical evidence and post-market surveillance for all new devices. Concurrently, the General Data Protection Regulation (GDPR) sets strict rules for patient data management, particularly for cloud-based platforms and teleradiology services. Successfully balancing the pace of technological innovation with this complex regulatory framework is the central strategic challenge for manufacturers operating in the region.
Market Dynamics
The central force shaping the Europe Medical Imaging Market is the tension between the clinical necessity for technologically advanced diagnostic systems and the stringent, cost-intensive compliance framework imposed by the EU's Medical Device Regulation (MDR).
Growth Catalysts
- Oncology Screening Mandates:National and EU-level initiatives, such as the Europe's Beating Cancer Plan, are expanding organized screening programs, directly stimulating demand for mammography, CT, and MRI systems for early detection.
- AI in Diagnostics:The integration of artificial intelligence and machine learning algorithms into imaging software is enhancing diagnostic accuracy and workflow efficiency, encouraging healthcare providers to upgrade existing platforms.
- Aging Demographics:Countries with pronounced aging populations, particularly Germany and Italy, face a rising prevalence of chronic conditions like cardiovascular and neurodegenerative diseases, sustaining demand for advanced diagnostic imaging.
Market Restraints
- Capital Expenditure Constraints:The high acquisition and installation costs of high-end systems, such as 3T MRI and multi-slice CT scanners, remain a significant barrier for smaller hospitals and outpatient clinics across Europe.
- Regulatory Compliance Burden:The EU's MDR requires extensive clinical evidence and post-market surveillance, increasing development costs and lengthening time-to-market for new imaging devices and software.
- Component Supply Concentration:The market relies on a limited number of global suppliers for critical components like high-performance X-ray tubes and superconducting magnets, creating potential bottlenecks and price volatility.
Strategic Opportunities
- Teleradiology Expansion:Developing robust teleradiology networks in Eastern European nations offers a significant opportunity to improve access to specialized radiological interpretations and optimize resource allocation.
- Point-of-Care Ultrasound (POCUS):The application of portable ultrasound devices is expanding from emergency rooms to general practice and specialist clinics, creating a new market for compact, user-friendly systems.
- Hybrid Imaging Modalities:The convergence of technologies, particularly PET/CT and PET/MRI systems, offers superior diagnostic capabilities in oncology and neurology, establishing a premium market segment for comprehensive cancer centers.
Industry Challenges
- Specialized Workforce Shortages:A Europe-wide shortage of qualified radiologists, medical physicists, and radiographers trained to operate sophisticated imaging equipment and interpret complex data limits system utilization.
- Data Security and GDPR:Managing and securing vast amounts of sensitive patient imaging data in compliance with the General Data Protection Regulation (GDPR) is a major operational challenge, especially for cloud-based platforms.
- Legacy System Integration:Ensuring seamless interoperability between new, advanced imaging systems and existing hospital information systems (HIS) and picture archiving and communication systems (PACS) is a persistent technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Imaging Market |
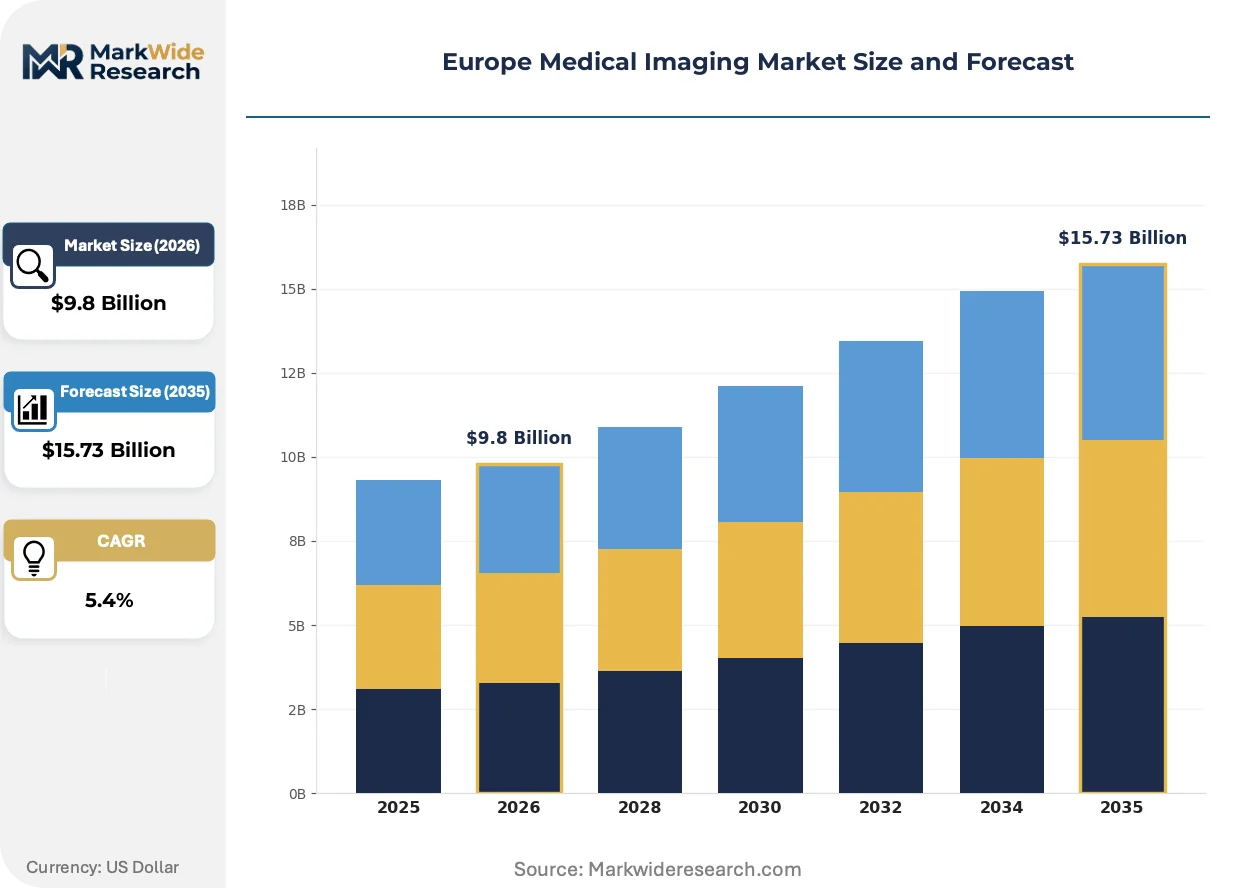
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Scanners, MRI Machines, Ultrasound Devices, X-ray Systems, Nuclear Imaging Equipment Application: Cardiology Diagnostics, Oncology Screening, Neurology Assessment, Musculoskeletal Analysis, Pulmonology Examination End User: Diagnostic Centers, Specialty Clinics, Radiology Departments, Ambulatory Surgical Centers, Research Institutions Deployment Type: On-Premise Installation, Cloud-Based Platforms, Mobile Imaging Units, Integrated Digital Solutions, Teleradiology Services |
| Companies Covered | Canon Medical Systems, Hologic, Siemens Healthineers, Shimadzu, Esaote, Philips Healthcare, FUJIFILM, Elekta, GE Healthcare, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Imaging Market Strategic Shifts & Innovations
Software-defined functionalities and rigorous data governance frameworks are fundamentally altering the value proposition of medical imaging systems in Europe. This shift prioritizes algorithmic performance and data compliance alongside traditional hardware specifications.
AI-powered image reconstruction serves as a core enabling technology, enhancing image clarity from scans using lower radiation doses or faster acquisition times. Radiology departments in large university hospitals across the EU are adopting these tools to improve diagnostic confidence and manage patient throughput. This software-led advancement is decomposing the traditional hardware-centric upgrade cycle, shifting value towards subscription-based algorithmic enhancements.
The European Union's upcoming AI Act introduces a risk-based framework for artificial intelligence, directly impacting medical diagnostic tools. This legislation mandates new conformity assessments and transparency protocols for manufacturers of AI-driven imaging software. The clinical decision support systems segment is most affected, compelling vendors to invest in auditable and explainable AI to secure market access and CE marking.
A transition towards managed equipment services (MES) and usage-based procurement models is gaining favor over direct capital purchases. This change disrupts the conventional capital sales model, benefiting vendors capable of providing comprehensive service, maintenance, and technology refresh packages. This trend is most visible within public healthcare systems, such as those in the UK and Scandinavia, that aim for more predictable operational costs.
Europe Medical Imaging Market Segmentation
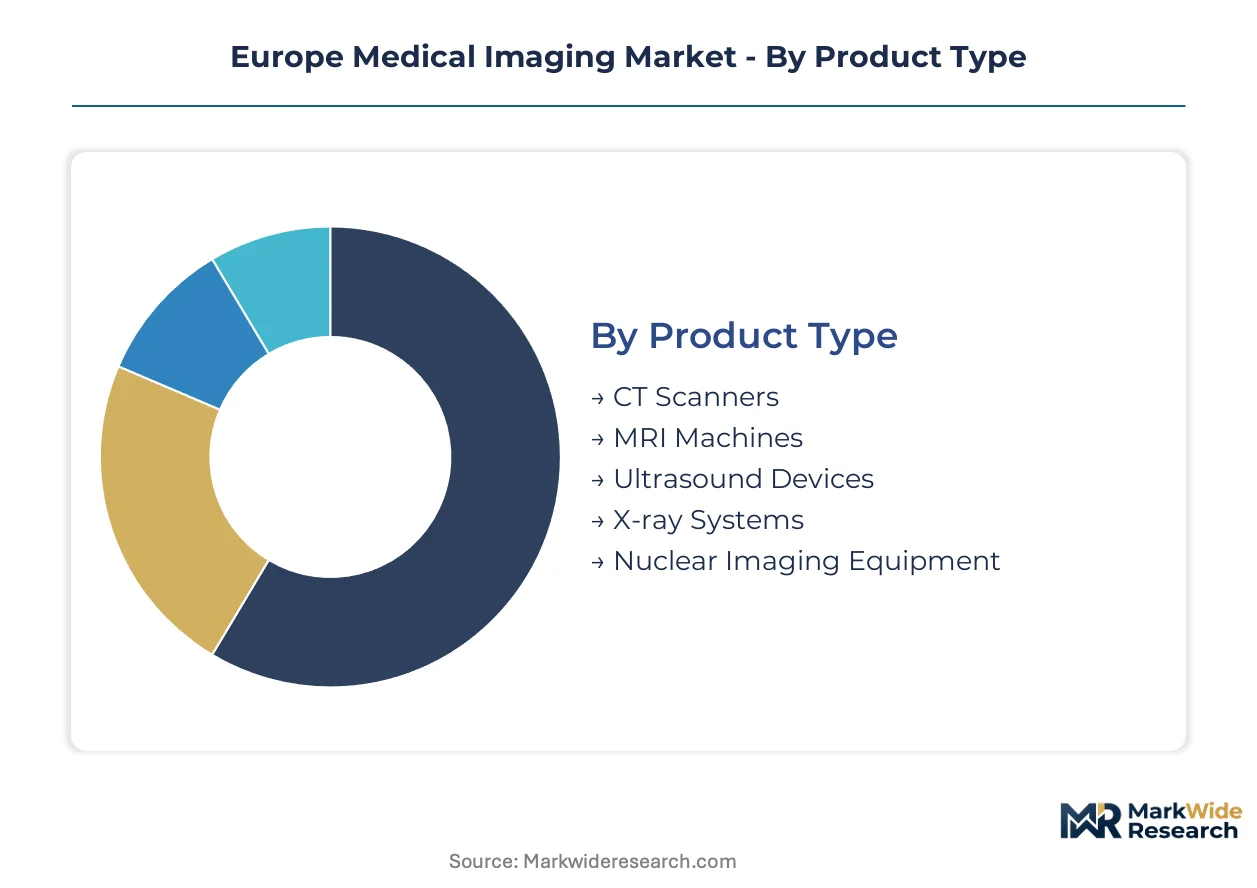
The Europe Medical Imaging Market's segmentation reflects diverse technological capabilities and varied clinical needs across the continent. Understanding these distinct segments helps manufacturers tailor product development and market access strategies effectively. Each category highlights specific demand patterns and regulatory considerations impacting device adoption.
Product Type:
The market for medical imaging products across Europe is characterized by the localized adoption of advanced modalities, with certain systems dominating in specific national healthcare frameworks.
- MRI Machines:These systems use strong magnetic fields and radio waves to generate detailed images of organs and soft tissues. Germany’s advanced healthcare system prioritizes high-end MRI modalities, especially for neurological and oncological diagnostics.
- CT Scanners:Computed Tomography devices employ X-rays and computer processing to create cross-sectional images of the body. Large university hospitals across the European Union rely on multi-slice CT scanners for rapid emergency diagnostics and comprehensive oncology screening programs.
- Ultrasound Devices:These portable systems utilize high-frequency sound waves to visualize internal body structures without ionizing radiation. Smaller specialty clinics and general practices throughout Europe increasingly adopt compact ultrasound devices for point-of-care diagnostics.
- X-ray Systems:Conventional X-ray systems use ionizing radiation for basic skeletal and chest imaging. Public healthcare systems in Eastern Europe maintain a significant installed base of X-ray units for primary diagnostic needs.
- Nuclear Imaging Equipment:This category includes PET and SPECT scanners, which detect radiation emitted from radiopharmaceuticals within the body. Comprehensive cancer centers in Western Europe utilize these systems for advanced metabolic and functional imaging.
X-ray Systems commands the established base. The steepest expansion runs through Ultrasound Devices.
Application:
The applications for medical imaging systems demonstrate varying levels of clinical urgency and technological sophistication across the European patient population.
- Oncology Screening:This application focuses on early cancer detection and staging, utilizing mammography, CT, and MRI systems. National and EU-level initiatives, such as Europe's Beating Cancer Plan, directly stimulate demand for these diagnostic tools.
- Cardiology Diagnostics:Imaging modalities like ultrasound, CT, and MRI are crucial for assessing heart structure and function, diagnosing cardiovascular diseases. Countries with aging populations, including Italy, sustain high demand for cardiology diagnostics.
- Neurology Assessment:MRI and CT are essential for diagnosing brain and spinal cord disorders, including stroke, tumors, and neurodegenerative conditions. Specialized neurology clinics across France and the UK frequently deploy advanced imaging for patient care.
- Musculoskeletal Analysis:X-ray, MRI, and ultrasound devices are used to evaluate bones, joints, and soft tissues for injuries and degenerative conditions. Orthopedic centers throughout Scandinavia rely on these systems for comprehensive patient evaluation.
- Pulmonology Examination:CT scans and X-rays are primary tools for diagnosing lung conditions, including infections, tumors, and chronic obstructive pulmonary disease. Respiratory clinics in Spain and Portugal utilize these imaging techniques for patient management.
Demand for Oncology Screening drives significant investment. Cardiology Diagnostics presents substantial clinical opportunities.
End User:
The end-user landscape for medical imaging equipment in Europe is undergoing a transformation, with procurement priorities shifting from traditional hospital settings to decentralized care providers.
- Radiology Departments:These are the traditional core users within large hospitals, requiring high-end CT, MRI, and nuclear imaging systems for complex diagnostic procedures. University hospitals in Germany maintain extensive radiology departments with diverse imaging portfolios.
- Diagnostic Centers:Independent diagnostic centers offer specialized imaging services, often focusing on efficiency and patient throughput. The shift toward decentralized care across Europe benefits these centers, driving equipment procurement.
- Specialty Clinics:These include cardiology, oncology, and orthopedic clinics, which integrate specific imaging modalities relevant to their medical focus. Smaller specialty clinics in the Netherlands are expanding their use of portable ultrasound devices.
- Ambulatory Surgical Centers:These facilities perform outpatient surgeries and require imaging for pre-operative assessment and post-operative follow-up. Ambulatory centers in Switzerland increasingly integrate compact imaging solutions.
- Research Institutions:Academic and private research organizations use advanced imaging for clinical trials, disease mechanism studies, and technological development. Leading research universities in the UK invest in cutting-edge imaging for scientific discovery.
Radiology Departments remains the traditional core. Diagnostic Centers shows accelerated growth in decentralized models.
Deployment Type:
The deployment of medical imaging solutions in Europe is increasingly influenced by digital transformation and regulatory frameworks governing data management.
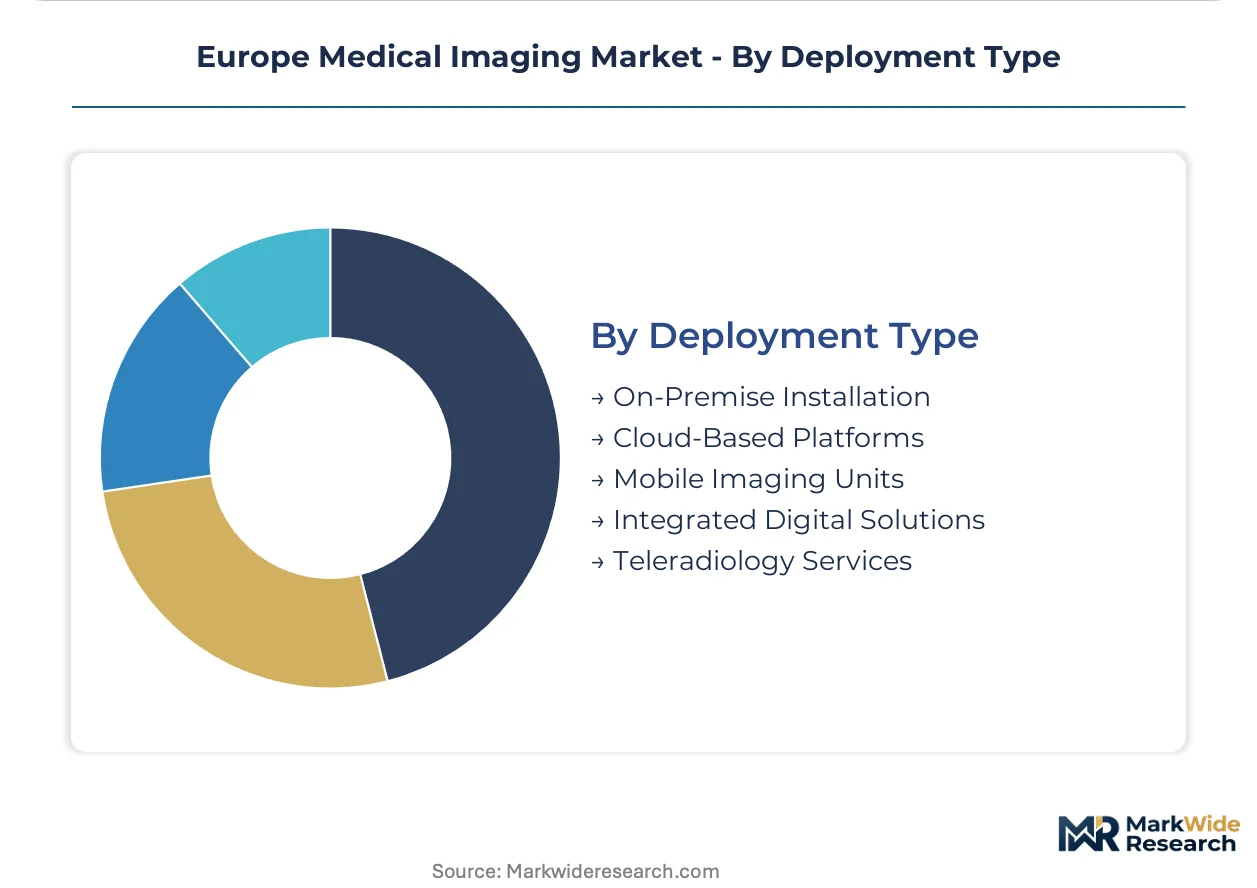
- Cloud-Based Platforms:These platforms host imaging data and software applications remotely, offering scalability and accessibility. The General Data Protection Regulation (GDPR) sets strict rules for patient data management on these platforms across the EU.
- Teleradiology Services:These services enable remote interpretation of medical images by radiologists, optimizing resource allocation and improving access to specialized expertise. Eastern European nations offer a significant opportunity for robust teleradiology network expansion.
- On-Premise Installation:Traditional deployment involves installing imaging systems and associated servers directly within healthcare facilities. Large hospital networks in France continue to rely on on-premise solutions for core imaging infrastructure.
- Mobile Imaging Units:These portable units bring imaging capabilities directly to patients or remote locations, enhancing accessibility. Rural healthcare providers in Scandinavia utilize mobile imaging units for outreach programs.
- Integrated Digital Solutions:These encompass software and hardware combinations that streamline imaging workflows, from acquisition to archiving and reporting. Healthcare systems in Belgium prioritize integrated digital solutions for enhanced operational efficiency.
Traditional On-Premise Installation solutions maintain operational stability. Digital transformation efforts prioritize Cloud-Based Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced medical technology exports to other EU nations underpin the regional market for high-end imaging systems. This trade flow supports technology dissemination and infrastructure upgrades across the continent. Demand for diagnostic equipment remains robust across diverse European healthcare systems.
Germany
Demand for high-end MRI modalities for neurological and oncological diagnostics drives equipment procurement. The EU's MDR mandates stringent clinical evidence for new devices, influencing product development. Munich's medical technology cluster actively develops AI-powered diagnostic software for advanced imaging platforms.
United Kingdom
Rising prevalence of chronic conditions sustains demand for advanced diagnostic imaging, particularly in cardiology and oncology. The UK's National Health Service (NHS) increasingly favors managed equipment services to control operational costs. London's academic medical centers lead research into novel imaging biomarkers and AI integration.
France
Specialized neurology clinics frequently deploy advanced imaging for patient care, emphasizing high-resolution CT and MRI systems. The CNIL (Commission Nationale de l'Informatique et des Libertés) enforces GDPR compliance for patient data management in teleradiology services. Paris's biomedical research institutions collaborate on hybrid imaging modalities for comprehensive cancer staging.
Italy
Countries with pronounced aging populations, such as Italy, sustain high demand for cardiology diagnostics and neurodegenerative disease assessment. The Italian Ministry of Health guides procurement of advanced diagnostic tools to support regional healthcare infrastructure. Milan's university hospitals are early adopters of AI-powered image reconstruction for improved diagnostic accuracy.
Poland
Expanding organized screening programs for oncology, supported by national initiatives, stimulate demand for mammography and CT systems. The EU's Beating Cancer Plan provides funding incentives for modernizing diagnostic equipment in Eastern European nations. Warsaw's emerging diagnostic centers are investing in compact ultrasound devices for decentralized patient care.
Europe Medical Imaging Market Key Industry Players
Player mix skews toward large, integrated medical technology providers offering comprehensive imaging portfolios across various modalities. The European market exhibits significant consolidation around a few global entities that command substantial market share in high-end segments. Strategic archetypes include integrated hardware-software solution providers, specialized diagnostic equipment manufacturers, and emerging AI-driven software developers. These firms primarily engage in portfolio diversification, strategic partnerships, and technology licensing to extend their market reach and technological capabilities, continually adapting to evolving clinical demands.
Within the integrated solution providers tier, Siemens Healthineers, a Germany-based entity, exemplifies leadership in high-end MRI systems. Philips Healthcare, a Netherlands-headquartered technology company, occupies a strong position with its specialized ultrasound and integrated digital solutions. GE Healthcare, a global diversified company, anchors its presence through an extensive service network and broad product portfolio across the continent. These entities represent the established market structure, offering diverse imaging modalities that cater to complex clinical needs in large hospital settings and diagnostic centers. Their offerings span from advanced hardware to sophisticated software platforms.
| Leading Market Players |
|---|
| Canon Medical Systems |
| Hologic |
| Siemens Healthineers |
| Shimadzu |
| Esaote |
| Philips Healthcare |
| FUJIFILM |
| Elekta |
| GE Healthcare |
| Others |
Cost & Logistics Intelligence
Typical lead times for high-end MRI systems, extending to 12-18 months, directly reflect the complex, multi-tiered supply chain and contribute to vendor pricing power for specialized components.
Pricing Analysis
The pricing gap between current-generation and next-generation medical imaging systems is widening, driven by advanced software functionalities and AI integration. Per-unit transactional sales dominate for hardware, complemented by subscription-based models for AI software and managed services. Brand premium from established players and the level of after-sales service significantly differentiate pricing. Pricing softness for commodity X-ray systems stems from public healthcare budget constraints in Eastern Europe. Smaller specialty clinics are most price-sensitive for ultrasound devices, while large university hospitals prioritize advanced features.
Supply Chain Analysis
Inventory levels for critical components like superconducting magnets remain tight, reflecting concentrated manufacturing in a few global hubs. Manufacturing of high-performance X-ray tubes primarily concentrates in Germany and Japan. The supply chain relies on rare earth elements for magnets and specialized semiconductors for digital detectors. Component supply concentration creates single-source vulnerability for advanced imaging modalities. Downstream distribution runs through established direct sales forces and specialized medical equipment distributors across Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Medical Imaging Market is a high-growth disruption, fundamentally reshaped by the rapid integration of artificial intelligence into diagnostic workflows.
For Market Incumbents:
Fortify market leadership through strategic investment in auditable AI development, ensuring compliance with the EU's upcoming AI Act. Consolidate service networks across Eastern Europe and deepen partnerships with university hospitals for clinical validation of new platforms. This counters the rising threat from specialized AI software developers and enhances system utilization. Invest in advanced R&D for hybrid imaging modalities to maintain technological superiority.
For New Entrants and Emerging Players:
A streamlined CE marking pathway for AI-driven diagnostic software offers a critical entry point for new market players. Target underpenetrated teleradiology networks in Eastern European nations and expand point-of-care ultrasound solutions for general practitioners. Develop user-friendly cloud-based platforms that simplify data management and ensure GDPR compliance. This strategy leverages technological agility against established hardware-centric models.
For Investors and Strategic Acquirers:
Long-term, this sits as a technology consolidation play because advanced imaging systems require significant R&D and regulatory navigation. Seek out specialized AI software developers with proven clinical validation or compact ultrasound manufacturers with strong distribution. The successful implementation rates of AI-powered diagnostic tools in major European hospital networks will signal further market maturation. Focus on firms with strong intellectual property and regulatory expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Software Development | Investing in AI algorithms improves diagnostic accuracy and workflow efficiency for radiologists. |
| Managed Equipment Services Expansion | Offering comprehensive service packages attracts public healthcare systems seeking predictable operational costs. |
| Teleradiology Network Partnership | Collaborating with teleradiology providers expands access to specialized interpretations in underserved regions. |
| Portable Ultrasound Innovation | Developing compact, user-friendly devices captures demand from smaller specialty clinics and general practices. |
| Hybrid Imaging R&D | Advancing PET/CT and PET/MRI technologies serves the premium market segment in comprehensive cancer centers. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary research involved discussions with clinicians, hospital purchasing managers, biomedical engineers, and GPO representatives across Europe. Secondary data included EU MDR documentation, national health statistics, medical device registries, and academic research. This approach facilitated bottom-up market sizing and top-down validation of market trends.
The analytical framework projected market dynamics across the analysis window, integrating historical data with future growth catalysts. Segmentation dimensions modeled included product type, application, end-user, deployment type, and regional adoption patterns. Compound annual growth rates were derived from a multi-factor analysis, accounting for technological advancements and evolving healthcare policies. Key forecast inputs included healthcare expenditure trends and regulatory approval timelines.
Decision-makers should treat outputs as directional under current regulatory and economic assumptions; material deviation would warrant model refresh. Forecasts reflect base assumptions, but significant shifts in EU AI Act implementation or component supply chains could alter projections. Outputs are directional, not point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Stationary Anode CT X-Ray Tube Market
Medical Imaging
C-Arms Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Canada Diagnostic Imaging Equipment Market
Medical Imaging
South America CT Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Open Magnetic Resonance Imaging System Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Europe Mobile Tomography Market