
 Global Spectral Computed Tomography (CT) Market | 2026-2036
Global Spectral Computed Tomography (CT) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spectral Computed Tomography (CT) Market Foresight
Modular system bundling is consolidating buyer choice in spectral CT, with vendors packaging detector hardware, reconstruction software, and service contracts into unified procurement offerings. Siemens Healthineers leverages its dual-source platform to anchor premium hospital contracts across European imaging networks. Canon Medical Systems competes on detector specialization in Japanese academic medical centers. United Imaging Healthcare extends manufacturing scale to control pricing in Chinese diagnostic imaging centers.
Spectral computed tomography uses energy-resolving detectors or rapid kV switching to discriminate X-ray attenuation at multiple energy levels, enabling material decomposition and iodine quantification for tissue characterization. Dual-layer detector CT leads installed base expansion due to simpler workflow integration, while energy-resolving detector CT represents the fastest-growing product category as semiconductor detector materials improve spatial resolution. Oncology imaging commands the largest application share, though cardiovascular diagnostics shows the strongest margin pool expansion as coronary plaque characterization protocols standardize.
FDA 510(k) premarket notification requirements shape device validation timelines in the United States, while EU MDR technical documentation demands are lengthening conformity assessment periods for European market access. Japan's PMDA pharmaceutical and medical device agency maintains distinct software-as-medical-device classifications for AI-enabled reconstruction algorithms. Stakeholders must monitor evolving reimbursement coding for spectral CT-specific procedures across Medicare, NHS England, and Germany's G-DRG system to anticipate capital equipment purchasing cycles.
Market Dynamics
Dual-layer detector maturation is compressing procurement cycles across tertiary hospital networks, as oncology departments demand material decomposition capabilities without workflow disruption. This hardware standardization is forcing reconstruction software vendors to differentiate on quantitative imaging biomarker validation rather than raw image quality.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification timelines for iterative detector hardware upgrades reduce validation bottlenecks for US-based imaging networks. Device manufacturers leverage predicate device databases to compress submission preparation.
- Oncology biomarker quantification:Iodine mapping protocols for tumor perfusion assessment are expanding spectral CT utilization in academic medical centers. Radiation oncology departments require iodine concentration data for treatment response monitoring.
- German hospital consolidation:Tertiary network mergers in Bavaria and North Rhine-Westphalia are centralizing capital equipment purchasing power. Combined procurement entities negotiate multi-system spectral CT contracts with bundled service terms.
Market Restraints
- Semiconductor detector material scarcity:Cadmium zinc telluride crystal growth capacity constraints limit energy-resolving detector production scaling. Two specialized foundries in Japan and Germany control substrate supply.
- EU MDR technical documentation burden:Extended conformity assessment periods for software-as-medical-device classifications delay European market entry. Notified body capacity bottlenecks stretch review timelines to 18-24 months.
- Magnetic resonance angiography substitution:Non-contrast MR techniques for coronary plaque characterization reduce spectral CT differentiation in cardiovascular diagnostics. Cardiology departments with existing MRI infrastructure defer CT capital replacement.
Strategic Opportunities
- Chinese diagnostic imaging center expansion:Tier-2 and Tier-3 city healthcare infrastructure investment creates procurement demand outside Beijing and Shanghai. Provincial hospital networks lack established vendor relationships.
- AI-enabled reconstruction algorithm convergence:Deep learning-based noise reduction paired with photon-counting detector data enables sub-millisievere dose protocols. Radiology departments in pediatric hospitals prioritize dose reduction capabilities.
- Japan PMDA software classification clarity:Distinct regulatory pathways for AI reconstruction modules separate hardware and algorithm approval processes. Vendors can update imaging software without full system re-registration.
Industry Challenges
- Quantitative imaging biomarker standardization:Lack of harmonized iodine concentration measurement protocols across vendor platforms complicates multi-site clinical trials. Radiology societies have not established reference ranges for tissue-specific applications.
- Legacy PACS integration complexity:Spectral CT DICOM datasets with energy-specific image series exceed storage and bandwidth capacity of installed picture archiving systems. Hospital IT departments face infrastructure upgrade costs unrelated to scanner acquisition.
- Dual-energy protocol training gaps:Radiologist and technologist certification programs for material decomposition interpretation lag hardware deployment. Academic medical centers absorb training costs without reimbursement mechanism.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spectral Computed Tomography (CT) Market |
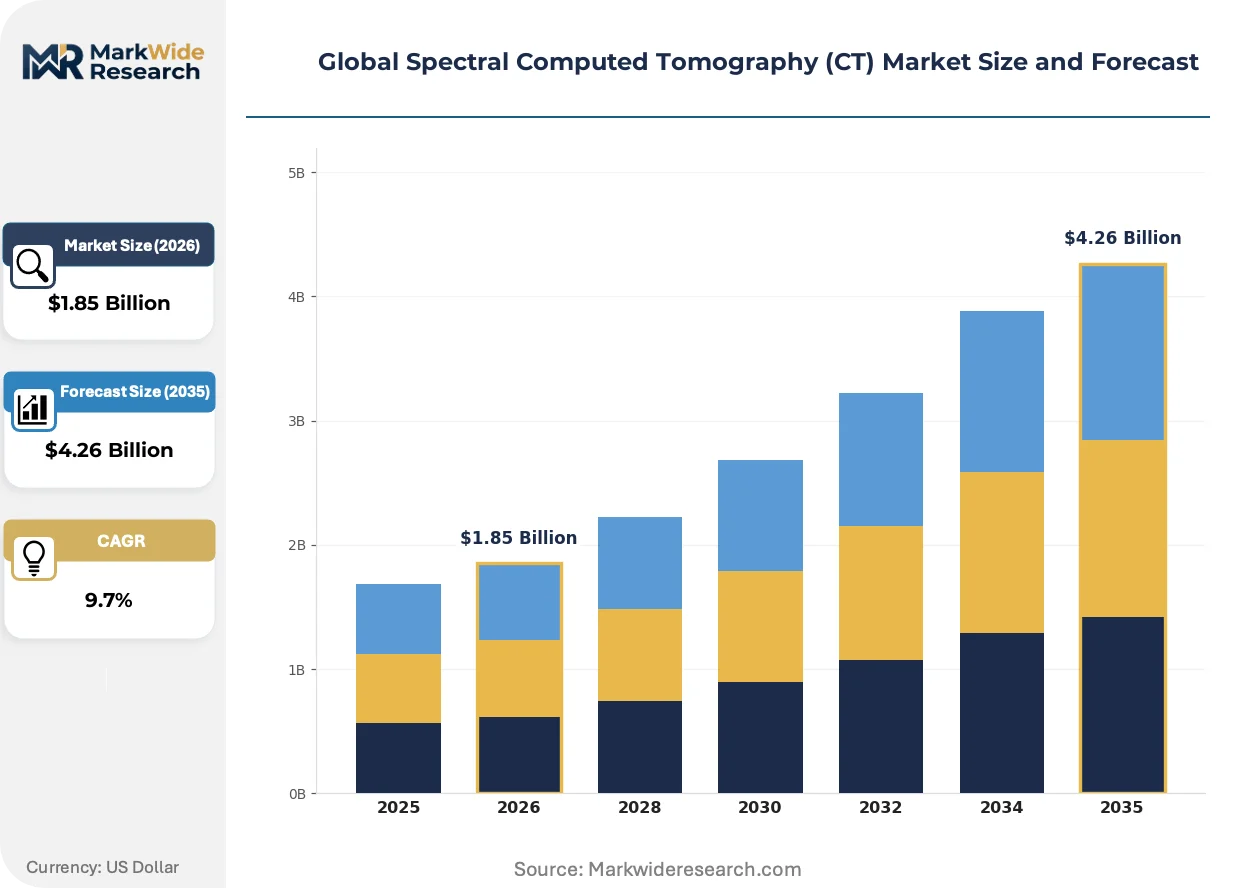
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.26 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dual-Layer Detector CT, Energy-Resolving Detector CT, Dual-Source CT, Rapid kV Switching CT Application: Oncology Imaging, Cardiovascular Diagnostics, Neurological Assessment, Musculoskeletal Analysis End User: Diagnostic Imaging Centers, Research Laboratories, Specialty Clinics, Academic Hospitals Deployment: In-hospital, Outpatient Imaging Facilities, Mobile Imaging Units, Telemedicine Networks |
| Companies Covered | General Electric Company, Koninklijke Philips N.V., Siemens Healthineers, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, United Imaging Healthcare, MARS Bioimaging Ltd, Neusoft Medical Systems, Shenzhen Anke High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spectral Computed Tomography (CT) Market Shifts & Advancements
Photon-counting detector technology is redefining spatial resolution benchmarks while compressing dose requirements, forcing incumbent dual-source architectures to demonstrate clinical equivalence. Regulatory frameworks in major markets are adapting validation requirements to accommodate semiconductor-based detection methods.
Photon-counting CT detectors using cadmium telluride substrates are integrating directly into gantry electronics without scintillator intermediaries. Siemens Healthineers and Philips are deploying first-generation systems in European university hospitals for research protocols. This integration is compressing the performance gap between spectral CT and conventional high-resolution diagnostic CT for lung nodule assessment.
EU MDR Annex XVI expansion is capturing AI-enabled reconstruction algorithms under medical device classification for the first time. Software vendors must now submit clinical validation data for noise reduction and virtual monoenergetic image generation. Japanese academic centers are accelerating local algorithm development to avoid European regulatory dependency for reconstruction modules.
Radiology departments are unbundling service contracts from initial hardware procurement, negotiating separate multi-vendor maintenance agreements after warranty expiration. Large US health systems with in-house biomedical engineering capabilities are absorbing first-line detector calibration and tube replacement. This pattern is most visible in California and Texas hospital networks with centralized fleet management programs.
Global Spectral Computed Tomography (CT) Market Segmentation
Technology heterogeneity in spectral CT creates distinct procurement patterns across hospital networks. Detector architecture choices directly impact workflow integration, dose protocols, and reimbursement eligibility for specific clinical indications.
Product Type:
Replacement cycles vary sharply by detector maturity, with early-generation systems facing accelerated obsolescence as photon-counting platforms enter validation.
- Dual-Layer Detector CT:Scintillator-photodiode stacks with energy-selective signal separation enable material decomposition without specialized tube hardware. Siemens Healthineers anchors installed base expansion across German university hospitals seeking workflow continuity.
- Energy-Resolving Detector CT:Direct-conversion semiconductor substrates discriminate individual photon energies with superior spatial resolution. Cadmium zinc telluride supply constraints from Japanese and German foundries limit production scaling despite radiology demand for pediatric dose reduction.
- Dual-Source CT:Orthogonal X-ray tube arrangements achieve temporal resolution for cardiac imaging through dual-energy acquisition.
- Rapid kV Switching CT:Alternating tube potential between projections approximates spectral separation on conventional detector platforms.
Dual-Layer Detector CT sits at the top of the volume ranking, with Energy-Resolving Detector CT climbing the fastest.
Application:
Clinical indication drives capital allocation priority, with reimbursement coding availability determining departmental purchasing authority.
- Oncology Imaging:Iodine quantification protocols for tumor perfusion monitoring command the largest installed base across academic medical centers. Radiation oncology departments in the United States require standardized iodine concentration data for treatment response assessment.
- Cardiovascular Diagnostics:Coronary plaque characterization and myocardial perfusion analysis generate premium pricing acceptance. Cardiology departments in Germany's G-DRG system negotiate separate reimbursement codes for spectral-derived fractional flow reserve calculations.
- Neurological Assessment:Virtual monoenergetic imaging reduces beam-hardening artifacts in posterior fossa evaluation.
- Musculoskeletal Analysis:Uric acid crystal deposition detection differentiates gout from pseudogout without joint aspiration.
Oncology Imaging dominates current procurement volumes, while Cardiovascular Diagnostics shows the steepest expansion trajectory as plaque protocols standardize.
End User:
Facility type determines service contract structure and software licensing terms, with academic centers demanding research protocol flexibility.
- Diagnostic Imaging Centers:High patient throughput operations prioritize workflow efficiency and technologist training standardization. Networks clustered around tertiary hospitals in China's Tier-2 cities absorb capital costs through provincial government infrastructure subsidies.
- Academic Hospitals:Research mission requirements drive demand for raw data access and algorithm customization. Japanese university medical centers negotiate separate PMDA pathways for internally developed reconstruction software.
- Research Laboratories:Phantom validation studies and biomarker development require spectral calibration stability.
- Specialty Clinics:Focused indications such as urology or rheumatology limit scanner utilization rates.
Diagnostic Imaging Centers lead equipment shipments, with Academic Hospitals gaining share fastest through research-industry partnerships.
Deployment:
Physical installation constraints shape detector selection, with mobile units prioritizing mechanical reliability over spectral sophistication.
- In-hospital:Fixed gantry installations with dedicated power and cooling infrastructure enable full spectral protocol implementation. Tertiary networks in Bavaria consolidate procurement across multiple campuses with standardized dual-layer configurations.
- Outpatient Imaging Facilities:Lower throughput operations balance capital cost against reimbursement rates for spectral-specific procedures. Independent centers in Texas health systems unbundle service contracts to leverage in-house biomedical engineering.
- Mobile Imaging Units:Transport vibration limits and power variability constrain energy-resolving detector deployment.
- Telemedicine Networks:Remote interpretation requirements drive DICOM standardization and bandwidth optimization.
In-hospital deployment captures the majority of spectral CT installations, with Outpatient Imaging Facilities expanding most quickly as reimbursement coding clarifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered dual-source CT architecture at Siemens Healthineers' Forchheim facility, establishing the foundational engineering lineage that now defines spectral imaging hardware standards worldwide. Japanese semiconductor foundries later supplied cadmium zinc telluride substrates for direct-conversion detectors, shifting production gravity toward energy-resolving architectures. China's diagnostic imaging center buildout now absorbs the largest share of new system installations.
United States
Tertiary hospital networks in Texas and California consolidate spectral CT procurement through centralized fleet management programs. FDA 510(k) premarket notification pathways compress validation timelines for iterative detector upgrades. The MD Anderson Cancer Center in Houston anchors multi-system contracts for oncology biomarker quantification protocols.
Germany
Bavarian and North Rhine-Westphalian hospital mergers centralize capital equipment purchasing across consolidated procurement entities. EU MDR conformity assessment requirements lengthen technical documentation review periods to 18-24 months. Siemens Healthineers' Forchheim engineering campus supplies dual-layer detector platforms across European academic networks.
Japan
PMDA maintains distinct software-as-medical-device classifications for AI-enabled reconstruction algorithms, separating hardware and algorithm approval pathways. Japanese academic medical centers negotiate local development rights for internally developed reconstruction modules. Canon Medical Systems anchors detector specialization contracts across Tokyo and Osaka university hospitals.
China
Provincial infrastructure subsidies drive Tier-2 and Tier-3 city diagnostic imaging center expansion outside Beijing and Shanghai. United Imaging Healthcare leverages manufacturing scale to control pricing for hospital networks lacking established vendor relationships. The Yangtze River Delta cluster absorbs capital equipment shipments through government-funded healthcare modernization programs.
Global Spectral Computed Tomography (CT) Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with imaging hardware heritage. Three to five integrated device manufacturers control detector fabrication, reconstruction software, and service contract bundling. Two strategic archetypes dominate: legacy imaging system vendors with installed base migration strategies, and semiconductor-specialized entrants leveraging direct-conversion detector materials. Competitive moves concentrate on multi-system procurement contract consolidation and AI reconstruction algorithm regulatory capture.
Among diversified health technology conglomerates, General Electric Company, Koninklijke Philips N.V., and Siemens Healthineers occupy positions defined by integrated hardware-software-service bundling. These manufacturers exemplify the archetype of vendors leveraging predicate device databases to compress FDA submission timelines. Canon Medical Systems and Fujifilm Holdings Corporation represent the Japanese specialist tier, with geographic naming anchoring their positions within detector material supply chains. United Imaging Healthcare exemplifies scale-driven manufacturing consolidation targeting price-sensitive procurement in emerging diagnostic networks.
| Leading Market Players |
|---|
| General Electric Company |
| Koninklijke Philips N.V. |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| United Imaging Healthcare |
| MARS Bioimaging Ltd |
| Neusoft Medical Systems |
| Shenzhen Anke High-Tech |
| Others |
Supply & Pricing Matrix
German hospital network consolidation across Bavaria and North Rhine-Westphalia is compressing procurement timelines and forcing vendors toward bundled service contracts with extended warranty terms. This buyer-side concentration is reshaping how detector manufacturers price hardware-software packages and allocate engineering resources across European academic medical centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates spectral CT procurement, with premium tiers commanding acceptance through photon-counting detector performance and bundled AI reconstruction modules. Price differentiation rests on FDA 510(k) clearance status and dual-layer detector maturity, with German tertiary networks showing lowest sensitivity due to consolidated purchasing power while Chinese Tier-2 diagnostic imaging centers exhibit acute price responsiveness. Cost compression in economy-tier dual-source systems is intensifying because United Imaging Healthcare's manufacturing scale is resetting baseline expectations.
Supply Chain Analysis
Cadmium zinc telluride crystal supply rests on specialized foundries in Japan and Germany, with substrate production capacity constraining energy-resolving detector scaling despite radiology demand. Raw material dependencies center on high-purity semiconductor substrates, precision scintillator ceramics, and gantry-grade bearing assemblies. Single-source vulnerability runs through Japanese specialty chemical producers controlling detector material purification. Distribution runs through direct vendor-hospital contracts for premium installations and provincial government procurement channels for Chinese infrastructure buildouts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The spectral CT market reads as a late-cycle quality story where procurement committees now prioritize quantitative imaging biomarker validation over raw hardware specifications. This demand-shift toward premium detector architectures rewards vendors with integrated software-service bundling capabilities.
For Market Incumbents: Anticipate photon-counting detector commoditization by accelerating backward integration into cadmium telluride substrate production and securing captive supply agreements with Japanese foundries. Defensive positioning requires embedding AI reconstruction algorithms within hospital IT infrastructure to raise switching costs against modular software competitors. Magnetic resonance angiography substitution in cardiovascular diagnostics represents the most acute substitution threat requiring clinical equivalence demonstrations. For New Entrants and Emerging Players: Direct-to-radiologist digital education platforms offer lower customer acquisition costs than traditional capital equipment sales cycles. White-space concentration sits in Chinese Tier-3 city diagnostic imaging centers lacking established vendor relationships and Japanese academic medical centers seeking PMDA-fast-tracked reconstruction algorithm partnerships. Target procurement committees at provincial hospital networks in the Yangtze River Delta with software-first positioning that decouples algorithm licensing from hardware commitments. For Investors and Strategic Acquirers: Asymmetric upside sits with semiconductor-specialized detector material producers positioned upstream of diversified imaging conglomerates. Long-term viability favors vendors controlling both direct-conversion detector fabrication and regulatory-cleared quantitative imaging protocols. Watch FDA 510(k) clearance velocity for photon-counting platforms as the signal indicating whether dual-layer architectures face accelerated obsolescence or extended replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Platform Launch | Siemens Healthineers and Philips are deploying first-generation cadmium telluride systems in European university hospitals for research protocols. |
| AI Reconstruction Algorithm Regulatory Capture | EU MDR Annex XVI expansion now classifies noise reduction software as medical devices requiring clinical validation submissions. |
| Hospital System Partnership Consolidation | Bavarian tertiary network mergers are centralizing multi-system spectral CT contracts with bundled service terms across campuses. |
| Backward Integration into Detector Materials | Japanese and German foundries control cadmium zinc telluride substrate supply, creating acquisition targets for imaging conglomerates. |
| Reimbursement Strategy Development | Germany's G-DRG system and Medicare coding evolution determine capital equipment purchasing cycles across oncology departments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee chairs, biomedical engineering directors, GPO contracts managers, and radiology department heads with secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, and hospital procurement system records. Bottom-up installation tracking across tertiary networks and top-down revenue triangulation against diversified health technology conglomerate disclosures anchored market sizing.
Segment-weighting across detector architecture, clinical application, and facility type drove analytical framework construction over the projection horizon. Modeled dimensions included dual-layer versus energy-resolving versus photon-counting technology platforms, oncology versus cardiovascular versus neurological indication splits, and academic hospital versus diagnostic imaging center versus research laboratory end-user categories. CAGRs derived from replacement cycle analysis, biomarker protocol adoption curves, and reimbursement coding expansion trajectories.
The model assumes a particular technology adoption path; alternative pathways for photon-counting detector maturation would alter the outlook if semiconductor material yields fail to scale or if AI reconstruction algorithms achieve diagnostic equivalence on legacy dual-source hardware. Forecasts reflect documented assumptions regarding hospital consolidation velocity, regulatory review period stability, and iodine quantification protocol standardization. A small set of named triggers—PMDA software classification enforcement shifts, cadmium zinc telluride supply disruptions, and Medicare spectral-specific reimbursement decisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Handheld Dental X-Ray Systems Market
Medical Imaging
Magnetic Resonance Imaging Equipment Coils Market
Medical Imaging
Cephalometric X-Ray System Market
Medical Imaging
Medical Image Analysis Software Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Global Orthopedic Imaging Equipment Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
United States Mammography Market
Medical Imaging
Mammography Market
Medical Imaging
X-Ray Devices Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market