
 North America and Europe Preclinical Medical Device Testing Services Market | 2026-2036
North America and Europe Preclinical Medical Device Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Preclinical Medical Device Testing Services Market Intelligence
A shortage of GLP-certified toxicologists and veterinary pathologists is reorganizing how sponsors allocate preclinical programs across contract laboratories. Charles River Laboratories International, Inc. leverages its integrated safety assessment platform to anchor large-device submissions in the United States. Eurofins Scientific competes through specialized biocompatibility testing capacity positioned near European notified body concentrations.
Preclinical medical device testing services encompass the in vitro and in vivo evaluation of device safety, performance, and biological interaction prior to human clinical trials, employing ISO 10993 biocompatibility protocols, sterilization assurance level verification, and human factors validation. These services reduce regulatory submission risk and accelerate time-to-market for implantable and diagnostic technologies. Biological evaluation commands premium pricing due to complex study designs and extended duration requirements, while sterilization validation sustains steady volume from reusable surgical instrument portfolios. Usability testing extends fastest among segments as FDA human factors guidance tightens for high-risk device categories.
FDA's 21 CFR Part 58 GLP regulations and the EU Medical Device Regulation's reinforced notified body oversight shape study design standards and documentation intensity across both regions. REACH substance restrictions and ISO 10993-1 biological evaluation frameworks further dictate material selection and extractables testing protocols. Sponsors must monitor evolving MDR transition timelines and FDA breakthrough device designation pathways to calibrate preclinical investment timing against commercialization windows.
Market Dynamics
GLP-certified laboratory capacity constraints across the United States and Germany are forcing sponsors to fragment preclinical programs across multiple contract research organizations, extending study timelines and inflating program management overhead.
Growth Catalysts
- EU MDR biological evaluation mandates:The regulation's reinforced Annex I requirements for material characterization and biocompatibility documentation are expanding outsourcing volumes for ISO 10993-1 testing protocols.
- Orthopedic implant innovation cycles:Additive manufacturing adoption in hip and knee reconstruction systems is generating novel surface topography and material combinations requiring expanded preclinical validation.
- FDA breakthrough device pathway:Expedited review timelines for designated devices are compressing preclinical development schedules and intensifying demand for integrated safety assessment platforms.
Market Restraints
- GLP toxicologist scarcity:The limited pool of certified study directors in the United States and Germany is creating bottlenecks for large-animal implantation studies and extending lead times.
- Specialized vivarium infrastructure costs:Construction and maintenance of large-species surgical facilities requires capital intensity that constrains new laboratory entry and concentrates supply.
- ISO 10993-18 extractables testing complexity:The chemical characterization framework's evolving interpretation by notified bodies is generating protocol amendments and retesting cycles.
Strategic Opportunities
- Central and Eastern European laboratory expansion:Poland and the Czech Republic offer GLP-compliant capacity at cost structures below Western European benchmarks with EU MDR recognition.
- Human factors validation services:FDA's tightened guidance for high-risk device categories is creating unmet demand for usability engineering integrated with biocompatibility programs.
- Digital pathology and AI-assisted histopathology:Machine learning integration with toxicologic pathology workflows promises accelerated study reporting and competitive differentiation.
Industry Challenges
- Veterinary pathologist recruitment:The specialized expertise required for medical device implant site evaluation faces demographic retirement waves and limited training pipeline replacement.
- Cross-border sample logistics:Temperature-controlled transport of biological specimens between United States and European Union laboratories encounters customs complexity and chain-of-custody documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Preclinical Medical Device Testing Services Market |
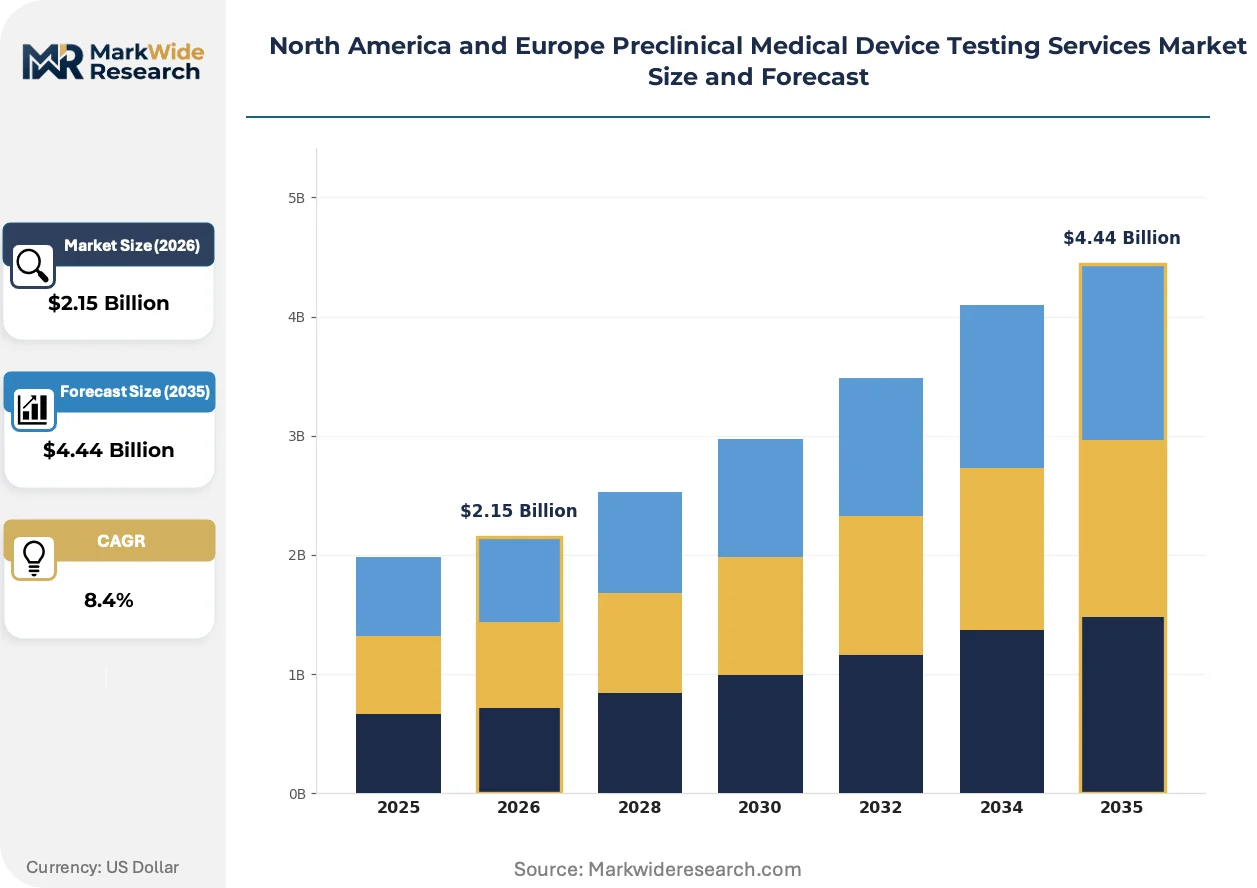
| Market Size in 2026 | $2.15 Billion |
| Market Size in 2035 | $4.44 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biocompatibility Testing, Sterilization Validation, Usability Testing, Biological Evaluation Product Type: Implants, Diagnostic Devices, Surgical Instruments, Monitoring Devices End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations Delivery Mode: Onsite Testing, Remote Testing, Outsourced Services, Blended Approach |
| Companies Covered | Charles River Laboratories International, Inc., WuXi AppTec, Eurofins Scientific, SGS SA, Intertek Group Plc, TÜV SÜD AG, NAMSA, Nelson Labs, Toxikon, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Preclinical Medical Device Testing Services Market Strategic Shifts & Innovations
Preclinical testing workflows are converging around data integrity automation and alternative model validation, compressing traditional study designs while expanding the evidentiary base for regulatory submissions.
Microphysiological systems incorporating organ-on-chip architectures are miniaturizing biocompatibility screening for blood-contacting devices. Cardiovascular implant manufacturers are adopting these platforms for early-phase thrombogenicity assessment, reducing large-animal study dependencies. The technology is miniaturizing material interaction data generation from months to weeks, though complete replacement of in vivo endpoints remains constrained by ISO 10993-4 hemocompatibility validation requirements.
FDA's 2016 guidance on use of ISO 10993-1 and subsequent updates to biological evaluation planning have tightened expectations for chemical characterization prior to biocompatibility testing. Device sponsors must now complete extractables and leachables profiling before initiating standard biocompatibility assays, reordering program sequencing and extending front-end timelines. High-risk implantable categories including permanent contact devices face the most intensive documentation scrutiny and are responding by integrating toxicologists earlier in design control processes.
Consolidated service contracting is displacing fragmented vendor management across large device portfolios. Mid-cap orthopedic and cardiovascular manufacturers are bundling biocompatibility, sterilization validation, and human factors services under single-provider frameworks to reduce program coordination overhead. The United States market exhibits the most pronounced concentration of procurement authority, with procurement functions centralizing vendor selection at headquarters level rather than delegating to individual product development teams.
North America and Europe Preclinical Medical Device Testing Services Market Segmentation
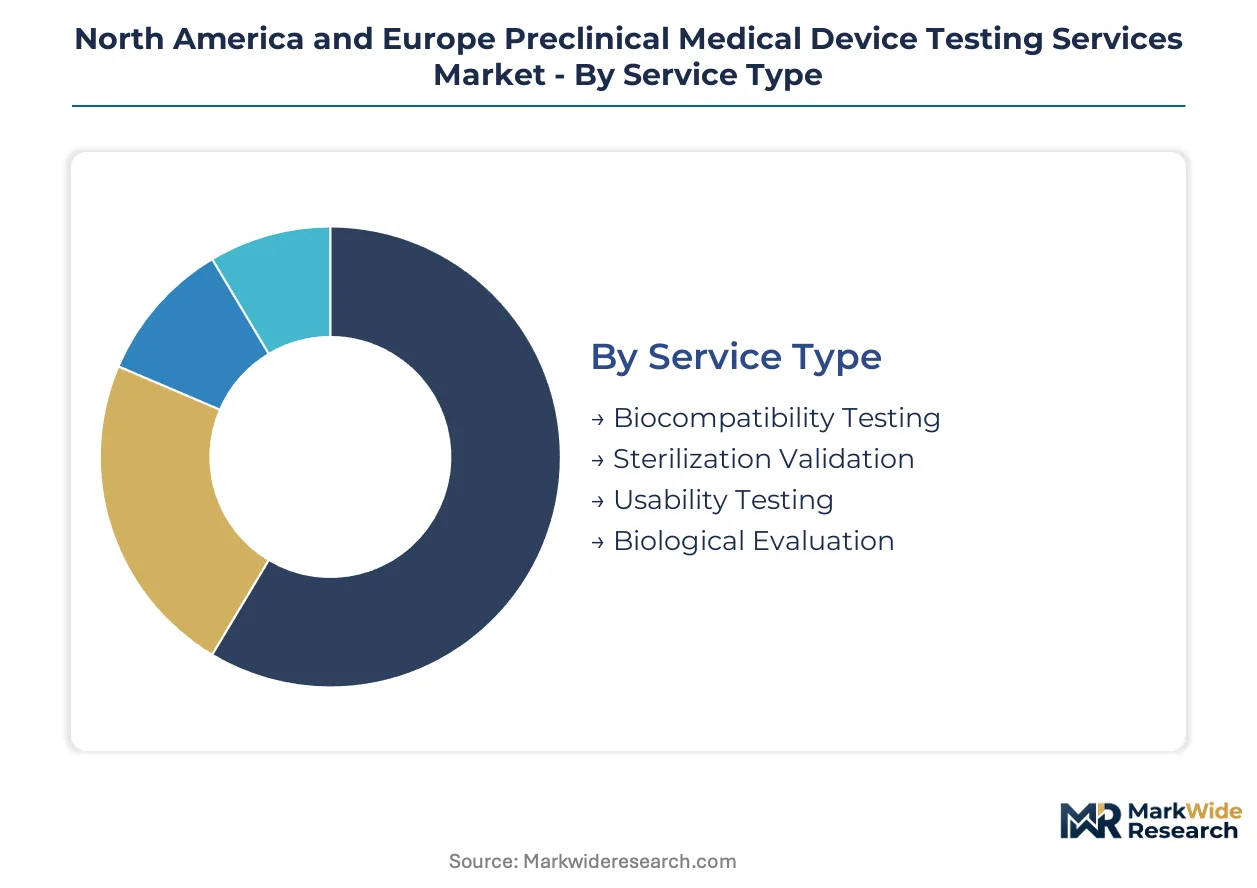
Preclinical testing procurement fragments across service capabilities, device categories, and sponsor operational models. Regulatory pathway requirements and sponsor internal capacity determine how testing budgets distribute across these dimensions.
Service Type:
FDA 21 CFR Part 58 GLP requirements and EU MDR Annex I mandates create divergent compliance burdens that reshape how sponsors prioritize service investments across biological and mechanical validation domains.
- Biocompatibility Testing:ISO 10993-1 protocol execution for cytotoxicity, sensitization, and irritation endpoints dominates outsourcing volume. Orthopedic implant manufacturers in Germany and the United States concentrate demand here as surface modification technologies proliferate.
- Biological Evaluation:Comprehensive safety assessment integrating toxicology, pathology, and risk characterization commands premium pricing. Extended study durations and GLP study director scarcity in the United States and Germany constrain capacity expansion.
- Sterilization Validation:Steam, ethylene oxide, and radiation sterilization assurance level verification sustains steady demand from reusable surgical instrument portfolios.
- Usability Testing:FDA human factors guidance compliance for high-risk device categories is climbing the fastest among service types.
Established volume favors Biocompatibility Testing; emerging adoption favors Usability Testing.
Product Type:
Implant contact duration and invasiveness tier determine testing intensity, with permanent contact devices requiring the most extensive biological evaluation against ISO 10993-1 frameworks.
- Implants:Permanent and prolonged contact devices including orthopedic, cardiovascular, and neurological systems demand the most extensive preclinical validation. Additive manufacturing adoption in hip and knee reconstruction is generating novel surface topography combinations requiring expanded testing protocols.
- Surgical Instruments:Reusable and single-use instrument portfolios drive sterilization validation volume across United States and European manufacturing clusters.
- Diagnostic Devices:In vitro diagnostic and imaging equipment requires focused biocompatibility assessment for patient-contacting components.
- Monitoring Devices:Wearable and implantable cardiac and glucose monitoring systems bridge biocompatibility and electrical safety testing requirements.
Implants capture the highest testing spend per device; Monitoring Devices are gaining share fastest as remote patient monitoring expands.
End User:
Sponsor scale and regulatory sophistication determine whether testing programs execute through internal laboratories, academic partnerships, or contract research organizations.
- Contract Research Organizations:Mid-cap device manufacturers without captive GLP facilities depend on CROs for complete preclinical program execution. Charles River Laboratories and Eurofins Scientific anchor large-device submissions through integrated platforms.
- Pharmaceutical Companies:Diversified life science conglomerates with device divisions leverage existing toxicology infrastructure for combination product development.
- Biotechnology Firms:Emerging device developers concentrate demand for bundled biocompatibility and sterilization validation services.
- Academic Institutions:University-affiliated research hospitals contribute early-stage validation and training pipeline development for veterinary pathologists.
Contract Research Organizations dominate transaction volume; Biotechnology Firms are expanding their share of outsourced testing fastest.
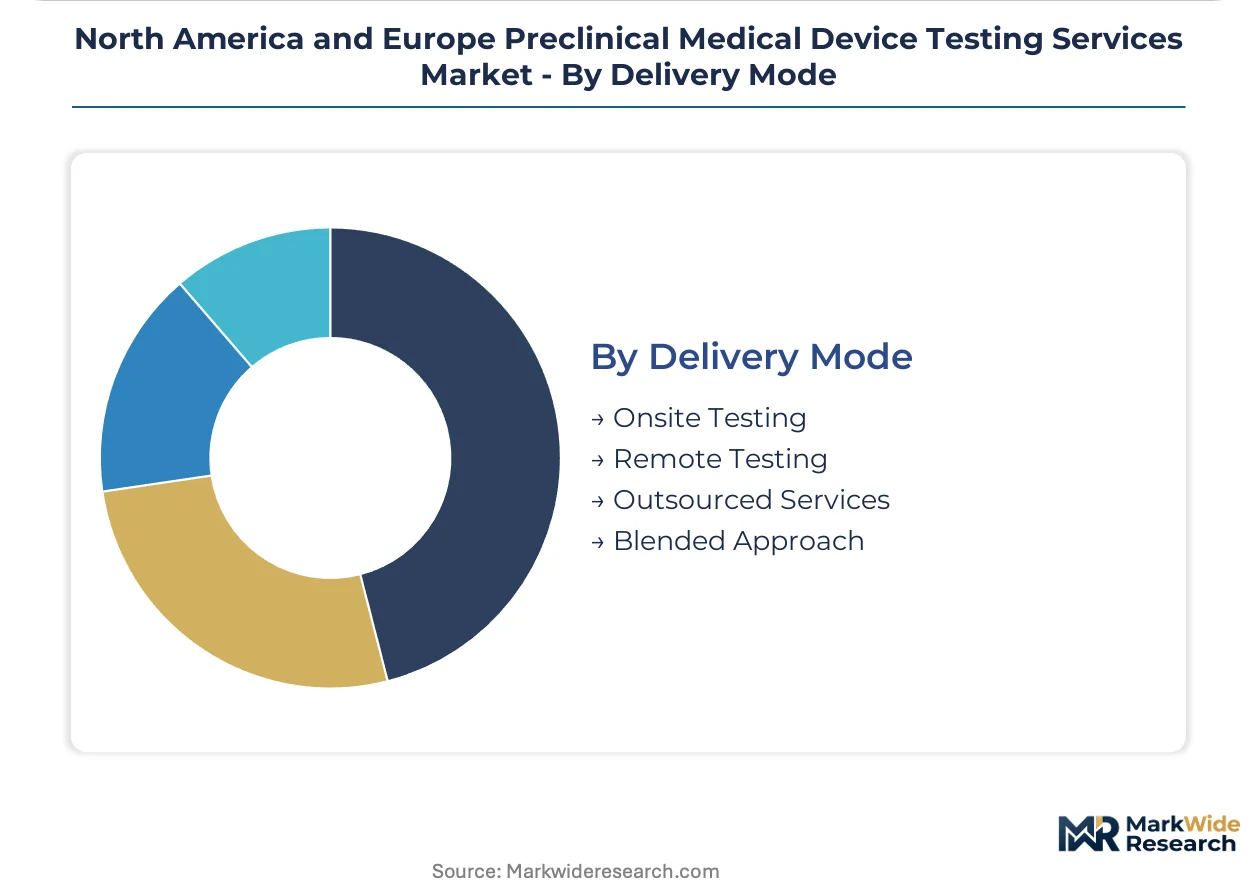
Delivery Mode:
Study complexity and specimen handling requirements constrain remote delivery adoption, though digital pathology and data analytics enable partial decentralization.
- Outsourced Services:Full program delegation to specialized laboratories remains the dominant model for sponsors without GLP-certified internal capacity. Germany's medical technology cluster concentrates European demand.
- Onsite Testing:Large-cap manufacturers with captive vivarium and pathology infrastructure retain critical safety assessment functions in-house.
- Blended Approach:Hybrid models combining sponsor oversight with CRO execution are displacing fragmented vendor management across large device portfolios.
- Remote Testing:Digital pathology and telepathology consultation enable partial decentralization of histopathology review, though specimen logistics remain concentrated.
Outsourced Services anchor current volume; Blended Approach is displacing fragmented procurement fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Preclinical medical device testing services in North America and Europe diverge in procurement concentration: United States sponsors favor consolidated vendor frameworks, while European demand fragments across notified body jurisdictions and national laboratory clusters.
United States
FDA's 21 CFR Part 58 GLP framework and breakthrough device designation pathways compress preclinical timelines for cardiovascular and orthopedic innovators. Charles River Laboratories anchors large-device submissions through integrated safety assessment platforms. Greater Boston and Research Triangle Park concentrate GLP-certified vivarium capacity for implantation studies.
Germany
EU MDR Annex I biological evaluation mandates expand outsourcing volumes for ISO 10993-1 testing from Tübingen and Munich medical technology clusters. TÜV SÜD AG leverages notified body proximity to anchor sterilization validation programs. Baden-Württemberg's surgical instrument manufacturers drive steady demand for reusable device assurance testing.
United Kingdom
Post-Brexit UKCA marking requirements and retained EU MDR alignment create dual compliance burdens for Cambridge and Oxfordshire device developers. MHRA recognition of EU testing data preserves cross-border laboratory relationships. London's contract research infrastructure specializes in human factors validation for high-risk diagnostic systems.
France
ANSM oversight of active implantable devices concentrates biological evaluation demand in Paris-Saclay and Lyon biotech corridors. REACH substance restrictions dictate extractables testing protocols for polymer-based cardiovascular components. Strasbourg's veterinary pathology training programs address regional study director scarcity.
Poland
GLP-compliant laboratory capacity in Warsaw and Kraków offers cost structures below Western European benchmarks with full EU MDR recognition. Central European location enables cross-border specimen logistics to German notified bodies. Emerging CRO infrastructure targets sterilization validation outsourcing from mid-cap device manufacturers.
North America and Europe Preclinical Medical Device Testing Services Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with consolidated procurement authority in the United States favoring end-to-end platform providers while European demand sustains regional niche laboratories. Three archetypes dominate: full-service CROs with captive GLP vivarium infrastructure, specialized biocompatibility laboratories positioned near notified body concentrations, and diversified testing conglomerates leveraging cross-industry toxicology platforms. Competitive moves concentrate on M&A-driven geographic expansion into Central and Eastern European GLP capacity and strategic partnerships integrating digital pathology workflows.
Within the integrated platform tier, Charles River Laboratories International, Inc. and Eurofins Scientific occupy anchor positions for large-device submissions across both regions. Charles River exemplifies the North American full-service archetype through its unified safety assessment infrastructure, while Eurofins Scientific represents the European specialist model with biocompatibility capacity clustered near regulatory body concentrations. WuXi AppTec sits within the diversified testing conglomerate archetype, leveraging cross-sector toxicology expertise.
| Leading Market Players |
|---|
| Charles River Laboratories International, Inc. |
| WuXi AppTec |
| Eurofins Scientific |
| SGS SA |
| Intertek Group Plc |
| TÜV SÜD AG |
| NAMSA |
| Nelson Labs |
| Toxikon, Inc. |
| Others |
Cost & Logistics Intelligence
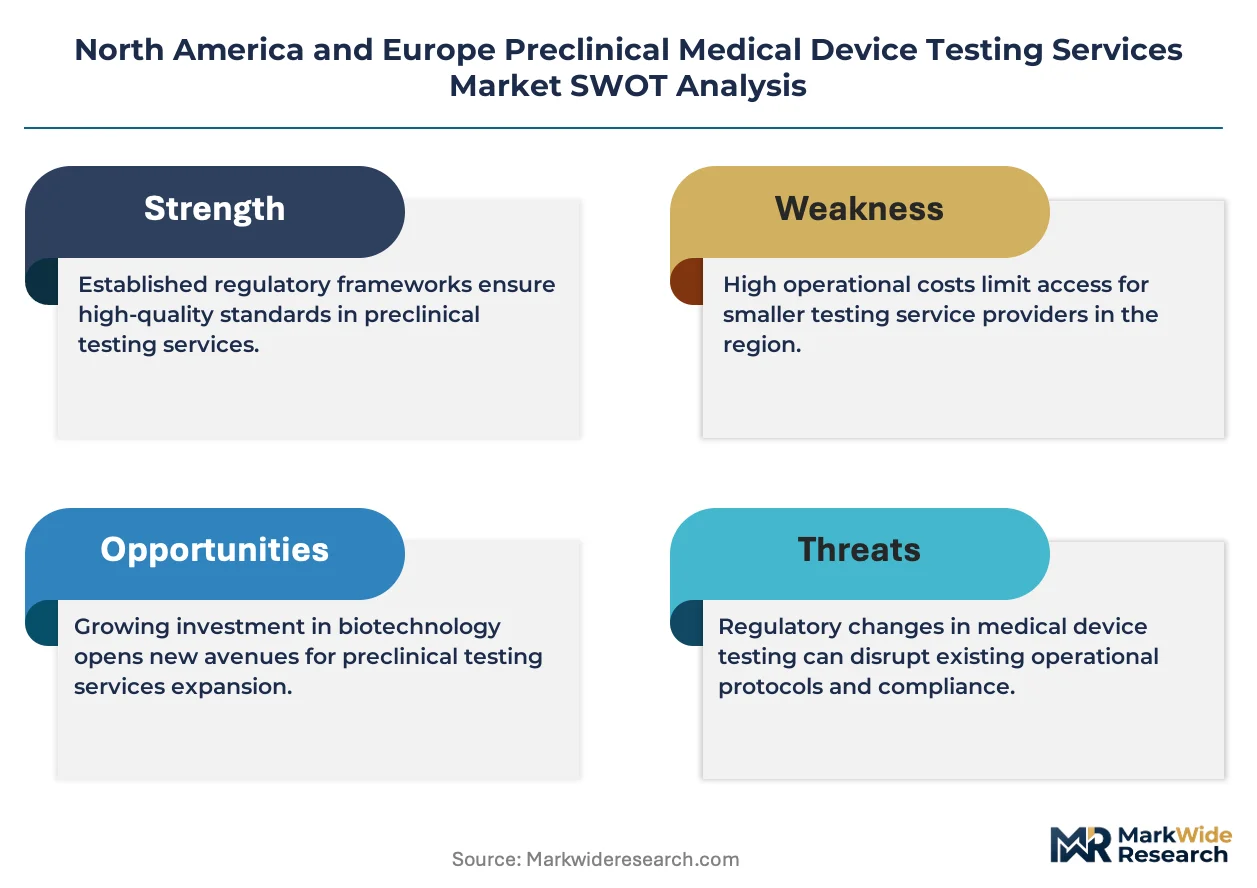
Long-term capacity reservation contracts with GLP-certified laboratories lock in study director access and price visibility for sponsors navigating FDA 21 CFR Part 58 and EU MDR compliance timelines. These arrangements concentrate procurement power among mid-cap device manufacturers while fragmenting spot-market availability for smaller sponsors.
Pricing Analysis
Project-based pricing dominates preclinical testing, with biological evaluation commanding premium rates against sterilization validation due to GLP study director scarcity in the United States and Germany. Price differentiation rests on certification tier—FDA GLP-compliant studies carry 15-25% premiums over non-GLP protocols—and volume scale, with bundled service frameworks reducing per-study overhead. Cost compression in standard biocompatibility testing is intensifying because Central European laboratory expansion introduces price-competitive capacity. Biotechnology firms exhibit highest price sensitivity due to constrained development budgets, while large-cap orthopedic manufacturers prioritize timeline certainty over rate negotiation.
Supply Chain Analysis
Inbound logistics costs for temperature-controlled biological specimens encounter customs complexity at transatlantic trade lanes, particularly for implantation study tissues requiring chain-of-custody documentation. Laboratory capacity concentrates in the United States, Germany, and Poland, with the latter offering cost structures below Western European benchmarks. The supply chain draws from specialized vivarium infrastructure, GLP-certified reagent suppliers, and veterinary pathology talent pools concentrated in academic medical centers. Single-source vulnerability sits with study director availability for large-animal implantation protocols. Distribution runs through direct CRO-sponsor relationships with limited intermediary presence.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America and Europe preclinical medical device testing services market tracks a cyclical recovery pattern as EU MDR transition deadlines compress outsourcing demand into concentrated windows. Orthopedic implant innovation cycles and FDA breakthrough device designations drive this cadence.
For Market Incumbents: Shield integrated safety assessment platforms from price erosion by anchoring large-device submissions through captive GLP vivarium infrastructure in Greater Boston and Research Triangle Park. Capacity addition in Poland and the Czech Republic defends margin position against Western European cost benchmarks while preserving EU MDR recognition. Certification investment in digital pathology workflows creates defensible differentiation against emerging CRO infrastructure. For New Entrants and Emerging Players: Differentiate on human factors validation services integrated with biocompatibility programs, where FDA tightened guidance for high-risk device categories generates unmet demand. Poland and the Czech Republic represent the most penetrable geographies, offering GLP-compliant capacity at cost structures below German clusters. A go-to-market angle targeting mid-cap cardiovascular manufacturers without captive pathology infrastructure accelerates initial contract capture. For Investors and Strategic Acquirers: Capital is best deployed toward specialized biocompatibility laboratories with notified body proximity and digital pathology integration capability across the five-to-ten year viability window. Acquisition targets should exhibit established ISO 10993-1 protocol execution capacity and veterinary pathologist training pipeline relationships. The signal to watch is EU MDR transition timeline extensions, which would compress near-term outsourcing demand and reset valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Capacity Expansion | Poland and Czech Republic laboratory buildout captures EU MDR outsourcing demand at cost-advantaged positions. |
| Digital Pathology Integration | AI-assisted histopathology workflows accelerate study reporting timelines for FDA breakthrough device submissions. |
| Human Factors Service Bundling | Usability engineering integration with biocompatibility programs addresses FDA tightened guidance compliance. |
| Notified Body Proximity Positioning | Tübingen and Munich cluster concentration anchors sterilization validation programs for German manufacturers. |
| Veterinary Pathologist Pipeline Development | Strasbourg and academic medical center partnerships address demographic retirement waves in toxicologic pathology. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) and PMA submission databases, EU MDR notified body guidance documents, and ISO 10993 technical committee publications. Primary interviews engaged regulatory affairs directors at orthopedic and cardiovascular device manufacturers, GLP study directors at contract research organizations, and hospital purchasing committee representatives. Bottom-up triangulation across service-type procurement volumes and top-down validation against national medical technology trade association data ensured cross-verification.
Segmentation dimensions modeled include service capability (biocompatibility testing, biological evaluation, sterilization validation, usability testing), device category (implants, surgical instruments, diagnostic devices, monitoring devices), sponsor operational model (contract research organization, pharmaceutical company, biotechnology firm, academic institution), and delivery mode (outsourced services, onsite testing, blended approach, remote testing). CAGRs were derived from regression analysis of historical outsourcing expenditure patterns and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporate EU MDR transition timeline assumptions and FDA breakthrough device designation pathway utilization rates.
The analysis sits within stated boundaries; outcomes outside maintained GLP certification standards, stable EU-UK regulatory recognition frameworks, and continued orthopedic implant additive manufacturing adoption would require recalibration. Forecasts reflect assumptions regarding study director availability, notified body capacity expansion, and cross-border specimen logistics efficiency. Specific risk factors include veterinary pathologist training pipeline constraints, REACH substance restriction amendments affecting extractables testing protocols, and potential EU MDR implementation deadline extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global ADME Toxicology Testing Market
Testing Services
Nipah Virus Testing Market
Testing Services
Platelet Function Testing Market
Testing Services
North America Newborn Screening Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
IVD Quality Control Market
Testing Services
Blood Sugar Tester Market
Testing Services
D-Dimer Testing Market
Testing Services
Global CA 125 Test Market
Testing Services
Toxicology Testing Services Market
Testing Services
Global GI Stool Testing Market
Testing Services
Radiographic Testing Market
Testing Services
Global IVD Regulatory Affairs Outsourcing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market