
 Global 3D Laparoscopy Imaging Market | 2026-2036
Global 3D Laparoscopy Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global 3D Laparoscopy Imaging Market Foresight
A global shortage of surgeons trained in advanced minimally invasive techniques is collapsing the effective deployment rate of 3D laparoscopy suites despite strong hardware availability. Olympus Corporation leverages its integrated endoscope-camera-display ecosystem to dominate high-volume hospital procurement cycles in Asia-Pacific. Karl Storz SE & Co. KG anchors its position through backward integration into precision optical manufacturing, while Siemens Healthineers competes by embedding 3D visualization within broader digital operating-room architectures.
3D laparoscopy imaging refers to stereoscopic surgical visualization systems that render depth-resolved anatomical structures by presenting offset images to each eye through dual-lens endoscopes or computational depth mapping, typically operating at HD or 4K resolution with latency below 50 milliseconds to preserve hand-eye coordination during suturing and dissection. The technology serves to reduce operative errors, shorten procedure duration, and accelerate surgeon training curves in minimally invasive environments. Endoscope systems and cameras command the largest revenue share within product categories due to their central role in every procedure and shorter replacement cycles than displays or insufflators. Stereoscopic vision leads the technology dimension with established clinical validation, while time-of-flight sensors represent the fastest-advancing segment as semiconductor miniaturization enables chip-scale depth sensing inside smaller instrument channels.
FDA premarket clearance requirements for 3D surgical visualization devices govern product entry into the United States, while the EU MDR and CE marking framework impose clinical evidence standards for European market access. Japan's PMDA maintains distinct biocompatibility and electromagnetic compatibility testing protocols that extend registration timelines for foreign manufacturers. Stakeholders must monitor how evolving software-as-medical-device classifications across these jurisdictions affect regulatory burdens for AI-enhanced depth mapping and augmented reality overlays.
Market Dynamics
Surgeon training bottlenecks are compressing the effective deployment rate of 3D laparoscopy suites despite robust hardware availability, creating a structural gap between capital investment and clinical utilization that vendors must address through education partnerships.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:The streamlined premarket notification process for 3D surgical visualization devices accelerates US commercialization timelines, reducing regulatory friction for stereoscopic endoscope systems.
- Japan's Surgical Volume Concentration:Tertiary hospitals in Tokyo and Osaka maintain capital budgets for advanced minimally invasive platforms, anchoring demand for 4K stereoscopic systems in high-complexity procedures.
- Time-of-Flight Miniaturization:Semiconductor process advances enable chip-scale depth sensors within smaller instrument channels, expanding 3D visualization to pediatric and single-port applications previously served by 2D systems.
Market Restraints
- Optical Component Supply Concentration:German and Japanese precision glass manufacturers control critical lens supply for stereoscopic endoscopes, exposing procurement to geographic concentration risk.
- EU MDR Clinical Evidence Burden:The expanded post-market surveillance and clinical evaluation requirements under the Medical Device Regulation extend CE marking timelines and compliance costs for 3D visualization platforms.
- Fluorescence Imaging Substitution:Near-infrared fluorescence systems from companies like Stryker and Intuitive Surgical compete for capital allocation in oncologic resections, displacing some 3D visualization demand in tumor-margin applications.
Strategic Opportunities
- India's Tertiary Hospital Expansion:Government-backed medical infrastructure programs in Maharashtra and Karnataka are equipping new surgical centers, creating first-mover advantage for 3D laparoscopy vendors in underpenetrated metropolitan markets.
- AI-Augmented Depth Mapping:Convergence of real-time depth sensing with machine learning-based anatomical recognition enables autonomous camera positioning, reducing assistant surgeon dependency in solo-practice settings.
- US ASC Migration Tailwind:The CMS expansion of payable procedures in ambulatory surgery centers drives demand for compact, cart-based 3D systems that fit constrained physical footprints.
Industry Challenges
- Stereoscopic Vision Training Deficits:Residency programs lack standardized curricula for depth-perceptual skill acquisition in 3D environments, extending the learning curve and limiting utilization rates among newly credentialed surgeons.
- Legacy 2D Infrastructure Interoperability:Hospital IT networks and archiving systems built around HD-SDI 2D signal standards require costly gateway hardware to integrate 4K 3D video streams.
- Software-as-Medical-Device Reclassification Uncertainty:Evolving FDA and EU guidance on AI-enhanced visualization algorithms creates compliance timeline risk for vendors embedding predictive depth correction features.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 3D Laparoscopy Imaging Market |
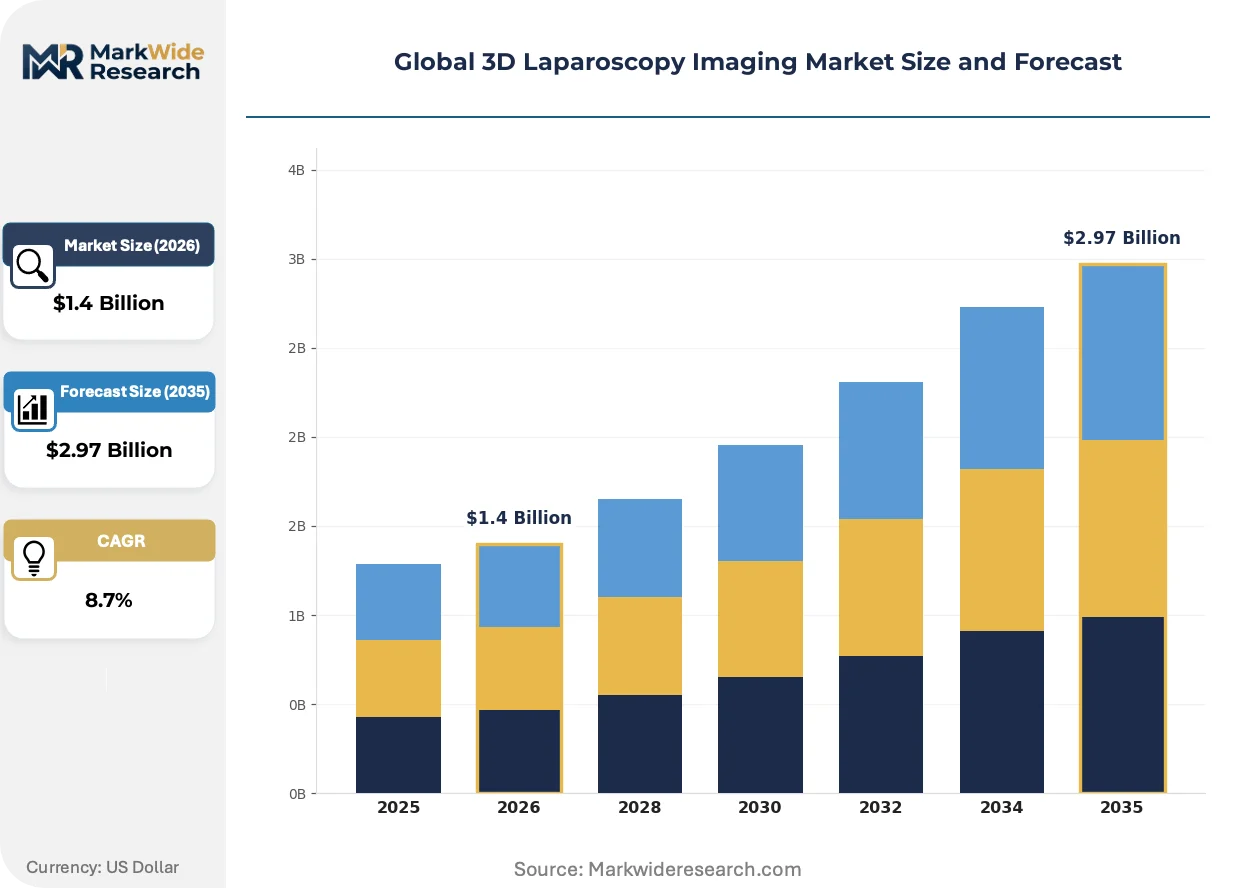
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscope Systems, Cameras, Displays, Insufflators, Trocar Instruments Technology: Stereoscopic Vision, Time-of-Flight, Structured Light, Laser Triangulation, Photometric Stereo Application: Minimally Invasive Surgery, Urological Procedures, Gynecological Procedures, General Surgery, Thoracic Surgery End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutes |
| Companies Covered | Olympus Corporation, Karl Storz SE & Co. KG, Sometech Inc., B. Braun Melsungen AG, Siemens Healthineers, Richard Wolf GmbH, Fujifilm Holdings Corporation, CONMED Corporation, Visionsense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 3D Laparoscopy Imaging Market Shifts & Advancements
Real-time computational depth processing is displacing purely optical stereoscopy as the dominant technical architecture, while regulatory frameworks adapt to software-enabled surgical visualization and procurement models compress replacement cycles.
Chip-scale time-of-flight sensors are bifurcating the technology landscape between established dual-lens optical stereoscopy and emerging computational depth mapping. Academic medical centers in Germany and the United States are piloting single-lens 3D systems that reduce instrument diameter and sterilization burden. This bifurcation is compressing the premium positioning of traditional optical stacks while opening mid-market segments to semiconductor-based alternatives.
The EU MDR's enhanced clinical evidence requirements for Class IIa surgical devices are extending validation timelines for 3D visualization platforms seeking CE marking. Manufacturers must now generate prospective clinical data on depth-perceptual outcomes rather than relying on predicate equivalence, favoring incumbents with established installed bases for post-market follow-up studies. Japanese and US submissions face less stringent evidentiary thresholds, creating a regulatory arbitrage that shapes product launch sequencing.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, driving vendors toward discrete software subscription models for depth-mapping algorithm updates. German university hospitals and US integrated delivery networks now negotiate three-year visualization platform leases with separate per-procedure fees for AI-enhanced features, a structure that compresses vendor cash conversion cycles while shifting technology obsolescence risk to suppliers.
Global 3D Laparoscopy Imaging Market Segmentation
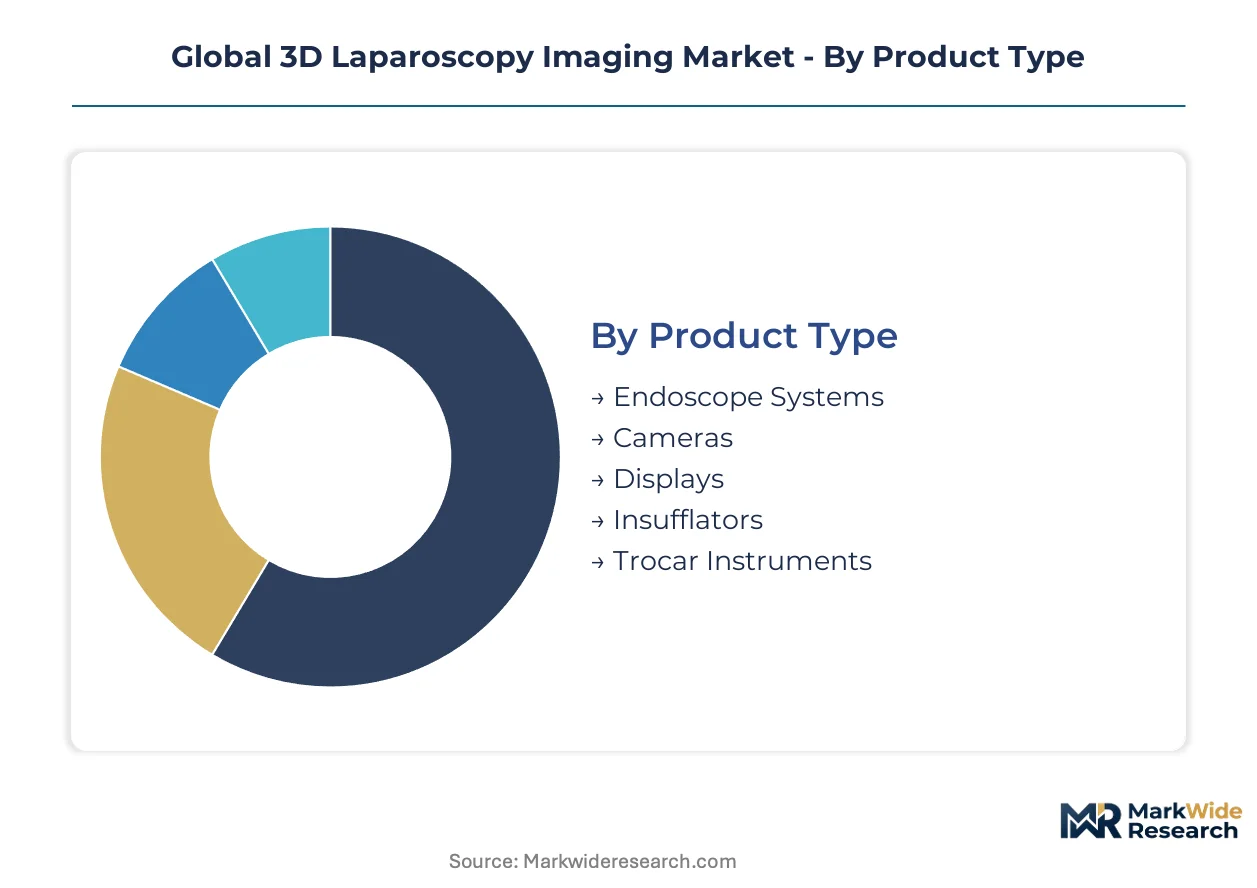
3D laparoscopy imaging segments reflect divergent regulatory pathways and capital deployment patterns across healthcare systems. Product and technology categories carry distinct compliance burdens, while application and end-user dimensions shape procurement velocity and replacement cycles.
Product Type:
FDA 510(k) premarket notification requirements vary substantially across hardware categories, with active electronic components facing stricter electromagnetic compatibility validation than passive instruments.
- Endoscope Systems:Dual-lens optical stacks with integrated light channels constitute the core procedural interface, requiring sterilization-compatible housing materials. Demand clusters in tertiary hospitals across the United States, Germany, and Japan where capital budgets absorb premium dual-4K configurations. EU MDR biocompatibility testing extends validation timelines for new optical stack introductions.
- Cameras:Stereoscopic image sensors with sub-50ms latency processing anchor depth-perceptual performance. Procurement concentrates in high-volume surgical centers performing complex oncologic resections, with replacement cycles compressed by rapid 4K-to-8K resolution transitions.
- Displays:Polarized or active-shutter 3D monitors with surgical-grade brightness calibration support hand-eye coordination.
- Insufflators:Pressure-regulated gas delivery systems maintain pneumoperitoneum during stereoscopic visualization.
- Trocar Instruments:Access ports with integrated seal mechanisms accommodate varying endoscope diameters.
Established volume favors endoscope systems; emerging adoption favors cameras.
Technology:
Cost tier stratification separates mature optical architectures from semiconductor-based alternatives, with capital intensity dictating hospital procurement accessibility.
- Stereoscopic Vision:Dual-lens optical parallax remains the clinical gold standard, validated through decades of minimally invasive surgery outcomes. Deployment dominates academic medical centers in the United States and Western Europe where training infrastructure supports depth-perceptual skill acquisition.
- Time-of-Flight:Chip-scale depth sensors enable single-laparoscope 3D reconstruction through modulated light phase detection. Adoption accelerates in pediatric and single-port applications across Japanese tertiary hospitals, driven by METI-funded semiconductor miniaturization programs.
- Structured Light:Projected pattern deformation analysis supports surface topography mapping.
- Laser Triangulation:Active scanning mechanisms provide high-precision depth measurement.
- Photometric Stereo:Multi-angle illumination analysis reconstructs surface geometry without stereo hardware.
Clinical validation concentrates in stereoscopic vision; steepest expansion trajectory belongs to time-of-flight miniaturization.
Application:
Procedure reimbursement codes and operative complexity determine 3D visualization ROI, with longer interventions justifying capital expenditure through time savings.
- Minimally Invasive Surgery:Broad laparoscopic procedures spanning cholecystectomy to colectomy represent the foundational demand base. Volume concentrates in United States integrated delivery networks where CMS reimbursement incentives reward reduced operative duration.
- Urological Procedures:Prostatectomy and partial nephrectomy demand precise depth perception for neurovascular bundle preservation. Adoption concentrates in German university hospitals where robotic-assisted platforms integrate stereoscopic visualization.
- Gynecological Procedures:Hysterectomy and myomectomy applications leverage 3D for suturing precision.
- General Surgery:Hernia repair and bariatric procedures utilize 3D for mesh placement accuracy.
- Thoracic Surgery:VATS procedures require depth-resolved hilar dissection.
Procedure volume favors minimally invasive surgery; technical complexity premium favors urological applications.
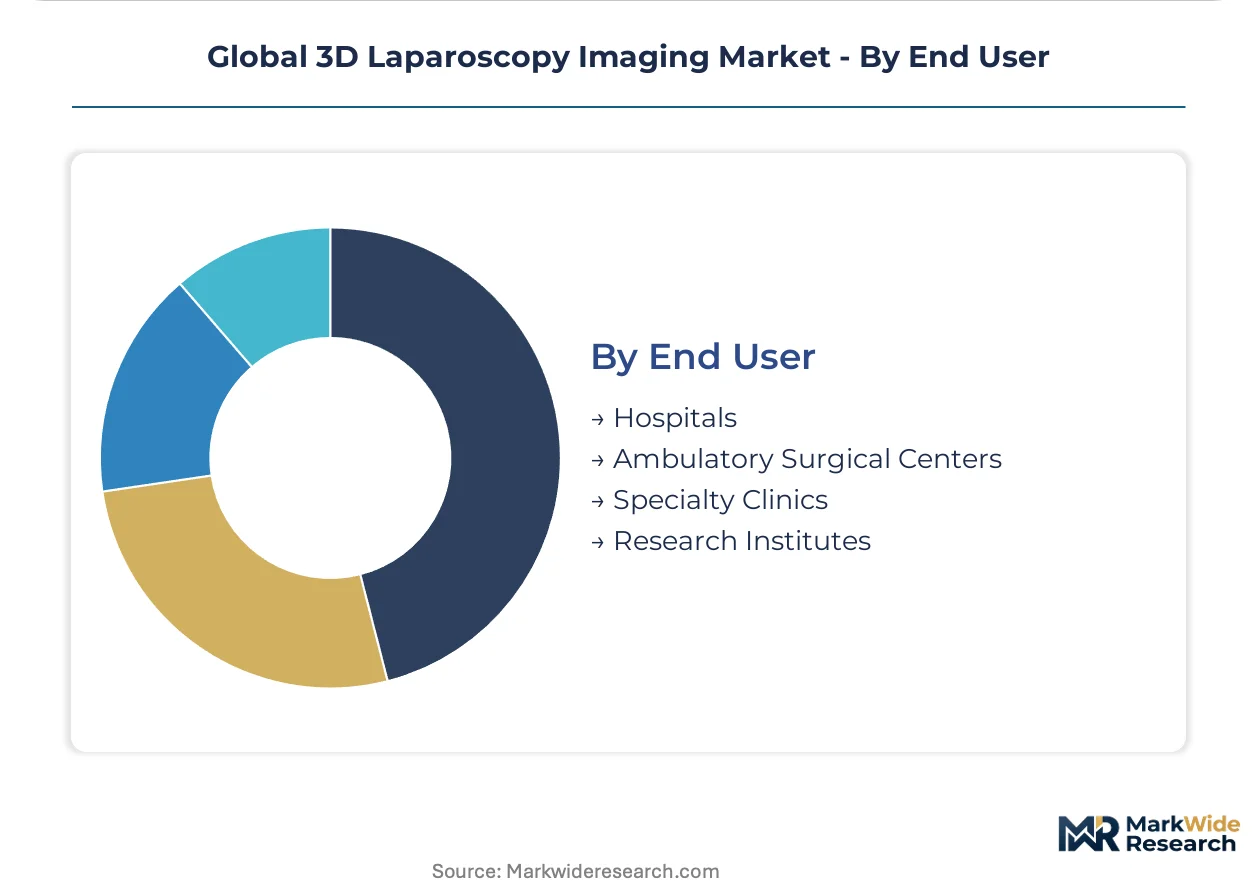
End User:
Customer type dictates equipment form factor and service contract structure, with physical footprint constraints separating institutional segments.
- Hospitals:Tertiary and quaternary centers with dedicated minimally invasive surgery suites drive premium system deployment. Capital allocation concentrates in United States academic medical centers and Japanese national hospital organizations with centralized procurement authority.
- Ambulatory Surgical Centers:CMS procedure code expansion enables same-day discharge for complex interventions. Demand concentrates in United States multi-site ASC chains seeking compact cart-based 3D systems with rapid turnover protocols.
- Specialty Clinics:Focused urology and gynecology practices deploy single-specialty configurations.
- Research Institutes:Preclinical and clinical trial facilities utilize 3D visualization for training curriculum development.
Capital deployment scale favors hospitals; volume growth rate favors ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that of India by a factor of three, reflecting divergent reimbursement structures and capital allocation authority across tertiary hospital systems.
United States
CMS reimbursement codes for minimally invasive procedures incentivize operative time reduction through advanced visualization platforms. The FDA's 510(k) premarket notification pathway accelerates commercialization timelines for stereoscopic surgical devices. Tertiary care clusters in Boston and Houston drive concentrated procurement of dual-4K endoscope systems.
Germany
University hospital networks in Bavaria and Baden-Württemberg maintain dedicated capital budgets for integrated operating room architectures. The EU MDR's expanded clinical evidence requirements extend CE marking timelines for new 3D visualization platforms. The Tübingen-Stuttgart surgical corridor anchors European demand for precision optical stacks.
Japan
METI-funded semiconductor miniaturization programs accelerate chip-scale time-of-flight sensor adoption in pediatric applications. The PMDA maintains distinct biocompatibility testing protocols that extend registration timelines for foreign manufacturers. Tokyo and Osaka tertiary hospitals concentrate demand for compact single-port 3D systems.
India
Government-backed medical infrastructure programs in Maharashtra and Karnataka equip new surgical centers with visualization platforms. The CDSCO regulates medical device imports through mandatory registration and quality testing requirements. Metropolitan hospital clusters in Mumbai and Bangalore create first-mover opportunities for mid-market 3D cart systems.
United Kingdom
NHS procurement frameworks prioritize interoperable visualization systems compatible with legacy HD-SDI infrastructure. MHRA conformity assessment procedures align with EU MDR standards post-Brexit, maintaining stringent clinical evidence requirements. The London-Oxford-Cambridge arc concentrates academic medical center demand for training-integrated 3D suites.
Global 3D Laparoscopy Imaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure where premium optical manufacturers compete alongside semiconductor-based challengers. The vendor base clusters around three strategic positions: integrated endoscope-camera-display ecosystems, precision optical component specialists, and digital operating room architecture providers. Consolidation pressure operates through backward integration into lens manufacturing and forward integration into software-enabled visualization services. Competitive moves center on education partnerships to address surgeon training bottlenecks and subscription-based pricing for algorithm updates.
Among Japanese and German precision manufacturers, Olympus Corporation and Karl Storz SE & Co. KG occupy positions as archetypal ecosystem integrators, while Siemens Healthineers exemplifies the digital architecture play. These three anchors represent divergent strategic bets on whether hardware integration, optical manufacturing depth, or software platform dominance will capture value in next-generation surgical visualization.
| Leading Market Players |
|---|
| Olympus Corporation |
| Karl Storz SE & Co. KG |
| Sometech Inc. |
| B. Braun Melsungen AG |
| Siemens Healthineers |
| Richard Wolf GmbH |
| Fujifilm Holdings Corporation |
| CONMED Corporation |
| Visionsense |
| Others |
Supply & Pricing Matrix
Chip-scale time-of-flight sensors displacing dual-lens optical stacks are redrawing procurement geography toward Japanese semiconductor foundries while compressing the premium once commanded by German precision glass manufacturers. This substitution simultaneously erodes the cost barrier for mid-market hospital systems and fragments supplier power across optical and electronic domains.
Pricing Analysis
The customization-premium spread between configured-to-order dual-4K endoscope systems and standard HD stereoscopic configurations spans subscription-tiered software models and per-unit transactional hardware sales. Price differentiation rests on FDA 510(k) clearance tier and volume scale, with academic medical centers absorbing premium positioning while ambulatory surgery centers drive cost compression through compact cart-based procurement. Pricing pressure intensifies as fluorescence imaging systems from Stryker and Intuitive Surgical vie for capital allocation in oncologic applications. Indian metropolitan hospital clusters exhibit highest price sensitivity; Japanese tertiary centers show least elasticity due to METI-funded infrastructure programs.
Supply Chain Analysis
Inventory lead times for precision optical components extend twelve to eighteen months, constraining rapid scaling of stereoscopic endoscope production. Supply concentrates in Germany and Japan for lens manufacturing, with South Korea and Taiwan feeding semiconductor sensor fabrication. Raw material dependencies encompass rare-earth doped glass, CMOS image sensors, and surgical-grade aluminum housings. Single-source vulnerability pervades German precision glass supply for stereoscopic stacks. Distribution runs through authorized dealer networks serving hospital procurement committees and GPO contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against computational depth mapping architectures that threaten to commoditize optical stereoscopy. Fluorescence-guided surgery platforms represent the most acute substitute threat, capturing capital allocation through superior tumor-margin visualization.
For Market Incumbents: Compound ecosystem lock-in through backward integration into precision lens manufacturing and forward integration into AI-augmented depth mapping subscriptions. Threat from semiconductor-based challengers demands captive supply of CMOS sensors through partnership with Japanese foundries. Priority lever: hospital education partnerships addressing surgeon training bottlenecks.
For New Entrants and Emerging Players: FDA 510(k) fast-track via predicate equivalence to established stereoscopic systems enables rapid US commercialization. White-space targets concentrate in India's Maharashtra and Karnataka tertiary hospital expansions and US ambulatory surgery center migration. Most penetrable segment: compact single-port 3D systems for pediatric applications. Go-to-market angle: software subscription bundling with hardware lease structures.
For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors semiconductor-enabled challengers over legacy optical manufacturers. Long-term viability across the projection horizon hinges on software platform dominance rather than hardware integration depth. Acquisition target archetype: chip-scale depth sensing specialists with PMDA registration progress. Signal to watch: EU MDR clinical evidence burden favoring incumbents with installed bases for post-market studies.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR clinical evidence requirements extend validation timelines for stereoscopic visualization platforms seeking European access. |
| Hospital System Partnership | US integrated delivery networks negotiate three-year platform leases with separate per-procedure fees for AI-enhanced features. |
| Software Companion Development | Real-time depth sensing convergence with machine learning-based anatomical recognition enables autonomous camera positioning. |
| FDA Submission | Premarket notification pathway accelerates US commercialization timelines for stereoscopic endoscope systems. |
| Reimbursement Strategy | CMS procedure code expansion in ambulatory surgery centers drives demand for compact cart-based 3D systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR notified body documentation, and hospital procurement databases. Primary interviews engaged surgeons, biomedical engineers, hospital purchasing committee members, and GPO contracts managers across tertiary centers in the United States, Germany, and Japan. Secondary validation drew from PMDA registration data, CMS reimbursement code filings, and METI semiconductor program disclosures. Bottom-up equipment shipment modeling triangulates against top-down healthcare capital expenditure analysis.
Segmentation dimensions modeled span product type, technology architecture, application procedure, and end-user facility category across the projection horizon. Analytical framework incorporates installed base dynamics, replacement cycle compression, and regulatory pathway efficiency as forecast inputs. CAGRs derive from procedure volume elasticity to visualization platform deployment and capital budget allocation patterns in academic medical centers.
The analysis sits within stated boundaries; outcomes outside FDA premarket notification efficiency or EU MDR clinical evidence stability would require recalibration. Forecasts reflect documented assumptions regarding surgeon training pipeline expansion and semiconductor miniaturization trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Magnetic Resonance Imaging Market
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Europe Portable X-Ray Devices Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Mexico Digital Radiology Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
US Contrast Media Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
US Teleradiology Market