
 Magnetic Resonance Imaging (MRI) Coils Market | 2026-2036
Magnetic Resonance Imaging (MRI) Coils Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Resonance Imaging (MRI) Coils Market Foresight
Market Context
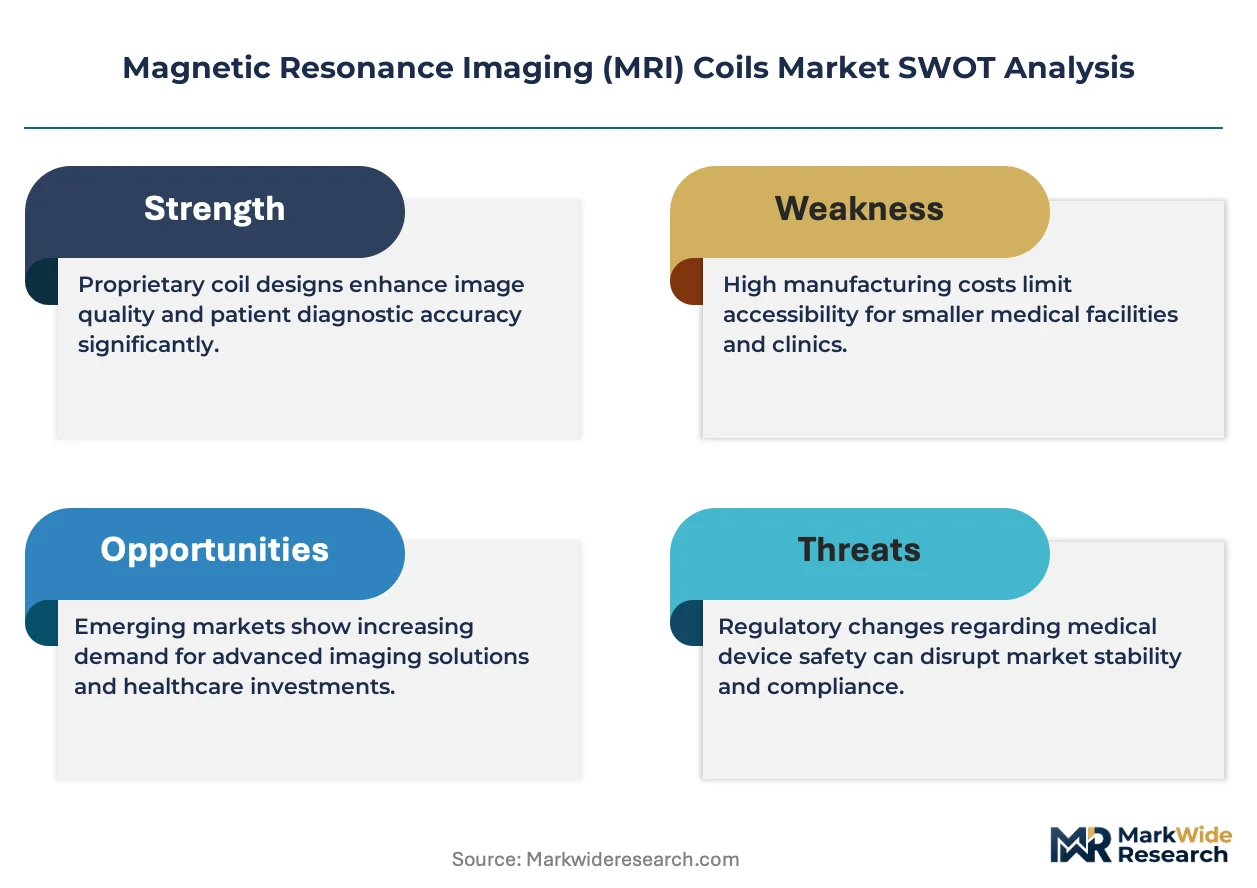
CE marking under the EU Medical Device Regulation is unwinding competitive access for coil manufacturers lacking notified body certification. Siemens Healthineers leverages captive magnet production to sustain integrated coil-to-system margins across European installations. GE Healthcare Technologies anchors North American hospital service contracts through proprietary coil compatibility locks. Canon Medical Systems competes on gradient coil performance in Japanese research institutions.
Technical Definition and Segments
Magnetic Resonance Imaging Coils are radiofrequency antenna assemblies composed of copper or silver-plated conductors embedded in biocompatible housings, engineered to transmit excitation pulses and receive proton relaxation signals at field strengths from 0.2T to 7.0T for diagnostic image reconstruction. High-Field MRI coil arrays dominate replacement revenue as hospitals retire 1.5T platforms, while Ultra-High Field MRI concentrates margin pools in academic medical centers running 7.0T neuroimaging protocols. Pediatric Coils represent the fastest-growing product category as neonatal intensive care units expand MRI-guided intervention capabilities.
Regulatory Frame
FDA 21 CFR Part 820 quality system regulation, EU MDR technical documentation requirements, and China's NMPA Class II medical device registration collectively shape coil market access timelines and post-market surveillance burdens. These frameworks force manufacturers to maintain design history files and clinical evaluation reports for each coil variant, raising working capital requirements for product line breadth. Stakeholders must monitor harmonization gaps between FDA predicate device pathways and EU MDR clinical evidence expectations when prioritizing geographic launch sequences.
Market Dynamics
The MRI coils market pivots on the collision between accelerated 3.0T platform deployment and tightening FDA quality system regulation enforcement, which is compressing aftermarket supplier margins while elevating certified incumbents.
Growth Catalysts
- Oncology imaging demand:Cancer centers in Germany and China are retiring 1.5T systems, forcing coil replacement cycles that favor high-field array configurations. Diagnostic throughput requirements in these facilities now mandate parallel imaging capabilities.
- EU MDR technical documentation:The regulation's clinical evidence requirements are filtering out uncertified coil variants, consolidating procurement toward notified body-approved suppliers. This reduces competitive fragmentation in European hospital tenders.
- Neonatal intensive care expansion:Pediatric-specific coil arrays are capturing new installation slots as NICU MRI-guided intervention protocols proliferate. Copper-silver hybrid conductor designs enable the anatomical flexibility these procedures require.
Market Restraints
- Copper and silver conductor volatility:Raw material price swings in precious metal markets compress coil manufacturing margins unpredictably. Biocompatible housing polymers compound input cost pressure.
- Magnet supply concentration:Captive production of superconducting magnets by integrated system manufacturers locks independent coil suppliers out of bundled procurement decisions. Siemens Healthineers' in-house magnet capacity exemplifies this barrier.
- 7.0T technical ceiling:Ultra-high field neuroimaging protocols remain confined to academic medical centers due to siting requirements and helium scarcity. Volume scalability beyond research settings is structurally constrained.
Strategic Opportunities
- Indian diagnostic chain consolidation:Corporate hospital networks in Mumbai and Delhi are importing 3.0T platforms, creating first-mover advantage for coil suppliers achieving CDSCO Class II registration. Local manufacturing incentives under the PLI scheme reduce landed cost exposure.
- Gradient coil-AI reconstruction convergence:Machine learning-based image denoising is relaxing hardware requirements for diagnostic-grade output. This enables mid-tier array designs to compete on software-augmented performance.
- Refurbished system channel expansion:Secondary equipment brokers in Brazil and Mexico are creating aftermarket coil demand detached from OEM service contracts. ANVISA registration pathways for refurbished accessories remain underdeveloped.
Industry Challenges
- RF engineer scarcity:Specialized talent for multi-channel array design is concentrating at incumbent manufacturers, constraining R&D velocity for emerging suppliers. University programs in electromagnetic coil engineering are not scaling with market demand.
- EU MDR notified body bottlenecks:Technical documentation review timelines for new coil variants now extend 18-24 months, freezing product pipeline releases. Design history file maintenance consumes disproportionate working capital.
- Legacy system compatibility:Hospital IT infrastructure for 1.5T platforms resists seamless integration with modern digital coil interfaces, forcing costly middleware development or full platform replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Resonance Imaging (MRI) Coils Market |
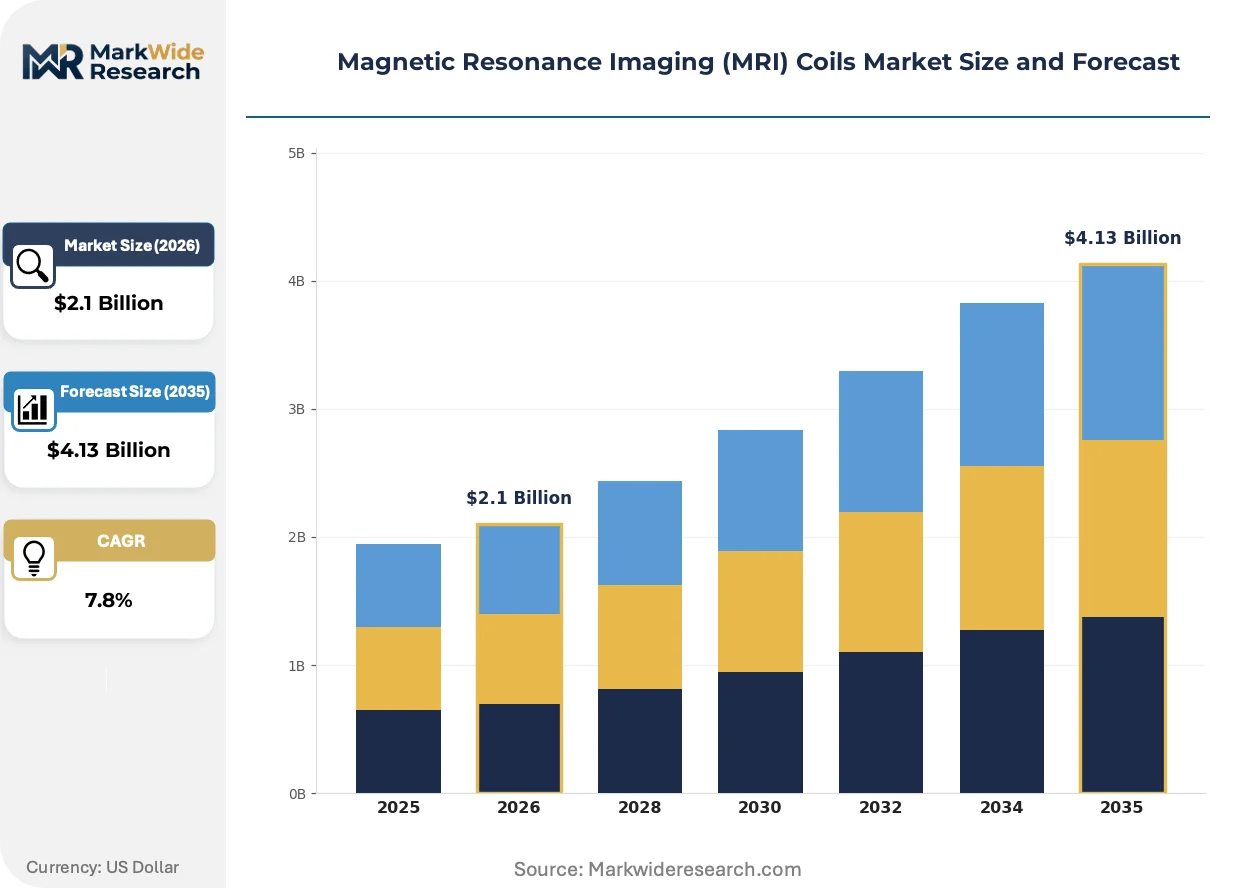
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Coils, Body Coils, Extremity Coils, Pediatric Coils Technology: High-Field MRI, Low-Field MRI, Ultra-High Field MRI, Open MRI End User: Hospitals, Imaging Centers, Research Institutions, Diagnostic Labs Installation Type: Fixed MRI Systems, Mobile MRI Units, Retrofit MRI, Modular MRI Suites |
| Companies Covered | Canon Medical Systems Corporation, Shanghai United Imaging Healthcare Co., Ltd., Siemens Healthineers AG, Esaote S.p.A., Neusoft Medical Systems Co., Ltd., GE Healthcare Technologies, Inc., Hitachi, Ltd., Bruker Corporation, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Resonance Imaging (MRI) Coils Market Shifts & Advancements
Digital coil architecture and software-defined radiofrequency processing are dissolving the hardware-software boundary in MRI signal acquisition, enabling performance tiering without physical array replacement.
Multi-element digital coil arrays with embedded analog-to-digital conversion are bifurcating the installed base. Academic medical centers in Switzerland and the Netherlands are adopting these configurations for 7.0T neuroimaging protocols. The technology is compressing upgrade cycles by decoupling coil hardware from reconstruction algorithm evolution.
FDA's renewed 21 CFR Part 820 enforcement is elevating design control documentation burdens for coil manufacturers. The agency's inspection frequency for radiofrequency device suppliers has intensified since 2023. Aftermarket suppliers lacking predicate device clearance pathways are retreating from US hospital tenders.
Hospital procurement committees are unbundling coil purchases from magnet service contracts, reversing decades of OEM bundling dominance. Independent distributors in Texas and Florida are capturing replacement coil volume through price transparency platforms. This disintermediation is most visible in non-acute imaging centers where capital constraint pressures vendor flexibility.
Magnetic Resonance Imaging (MRI) Coils Market Segmentation
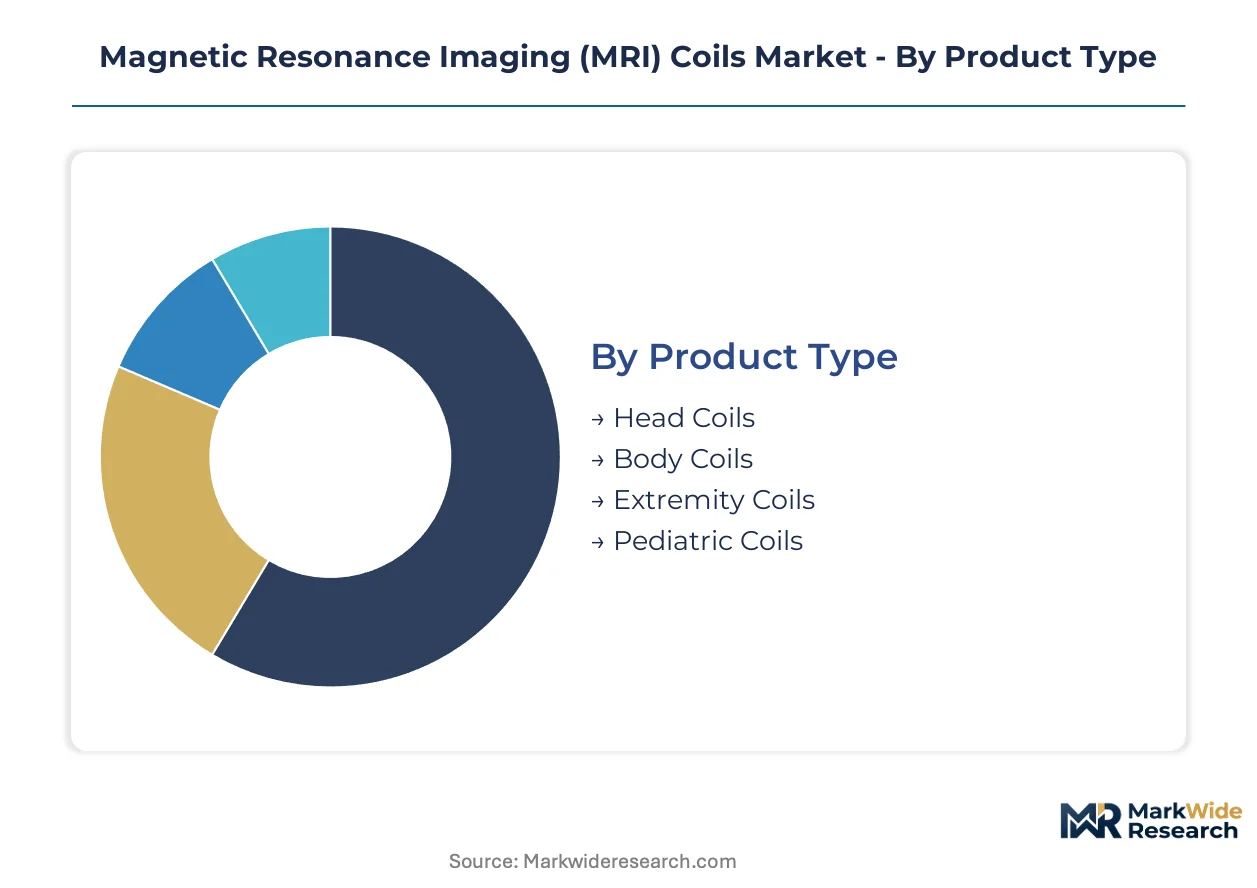
Coil segmentation determines procurement economics and regulatory pathways. Product architecture, field strength technology, and installation modality each create distinct margin profiles and customer access patterns.
Product Type:
Head and body coil variants dominate domestic hospital procurement, while pediatric and extremity designs concentrate in specialized export markets.
- Head Coils:Multi-channel phased arrays encasing the cranium for neurovascular and functional brain imaging. Demand clusters in German university hospitals upgrading to 3.0T platforms for stroke protocol throughput.
- Body Coils:Torso-encompassing arrays with integrated spine elements for abdominal and cardiac sequences. Chinese cancer centers are retiring 1.5T-compatible body arrays as procurement shifts toward high-field replacements.
- Extremity Coils:Anatomically contoured small-bore designs for orthopedic and rheumatology applications. Swiss sports medicine clinics drive premium demand for dedicated knee and wrist configurations.
- Pediatric Coils:Flexible copper-silver hybrid conductor arrays sized for neonatal anatomy. NICU MRI-guided intervention expansion in the Netherlands and Texas pediatric networks accelerates category uptake.
Body coils command the established base. The steepest expansion runs through pediatric coils.
Technology:
Cost tiering separates premium ultra-high field systems from volume mid-field platforms, with open MRI occupying a distinct price-accessibility niche.
- High-Field MRI:3.0T array configurations with parallel imaging capability. Replacement cycles in China and Germany absorb disproportionate volume as hospital procurement shifts toward these platforms.
- Low-Field MRI:0.2T to 1.0T permanent magnet systems for claustrophobic patients and interventional guidance. Rural Indian diagnostic chains favor these for lower siting costs and helium independence.
- Ultra-High Field MRI:7.0T research-dedicated arrays with cryogenic RF front-ends. Academic medical centers in Switzerland and the Netherlands run neuroimaging protocols that concentrate margin pools in this segment.
- Open MRI:C-shaped or vertically oriented magnet geometries with specialized surface coils. Brazilian secondary equipment brokers create aftermarket demand detached from OEM service contracts.
High-field MRI commands the established base. The steepest expansion trajectory belongs to ultra-high field MRI.
End User:
Customer type determines coil replacement frequency and bundled service contract attachment rates.
- Hospitals:Integrated health systems with captive biomedical engineering departments. US hospital procurement committees are unbundling coil purchases from magnet service contracts, reversing decades of OEM bundling dominance.
- Imaging Centers:Independent outpatient facilities with high throughput requirements. Independent distributors in Texas and Florida capture replacement coil volume through price transparency platforms.
- Research Institutions:University-affiliated facilities with protocol development needs. Academic medical centers adopt digital coil arrays with embedded analog-to-digital conversion for 7.0T neuroimaging.
- Diagnostic Labs:Corporate chain laboratories with standardized equipment fleets. Mumbai and Delhi networks import 3.0T platforms, creating first-mover advantage for CDSCO-registered suppliers.
Hospitals command the established base. The steepest expansion runs through diagnostic labs.
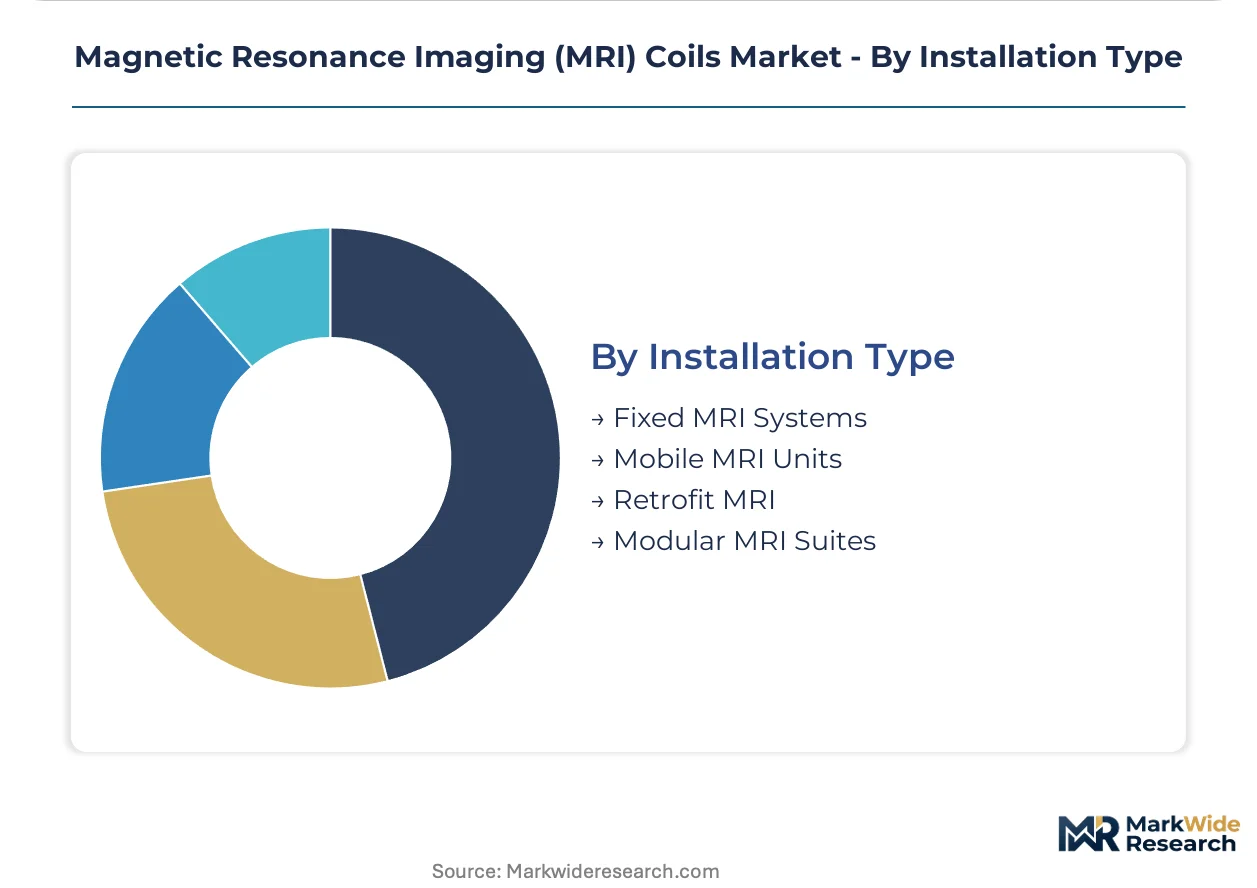
Installation Type:
Volume concentration favors fixed installations, while mobile and modular configurations address infrastructure-constrained demand pockets.
- Fixed MRI Systems:Permanent magnet installations with dedicated coil inventories. Oncology imaging departments in Germany and China are accelerating coil replacement cycles on these platforms.
- Mobile MRI Units:Trailer-mounted systems serving rural or temporary patient populations. Helium scarcity and siting flexibility constraints limit coil array complexity in this segment.
- Retrofit MRI:Upgrade pathways for legacy 1.5T platforms with backward-compatible coil interfaces. Hospital IT infrastructure resists seamless integration with modern digital coil architectures.
- Modular MRI Suites:Prefabricated shielded enclosures with plug-and-play coil configurations. NICU expansion protocols in neonatal intensive care units favor these for rapid deployment.
Fixed MRI systems command the established base. The steepest expansion runs through modular MRI suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany and China absorb disproportionate volumes of high-field array coils as 3.0T platform deployment accelerates. Academic medical centers in Switzerland and the Netherlands concentrate ultra-high field neuroimaging demand. Independent distributors in Texas and Florida capture replacement coil volume through price transparency platforms.
United States
Oncology imaging departments and NICU MRI-guided intervention protocols drive coil replacement cycles. FDA's renewed 21 CFR Part 820 enforcement elevates design control documentation burdens for radiofrequency device suppliers. Texas and Florida pediatric networks accelerate pediatric-specific coil array uptake.
Germany
Cancer centers retiring 1.5T systems force procurement shifts toward high-field array configurations with parallel imaging capabilities. EU MDR technical documentation requirements filter out uncertified coil variants from hospital tenders. University hospitals in Bavaria and North Rhine-Westphalia upgrade to 3.0T platforms for stroke protocol throughput.
China
Hospital procurement committees shift disproportionate volume toward 3.0T platforms, accelerating coil replacement cycles. NMPA Class II medical device registration shapes market access timelines and post-market surveillance burdens. Shanghai and Beijing absorb high-field array coil volumes as diagnostic chains consolidate.
Switzerland
Academic medical centers run 7.0T neuroimaging protocols that concentrate margin pools in ultra-high field segments. Swissmedic regulatory frameworks govern coil market access alongside EU MDR harmonization efforts. Geneva and Zurich research institutions adopt digital coil arrays with embedded analog-to-digital conversion.
India
Corporate hospital networks in Mumbai and Delhi import 3.0T platforms, creating first-mover advantage for CDSCO-registered suppliers. PLI scheme local manufacturing incentives reduce landed cost exposure for coil manufacturers. Maharashtra and Karnataka diagnostic chains favor low-field systems for lower siting costs and helium independence.
Magnetic Resonance Imaging (MRI) Coils Market Competitive Landscape
Player mix skews toward integrated system manufacturers with captive magnet production and independent coil specialists serving aftermarket channels. Siemens Healthineers leverages in-house magnet capacity to sustain integrated coil-to-system margins. Strategic archetypes include bundled OEM service contract providers, price-transparent independent distributors, and research-dedicated ultra-high field specialists. Dominant competitive moves encompass backward integration into superconducting magnet production and geographic expansion through notified body certification acquisition.
Among Germany-based integrated health technology conglomerates, Siemens Healthineers AG exemplifies the bundled OEM archetype through captive magnet production. Koninklijke Philips N.V. occupies a position within the diversified medical imaging tier, while GE Healthcare Technologies, Inc. anchors North American hospital service contract structures. Canon Medical Systems Corporation represents the Japanese precision equipment specialist segment competing on gradient coil performance. Shanghai United Imaging Healthcare Co., Ltd. sits within the China-based emerging supplier tier pursuing CDSCO registration for Indian market entry.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Shanghai United Imaging Healthcare Co., Ltd. |
| Siemens Healthineers AG |
| Esaote S.p.A. |
| Neusoft Medical Systems Co., Ltd. |
| GE Healthcare Technologies, Inc. |
| Hitachi, Ltd. |
| Bruker Corporation |
| Koninklijke Philips N.V. |
| Others |
Supply & Pricing Matrix
Captive magnet production at Siemens Healthineers and GE Healthcare concentrates upstream scale economies, compressing price floors for independent coil suppliers while elevating bundled service contract premiums for integrated system manufacturers across German and Chinese hospital procurement.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between OEMs and tier-1 coil manufacturers. Three-tier pricing structure across premium array, standard phased, and economy surface coil levels separates FDA-cleared variants from CE-marked and unregistered aftermarket alternatives. Pricing pressure stems from NMPA registration cost absorption as Chinese diagnostic chains consolidate procurement volume. Imaging centers in Texas and Florida exhibit highest price sensitivity through independent distributor price transparency platforms, while Swiss academic medical centers show lowest sensitivity for 7.0T cryogenic RF configurations.
Supply Chain Analysis
Strait of Malacca transit underwrites copper concentrate delivery schedules from Chilean and Peruvian mines to Chinese conductor drawing facilities. Superconducting niobium-titanium wire production concentrates in Japan, Germany, and the United States, with biocompatible housing polymer compounding anchored in South Korea and the Netherlands. Single-source vulnerability in helium-3 cryogenic cooling systems feeds from Russian and Qatari extraction concentration. Distribution runs through OEM captive service organizations for hospital systems, with independent distributors capturing replacement volume in non-acute imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MRI coils market functions as a service-attach opportunity where software-defined radiofrequency processing subscriptions and coil refurbishment programs expand faster than hardware replacement cycles, decoupling recurring revenue from magnet upgrade timelines.
For Market Incumbents: Fortify backward integration into superconducting magnet production to sustain coil-to-system bundling power against unbundling procurement committees in US hospitals. Deepen CDSCO registration investment for Indian diagnostic chain consolidation, as PLI scheme local manufacturing incentives reduce landed cost exposure for certified suppliers. Prioritize digital coil architecture R&D to maintain performance tiering against AI-reconstruction-enabled mid-tier competitors.
For New Entrants and Emerging Players: Lead with pediatric-specific coil arrays for NICU MRI-guided intervention protocols in Texas and Netherlands neonatal networks, where anatomical flexibility requirements and copper-silver hybrid conductor designs favor specialist suppliers over integrated OEMs. Target Brazilian and Mexican refurbished system channels through ANVISA registration pathways for accessories, leveraging underdeveloped regulatory frameworks and secondary equipment broker demand detached from OEM service contracts.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coil specialists with embedded analog-to-digital conversion capabilities and notified body certification breadth across FDA, EU MDR, and NMPA jurisdictions. Long-term viability hinges on software companion development velocity rather than hardware replacement frequency. Watch for gradient coil-AI reconstruction convergence as inflection indicator, where machine learning-based image denoising relaxes hardware requirements and enables mid-tier array competition.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Certification Acquisition | Accelerates market access timelines for coil variants across German and Dutch hospital tenders. |
| Digital Coil Architecture Platform Launch | Decouples hardware upgrade cycles from reconstruction algorithm evolution in Swiss research institutions. |
| CDSCO Class II Registration Investment | Captures first-mover advantage in Mumbai and Delhi corporate hospital network 3.0T platform imports. |
| Software Companion Development Partnership | Enables AI-augmented performance tiering for mid-tier array designs competing on denoising capability. |
| Refurbished System Channel Distribution Agreement | Accesses aftermarket coil demand in Brazilian secondary equipment markets outside OEM service contracts. |
Research Methodology
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers and secondary validation through FDA 510(k) filings, EU MDR technical documentation databases, and NMPA registration records anchors the qualitative findings. Bottom-up coil shipment tracking by field strength configuration and top-down diagnostic imaging capital expenditure analysis triangulate volume estimates across the analysis window.
Sensitivity analysis around raw material price volatility and regulatory approval timeline scenarios shapes the analytical framework. Segmentation dimensions modeled include product architecture, field strength technology, end user type, and installation modality across the projection horizon. CAGRs derive from installed base replacement cycle analysis and platform upgrade intensity patterns, with helium scarcity constraints and RF engineer talent concentration as industry-specific forecast inputs.
Underlying assumptions cover stable copper and silver conductor pricing, with deviation risk concentrated in precious metal market volatility and EU MDR notified body review timeline extensions. Practitioners should keep alternative scenarios live as FDA 21 CFR Part 820 enforcement intensity and NMPA Class II registration pathway harmonization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Teleradiology Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
China Magnetic Resonance Imaging Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Global AI for Radiology Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Spinal Imaging Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Digital Pathology Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Americas Interventional Radiology Market
Medical Imaging
Radiology As a Service Market
Medical Imaging
Image Guided Systems Market
Medical Imaging
Ga 68 DOTATOC Market
Medical Imaging
Urology Imaging Systems Market
Medical Imaging
Canada Computed Tomography Market