
 China Nuclear Imaging Market | 2026-2036
China Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
China Nuclear Imaging Market Outlook
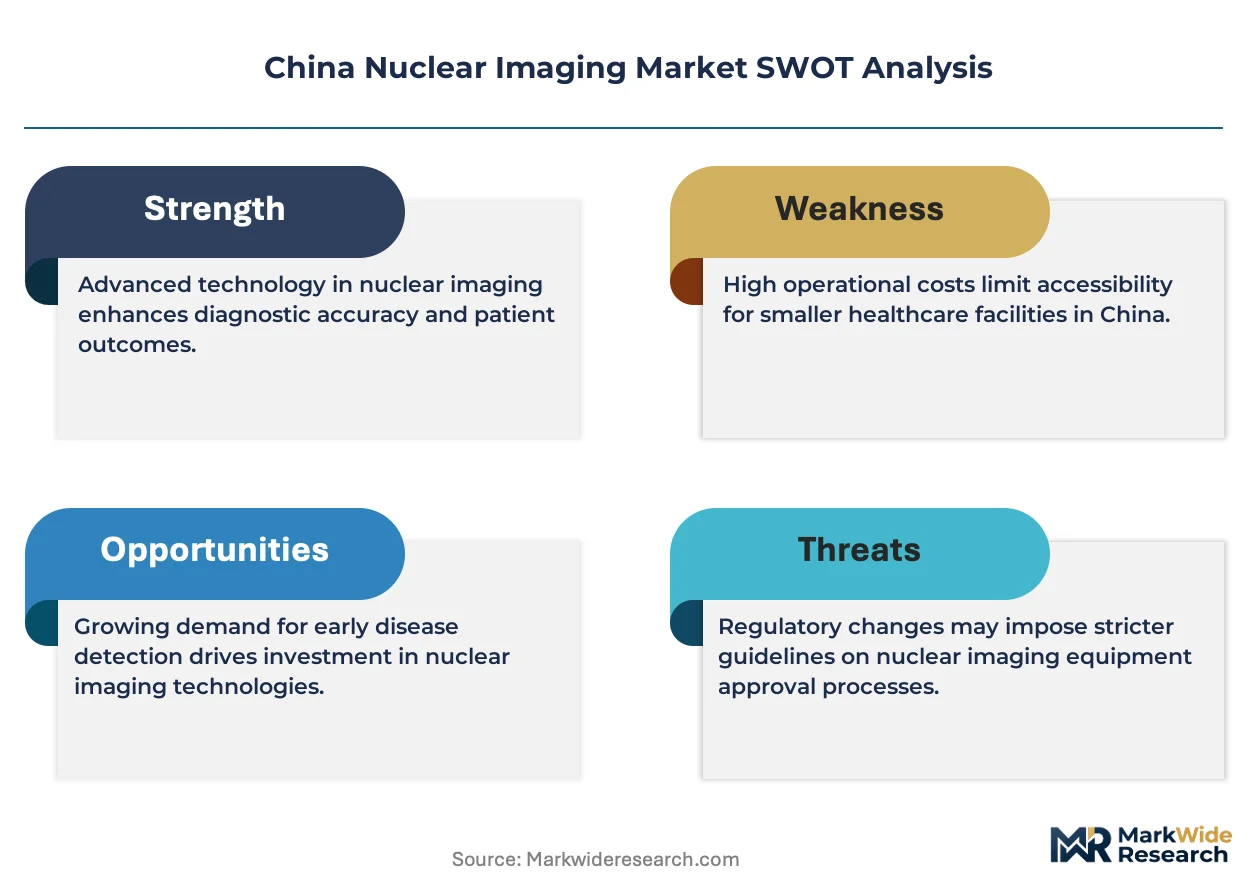
Hospital procurement channels for nuclear imaging systems is fragmenting as provincial centralized tendering displaces direct institutional purchasing. GE Healthcare leverages its installed base of cyclotron-equipped sites to sustain service revenue streams. Siemens Healthineers anchors its position through digital detector upgrades that extend system lifecycles. China Isotope & Radiation Corporation competes on isotope supply security with its domestic reactor network.
China nuclear imaging encompasses diagnostic modalities that utilize radiopharmaceuticals emitting gamma rays or positrons, detected by scintillation crystals converting photon energy into electrical signals for tomographic reconstruction. These systems enable functional visualization of metabolic processes at spatial resolutions approaching four millimeters, primarily serving oncological staging and cardiac perfusion assessment. Positron Emission Tomography systems command the dominant share of capital expenditure as hybrid PET-CT configurations become standard for tumor characterization. Digital Detectors represent the fastest-expanding technology segment as solid-state photon counting replaces analog PMT architectures. Oncology applications concentrate the highest procedure volume, though Neurology shows accelerating utilization for Alzheimer's biomarker imaging.
NMPA's Class III medical device registration requirements govern system approvals, while MIIT oversees domestic manufacturing certifications under GB standards for radiation-emitting equipment. The dual carbon goals framework pressures facilities toward energy-efficient system architectures and reduced isotope waste profiles. Stakeholders must monitor NMPA's evolving radiopharmaceutical tracer approval timelines, as domestic novel agent pipelines will reshape competitive access dynamics.
Market Dynamics
Provincial centralized tendering for medical devices is fragmenting hospital procurement channels across China, forcing equipment vendors to rebuild sales architectures around bulk-purchase frameworks rather than direct institutional relationships.
Growth Catalysts
- NMPA's streamlined Class III pathway:Accelerated review timelines compress domestic innovation cycles, enabling faster market entry for locally developed PET-CT systems.
- Oncology department expansion:Tertiary hospitals are scaling PET-CT fleets under volume-based procurement mandates, concentrating demand in high-throughput facilities.
- Yangtze River Delta clustering:Shanghai and Jiangsu province generate disproportionate imaging procedure volume, creating dense service ecosystems that lower per-scan operational costs.
Market Restraints
- Isotope supply concentration:Domestic reactor networks remain limited, creating dependency on imported molybdenum-99 and fluorine-18 precursors from concentrated overseas sources.
- Digital detector cost structure:Solid-state photon counting arrays require rare-earth scintillation crystals whose price volatility compresses system margins.
- Dual carbon goals compliance:MEE oversight of radiation-emitting equipment forces capital expenditure toward energy-efficient architectures with extended payback periods.
Strategic Opportunities
- Neurology biomarker imaging:Alzheimer's diagnostic protocols are expanding PET tracer applications beyond oncology into neurodegenerative staging.
- MIIT domestic manufacturing certification:GB standards compliance creates preferential access for locally produced cyclotron and detector components.
- Service revenue unbundling:Cyclotron-equipped sites can monetize isotope production for third-party hospitals, decoupling revenue from equipment sales cycles.
Industry Challenges
- Radiopharmaceutical tracer approval timelines:NMPA's evolving novel agent review processes create uncertainty for domestic pipeline commercialization schedules.
- Digital-legacy system integration:Solid-state detector upgrades require compatibility engineering with installed analog PMT architectures, complicating hospital retrofit decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Nuclear Imaging Market |
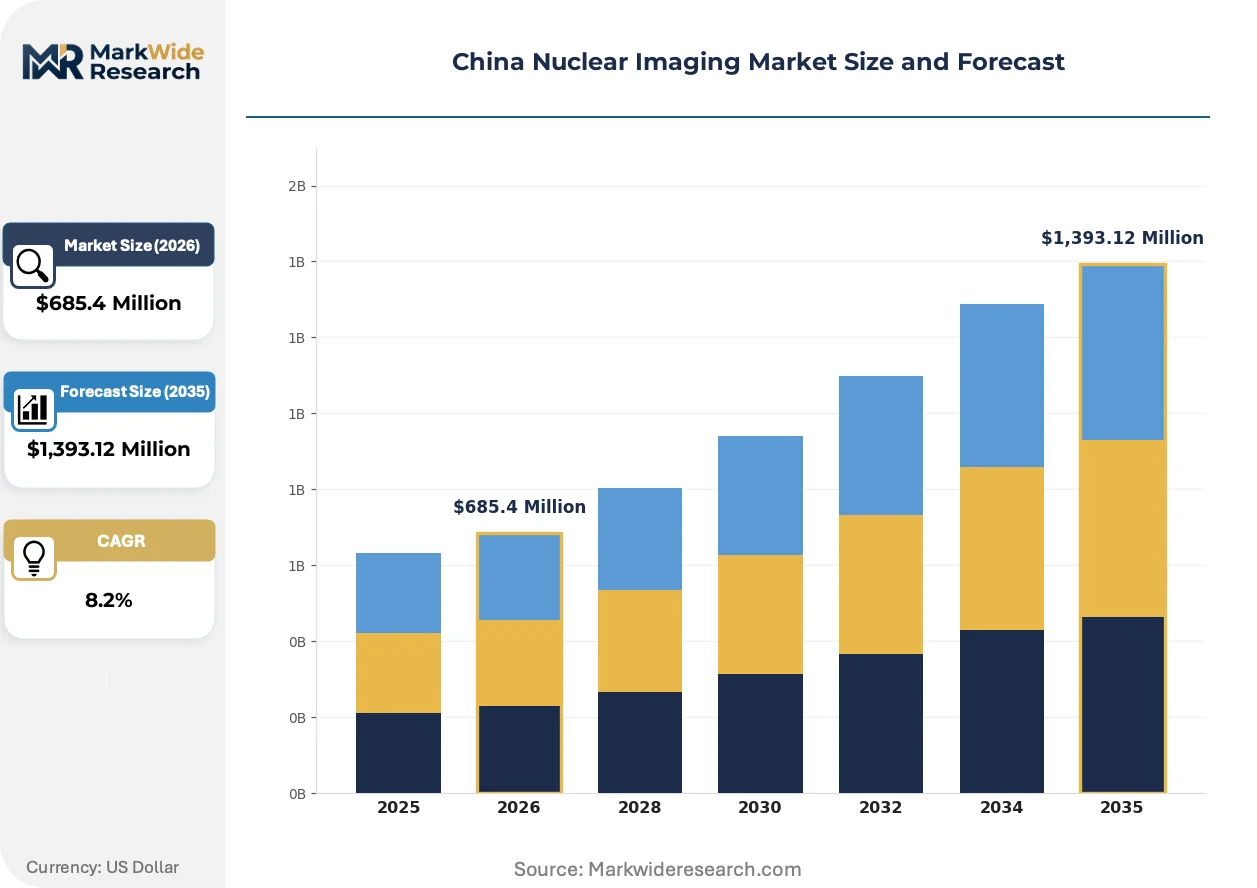
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Photon Emission Tomography, Positron Emission Tomography, Hybrid Systems, Mobile Imaging Units End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Service Providers Technology: Analog Detectors, Digital Detectors, Advanced Imaging Software, Cloud-based Solutions Application: Oncology, Cardiology, Neurology, Infectious Diseases |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Inc, China Isotope & Radiation Corporation, China National Nuclear Corp, Yantai Dongcheng Pharmaceutical Group, Bracco Imaging SpA, Cardinal Health Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Nuclear Imaging Market Strategic Shifts
Detector architecture transformation and procurement model disruption are restructuring competitive advantage in China's nuclear imaging sector, with technology migration and channel fragmentation occurring in parallel.
Solid-state photon counting detectors are replacing analog photomultiplier tube architectures in PET-CT systems. Tertiary hospitals with high procedure volumes are prioritizing these upgrades during replacement cycles. The technology is migrating from premium-tier installations toward mid-range system configurations as manufacturing scale reduces unit costs.
NMPA's radiopharmaceutical tracer approval framework is tightening documentation requirements for novel diagnostic agents. Domestic manufacturers face extended clinical validation timelines before commercial launch. Oncology applications encounter the most regulatory scrutiny, pushing developers toward cardiac perfusion biomarkers as faster approval pathways.
Hospital buying committees are consolidating purchasing authority under provincial health commission tendering platforms. Direct manufacturer relationships with individual institutions are losing influence to centralized negotiation frameworks. This behavioral shift concentrates most visibly in Jiangsu and Zhejiang provinces, where bulk-procurement volumes enable aggressive price benchmarking.
China Nuclear Imaging Market Segmentation
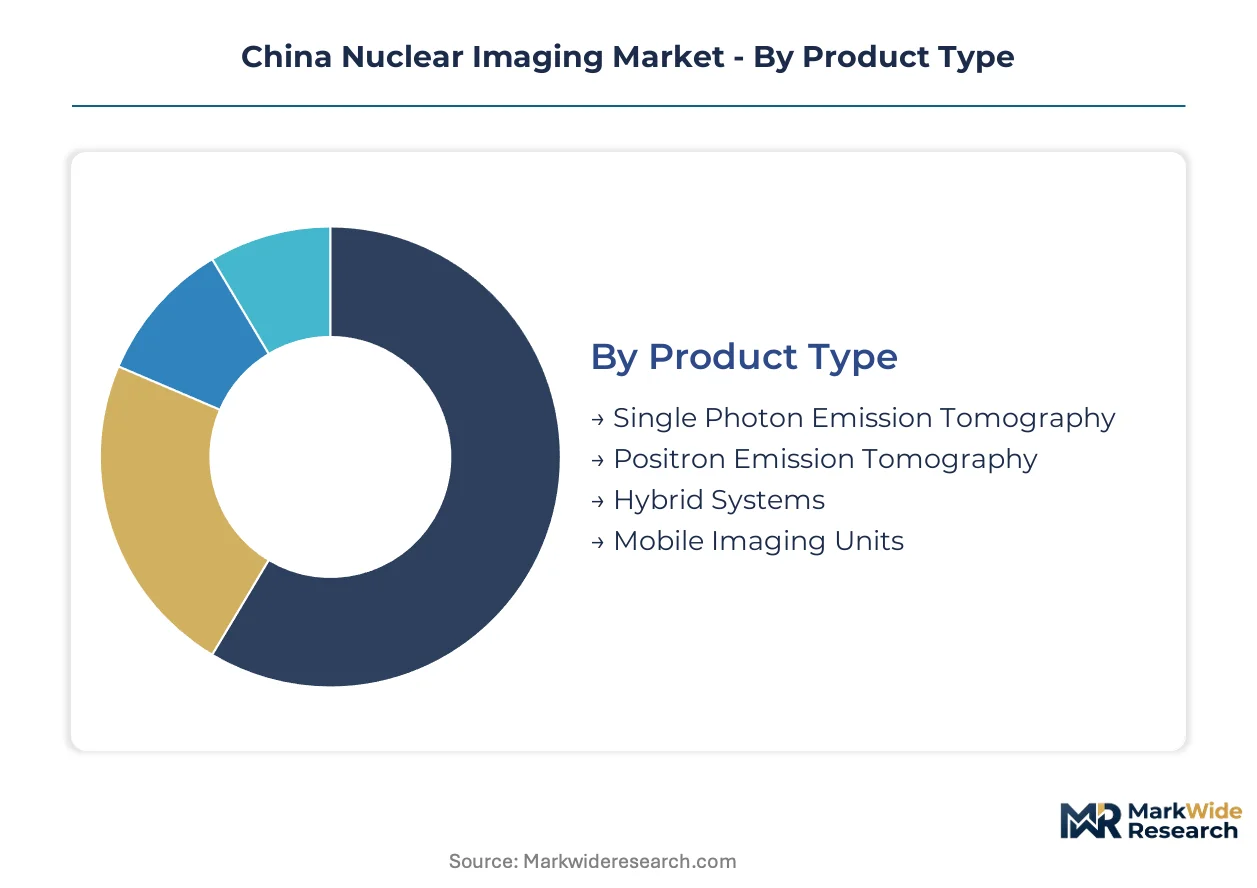
Segmentation reveals how procurement fragmentation and detector technology migration are reshaping competitive positioning across China's nuclear imaging landscape. Each dimension carries distinct service intensity profiles and margin structures.
Product Type:
After-sales-service intensity varies sharply across product categories, with cyclotron-equipped installations demanding multi-year isotope supply contracts and specialized technical support.
- Positron Emission Tomography:Hybrid PET-CT configurations dominate capital expenditure at tertiary hospitals, requiring continuous fluorine-18 supply logistics and cyclotron maintenance. Shanghai and Jiangsu province clusters concentrate demand as oncology departments expand fleet procurement under centralized tendering.
- Hybrid Systems:PET-CT and PET-MRI combinations command premium positioning through fused anatomical-functional imaging capabilities. Tertiary hospitals prioritize these during replacement cycles despite extended payback periods under dual carbon goals compliance pressure.
- Single Photon Emission Tomography:SPECT systems serve cardiac perfusion assessment with lower isotope logistics complexity.
- Mobile Imaging Units:Deployable systems address rural access gaps with reduced infrastructure requirements.
Positron Emission Tomography holds the largest share; momentum sits with Hybrid Systems.
End User:
Procurement authority concentration determines vendor channel strategy, with centralized tendering platforms displacing direct institutional relationships.
- Hospitals:Tertiary hospital oncology departments drive PET-CT fleet expansion under volume-based procurement mandates. Yangtze River Delta facilities generate disproportionate procedure throughput, creating dense service ecosystems.
- Diagnostic Centers:Independent imaging facilities focus on high-margin cardiac and neurological protocols with faster patient turnaround.
- Research Institutions:Academic medical centers pilot novel radiopharmaceutical tracers under NMPA's evolving approval framework.
- Imaging Service Providers:Third-party operators monetize cyclotron isotope production for hospital networks.
Hospitals dominate installed base; Diagnostic Centers are climbing the fastest.
Technology:
Detector architecture migration creates retrofit opportunity windows and compatibility engineering challenges for installed analog systems.
- Digital Detectors:Solid-state photon counting arrays replace analog PMT architectures, extending system lifecycles through detector upgrades. Tertiary hospitals with high procedure volumes prioritize these conversions despite rare-earth scintillation crystal price volatility.
- Analog Detectors:Legacy photomultiplier tube systems retain installed base through lower capital requirements.
- Advanced Imaging Software:Reconstruction algorithms and AI-assisted quantification tools enhance diagnostic accuracy.
- Cloud-based Solutions:Remote image storage and teleradiology capabilities support multi-site hospital networks.
Digital Detectors are gaining share fastest; Analog Detectors retain legacy footprint.
Application:
Clinical utility expansion beyond oncology is reshaping tracer development pipelines and regulatory submission strategies.
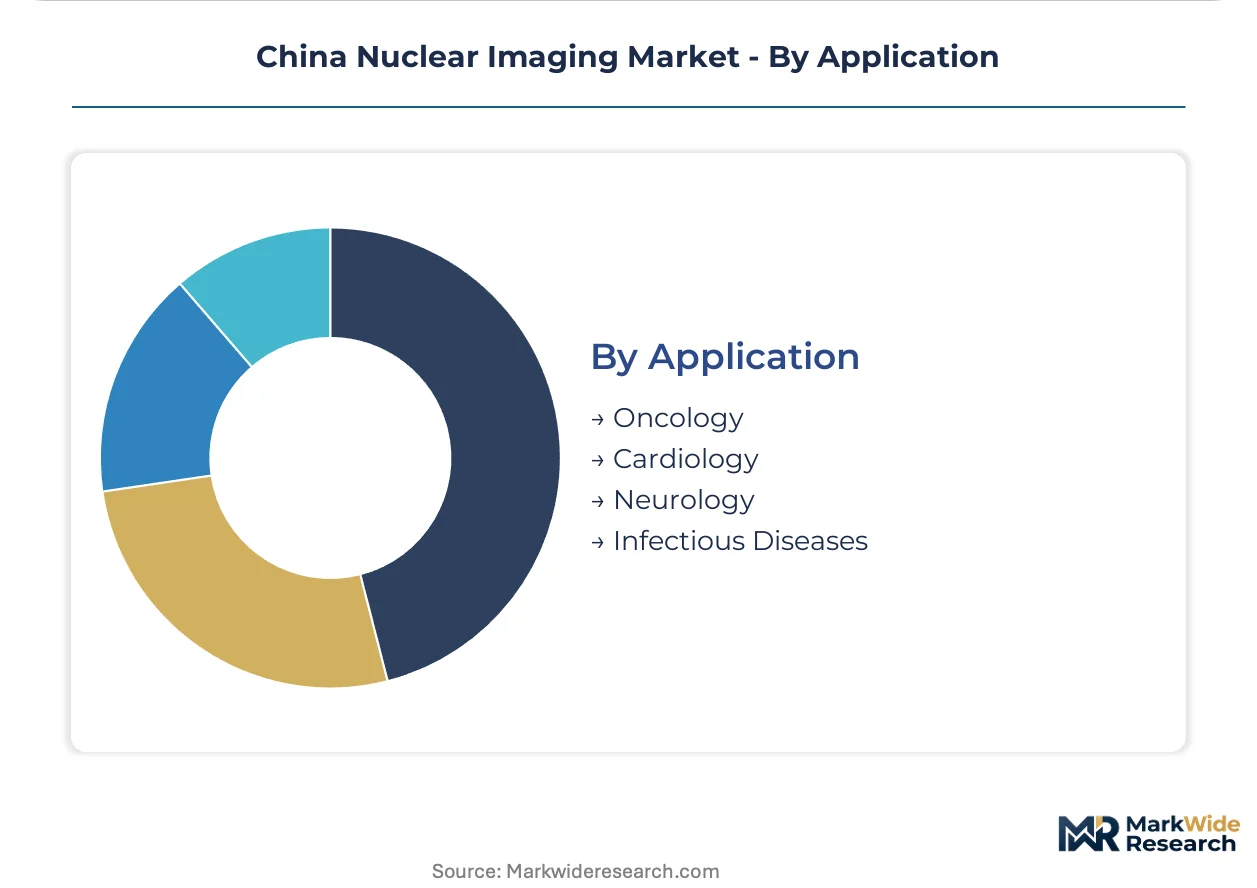
- Oncology:Tumor staging and treatment response monitoring concentrate the highest procedure volume, with NMPA scrutiny extending novel agent approval timelines. Tertiary hospital procurement focuses here under centralized bulk-purchase frameworks.
- Neurology:Alzheimer's biomarker imaging accelerates as diagnostic protocols expand PET tracer applications into neurodegenerative staging.
- Cardiology:Cardiac perfusion assessment offers faster regulatory pathways compared to oncology agents.
- Infectious Diseases:Emerging applications in infection localization remain niche.
Oncology commands largest procedure volume; Neurology shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA's Class III medical device review pathway anchors demand concentration in the Yangtze River Delta, where tertiary hospitals drive procurement volume under centralized tendering frameworks. Provincial health commissions across China are consolidating purchasing authority, reshaping how vendors access institutional buyers.
Yangtze River Delta
Shanghai and Jiangsu province generate the nation's highest imaging throughput, with oncology departments expanding PET-CT fleets under volume-based procurement mandates. NMPA's streamlined approval timelines compress innovation cycles for domestic system developers. The Shanghai cluster sustains dense service ecosystems that lower per-scan operational costs through cyclotron network effects.
Pearl River Delta
Guangdong province's tertiary hospitals are digitizing detector architectures during replacement cycles, prioritizing solid-state photon counting arrays. MIIT oversees domestic manufacturing certifications under GB standards for radiation-emitting equipment across Shenzhen and Guangzhou production bases. The region's independent imaging facilities focus on high-margin cardiac protocols with faster patient turnaround.
Beijing-Tianjin-Hebei
Academic medical centers in Beijing pilot novel radiopharmaceutical tracers under NMPA's evolving approval framework for Alzheimer's biomarkers. The dual carbon goals framework pressures facilities toward energy-efficient system architectures with extended payback periods. Tianjin's research institutions concentrate neurodegenerative staging applications beyond traditional oncology.
Sichuan-Chongqing
Western China's hospital networks address rural access gaps through mobile imaging unit deployment with reduced infrastructure requirements. Provincial centralized tendering in Sichuan fragments procurement channels, forcing equipment vendors to rebuild sales architectures around bulk-purchase frameworks. Chongqing's diagnostic centers monetize cyclotron isotope production for third-party hospital networks.
Shandong Peninsula
Shandong's tertiary hospitals balance digital detector upgrades against legacy analog PMT system compatibility engineering challenges. MEE oversight of radiation-emitting equipment forces capital expenditure toward compliant architectures. The peninsula's manufacturing base supplies rare-earth scintillation crystals for solid-state detector arrays serving domestic OEMs.
China Nuclear Imaging Market Competitive Environment
Multinational imaging system manufacturers and domestic isotope suppliers split the market into distinct capability tiers. Consolidation pressures intensify as provincial tendering platforms concentrate purchasing volume among fewer approved vendors. Equipment vendors and radiopharmaceutical producers represent the two dominant strategic archetypes, each defending position through cyclotron network coverage and detector upgrade pathways respectively. Competitive moves center on service revenue unbundling and digital detector lifecycle extension.
Among multinational equipment manufacturers, GE Healthcare, Siemens Healthineers, and Philips occupy positions anchored by installed base scale and cyclotron-equipped site networks. GE Healthcare exemplifies the service-revenue archetype through sustained technical support streams. Siemens Healthineers represents the detector-upgrade pathway, extending system lifecycles through digital architecture migration. Philips sits within the hybrid-system premium tier, positioning around fused anatomical-functional imaging capabilities. Domestic isotope security plays, including China Isotope & Radiation Corporation, compete through reactor network control and fluorine-18 supply logistics rather than equipment innovation cycles.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Inc |
| China Isotope & Radiation Corporation |
| China National Nuclear Corp |
| Yantai Dongcheng Pharmaceutical Group |
| Bracco Imaging SpA |
| Cardinal Health Inc |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on imported molybdenum-99 and fluorine-18 precursors determines both the premium spread for cyclotron-equipped installations and the geographic shape of isotope logistics networks across China.
Pricing Analysis
Configured-to-order pricing for hybrid PET-CT systems commands substantial premiums over standard configurations due to detector architecture customization and site-specific cyclotron integration requirements. Three-tier pricing structure across premium, standard, and economy levels reflects NMPA Class III certification tiers, volume procurement scale under provincial tendering, and after-sales service bundling intensity. Cost compression in mid-range system tiers is intensifying because rare-earth scintillation crystal price volatility compresses margins. Tertiary hospitals with high procedure volumes exhibit lowest price sensitivity due to centralized bulk-purchase frameworks, while independent diagnostic centers face acute margin pressure from cyclotron infrastructure requirements.
Supply Chain Analysis
Contract manufacturing concentration for solid-state photon counting arrays rests with specialized foundries in Japan, South Korea, and Taiwan, while cyclotron component assembly clusters in domestic MIIT-certified facilities. Rare-earth scintillation crystals, analog PMT legacy components, and fluorine-18 precursor chemistry kits constitute critical input dependencies. Single-source vulnerability pervades the molybdenum-99 reactor supply, with concentrated overseas production creating tariff exposure and logistics chokepoint risks. Distribution runs through provincial health commission tendering platforms that consolidate hospital procurement authority, displacing direct manufacturer relationships with institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's nuclear imaging market functions as a defensive-moat arena where cyclotron network density creates switching costs that entrench incumbent positions against new equipment vendors.
For Market Incumbents: Pre-empt domestic detector upgrade cycles by accelerating digital photon counting retrofit programs before NMPA streamlines approval pathways for local OEMs. Secure long-term isotope supply contracts with China Isotope & Radiation Corporation to defend against emerging domestic cyclotron operators threatening service revenue streams. Anchor installed base retention through backward integration into fluorine-18 production logistics.
For New Entrants and Emerging Players: Establish a beachhead in neurology biomarker imaging protocols where Alzheimer's diagnostic expansion outpaces regulatory scrutiny timelines faced by oncology tracers. Target Sichuan-Chongqing mobile imaging unit deployment as the most penetrable geography, addressing rural access gaps with reduced cyclotron infrastructure requirements. Pursue MIIT domestic manufacturing certification as the primary go-to-market angle for preferential access under GB standards compliance.
For Investors and Strategic Acquirers: NMPA's evolving radiopharmaceutical tracer approval timelines reshapes the acquisition landscape by extending clinical validation periods and elevating regulatory affairs capabilities as a scarce asset. Long-term viability centers on cyclotron-equipped service networks rather than equipment sales cycles, favoring targets with captive isotope production infrastructure. Monitor provincial centralized tendering platform vendor shortlist announcements as the critical inflection signal for competitive access dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Captive fluorine-18 production secures isotope supply autonomy against import dependency risks. |
| Digital Detector Upgrade Programs | Solid-state photon counting migration extends system lifecycles and defends installed base positions. |
| MIIT Domestic Manufacturing Certification | GB standards compliance unlocks preferential access under provincial bulk-procurement frameworks. |
| Neurology Tracer Pipeline Development | Alzheimer's biomarker protocols offer faster NMPA approval pathways compared to oncology agents. |
| Provincial Tendering Platform Registration | Approved vendor status under health commission consolidation enables hospital procurement access. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NMPA Class III device filings, MIIT GB standards documentation, and provincial health commission tendering records. Primary interviews engaged cyclotron operations directors, hospital purchasing committee members, biomedical engineering managers, and GPO contracts specialists across the Yangtze River Delta and Pearl River Delta clusters. Secondary sources included customs trade data for isotope imports, hospital procurement databases, and domestic reactor network capacity disclosures. Bottom-up procedure volume estimates triangulate against top-down capital expenditure flows from centralized tendering platforms.
Forecast inputs incorporate detector technology migration curves, provincial procurement mandate implementation schedules, and radiopharmaceutical tracer approval pipeline progression across the projection horizon. Segmentation modeling spans product architecture, end-user procurement authority concentration, detector technology generation, and clinical application area. CAGRs derive from procedure volume elasticity to fleet expansion rates and per-scan reimbursement trajectory assumptions. NMPA review timeline compression and dual carbon goals compliance cost structures inform scenario-weighted outputs.
Stress conditions across isotope supply disruption severity, rare-earth crystal price volatility bands, and provincial tendering price compression thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding NMPA regulatory pathway evolution and MIIT domestic certification penetration. Cross-checking against cyclotron installation capacity utilization rates reported in tertiary hospital financial disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
France Mammography Market
Medical Imaging
Fluoroscopy Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
China Mammography Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Global Mini C-Arm Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
France Nuclear Imaging Market
Medical Imaging
Italy Nuclear Imaging Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Interventional Radiology Market