
 Asia Pacific Magnetic Resonance Imaging (MRI) Market | 2026-2036
Asia Pacific Magnetic Resonance Imaging (MRI) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Magnetic Resonance Imaging (MRI) Market Outlook
Market Context
A shift from multi-source component procurement to captive magnet and coil production is consolidating supply relationships among Asia Pacific MRI vendors. Siemens Healthineers leverages its in-house superconducting wire capabilities to control lead times for high-field systems across East Asia. Canon Medical Systems anchors its regional position through specialized extremity MRI platforms designed for Japan's aging orthopedic patient base. United Imaging Healthcare competes aggressively on domestic China tenders by sustaining vertical integration from gradient amplifiers to software reconstruction.
Technical Definition and Segment Structure
Magnetic Resonance Imaging (MRI) is a non-invasive diagnostic modality that applies strong static magnetic fields, typically 1.5 to 3.0 Tesla for clinical systems, along with radiofrequency pulses and gradient coils to excite and spatially encode hydrogen nuclei in tissue, producing high-resolution anatomical and functional images for disease detection and treatment planning. Closed MRI systems occupy the dominant revenue position due to their superior field homogeneity and signal-to-noise ratios, though open MRI configurations are gaining traction in pediatric and claustrophobic patient segments across Southeast Asian imaging centers. Superconducting technology leads installed base value while low-field systems represent the fastest-growing technology category as Chinese manufacturers drive cost reduction for county-level hospital procurement. Oncology applications command premium pricing due to multiparametric imaging requirements, whereas neurology maintains the largest procedure volume across Japan and South Korea's hospital networks.
Regulatory Environment
China's NMPA medical device classification system and Japan's PMDA quality management requirements shape product registration timelines and clinical evidence standards for MRI systems entering these markets. India's CDSCO import licensing framework and BIS electrical safety standards create compliance layers that favor established multinationals with dedicated regulatory affairs teams in Mumbai and Delhi. Stakeholders must monitor how Australia's TGA alignment with EU MDR technical documentation requirements will reshape post-market surveillance obligations for vendors serving that market.
Market Dynamics
China's NMPA registration pathway compression is accelerating domestic superconducting MRI approvals while provincial governments in tier-two and tier-three cities fund diagnostic imaging center expansions, reshaping procurement velocity across the region.
Growth Catalysts
- Provincial Hospital Infrastructure:India's healthcare budget allocations for district hospitals are expanding high-field MRI procurement in Maharashtra and Tamil Nadu. State tender volumes for 1.5 Tesla systems are rising.
- Helium Conservation Mandates:China's dual carbon goals are pressuring manufacturers toward closed-cycle cryogenic designs. This regulatory pressure is compressing operating cost structures for hospital buyers.
- Orthopedic Imaging Demand:Japan's aging population is driving specialized extremity MRI utilization in orthopedic clinics. Procedure volumes for joint and spine imaging are climbing.
Market Restraints
- Liquid Helium Supply Concentration:Qatar and Algeria control over 60 percent of global helium production. Price volatility and export quota fluctuations create input cost uncertainty for superconducting system operators.
- Import Licensing Friction:India's CDSCO framework requires extensive technical documentation and local electrical safety testing. This regulatory layer extends commercialization timelines for new entrants.
- Low-Field Performance Ceiling:Permanent magnet systems below 0.5 Tesla cannot achieve the signal-to-noise ratios required for cardiac or functional neuroimaging. This technical limitation constrains application breadth in oncology.
Strategic Opportunities
- Vietnam Diagnostic Network Expansion:Ho Chi Minh City and Hanoi are funding provincial imaging centers through public-private partnership models. Equipment leasing structures are emerging as viable commercialization channels.
- AI-Accelerated Reconstruction:Deep learning-based image denoising is converging with low-field hardware to compress scan times. This technology pairing enables throughput gains without magnet upgrades.
- Australia TGA-EU MDR Alignment:Technical documentation harmonization is reducing duplicate clinical evidence requirements. Vendors can leverage single regulatory packages across both markets.
Industry Challenges
- Superconducting Engineer Scarcity:Cryogenic system maintenance and magnet quench recovery require specialized training. Southeast Asian service networks face technician pipeline gaps.
- Legacy PACS Integration:Hospital information systems in South Korea and Japan run on decade-old DICOM implementations. New MRI software platforms require costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Magnetic Resonance Imaging (MRI) Market |
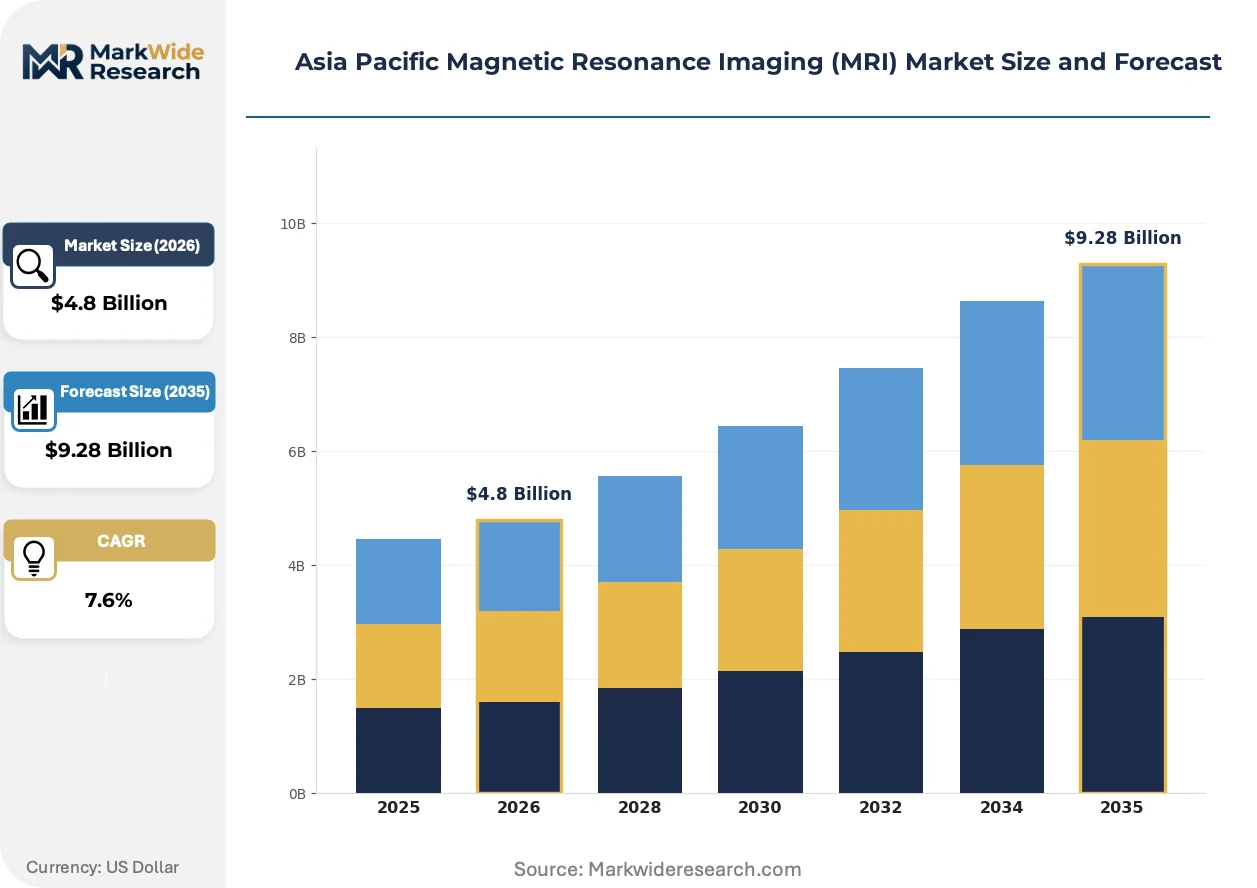
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed MRI, Open MRI, Extremity MRI, Functional MRI End User: Hospitals, Imaging Centers, Research Institutions, Clinics Technology: Superconducting, Open Magnetic, High-Field, Low-Field Application: Oncology, Neurology, Orthopedics, Cardiovascular |
| Companies Covered | Siemens Healthineers, Canon Medical Systems Corporation, Koninklijke Philips NV, GE Healthcare, Fujifilm Corporation, United Imaging Healthcare, Neusoft Medical Systems, Shenzhen Anke High-Tech, Beijing Wandong Medical Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Magnetic Resonance Imaging (MRI) Market Strategic Shifts
Artificial intelligence reconstruction algorithms and low-field permanent magnet architectures are compressing the traditional trade-off between image quality and capital cost, opening procurement pathways for budget-constrained healthcare networks.
Helium-free superconducting magnet designs are overtaking conventional liquid helium-cooled systems in new hospital construction projects. Chinese manufacturers have pioneered conduction-cooled niobium-tin wire configurations that eliminate cryogen dependence. Provincial procurement committees in Jiangsu and Sichuan are prioritizing these systems for county-level hospital deployments.
Japan's PMDA revised its software as a medical device classification guidance in 2023, creating accelerated review tracks for AI-enabled image reconstruction modules. This regulatory streamlining is compressing time-to-market for algorithm vendors targeting oncology and neuroradiology applications. Domestic Japanese manufacturers are restructuring quality management systems to capture this pathway advantage.
Diagnostic imaging centers in Thailand and Indonesia are unbundling equipment acquisition from maintenance contracts, shifting toward third-party service providers for gradient coil and RF subsystem repairs. This channel fragmentation is eroding traditional OEM service revenue streams. Independent service organizations with PMDA-trained technicians are capturing aftermarket share in Bangkok and Jakarta metropolitan clusters.
Asia Pacific Magnetic Resonance Imaging (MRI) Market Segmentation
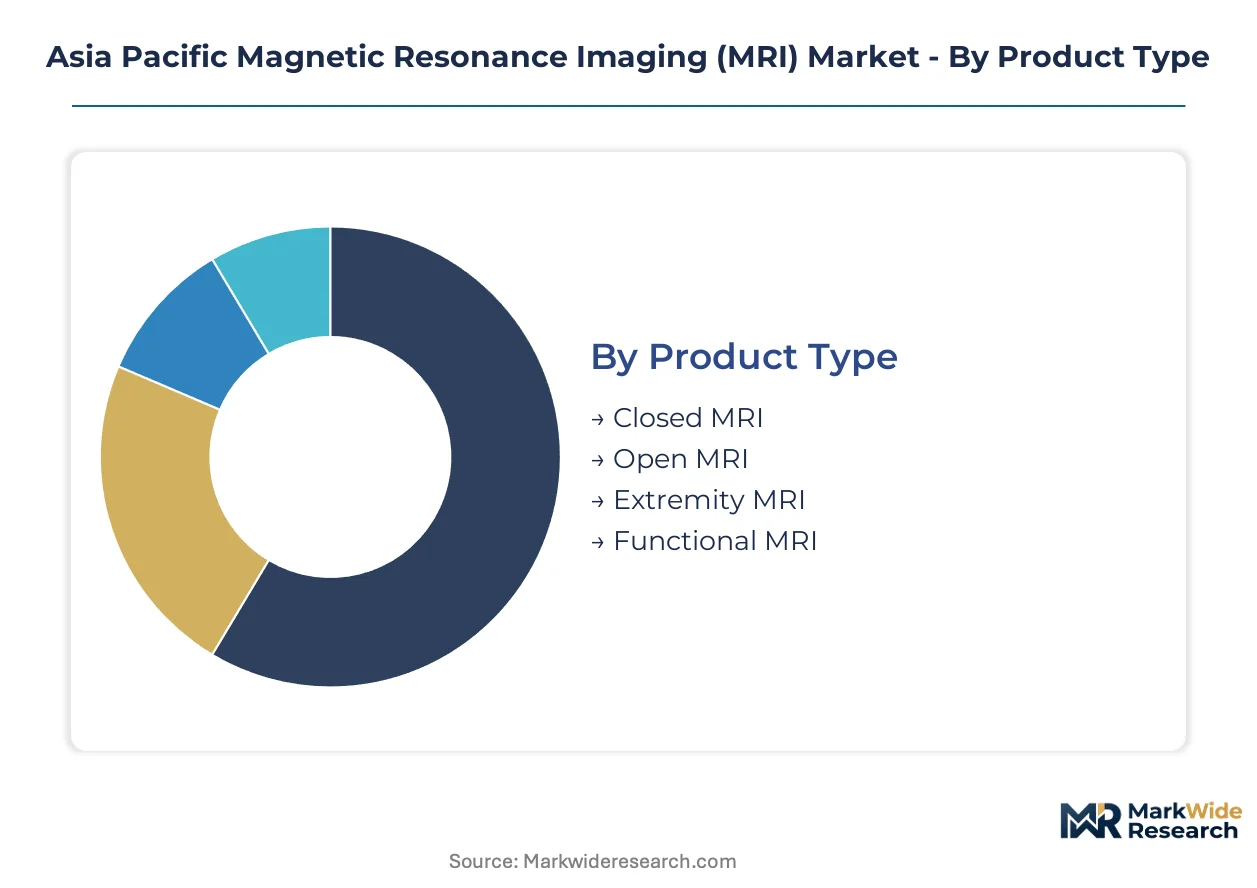
Segmentation in the Asia Pacific MRI market reveals divergent capital requirements and procurement patterns across hospital networks, imaging centers, and research institutions. Understanding these structural divisions illuminates where procurement budgets concentrate and which technology configurations align with specific clinical workflows.
Product Type:
Capital intensity varies dramatically across MRI configurations, with closed systems demanding the highest upfront investment due to superconducting infrastructure and specialized installation requirements.
- Closed MRI:Enclosed cylindrical bore designs utilizing superconducting magnets deliver superior field homogeneity and signal-to-noise ratios for whole-body imaging. Hospital procurement in China's Jiangsu and Sichuan provinces prioritizes these systems for oncology and neuroradiology departments where diagnostic precision commands premium reimbursement.
- Open MRI:C-shaped or double-doughnut magnet configurations eliminate the enclosed tunnel, accommodating claustrophobic patients and bariatric cases. Pediatric imaging centers in Bangkok and Jakarta are retrofitting facilities with open systems to capture underserved patient segments.
- Extremity MRI:Dedicated limb-scanning systems with compact permanent magnet designs target orthopedic clinics and sports medicine practices.
- Functional MRI:Blood-oxygen-level-dependent imaging systems enable real-time brain activity mapping for neurosurgical planning and research applications.
Most installed capacity flows through closed MRI systems across tier-two and tier-three Chinese cities. Expansion is steepest in extremity MRI as Japan's aging population drives specialized orthopedic diagnostics.
End User:
Procurement authority and budget scale differentiate these customer segments, with hospitals commanding the largest capital allocations and longest replacement cycles.
- Hospitals:Acute care facilities with comprehensive radiology departments purchase high-field superconducting systems for emergency, inpatient, and outpatient imaging workflows. India's district hospital modernization programs in Maharashtra and Tamil Nadu are accelerating 1.5 Tesla procurement through state tender mechanisms.
- Imaging Centers:Dedicated diagnostic facilities optimize throughput and equipment utilization across multiple referring physician networks. Independent operators in Ho Chi Minh City and Hanoi are adopting equipment leasing structures to minimize capital exposure.
- Research Institutions:University hospitals and national laboratories acquire specialized systems for clinical trial imaging and translational research protocols.
- Clinics:Single-specialty practices and ambulatory surgical centers deploy compact low-field systems for targeted diagnostic services.
Hospital procurement absorbs the majority of superconducting system shipments. Imaging centers are expanding most quickly in Vietnam's public-private partnership diagnostic networks.
Technology:
Magnet architecture determines operational cost structures, with superconducting systems requiring liquid helium or conduction-cooled cryogen management versus permanent magnet simplicity.
- Superconducting:Niobium-titanium or niobium-tin wire coils cooled to cryogenic temperatures generate fields from 1.5 to 3.0 Tesla and beyond. China's NMPA registration pathway compression is accelerating domestic manufacturer approvals for these systems.
- Open Magnetic:Permanent magnet or resistive electromagnet designs enable patient-accessible configurations without cryogenic infrastructure. Southeast Asian imaging centers favor these for pediatric and geriatric populations.
- High-Field:Systems operating at 3.0 Tesla and above deliver enhanced spatial resolution for demanding neurovascular and musculoskeletal applications.
- Low-Field:Permanent magnet systems below 0.5 Tesla reduce capital and operating costs for resource-constrained settings. County-level hospitals in China's interior provinces are prioritizing these for basic diagnostic capabilities.
Superconducting technology dominates installed base value across the region. Low-field systems are climbing the fastest as Chinese manufacturers drive cost reduction for rural hospital procurement.
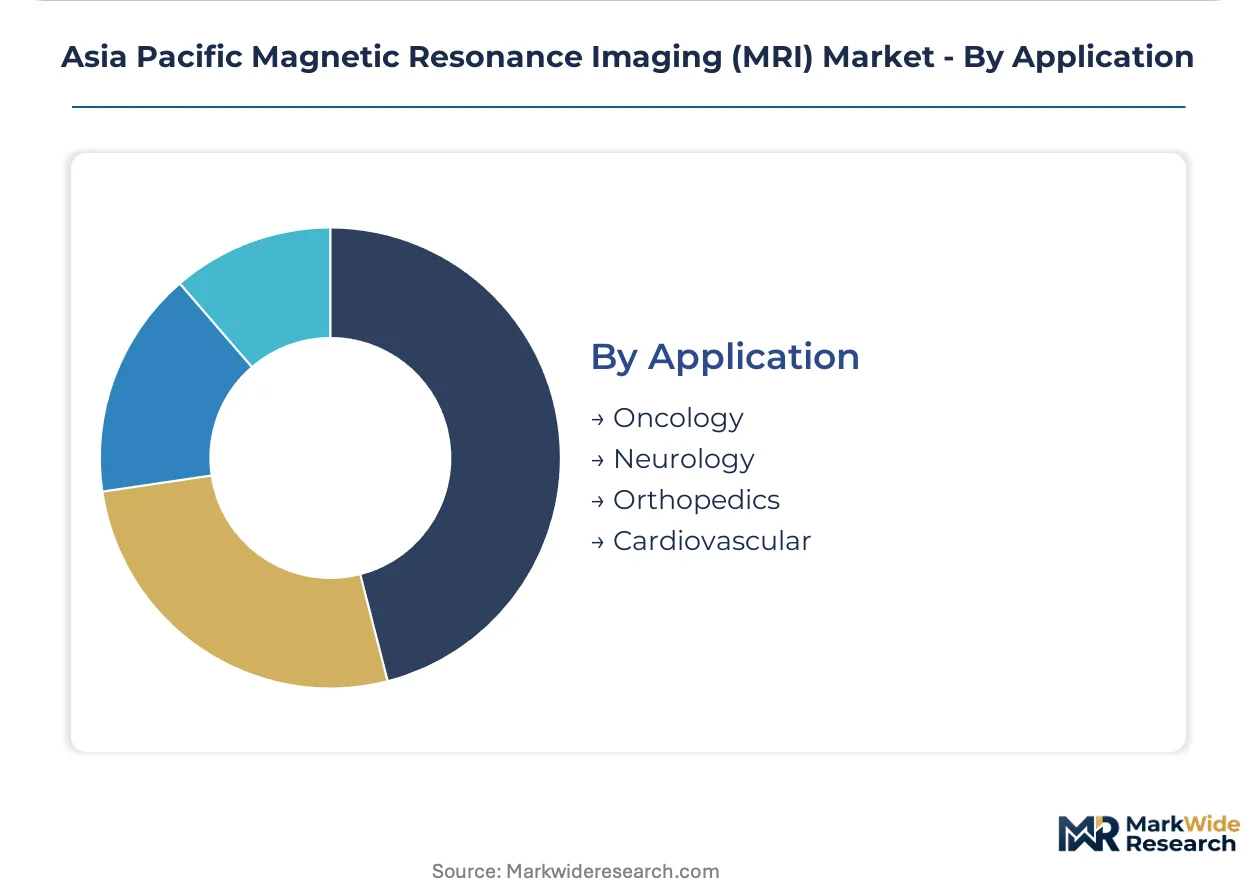
Application:
Clinical indication shapes equipment specification requirements, with oncology and functional neuroimaging demanding the most advanced gradient and RF subsystem performance.
- Oncology:Multiparametric imaging protocols combining T1, T2, diffusion-weighted, and dynamic contrast-enhanced sequences enable tumor characterization and treatment response assessment. Premium pricing reflects the complexity of hardware and software requirements.
- Neurology:Brain and spine imaging constitutes the largest procedure volume across Japan and South Korea's hospital networks, driving standardized 1.5 Tesla platform deployment.
- Orthopedics:Joint, spine, and soft tissue imaging supports surgical planning and postoperative monitoring. Japan's aging demographic is accelerating dedicated extremity MRI utilization in orthopedic clinics.
- Cardiovascular:Cardiac MRI with cine imaging and late gadolinium enhancement requires advanced gradient performance and specialized coils. Technical demands limit this application to high-field installations.
Neurology applications command the largest procedure volumes across established East Asian hospital networks. Oncology imaging is gaining share fastest as multiparametric protocols expand into provincial cancer centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Sichuan provinces anchor superconducting MRI deployment through county-level hospital procurement programs funded by provincial health budgets.
China
Provincial governments in tier-two and tier-three cities are expanding diagnostic imaging center networks through dedicated infrastructure funds. NMPA registration pathway compression accelerates domestic superconducting MRI approvals. Jiangsu and Sichuan procurement committees prioritize helium-free conduction-cooled systems for rural hospital deployments.
Japan
Aging demographics drive specialized extremity MRI utilization in orthopedic clinics and sports medicine practices. PMDA revised software as a medical device classification guidance in 2023, creating accelerated review tracks for AI-enabled reconstruction modules. Tokyo and Osaka metropolitan clusters concentrate high-field system installations for neuroradiology applications.
India
District hospital modernization programs in Maharashtra and Tamil Nadu accelerate 1.5 Tesla procurement through state tender mechanisms. CDSCO import licensing and BIS electrical safety standards create compliance layers favoring established multinationals with dedicated regulatory affairs teams. Mumbai and Delhi serve as regulatory coordination hubs for multinational market entry.
South Korea
Hospital networks maintain standardized 1.5 Tesla platform deployment for neurology applications commanding the largest procedure volumes. MFDS quality management requirements shape product registration timelines and clinical evidence standards. Seoul metropolitan hospitals drive premium system replacement cycles.
Vietnam
Ho Chi Minh City and Hanoi fund provincial imaging centers through public-private partnership models, with equipment leasing structures emerging as viable commercialization channels. Provincial health authorities expand diagnostic networks beyond major urban centers. Equipment financing innovation reduces capital barriers for independent imaging center operators.
Asia Pacific Magnetic Resonance Imaging (MRI) Market Competitive Environment
Global majors compete with regional champions across technology tiers and price segments, producing a bifurcated structure where premium high-field installations concentrate in established East Asian hospital networks while cost-optimized configurations penetrate emerging Southeast Asian markets. Market participants cluster into three archetypes: integrated superconducting system manufacturers with captive magnet production, specialized extremity and open-configuration vendors targeting orthopedic workflows, and low-field permanent magnet specialists serving county-level procurement. Dominant competitive moves include backward integration into superconducting wire and gradient coil production, plus strategic partnerships with provincial distribution networks for tender participation.
Among Germany-based integrated health technology conglomerates, Siemens Healthineers exemplifies the captive supply archetype through in-house superconducting wire capabilities controlling lead times for high-field systems across East Asia. Canon Medical Systems Corporation, a Japanese precision equipment manufacturer, occupies a position within the specialized imaging tier, anchoring regional presence through extremity platforms designed for aging orthopedic patient bases. United Imaging Healthcare, a Chinese domestic manufacturer, represents the vertically integrated challenger archetype, competing aggressively on domestic tenders through control from gradient amplifiers to software reconstruction.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Koninklijke Philips NV |
| GE Healthcare |
| Fujifilm Corporation |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Shenzhen Anke High-Tech |
| Beijing Wandong Medical Technology |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals are gating qualified superconducting magnet supply and premium-tier pricing access for hospital procurement committees in Jiangsu and Sichuan provinces. Manufacturers lacking helium-free conduction-cooled designs face exclusion from county-level tenders, while domestic champions with captive niobium-tin wire production command pricing power in tier-two and tier-three city expansions.
Pricing Analysis
Liquid helium pass-through from Qatar and Algeria supply concentration is compressing margins for superconducting system operators across India and Southeast Asia. Three-tier pricing structure across premium, standard, and economy levels separates 3.0 Tesla neuroradiology platforms from 1.5 Tesla workhorse systems and sub-0.5 Tesla permanent magnet configurations for rural deployment. Pricing pressure stems from Chinese manufacturers driving cost reduction in low-field segments through vertical integration from gradient amplifiers to software reconstruction. Imaging centers in Vietnam's public-private partnership networks exhibit highest price sensitivity, while Japan's orthopedic clinics pay premiums for specialized extremity platforms.
Supply Chain Analysis
Direct-to-hospital channels handle high-field system procurement for acute care networks in China, Japan, and South Korea, while distributor-led models serve imaging center clusters in Vietnam, Thailand, and Indonesia. Superconducting wire supply concentrates in China, Germany, and Japan, with niobium-titanium and niobium-tin coil fabrication drawing from rare earth processing in Inner Mongolia and cryogenic component manufacturing in Bavaria. Liquid helium dependency creates single-source vulnerability given Qatar and Algeria export quota volatility. Distribution runs through provincial tender platforms in China, state procurement mechanisms in India, and equipment leasing structures in Vietnam's emerging diagnostic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific MRI market functions as a stable compounder anchored by aging demographics across Japan and South Korea driving replacement cycles, plus provincial infrastructure budgets in China and India sustaining procurement velocity regardless of macroeconomic cyclicality.
For Market Incumbents: Anchor service network density in Bangkok and Jakarta metropolitan clusters to defend against independent service organizations capturing aftermarket share through PMDA-trained technician deployment. Deepen backward integration into superconducting wire production to control lead times as Chinese domestic manufacturers compress pricing in tier-two city tenders. Prioritize AI-enabled reconstruction module development to capture Japan's PMDA accelerated review tracks before algorithm vendors displace hardware differentiation. For New Entrants and Emerging Players: NMPA registration pathway compression in China opens a window for domestic superconducting MRI specialists to capture county-level hospital procurement through helium-free conduction-cooled system offerings. Target Vietnam's provincial imaging center expansion through equipment leasing structures that minimize capital barriers for independent operators. Penetrate India's district hospital modernization programs in Maharashtra and Tamil Nadu by establishing CDSCO regulatory affairs capabilities in Mumbai and Delhi before competing on state tender participation. For Investors and Strategic Acquirers: Roll-up economics work for independent service organizations with cryogenic technician training capabilities because Southeast Asian hospital networks face superconducting engineer scarcity and escalating maintenance outsourcing trends. Long-term viability centers on aftermarket revenue streams recurring through decade-long system lifecycles rather than capital equipment cyclicality. Watch helium-free magnet adoption rates in China's interior provinces as inflection indicator for technology displacement timelines across the broader installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Helium-Free Magnet Development | Eliminates cryogen dependency for NMPA approval in China's county-level tenders. |
| AI Reconstruction Module Submission | Captures PMDA accelerated review tracks in Japan's neuroradiology applications. |
| Provincial Service Network Expansion | Defends aftermarket revenue against ISO capture in Bangkok and Jakarta clusters. |
| CDSCO Regulatory Affairs Investment | Enables state tender participation in Maharashtra and Tamil Nadu hospital programs. |
| Equipment Leasing Structure Pilot | Reduces capital barriers for Vietnam public-private partnership imaging centers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committees, biomedical engineers, GPO contracts managers, and provincial health authority procurement officers alongside secondary validation through hospital procurement databases, NMPA registration filings, PMDA quality management documentation, and CMS-equivalent reimbursement schedules across Japan, South Korea, and Australia. Bottom-up system shipment modeling and top-down healthcare expenditure allocation triangulated market sizing across the analysis window.
Segment-weighting approaches distributed value and volume across product type, technology architecture, end-user category, and clinical application dimensions, with superconducting versus permanent magnet technology splits and high-field versus low-field performance tiers receiving distinct growth trajectory modeling. CAGRs derived from replacement cycle analysis, infrastructure budget allocation trends, and procedure volume elasticity to equipment penetration rates, incorporating NMPA approval velocity and provincial tender timing as China-specific forecast inputs.
Revisions become necessary when NMPA regulatory pathway timelines extend, liquid helium export quotas from Qatar and Algeria fluctuate beyond historical variance bands, or AI reconstruction algorithms achieve performance parity with high-field hardware at substantially lower capital cost points. Periodic stress-testing of base assumptions against hospital budget freeze scenarios and technician training pipeline constraints is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital X Ray Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
China Medical Imaging Market
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
US Contrast Media Market
Medical Imaging
AI-Assisted Digital Radiography Equipment Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market