
 X-Ray Flat Panel Detectors Market | 2026-2036
X-Ray Flat Panel Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Flat Panel Detectors Market Intelligence
Aftermarket service and software upgrade revenue is fragmenting the traditional hardware-centric business model for detector manufacturers. This shift forces a greater focus on lifecycle value over initial unit sales. Varex Imaging Corporation leverages its broad product portfolio to compete across both medical and industrial verticals. Canon Inc. differentiates with its deep expertise in optical and imaging systems, while Vieworks Co., Ltd. specializes in high-performance detectors for demanding scientific and industrial applications.
An X-ray flat panel detector is a solid-state device that directly or indirectly converts X-ray photons into a digital electronic signal. These detectors often use a scintillator layer, such as cesium iodide, coupled with a photodiode array. Their primary purpose is to provide high-resolution digital images for diagnostic, inspection, and security tasks, replacing conventional photographic film. While amorphous silicon (a-Si) based detectors constitute a mature segment, detectors built on CMOS technology represent the fastest-growing category. Demand from industrial inspection and security scanning applications provides new avenues for expansion beyond core medical uses.
Regulatory frameworks dictate market access and product design requirements. In the United States, the FDA's 510(k) clearance process governs medical devices, while in Europe, compliance with the Medical Device Regulation (MDR) and CE marking is mandatory. China's National Medical Products Administration (NMPA) sets parallel standards for its domestic market. Future competitive advantage depends on navigating these varied international standards while delivering quantifiable improvements in image quality and workflow efficiency.
Market Dynamics
The central dynamic shaping the market is the technological and economic tension between mature, high-volume amorphous silicon detectors for medical imaging and the ascendant, higher-performance CMOS detectors carving out new applications in industrial non-destructive testing and security.
Growth Catalysts
- CMOS Technology Adoption:The shift to CMOS sensors delivers higher resolution and faster frame rates, which is essential for detailed non-destructive testing in electronics and aerospace manufacturing.
- Industrial Automation in Asia:Demand for automated quality control in manufacturing hubs, particularly in China, drives the integration of flat panel detectors into inline inspection systems for batteries, welds, and castings.
- Security Mandates:Stricter regulations for cargo and baggage screening at ports and airports globally necessitate the deployment of high-throughput, high-resolution digital X-ray systems, replacing older technologies.
Market Restraints
- High Capital Costs:The initial investment for high-performance CMOS and large-area amorphous silicon detectors remains a significant barrier for smaller medical clinics and industrial operators compared to older imaging technologies.
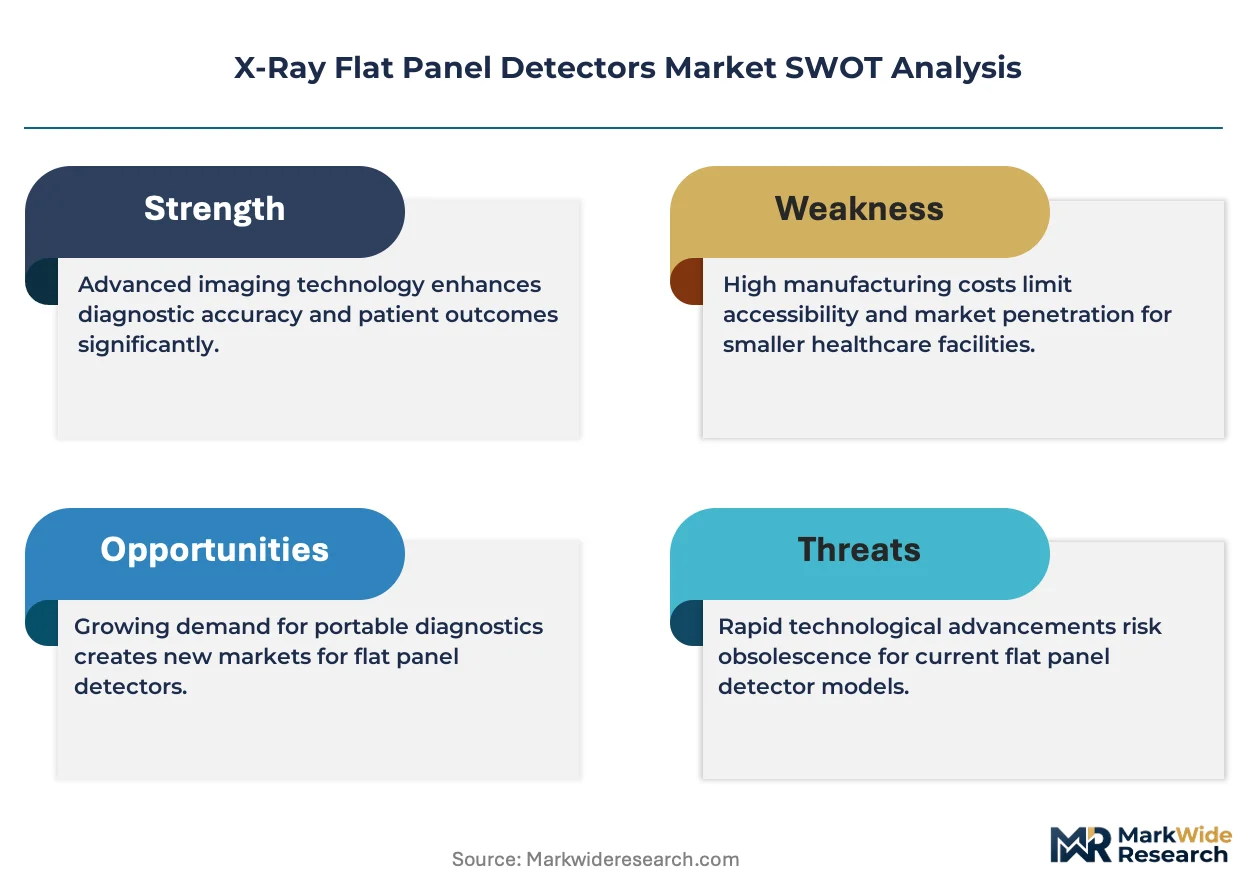
- Scintillator Material Degradation:Materials like cesium iodide used in indirect conversion detectors are sensitive to humidity and temperature, which can degrade image quality and operational lifetime if not properly managed.
- Regulatory Approval Timelines:Navigating the stringent and lengthy clearance processes of bodies like the FDA in the United States and the NMPA in China delays the market entry of new products.
Strategic Opportunities
- Portable and Wireless Detectors:There is a significant opportunity for lightweight, battery-powered detectors in field applications such as large animal veterinary medicine, pipeline integrity inspection, and mobile security screening.
- AI and Edge Computing Integration:Embedding artificial intelligence algorithms directly on the detector for automated defect recognition or preliminary diagnosis can create significant value by improving workflow efficiency and accuracy.
- Medical Infrastructure Upgrades:Emerging economies across Latin America and Southeast Asia represent a key opportunity as healthcare systems upgrade from analog X-ray film to digital radiography systems.
Industry Challenges
- Legacy System Integration:Ensuring new flat panel detectors are fully compatible with a diverse and aging installed base of Picture Archiving and Communication Systems (PACS) in hospitals presents a major technical hurdle. *Specialized Talent Scarcity: A shortage of engineers with combined expertise in semiconductor physics, high-voltage electronics, and medical imaging software development hinders innovation and product development cycles.
- Component Supply Chain Vulnerability:The supply of critical components, including large-format TFT backplanes and high-purity scintillator materials, is concentrated among a few suppliers, creating potential bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Flat Panel Detectors Market |
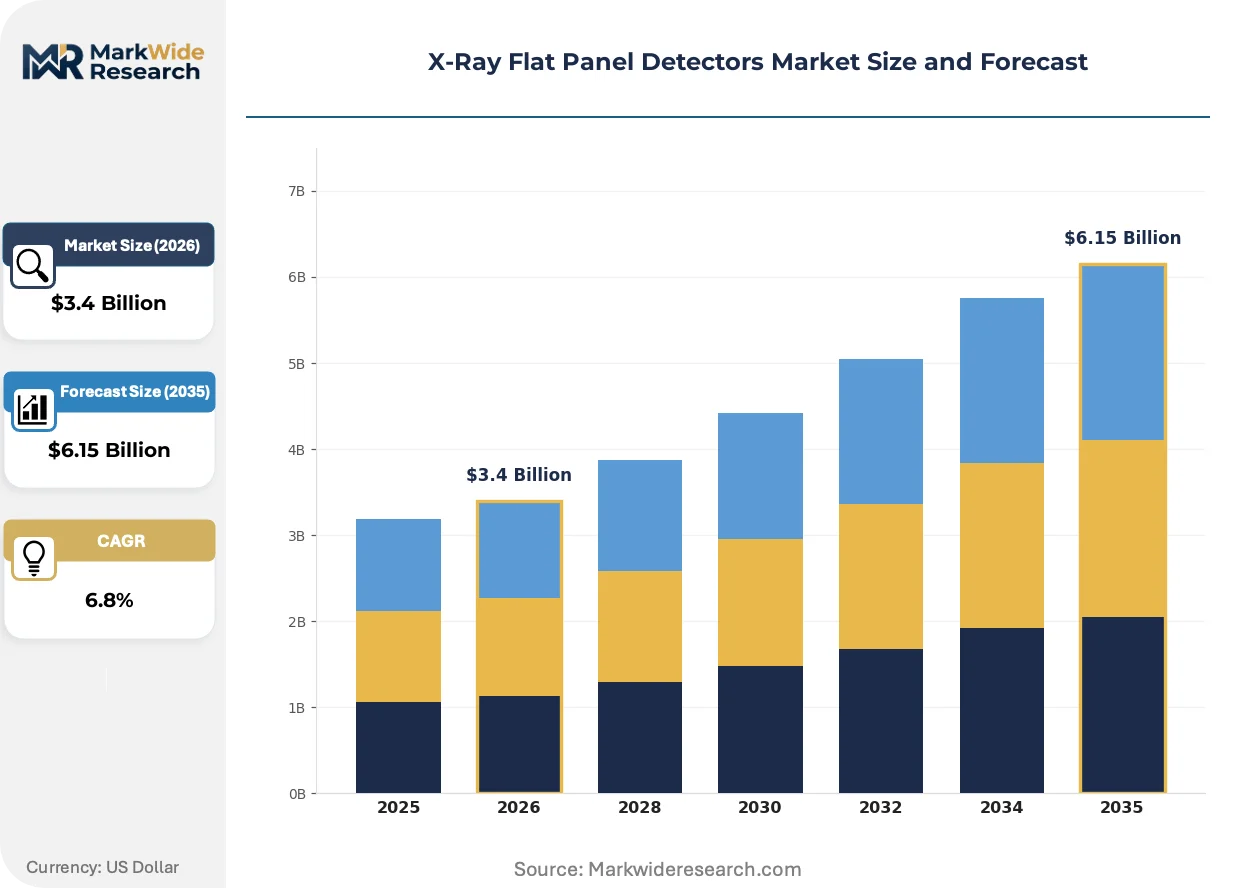
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indirect Conversion, Direct Conversion, Wireless, Wired Technology: Complementary Metal-Oxide Semiconductor, Amorphous Silicon, Cadmium Telluride, Selenium Application: Orthopedic Imaging, Dental Imaging, Veterinary Diagnostics, Security Scanning, Industrial Inspection End User: Diagnostic Clinics, Veterinary Centers, Research Laboratories, Security Agencies |
| Companies Covered | iRay Technology, Rayence, Inc., Varex Imaging Corporation, Teledyne DALSA, Hamamatsu Photonics K.K., Trixell, Vieworks Co., Ltd., Carestream Health, Canon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Flat Panel Detectors Market Strategic Shifts & Innovations
The market's evolution is defined by the detector's transformation from a simple image capture device into an intelligent edge-computing node. This shift embeds more analytical power and connectivity directly at the source of image acquisition, altering system architectures and business models.
On-detector processing, enabled by advanced System-on-Chip (SoC) designs, integrates functions like image correction and preliminary analysis directly within the detector housing. Both medical diagnostics and industrial non-destructive testing segments are adopting these intelligent detectors to accelerate workflows. This integration of processing power at the hardware level is virtualizing components of the traditional backend image processing workstation, thereby simplifying the overall system architecture.
The European Union's Medical Device Regulation (MDR) establishes more rigorous requirements for clinical evidence and post-market surveillance for all medical devices. This policy directly increases the compliance burden and extends development timelines for manufacturers seeking CE marking. The medical detector segment is most affected, compelling companies to allocate greater resources toward clinical data generation and robust quality management systems to retain access to the European market.
A significant shift is underway from one-time hardware sales to recurring revenue models based on software features, analytics, and service contracts. This unbundling of hardware from its associated software disrupts the traditional capital equipment procurement cycle, creating more predictable, long-term revenue streams. This trend is most visible in advanced industrial inspection and high-end medical imaging, where operational uptime and access to the latest analytical algorithms are critical priorities for end-users.
X-Ray Flat Panel Detectors Market Segmentation
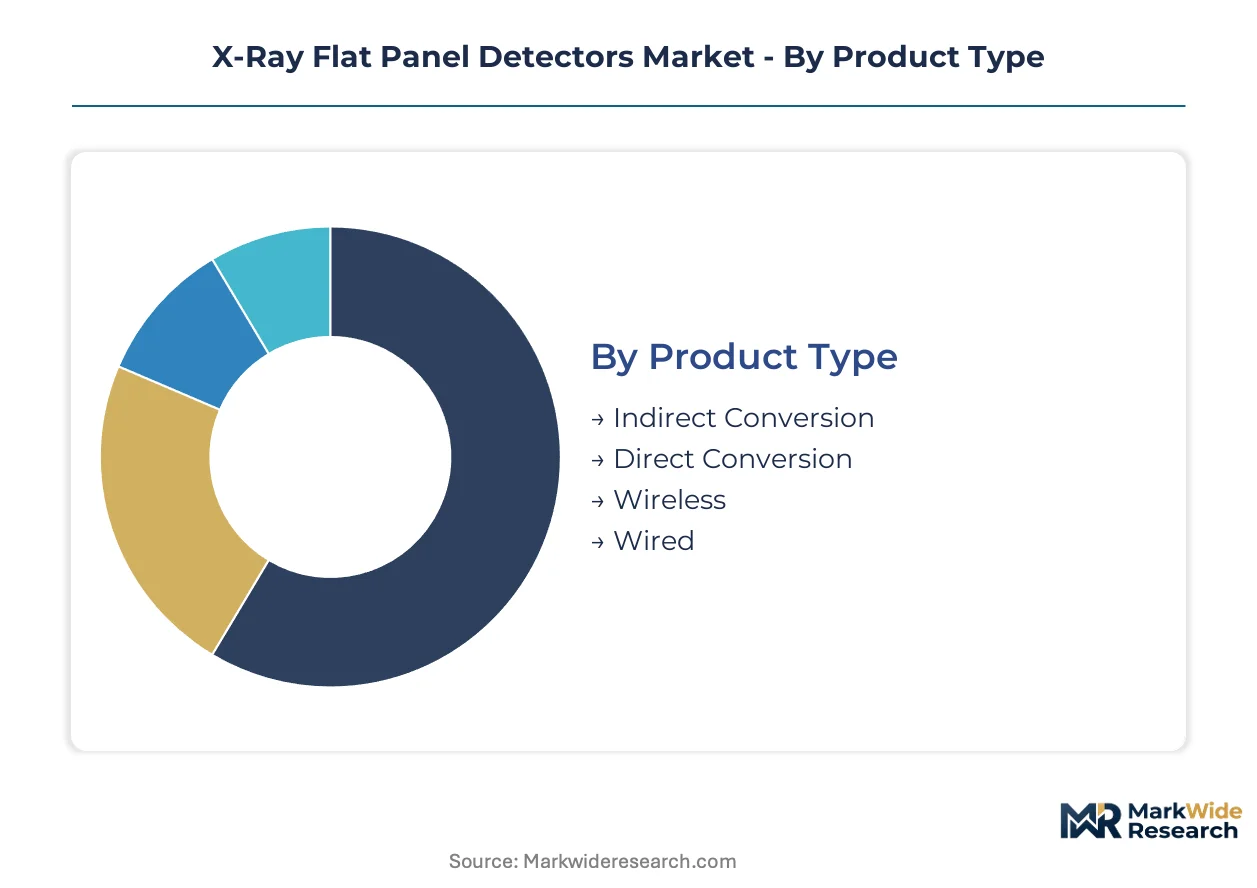
The X-ray flat panel detectors market segmentation offers a detailed view of the various product types, underlying technologies, diverse applications, and distinct end-user categories. This granular analysis helps identify specific growth pockets and areas of technological innovation within the broader market landscape.
Product Type:
Product type segmentation delineates the functional mechanisms and connectivity options available to end-users.
- Indirect Conversion:These detectors utilize a scintillator material, typically cesium iodide, to convert X-ray photons into visible light, which is then captured by a photodiode array. Demand concentrates in medical diagnostic imaging in countries like Japan and Germany, where high image quality for general radiography remains critical.
- Wireless:These battery-powered detectors transmit images via Wi-Fi or Bluetooth, offering enhanced portability and flexibility in diverse environments. Demand is concentrating in field applications such as veterinary medicine in Canada and pipeline inspection in the United States, enabling remote and difficult-to-access imaging.
- Direct Conversion:These detectors directly convert X-ray photons into an electrical charge using materials like amorphous selenium, offering superior spatial resolution.
- Wired:These traditional detectors connect directly to an imaging system via cables, ensuring stable data transmission and power supply.
Wired detectors command the established base. The steepest expansion runs through wireless detectors.
Technology:
Technological advancements drive differentiation in image quality and operational speed across various detector designs.
- Complementary Metal-Oxide Semiconductor:CMOS sensors offer higher frame rates, lower noise, and greater dynamic range compared to older technologies, enabling advanced imaging. Demand is concentrating in industrial non-destructive testing in China and aerospace manufacturing in the United States, where rapid, high-resolution defect detection is paramount.
- Amorphous Silicon:Amorphous silicon (a-Si) detectors are a mature technology, widely used due to their large area coverage and cost-effectiveness for general radiography. Demand is concentrating in hospital upgrades across Southeast Asia and Latin America, replacing analog film systems in established medical facilities.
- Cadmium Telluride:These detectors provide high X-ray stopping power and direct conversion capabilities, suitable for high-energy applications.
- Selenium:Amorphous selenium is a direct conversion material known for excellent spatial resolution, primarily used in mammography and industrial applications.
Amorphous silicon technology dominates existing installations, while complementary metal-oxide semiconductor technology is expanding most quickly.
Application:
The diverse applications of X-ray flat panel detectors reflect their adaptability across medical, security, and industrial sectors.
- Industrial Inspection:This segment involves using X-ray detectors for non-destructive testing of materials, components, and assemblies in manufacturing processes. Demand is concentrating in automotive manufacturing in Germany and electronics production in South Korea, driven by stringent quality control requirements for complex products.
- Security Scanning:Detectors are deployed in baggage, cargo, and personnel screening systems at airports, ports, and border crossings to detect contraband or threats. Demand is concentrating in major international airports in the United States and seaports in the Netherlands, driven by global security mandates and high-throughput requirements.
- Orthopedic Imaging:This application focuses on capturing images of bones and joints for diagnosing fractures, dislocations, and degenerative conditions.
- Dental Imaging:Detectors are used for intraoral and panoramic X-rays to assess dental health and plan treatments.
- Veterinary Diagnostics:This involves using X-ray systems to diagnose injuries and illnesses in animals, from small pets to large livestock.
Medical applications form a substantial demand base; however, industrial inspection and security scanning are driving new revenue streams.
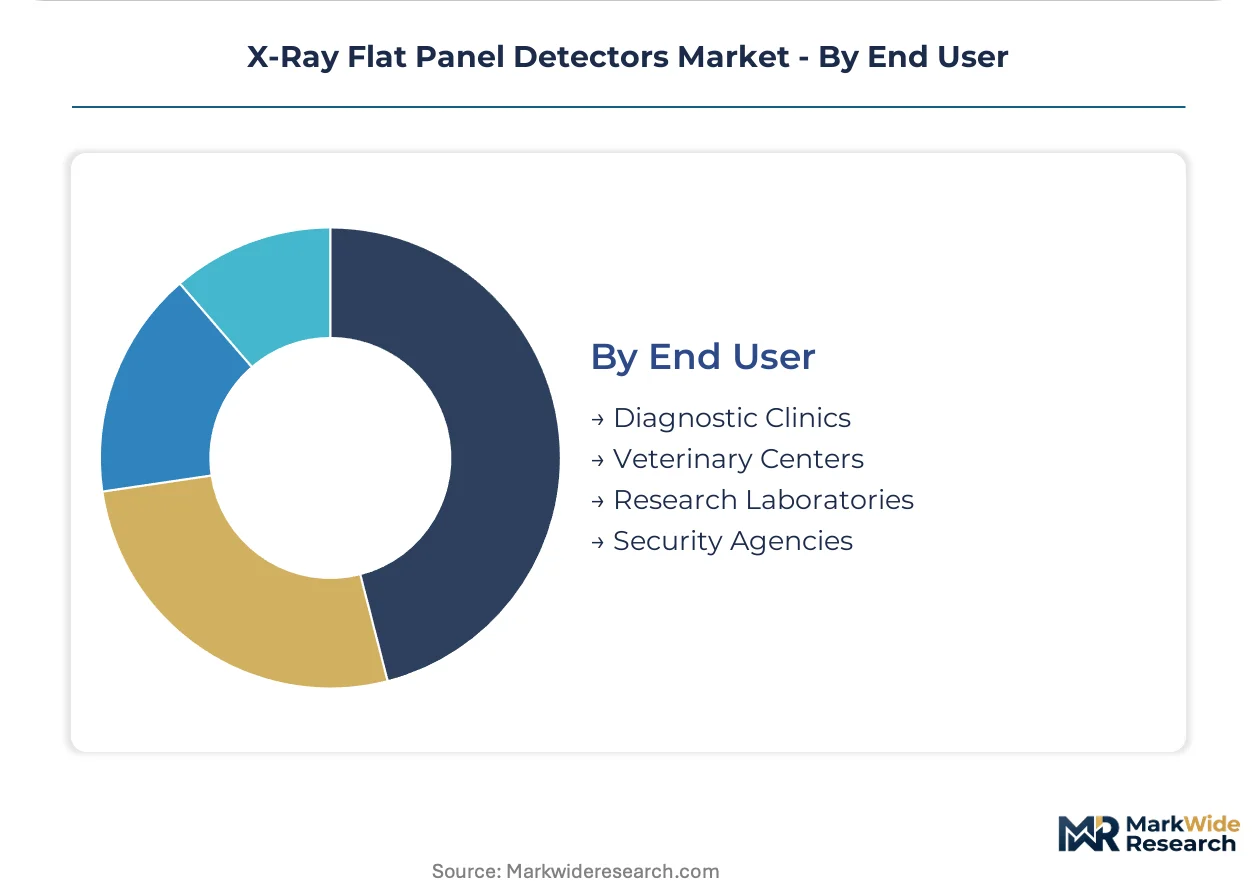
End User:
End-user segments highlight the varied operational environments and specific imaging requirements influencing detector design and sales.
- Diagnostic Clinics:These facilities provide outpatient medical imaging services, including general radiography, to a broad patient population. Demand is concentrating in urban centers across India and Brazil, driven by expanding healthcare infrastructure and patient access to digital imaging.
- Security Agencies:Government and private security organizations deploy X-ray systems for screening purposes at critical infrastructure points and public venues. Demand is concentrating at international borders in the United States and major transportation hubs in the United Kingdom, driven by evolving threat landscapes and regulatory compliance.
- Veterinary Centers:These clinics provide diagnostic imaging for animals, ranging from routine check-ups to complex surgical planning.
- Research Laboratories:Academic and industrial research facilities use X-ray detectors for material science, physics, and preclinical studies.
Diagnostic clinics represent the largest volume of detector deployments, with security agencies showing significant procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for X-ray flat panel detectors exhibits varying price elasticities across different regions. Some markets prioritize cost-effectiveness for widespread medical upgrades, while others demand cutting-edge performance for high-precision industrial inspection regardless of initial investment. This distinction shapes regional procurement strategies for X-ray flat panel detectors, influencing technology adoption and market growth.
China
China's industrial automation initiatives drive significant demand for high-resolution CMOS detectors in non-destructive testing. The NMPA's stringent medical device standards also influence product design for domestic medical applications. Manufacturing hubs in the Yangtze River Delta integrate these detectors into inline inspection systems for batteries and automotive components.
United States
Demand in the United States stems from advanced aerospace manufacturing and evolving security screening mandates. The FDA's 510(k) clearance process rigorously vets new medical imaging devices before market entry. Aerospace clusters in Seattle and Wichita deploy high-performance detectors for critical component inspection.
Germany
Germany exhibits strong demand for industrial inspection in automotive manufacturing and precision medical diagnostics. Compliance with the EU's Medical Device Regulation (MDR) is mandatory for market access and product design. Automotive production centers around Stuttgart and Munich utilize advanced X-ray systems for weld and casting integrity.
Japan
Japan's market emphasizes high image quality for medical diagnostics and precision non-destructive testing in electronics. The PMDA sets rigorous standards for medical device approval, influencing detector development. Research and development hubs in Tokyo drive innovation for indirect conversion detectors in general radiography.
India
India's market for X-ray flat panel detectors is expanding due to significant medical infrastructure upgrades. The CDSCO regulates medical device imports and manufacturing, impacting market entry for new products. Diagnostic clinics in urban centers like Mumbai and Delhi are rapidly adopting digital radiography systems.
X-Ray Flat Panel Detectors Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another within the X-ray flat panel detectors market. This market presents a tiered structure, from large, diversified imaging solutions providers to specialized component manufacturers. Three strategic archetypes emerge: established generalists with broad portfolios, high-performance specialists focusing on niche applications, and agile innovators leveraging new material science. Portfolio diversification across medical and industrial verticals, alongside strategic partnerships for system integration, are dominant competitive moves. Geographic expansion also remains a key strategy for market penetration.
Companies such as Varex Imaging Corporation exemplify the established generalist archetype, offering a wide range of detectors for both medical and industrial sectors. Canon Inc., leveraging its deep expertise in optical and imaging systems, occupies a position as a diversified technology conglomerate with significant detector offerings. Vieworks Co., Ltd. represents the high-performance specialist, focusing on advanced detectors for demanding scientific and industrial applications. These entities collectively anchor the market's competitive dynamics across different performance and cost segments, driving innovation in image quality and workflow efficiency.
| Leading Market Players |
|---|
| iRay Technology |
| Rayence, Inc. |
| Varex Imaging Corporation |
| Teledyne DALSA |
| Hamamatsu Photonics K.K. |
| Trixell |
| Vieworks Co., Ltd. |
| Carestream Health |
| Canon Inc. |
| Others |
Cost & Logistics Intelligence
Component supply chain vulnerability, particularly for large-format TFT backplanes and high-purity scintillator materials, determines both pricing tier spreads and the overall supply chain shape within the X-ray flat panel detectors market. This concentration of critical component manufacturing creates potential chokepoints, influencing final product costs and market access for detector manufacturers.
Pricing Analysis
After-sales service and software upgrade revenue drives lifetime value for detector manufacturers, shifting focus from initial hardware sales. Pricing stratifies across premium, standard, and economy tiers, with differentiation stemming from image quality, regulatory certifications like FDA 510(k) and CE marking, and bundled after-sales service contracts. Pricing pressure on initial hardware units stems from the shift towards lifecycle value models. Smaller medical clinics and industrial operators exhibit higher price sensitivity compared to aerospace manufacturers or large hospital networks.
Supply Chain Analysis
Contract-manufacturing concentration for critical components primarily sits with specialized foundries in East Asia. Geographic supply concentration for these detectors and their sub-components centers in China, South Korea, and Japan. The industry draws from raw material dependencies including large-format TFT backplanes and high-purity cesium iodide scintillator materials. A structural supply chain risk is single-source vulnerability for these specialized components. Distribution runs through a combination of direct sales to large medical OEMs and industrial integrators, alongside specialized distributors serving smaller end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the rapid adoption of CMOS technology and escalating demand for digital imaging across diverse applications. The transformation of detectors into intelligent edge-computing nodes creates new value propositions.
For Market Incumbents: Harden core product portfolios by investing in advanced CMOS manufacturing capabilities and diversifying across medical and industrial verticals. Integrate AI and edge computing directly into detector hardware to enhance workflow efficiency and analytical power. Pursue strategic partnerships with system integrators to ensure seamless compatibility with existing Picture Archiving and Communication Systems (PACS) and industrial automation platforms.
For New Entrants and Emerging Players: Pursue white-space opportunities in portable and wireless detector solutions for field applications such as large animal veterinary medicine and pipeline integrity inspection. Target emerging economies across Latin America and Southeast Asia as healthcare systems upgrade from analog X-ray film. A go-to-market angle focusing on software-defined features and recurring revenue models can disrupt traditional hardware-centric procurement cycles.
For Investors and Strategic Acquirers: The EU Medical Device Regulation (MDR) reshapes the acquisition landscape, favoring companies with robust clinical evidence and quality management systems. Long-term viability hinges on the sustained global demand for high-resolution digital imaging and the ongoing shift towards intelligent, connected devices. Acquisition targets should include specialized firms in advanced CMOS sensor development, AI integration for image analysis, or novel scintillator materials. Quarterly review of regulatory approval timelines and component supply chain stability is advised to detect inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in CMOS Manufacturing Capacity | Ensures competitive advantage in high-resolution, high-speed imaging for industrial and advanced medical uses. |
| Integrate AI for On-Detector Processing | Enhances workflow efficiency and diagnostic accuracy, reducing reliance on traditional backend workstations. |
| Expand Portable/Wireless Detector Offerings | Captures new market segments in field diagnostics and mobile security screening. |
| Secure Long-Term Scintillator Material Contracts | Mitigates supply chain vulnerability for critical components, ensuring production stability. |
| Obtain Global Regulatory Clearances (FDA, CE, NMPA) | Unlocks market access and accelerates product adoption in key medical and industrial geographies. |
Research Approach
Desk research of regulatory filings, industry association reports, and patent databases preceded structured interviews with imaging system OEMs, medical device engineers, industrial NDT specialists, and regulatory affairs managers. This approach facilitated a comprehensive understanding of market dynamics, technology trends, and competitive landscapes. Data triangulation across primary and secondary sources ensured a robust and validated analytical foundation for both bottom-up and top-down market sizing.
Assumptions regarding technological adoption rates, regulatory stability, and macroeconomic conditions were held fixed across the analysis window, while variations in regional healthcare spending and industrial automation investments were modeled. The analytical framework incorporated segmentation dimensions including product type, technology, application, end-user, and geographic adoption rates. Compound Annual Growth Rates (CAGRs) were derived through a regression analysis of historical market data and projected future demand, informed by inputs such as CMOS manufacturing capacity expansion and healthcare infrastructure spending.
Sensitivities concentrate around potential regulatory changes, unforeseen supply chain disruptions, and rapid technological breakthroughs that could alter market trajectories. Forecasts reflect these underlying assumptions. Quarterly review of new product launches, key regulatory approvals, and major component pricing trends is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Nuclear Medicine Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Treatment Planning Systems and Advanced Image Processing Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
France Magnetic Resonance Imaging Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
Chile Diagnostic Imaging Equipment Market
Medical Imaging
Argentina Digital X-Ray Market
Medical Imaging
3D Imaging Surgical Solution Market
Medical Imaging
Fluoroscopy C-Arms Market
Medical Imaging
Asia Pacific Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Medical Imaging Management Market
Medical Imaging
South Korea Computed Tomography Market
Medical Imaging
CT Guided Intervention Market
Medical Imaging
South America Nuclear Imaging Market