
 China Mammography Market | 2026-2036
China Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
China Mammography Market Outlook
Equipment leasing and pay-per-scan service models are reshaping capital deployment across China's mammography landscape, lowering barriers for secondary hospitals to access premium imaging platforms. Siemens Healthineers leverages its localized manufacturing base in Shanghai to sustain cost-competitive positioning for digital systems. United Imaging Healthcare anchors its domestic market presence through vertically integrated detector production and direct hospital channel control. GE Healthcare competes by extending its service infrastructure into tier-two and tier-three cities, capturing recurring revenue streams beyond initial hardware sales.
Mammography encompasses X-ray-based breast imaging utilizing low-dose ionizing radiation to detect microcalcifications and soft-tissue masses, with full-field digital systems employing amorphous selenium or cesium iodide flat-panel detectors achieving spatial resolution below 100 micrometers for clinical screening programs. Full-field digital mammography dominates installed base volumes across Chinese provincial hospitals, while 3D tomosynthesis systems command premium positioning in top-tier oncology centers where reimbursement differentials justify higher capital outlay. Portable systems represent the fastest-expanding installation category, driven by mobile screening vans serving rural counties under national cancer prevention initiatives.
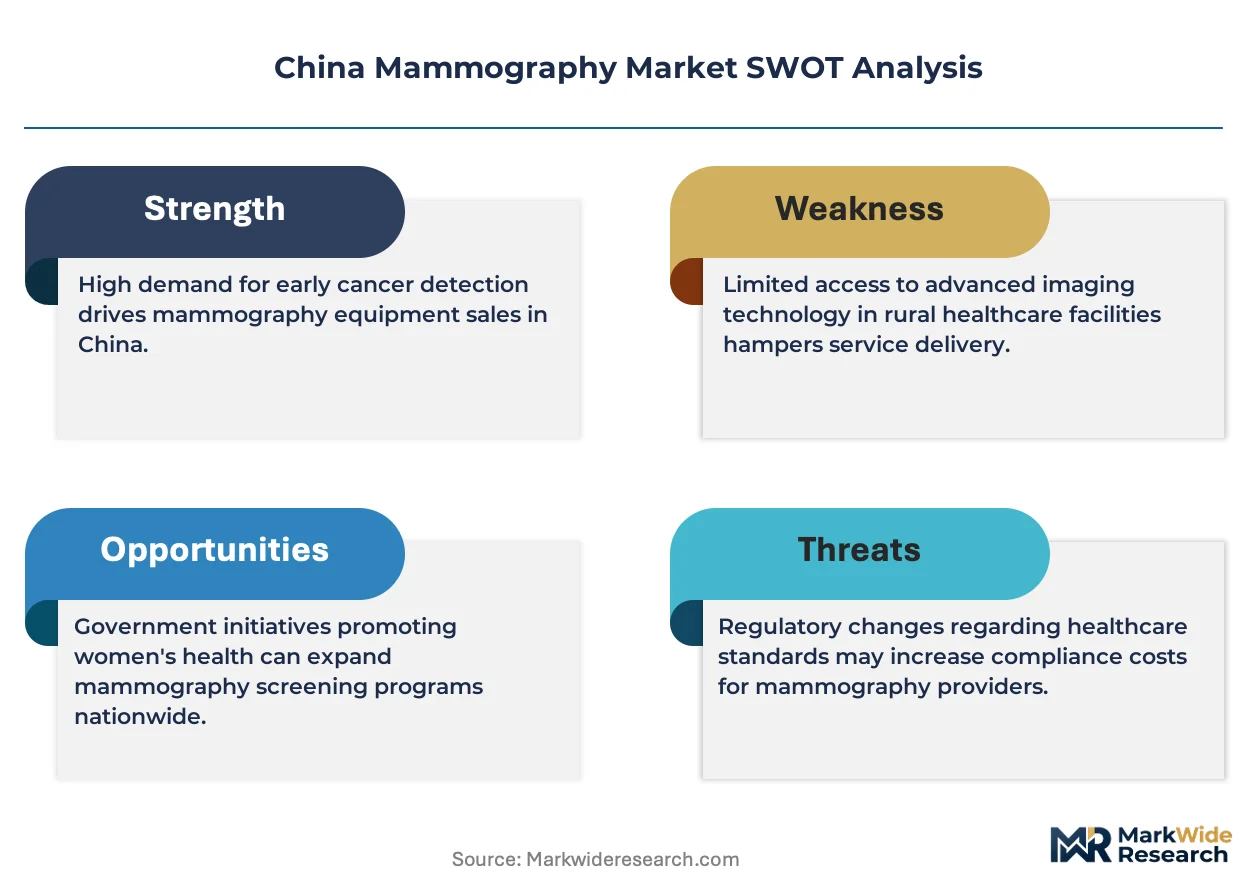
NMPA medical device registration requirements enforce clinical validation standards for digital breast tomosynthesis algorithms, while China's dual carbon goals from MEE pressure manufacturers toward energy-efficient tube designs and reduced rare-earth dependency in scintillator materials. GB standards for electromagnetic compatibility and radiation safety shape product specification sheets for all imported and domestically produced systems. Stakeholders must monitor NMPA's evolving software-as-medical-device guidance, which will determine whether AI-assisted detection modules require separate regulatory pathways or piggyback on existing hardware licenses.
Market Dynamics
Equipment leasing and pay-per-scan service models are compressing capital deployment cycles across China's mammography landscape, enabling county-level hospitals to access premium digital imaging platforms without upfront ownership burdens.
Growth Catalysts
- NMPA streamlined registration:Updated medical device classification rules accelerate digital mammography approval pathways, reducing time-to-market for domestic and imported systems.
- County-level network expansion:Tier-three municipal hospitals are procuring systems at accelerated rates to fulfill national cancer prevention mandates across rural screening programs.
- Amorphous selenium detector maturation:Advances in flat-panel detector manufacturing are lowering unit costs while maintaining sub-100 micrometer spatial resolution for clinical-grade screening.
Market Restraints
- Rare-earth supply concentration:Cesium iodide scintillator production depends on concentrated rare-earth processing, exposing manufacturers to input cost volatility and MEE dual carbon compliance pressures.
- 3D tomosynthesis reimbursement gaps:Premium system deployment faces structural headwinds where provincial reimbursement differentials fail to justify capital outlay outside top-tier oncology centers.
- Specialized radiologist scarcity:Breast imaging interpretation requires fellowship-trained specialists, creating bottlenecks in tier-two and tier-three city deployment.
Strategic Opportunities
- Mobile screening van networks:Portable system categories are capturing fastest-expanding installation volumes under national rural cancer prevention initiatives.
- AI-assisted detection modules:NMPA software-as-medical-device guidance will clarify whether algorithmic tools require separate regulatory pathways or piggyback on hardware licenses.
- Yangtze River Delta cluster densification:Demand concentrates in Shanghai-Jiangsu-Zhejiang corridor where hospital procurement budgets and screening program maturity exceed national averages.
Industry Challenges
- GB standards compliance complexity:Electromagnetic compatibility and radiation safety specifications require redesign cycles for both imported and domestically produced systems.
- Legacy analog system integration:County hospitals with existing film-based infrastructure face workflow reconfiguration costs when transitioning to full-field digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Mammography Market |
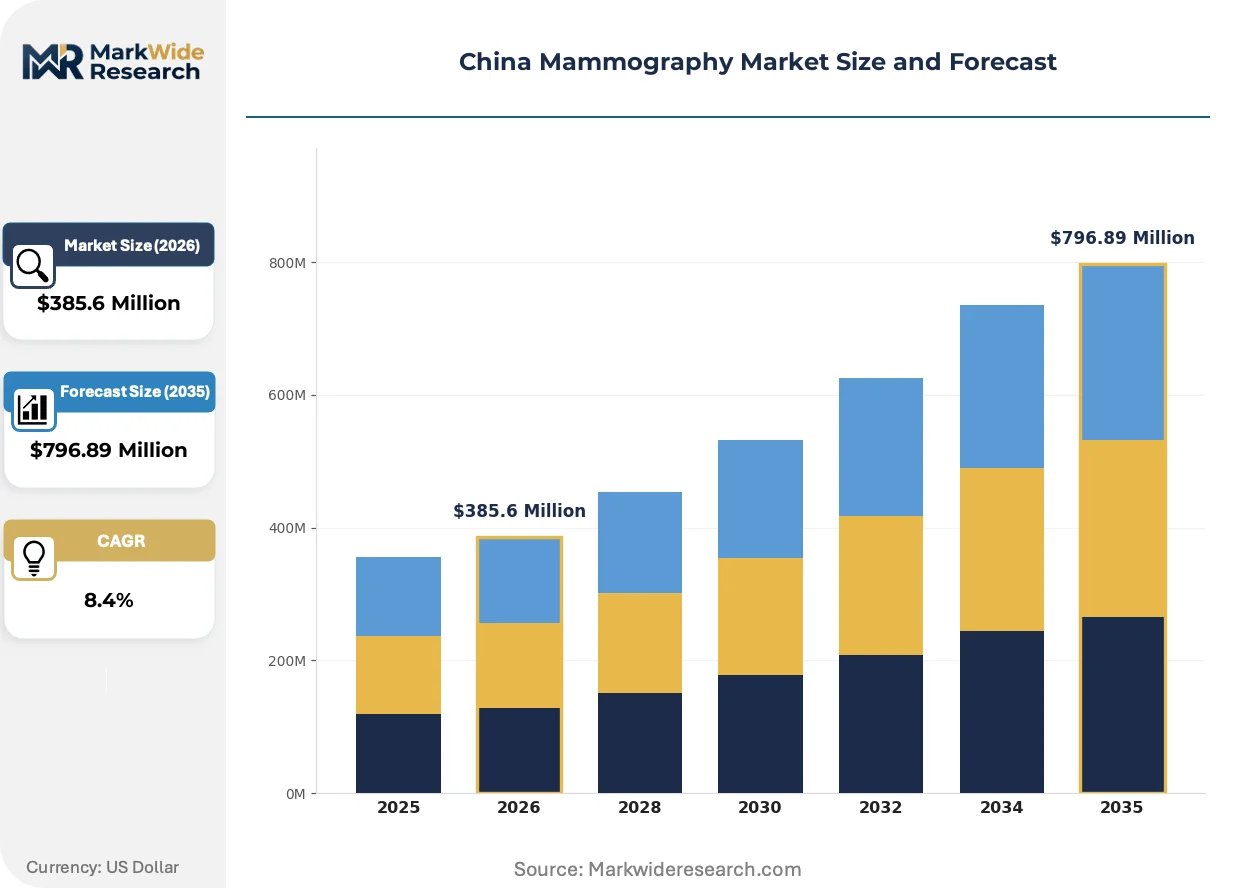
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Field Digital, Screen-Film, 3D Mammography, Portable Systems Technology: Analog, Digital, Tomosynthesis, Contrast-Enhanced End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Installation: Fixed, Mobile, On-Demand, Hybrid |
| Companies Covered | Fujifilm Holdings Corporation, Koninklijke Philips NV, GE Healthcare, Mindray Bio-Medical Electronics Co., Canon Inc., Siemens Healthineers AG, Carestream Health Inc., United Imaging Healthcare Co., Hologic Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Mammography Market Strategic Shifts
Digital breast tomosynthesis algorithms are compressing diagnostic uncertainty while NMPA regulatory frameworks and mobile deployment models reshape competitive positioning across China's screening infrastructure.
Photon-counting detector technology is digitizing mammography signal processing at the photon level, eliminating electronic noise floors that constrain conventional energy-integrating detectors. Top-tier oncology centers in Beijing and Shanghai are piloting these systems for high-risk patient stratification. The technology is digitizing the trade-off between radiation dose reduction and image quality that has historically limited screening frequency in dense breast populations.
MEE dual carbon goals are forcing energy-efficient X-ray tube redesigns across all NMPA-registered mammography systems, with manufacturers eliminating rare-earth dependencies in scintillator materials to align with national emissions reduction timelines. Provincial hospital procurement committees are now weighting lifecycle energy consumption in tender evaluations. Domestic detector producers are responding with localized supply chains that reduce carbon intensity in raw material sourcing.
Service-based contracting is displacing capital purchase models across Jiangsu and Zhejiang provincial health systems, with pay-per-scan arrangements transferring utilization risk from hospital balance sheets to equipment vendors. Siemens Healthineers and United Imaging Healthcare are restructuring sales organizations to capture recurring revenue streams through managed service agreements. County-level networks in Anhui and Shandong are adopting these structures to circumvent centralized capital budget constraints.
China Mammography Market Segmentation
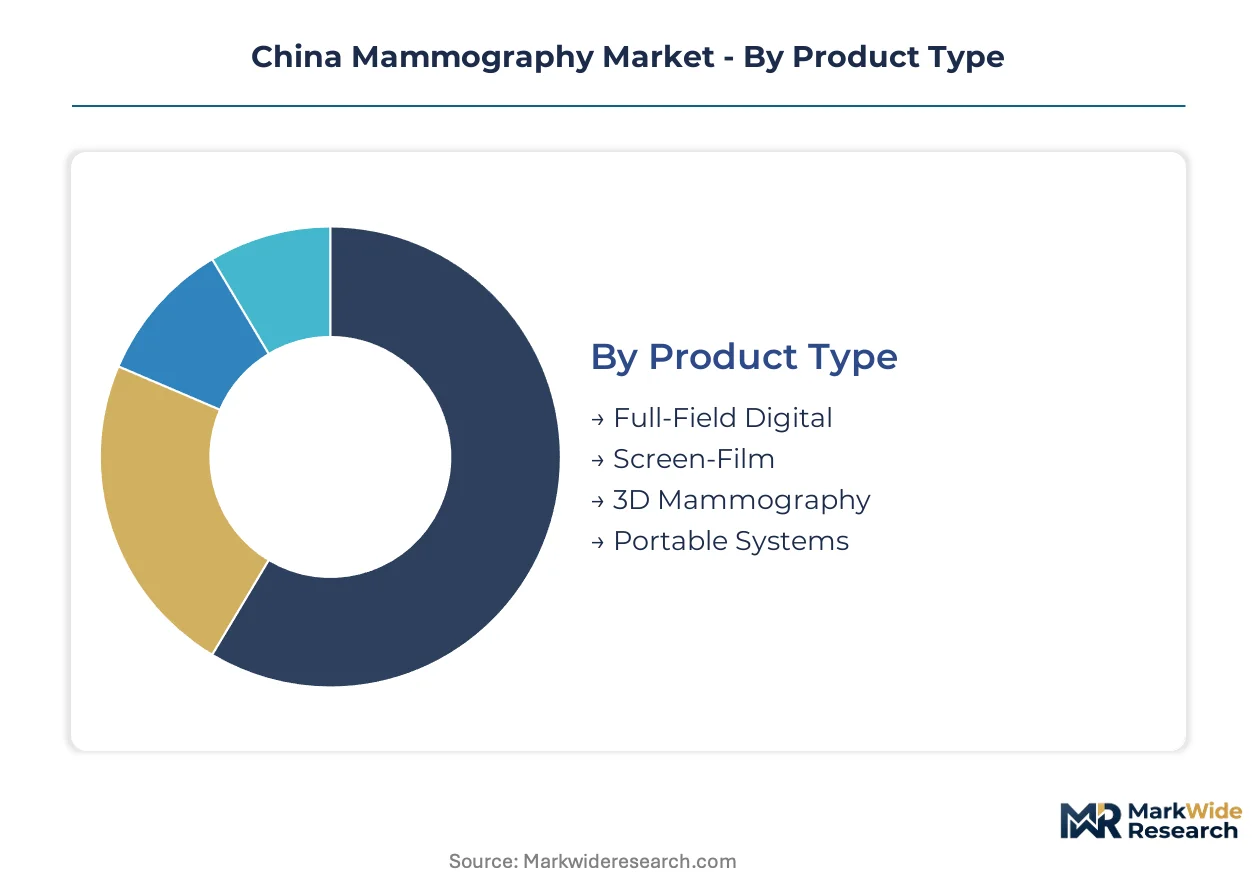
Equipment service intensity varies sharply across mammography segments in China, with digital platforms demanding multi-year maintenance contracts while portable units shift utilization risk to vendors through pay-per-scan structures. Procurement committees weigh total cost of ownership against throughput requirements when segmenting capital allocation across hospital tiers.
Product Type:
After-sales service contracts differentiate product tiers, with premium platforms commanding multi-year maintenance agreements and remote diagnostic capabilities.
- Full-Field Digital:Amorphous selenium or cesium iodide flat-panel detectors achieve sub-100 micrometer spatial resolution for clinical screening programs. Provincial hospitals in Jiangsu and Zhejiang concentrate procurement here, driven by NMPA streamlined registration pathways that accelerate deployment timelines.
- 3D Mammography:Tomosynthesis algorithms reconstruct thin-slice breast images from multiple projection angles, reducing tissue overlap artifacts. Beijing and Shanghai oncology centers absorb premium system volumes where reimbursement differentials justify capital outlay despite higher per-scan costs.
- Screen-Film:Legacy analog systems persist in underfunded county hospitals facing workflow reconfiguration barriers.
- Portable Systems:Mobile screening vans serving rural Anhui and Shandong counties drive fastest-expanding installation volumes under national cancer prevention mandates.
Full-Field Digital holds the largest share; momentum sits with Portable Systems.
Technology:
Detector manufacturing maturity shapes cost trajectories across technology tiers, with domestic producers narrowing performance gaps against imported platforms.
- Digital:Flat-panel detectors digitize X-ray signals for immediate display and storage, eliminating chemical processing. Yangtze River Delta hospital clusters standardize on these systems where procurement budgets accommodate premium positioning.
- Tomosynthesis:Three-dimensional reconstruction algorithms separate overlapping tissue structures, improving cancer detection rates in dense breast populations. NMPA clinical validation requirements enforce algorithmic performance standards before market authorization.
- Analog:Screen-film combinations require darkroom processing and chemical handling, constraining deployment to capital-constrained facilities.
- Contrast-Enhanced:Iodinated contrast agents highlight vascular patterns in suspicious lesions, serving diagnostic rather than screening applications.
Digital dominates installed base volumes; Tomosynthesis climbs fastest in tier-one oncology centers.
End User:
Capital deployment cycles diverge by institution type, with municipal hospitals owning equipment versus imaging clinics favoring service-based contracting.
- Hospitals:Tier-three municipal hospitals anchor procurement volumes as county-level network expansion accelerates under national cancer prevention mandates. NMPA registration compliance and GB standards adherence shape tender specifications.
- Diagnostic Centers:Specialized breast imaging facilities concentrate radiologist expertise, alleviating interpretation bottlenecks that constrain tier-two and tier-three city deployment.
- Imaging Clinics:Pay-per-scan arrangements transfer utilization risk to equipment vendors, circumventing centralized capital budget constraints.
- Research Institutions:Photon-counting detector pilots and AI algorithm validation studies occur in Beijing and Shanghai academic medical centers.
Hospitals command the greatest equipment volume; Diagnostic Centers gain share through specialization economics.
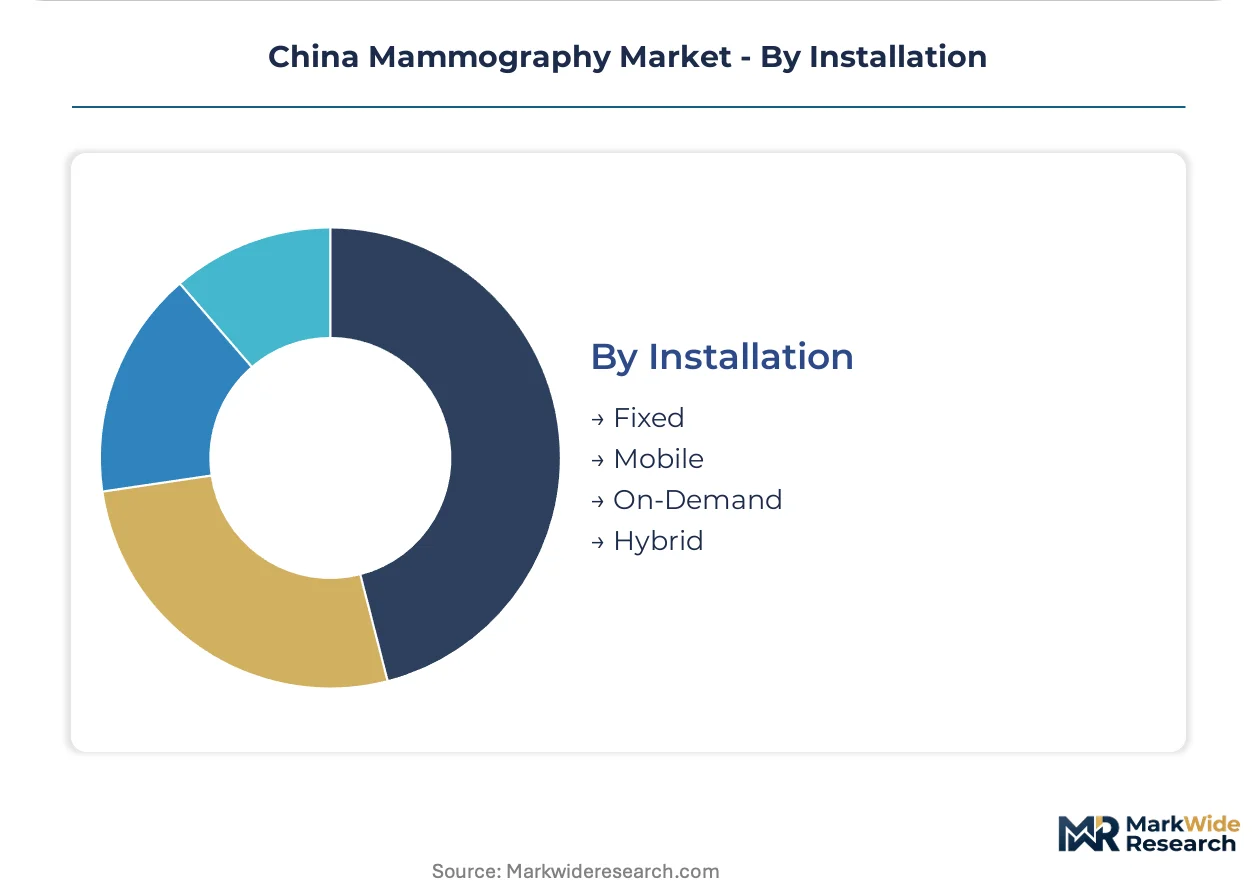
Installation:
Physical configuration determines deployment flexibility and reimbursement pathway complexity across China's screening infrastructure.
- Mobile:Screening vans equipped with portable systems reach rural counties lacking fixed imaging infrastructure. MEE dual carbon goals pressure manufacturers toward energy-efficient tube designs for vehicle-mounted deployment.
- Fixed:Permanent installations in hospital radiology departments maximize daily throughput and integrate with PACS networks for centralized image management.
- Hybrid:Systems supporting both stationary and transportable operation serve multi-site health systems optimizing asset utilization across facilities.
- On-Demand:Short-term leasing arrangements address temporary capacity surges without long-term capital commitment.
Fixed installations retain the largest footprint; Mobile configurations expand most quickly through rural screening networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's mammography equipment trade flows reflect concentrated import dependence for high-end detector components alongside expanding domestic production of full-field digital systems. Provincial procurement patterns diverge sharply between coastal technology clusters and interior county networks.
Shanghai
Municipal hospitals in Shanghai drive premium system procurement, leveraging direct NMPA registration pathways for digital breast tomosynthesis platforms. Siemens Healthineers maintains localized manufacturing operations here, supplying cost-competitive detectors to Yangtze River Delta health systems. Zhangjiang Hi-Tech Park anchors photon-counting detector pilot programs alongside AI algorithm validation studies.
Jiangsu
Tier-three municipal hospitals across Nanjing and Suzhou accelerate digital mammography deployment under national cancer prevention mandates. Provincial reimbursement frameworks favor full-field digital systems over 3D tomosynthesis outside oncology centers. Wuxi and Changzhou industrial corridors concentrate flat-panel detector component sourcing for domestic equipment assemblers.
Zhejiang
Hangzhou and Ningbo health systems pioneer pay-per-scan service contracts, transferring utilization risk from hospital balance sheets to equipment vendors. MEE dual carbon compliance pressures reshape tender evaluations toward energy-efficient tube designs. The province's medical device industrial parks supply amorphous selenium detectors to tier-two city networks.
Beijing
Academic medical centers in Beijing pilot photon-counting technology for high-risk patient stratification, supported by NMPA streamlined registration for innovative algorithms. The city's concentration of fellowship-trained breast imaging specialists alleviates interpretation bottlenecks constraining tier-three deployment. Zhongguancun software clusters develop AI-assisted detection modules awaiting regulatory pathway clarification.
Shandong
County-level hospitals across Jinan and Qingdao adopt portable mammography systems for mobile screening van networks serving rural populations. Equipment leasing structures circumvent centralized capital budget constraints prevalent in municipal procurement systems. The province's manufacturing base supplies vehicle-mounted X-ray tube assemblies compliant with GB electromagnetic compatibility standards.
China Mammography Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying detectors and tube assemblies to finished equipment manufacturers. The vendor base stratifies across three tiers: multinational imaging conglomerates with localized production, domestic vertically integrated producers, and specialized detector component fabricators. Market concentration remains moderate, with top-tier players competing through service infrastructure extension and managed service agreements rather than hardware differentiation alone. Strategic moves center on backward integration into detector manufacturing and pay-per-scan revenue model restructuring.
Among multinational imaging conglomerates, Siemens Healthineers and GE Healthcare occupy positions defined by service network density across tier-two and tier-three cities. United Imaging Healthcare exemplifies the domestic vertically integrated archetype, leveraging in-house detector production and direct hospital channel control. Fujifilm Holdings Corporation represents the diversified imaging specialist tier, drawing on optical and film heritage to position within digital transition markets. These three anchors illustrate competitive positioning pathways: service infrastructure depth, manufacturing integration, and technology transition leverage.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| Koninklijke Philips NV |
| GE Healthcare |
| Mindray Bio-Medical Electronics Co. |
| Canon Inc. |
| Siemens Healthineers AG |
| Carestream Health Inc. |
| United Imaging Healthcare Co. |
| Hologic Inc. |
| Others |
Value Chain & Pricing Dynamics
Rare-earth supply concentration for cesium iodide scintillator production creates dual exposure to input cost volatility and MEE dual carbon compliance costs, compressing margins in premium detector tiers while forcing tier-three hospitals toward leasing structures that offload procurement risk to vendors.
Pricing Analysis
Provincial hospital procurement committees anchor three-tier pricing stratification across premium, standard, and economy levels, with full-field digital systems commanding spreads based on detector resolution grade and NMPA registration tier. Siemens Healthineers and United Imaging Healthcare compete on after-sales bundling rather than hardware alone. Cost compression in economy tiers intensifies because domestic producers narrow performance gaps against imported platforms. County-level networks exhibit highest price sensitivity; top-tier oncology centers in Beijing and Shanghai demonstrate lowest sensitivity where reimbursement differentials absorb premium outlay.
Supply Chain Analysis
Contract manufacturing for flat-panel detector assemblies concentrates in Wuxi and Changzhou industrial corridors, with Shanghai-based Siemens Healthineers operations supplementing domestic capacity. Amorphous selenium substrate production draws from localized supply chains in Jiangsu and Zhejiang, while cesium iodide crystal growth rests on concentrated rare-earth processing facilities. Single-source vulnerability in scintillator raw material feeds from geopolitical concentration in rare-earth refining. Distribution runs through direct hospital channel control by United Imaging Healthcare and tier-two city service infrastructure extension by GE Healthcare.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated provincial procurement committees that aggregate demand across Yangtze River Delta hospital networks, fragmenting vendor pricing power while elevating service contract terms as competitive battlegrounds.
For Market Incumbents: Entrench position through backward integration into amorphous selenium detector manufacturing and captive service infrastructure in tier-three cities. Siemens Healthineers must deepen Shanghai manufacturing integration to offset rare-earth cost volatility. GE Healthcare should extend remote diagnostic capabilities to county-level networks before domestic competitors lock channel control. Threat from United Imaging Healthcare's vertical integration demands response through multi-year maintenance contract pre-emption. For New Entrants and Emerging Players: Portable system deployment for mobile screening vans in Anhui and Shandong counties represents the most penetrable entry point, given circumvented capital budget constraints and lower NMPA registration barriers versus premium 3D tomosynthesis. AI-assisted detection modules awaiting NMPA software-as-medical-device guidance offer regulatory arbitrage opportunity. Go-to-market angle should emphasize pay-per-scan arrangements that transfer utilization risk from hospital balance sheets. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors detector component specialists with NMPA-registered platforms and established hospital channel relationships. Long-term viability hinges on positioning upstream of equipment leasing model proliferation. Acquisition target archetype: domestic flat-panel detector fabricators with GB standards compliance and vertically integrated production. Signal to watch is NMPA clarification on AI module regulatory pathways, which will determine whether algorithmic tools require separate licensing or piggyback on hardware authorizations.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Streamlining | Accelerated approval pathways reduce time-to-market for digital mammography systems competing in provincial tenders. |
| Detector Manufacturing Integration | In-house amorphous selenium production insulates United Imaging Healthcare from rare-earth supply volatility and MEE compliance costs. |
| Service Infrastructure Extension | GE Healthcare's tier-two and tier-three city service networks capture recurring revenue beyond initial hardware sales. |
| Pay-per-Scan Contracting | Leasing structures transfer utilization risk to vendors, enabling county hospital access without centralized capital budget approval. |
| Photon-Counting Technology Pilot | Beijing and Shanghai oncology centers validate next-generation signal processing for high-risk patient stratification applications. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NMPA medical device registration databases, hospital procurement committee records, and GB standards documentation. Primary interviews engaged radiology department heads, biomedical engineers at tier-three municipal hospitals, GPO contracts managers, and flat-panel detector manufacturing executives. Secondary validation drew from MEE dual carbon policy filings, provincial health commission tender announcements, and equipment import customs records. Bottom-up installation volume estimates triangulate against top-down market sizing across the analysis window.
Forecast inputs incorporate product type segmentation across full-field digital, 3D tomosynthesis, and portable system categories; technology tiers spanning analog through photon-counting detection; end-user institution types from hospitals through imaging clinics; and installation configurations including mobile, fixed, hybrid, and on-demand deployment. CAGRs derive from regression analysis of historical procurement patterns against projected county-level network expansion under national cancer prevention mandates. Industry-specific inputs include NMPA registration timeline assumptions and reimbursement differential evolution across provincial health systems.
Macroeconomic conditions sit as an overlay; deviation in rare-earth commodity pricing, RMB exchange rate volatility, or provincial healthcare budget allocation would shift the trajectory. Forecasts reflect documented assumptions regarding NMPA regulatory pathway clarity and MEE dual carbon compliance timeline adherence. Quarterly review of provincial tender award volumes and NMPA software-as-medical-device guidance publication is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Korea Digital X-Ray Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
Spain Digital Radiology Market
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Diagnostic Imaging Markers Market
Medical Imaging
Asia-Pacific Nuclear Medicine Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
Germany Digital X-Ray Market
Medical Imaging
Global Magnetic Resonance Imaging System Market
Medical Imaging
Medical Holography Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Gallium-68 Market
Medical Imaging
Asia Pacific Computed Tomography (CT) Market