
 Portable Inverter Generators Market | 2026-2036
Portable Inverter Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Inverter Generators Market Analysis
The EPA's updated emission standards for small spark-ignition engines is shifting procurement priorities across the portable inverter generators market, compelling manufacturers to redesign combustion architectures and accelerate battery-hybrid development. Honda Motor Co., Ltd. leverages its four-stroke engine heritage to sustain premium positioning in gasoline segments while navigating electrification timelines. Generac Power Systems anchors its growth strategy through residential backup systems with integrated inverter technology and smart-load management. Champion Power Equipment competes aggressively on price-performance ratios in the recreational and emergency services channels, extending distribution through big-box retail partnerships.
Portable inverter generators convert mechanical energy into alternating current through high-frequency inversion stages, producing stable sine-wave output with total harmonic distortion below three percent for sensitive electronics and medical equipment. These units employ permanent magnet alternators coupled with microprocessor-controlled inverters to maintain voltage and frequency precision across variable load conditions. Gasoline configurations still dominate unit shipments across residential and recreational end users, though battery and solar segments attract the fastest-growing demand pools as lithium-ion energy densities improve and solar panel integration costs decline. Small and medium size classes, particularly 1000W to 2000W power ratings, concentrate margin pools due to their portability and alignment with outdoor recreation and home backup applications.
The EPA regulates exhaust emissions and noise output for portable generators sold in the United States, while California Air Resources Board imposes stricter state-level standards that effectively gate market access for non-compliant products. OSHA guidelines govern workplace deployment of portable power equipment, influencing commercial buyer specifications and fleet replacement cycles. Stakeholders must monitor evolving battery safety standards and inverter interoperability protocols as electrification reshapes competitive requirements and aftermarket service models.
Market Dynamics
The EPA's updated emission standards for small spark-ignition engines is forcing manufacturers to accelerate lithium-ion and solar-hybrid development while maintaining gasoline unit profitability through the transition window. This regulatory pressure compresses combustion R&D timelines and reallocates capital toward battery supply chain integration.
Growth Catalysts
- California Air Resources Board standards:Stricter state-level emission thresholds gate market access and redirect manufacturer investment toward compliant architectures, pulling forward electrification roadmaps for portable power equipment.
- Emergency services procurement:Disaster response agencies across the United States are expanding fleet purchases of battery-powered units for field deployment, creating institutional demand pools that validate emerging technology platforms.
- Lithium-ion energy density improvements:Advancing cell chemistry enables competitive runtimes in lighter form factors, opening recreational and residential backup segments previously dominated by gasoline configurations.
Market Restraints
- Battery raw material cost volatility:Lithium and cobalt price swings compress margin predictability for manufacturers scaling electrified product lines against established gasoline cost structures.
- Combustion engine supplier concentration:Specialized small-engine production clusters in specific Asian manufacturing regions create vulnerability to trade friction and logistics disruption.
- OSHA workplace deployment guidelines:Stringent commercial safety requirements extend certification timelines and limit immediate addressable market for new entrant battery platforms.
Strategic Opportunities
- Underpenetrated solar-hybrid recreational segment:Campsite and RV owners in western United States states present addressable demand for panel-integrated charging systems that reduce fuel logistics.
- Smart-load management convergence:Integration of inverter control with home energy management systems opens premium residential backup positioning beyond basic outage protection.
- Inflation Reduction Act residential incentives:Federal clean energy tax credits accelerate homeowner willingness to invest in battery backup infrastructure alongside solar installations.
Industry Challenges
- Inverter interoperability certification delays:Evolving IEEE standards for grid-tie functionality extend product validation cycles and fragment aftermarket service requirements.
- Power electronics engineering talent scarcity:Competition with electric vehicle and renewable energy sectors constrains hiring pipelines for specialized firmware and thermal management roles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Inverter Generators Market |
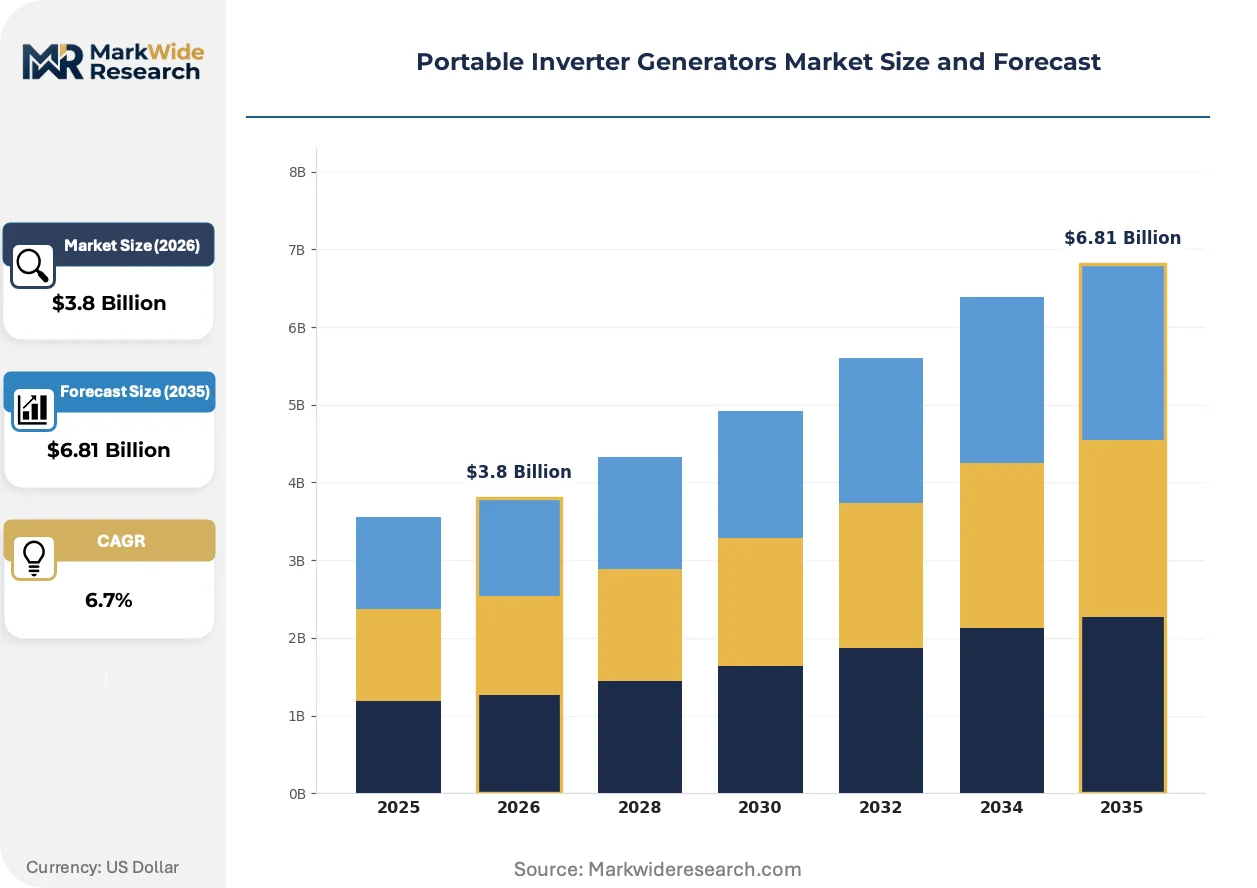
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, Gas, Diesel, Battery Size: Small, Medium, Large, Extra Large Power Rating: 500W, 1000W, 2000W, 3000W End User: Residential, Commercial, Recreational, Emergency Services |
| Companies Covered | Honda Motor Co., Ltd., Generac Power Systems, Yamaha Motor Co., Ltd., Cummins Inc., Briggs & Stratton, Champion Power Equipment, Westinghouse, Atlas Copco, Kohler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Inverter Generators Market Emerging Trajectories
Portable inverter generator architecture is bifurcating between refined combustion efficiency and full electrification, with hybrid interim configurations capturing transitional demand. Manufacturers must simultaneously optimize legacy platforms and build battery supply competencies.
Silicon carbide power semiconductors are expanding into inverter stage designs, enabling higher switching frequencies that reduce magnetic component size and improve conversion efficiency across variable load profiles. Marine and medical equipment buyers are adopting these configurations first due to strict harmonic distortion requirements. The technology is expanding into premium residential and commercial segments as cost curves improve.
EPA Tier 4 final emission standards for small spark-ignition engines are compelling manufacturers to deploy advanced aftertreatment systems or exit gasoline product categories entirely. Industrial consequence includes accelerated R&D reallocation toward battery platforms and supplier consolidation among compliant engine producers. California and northeastern United States markets are experiencing the most severe product line compression as state-level standards precede federal implementation.
Recreational buyers are consolidating purchase decisions around integrated ecosystem compatibility, prioritizing generators that interface with existing battery tool platforms and solar panel arrays. Big-box retail channels are responding with bundled merchandising that displaces standalone generator sales. This pattern concentrates most visibly in Pacific Coast metropolitan areas where outdoor recreation participation overlaps with clean energy preference demographics.
Portable Inverter Generators Market Segmentation
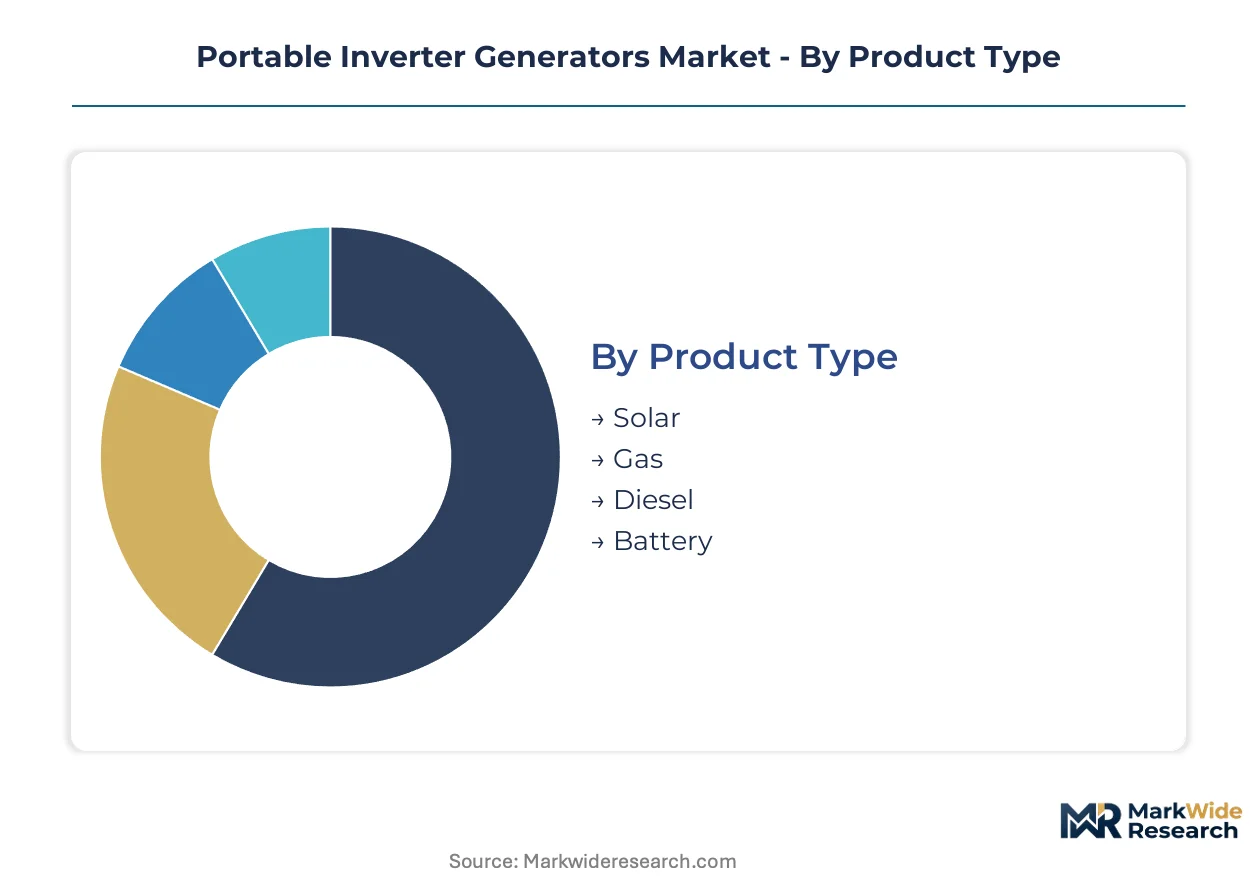
Portable inverter generators serve divergent use cases across emergency backup, outdoor recreation, and professional deployment, making granular segmentation essential for aligning power output, fuel architecture, and form factor with buyer requirements. Product type and power rating configurations determine margin structures and regulatory exposure, while end-user segmentation shapes distribution channel selection and service model design.
Product Type:
Technology architecture defines emissions compliance pathways and total cost of ownership trajectories across buyer segments.
- Gas:Four-stroke and two-stroke internal combustion engines dominate current installed base with mature supply chains and established service networks. CARB-compliant variants concentrate sales in California and northeastern states where state-level standards exceed federal EPA Tier 4 thresholds, though manufacturers face compressed R&D timelines to maintain gasoline platform viability.
- Battery:Lithium-ion cell packs with integrated battery management systems deliver silent operation and zero direct emissions, attracting fastest-growing demand from emergency services agencies and residential buyers seeking solar integration. OSHA workplace certification requirements and IEEE grid-tie interoperability standards currently limit immediate commercial addressability despite improving energy densities.
- Solar:Panel-integrated charging systems with MPPT controllers serve off-grid recreational deployments in western states with high insolation profiles.
- Diesel:Compression-ignition architectures persist in large-format industrial applications requiring extended runtime and fuel stability.
Most installed capacity flows through Gas configurations. Expansion is steepest in Battery architectures.
Size:
Physical footprint and transportability determine addressable use cases from backpack-portable units to skid-mounted industrial systems.
- Small:Units under 25 pounds with sub-2000W output target recreational buyers and residential light-load backup. Demand concentrates in Pacific Coast metropolitan areas where outdoor recreation participation overlaps with clean energy preference demographics, with big-box retail bundling alongside battery tool platforms displacing standalone sales.
- Medium:25-50 pound form factors with 2000-4000W capacity anchor home backup and small commercial applications. California wildfire-driven grid outages and state-level clean energy mandates reshape buyer preferences toward hybrid configurations in this weight class.
- Large:Wheel-mounted chassis with 4000-8000W output serve construction sites and mobile food service operations.
- Extra Large:Trailer-towed systems exceeding 8000W address industrial backup and remote infrastructure power requirements.
Revenue concentrates in Medium size classes. Volume expansion runs highest in Small form factors.
Power Rating:
Wattage specifications align with load profiles from personal electronics to whole-home backup, with inverter precision requirements varying by sensitivity of connected equipment.
- 2000W:The dominant residential and recreational rating balances runtime, portability, and load capacity for essential circuit backup and RV air conditioning. EPA emission standard updates and CARB thresholds are accelerating manufacturer migration toward lithium-ion alternatives in this rating band.
- 1000W:Compact units serve camping, tailgating, and medical device backup with sub-three-percent total harmonic distortion for sensitive electronics. Inflation Reduction Act residential incentives accelerate homeowner willingness to invest in battery backup infrastructure alongside solar installations.
- 500W:Pocket-sized units target personal electronics charging and drone operation in remote field conditions.
- 3000W:High-capacity inverters address whole-home backup and commercial equipment with soft-start motor loads.
Margin pools concentrate in 2000W ratings. Technology transition is advancing most quickly in 1000W segments.
End User:
Buyer category determines specification priorities, procurement channels, and replacement cycle timing.
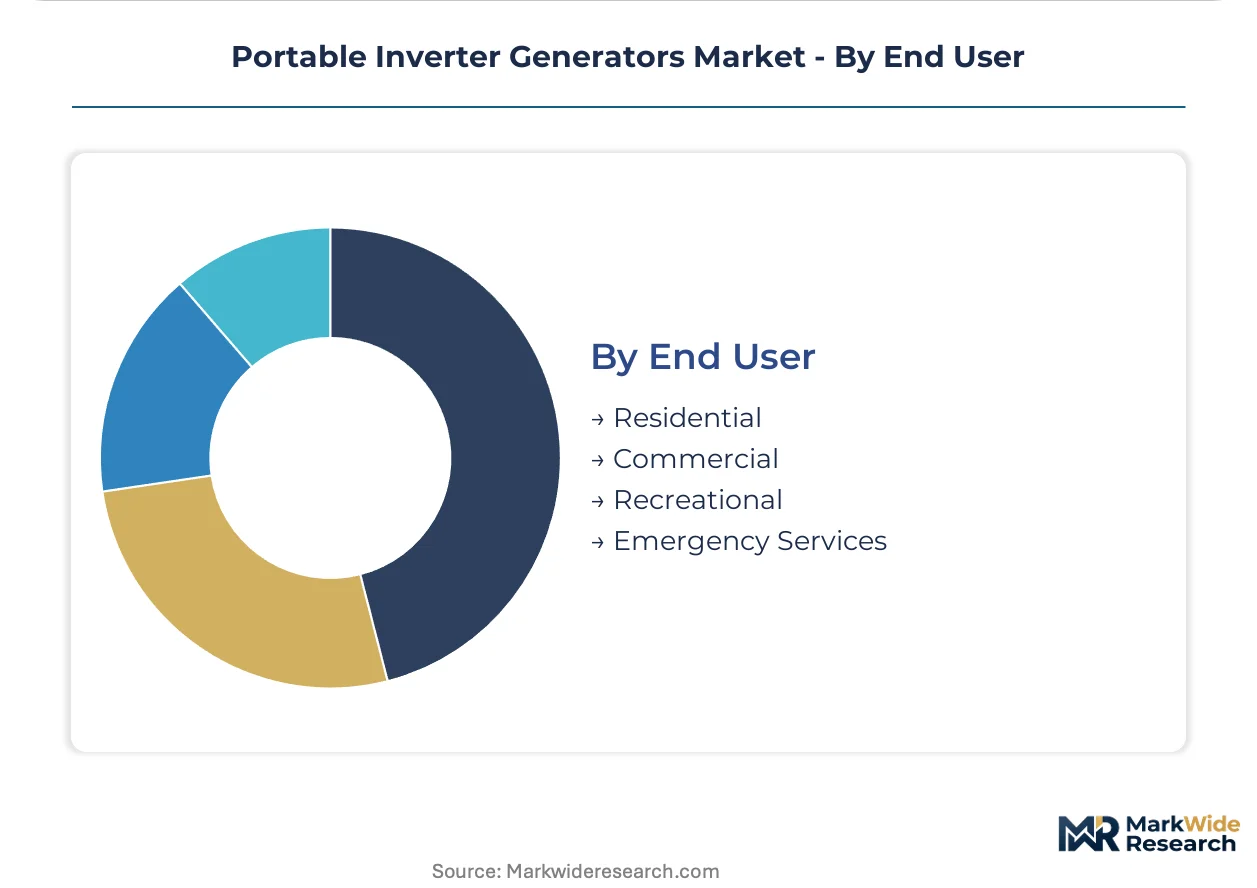
- Residential:Homeowners prioritize outage protection for essential circuits, with smart-load management integration opening premium positioning beyond basic backup functionality. California and northeastern markets experience most severe product line compression as state-level standards precede federal implementation.
- Emergency Services:Disaster response agencies across the United States are expanding fleet purchases of battery-powered units for field deployment, creating institutional demand pools that validate emerging technology platforms and establish performance benchmarks for commercial adoption.
- Recreational:Campsite and RV owners in western states present addressable demand for solar-hybrid panel-integrated charging systems that reduce fuel logistics and generator runtime.
- Commercial:Workplace deployment governed by OSHA guidelines extends certification timelines and influences fleet replacement cycles for construction, mobile service, and event production applications.
Procurement volume flows heaviest through Residential channels. Adoption curves are climbing fastest in Emergency Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portable inverter generator manufacturing scaled first in Japan through precision engine heritage, then consolidated production across East Asian industrial clusters before dispersing final assembly to regional demand centers. Regulatory divergence now shapes competitive geography more than labor arbitrage.
United States
California wildfire-driven grid outages and Texas winter storm resilience investments sustain replacement demand across residential and emergency services channels. EPA Tier 4 final emission standards and CARB thresholds compress gasoline platform viability while accelerating battery-hybrid procurement. Manufacturing concentrates in Wisconsin and South Carolina industrial corridors serving big-box retail distribution networks.
Japan
Precision inverter engineering heritage anchors premium export positioning, with domestic demand stabilizing around disaster preparedness mandates and aging grid infrastructure. METI carbon neutrality roadmaps redirect manufacturer R&D toward lithium-ion integration and hydrogen-compatible architectures. Industrial clusters in Hamamatsu and Tokyo Bay regions concentrate power electronics engineering talent and semiconductor component supply.
Germany
Construction sector equipment replacement cycles and residential solar-plus-storage adoption create dual demand streams for hybrid power systems. EU Green Deal emission benchmarks and national building energy codes accelerate displacement of pure combustion units in commercial deployment. Bavarian and Baden-Württemberg manufacturing zones host precision engineering suppliers serving inverter stage production.
China
Domestic outdoor recreation expansion and export manufacturing scale drive volume production across battery and gasoline configurations. MIIT new energy equipment standards and dual carbon policy targets compress timelines for electrified product line transitions. Pearl River Delta and Yangtze River Delta industrial corridors concentrate lithium-ion cell integration and power electronics assembly capacity.
Australia
Remote mining operations and bushfire-prone rural electrification sustain demand for ruggedized portable power across extreme climate conditions. National construction code amendments and state-level renewable energy targets reshape procurement specifications toward solar-hybrid compatibility. Queensland and Western Australia mining corridors represent concentrated addressable demand for large-format industrial units.
Portable Inverter Generators Market Vendor Landscape
Premium-margin players sit above commodity-margin players across inverter precision and emission compliance capabilities, with technology heritage determining pricing power. The vendor base stratifies between integrated power equipment conglomerates, specialized engine manufacturers, and emerging battery-platform entrants. Three archetypes dominate: heritage engine-to-inverter integrators, solar-battery ecosystem specialists, and industrial rental fleet suppliers. Competitive moves concentrate on battery supply chain partnerships and smart-load management software acquisition.
Within the heritage engine-to-inverter tier, Honda Motor Co., Ltd. and Yamaha Motor Co., Ltd. occupy positions shaped by four-stroke engineering lineage and precision manufacturing reputation. Generac Power Systems and Champion Power Equipment exemplify North American-focused residential and emergency services positioning. Cummins Inc. and Kohler represent industrial-scale power generation heritage extending into portable inverter segments through commercial channel leverage.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Generac Power Systems |
| Yamaha Motor Co., Ltd. |
| Cummins Inc. |
| Briggs & Stratton |
| Champion Power Equipment |
| Westinghouse |
| Atlas Copco |
| Kohler |
| Others |
Supply Flow & Price Mechanics
Lithium carbonate spot prices cascade through portable inverter generator manufacturing tiers, compressing margins on battery-hybrid configurations while gasoline units retain cost stability through established four-stroke engine supply contracts. This input cost divergence stratifies end-market pricing power across recreational buyers seeking sub-2000W portability and emergency services agencies prioritizing silent operation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates transaction patterns, with premium tiers capturing inverter precision certification and CARB compliance while economy tiers compete on per-watt output metrics. Price differentiation hinges on emission certification grade and smart-load management integration, with battery platforms experiencing cost compression from lithium supply volatility while gasoline units face margin tightening from Tier 4 aftertreatment requirements. Recreational buyers exhibit highest price sensitivity, whereas emergency services procurement prioritizes operational reliability over unit economics.
Supply Chain Analysis
Lithium-ion cell supply rests on Chinese, South Korean, and Japanese cathode and electrolyte producers, with silicon carbide semiconductor substrates drawing from Taiwanese and German wafer foundries. Small spark-ignition engine castings and permanent magnet alternators source from Vietnamese and Thai precision metalworking clusters. Single-source vulnerability concentrates in rare-earth magnet supply for inverter stage alternators. Distribution runs through big-box retail networks and specialized industrial equipment dealers serving regional contractor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable inverter generators function as a stable compounder, with climate-driven grid instability and emission regulatory tightening ensuring replacement cycle continuity across residential and institutional channels.
For Market Incumbents: Lock in battery supply partnerships through offtake agreements with Korean and Chinese cell producers before lithium demand competition intensifies from electric vehicle manufacturers. Secure CARB certification pathways for hybrid architectures to defend California market access against pure-play battery entrants. Prioritize inverter firmware talent acquisition from adjacent power electronics sectors experiencing hiring pressure. For New Entrants and Emerging Players: Capture the underpenetrated solar-hybrid recreational segment in western United States states where campsite electrification and RV boondocking demand outpaces incumbent product development timelines. Target emergency services battery procurement channels through modular form factors that interface with existing fleet logistics. Pursue direct-to-field deployment partnerships with disaster response agencies to validate performance benchmarks before commercial scale. For Investors and Strategic Acquirers: Asymmetric upside sits with battery-platform specialists possessing integrated battery management system IP and established UL safety certification, positioned to consolidate as gasoline incumbents face Tier 4 compliance cost structures. Five-to-ten year viability favors manufacturers with captive lithium supply arrangements and power electronics engineering depth. Watch EPA enforcement trajectory on small spark-ignition engines as inflection indicator for accelerated electrification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from Korean producers ahead of EV demand competition. |
| CARB Certification Investment | Unlocks California market access as state standards precede federal EPA Tier 4 implementation. |
| Smart-Load Management Integration | Enables premium residential positioning through home energy system interoperability. |
| Solar-Hybrid Product Launch | Addresses western state recreational demand for panel-integrated off-grid power. |
| Inverter Firmware Acquisition | Captures scarce power electronics engineering talent from competing renewable energy sectors. |
Methodological Framework
Direct dialogue with portable power equipment procurement officers at emergency services agencies, residential solar installers, big-box retail category managers, and aftermarket service technicians combined trade data validation and regulatory filing review. Secondary sources encompassed EPA emission standard documentation, CARB certification databases, EIA residential energy consumption surveys, and SEC filings from publicly traded power equipment manufacturers. Bottom-up unit shipment estimates triangulated against top-down energy demand modeling across the analysis window.
Bottom-up segmentation by fuel architecture, power rating tier, and end-user category fed into top-down macro demand elasticity assessment. CAGRs derived from replacement cycle analysis, regulatory phase-in schedules, and technology substitution curves. Forecast inputs included lithium-ion energy density improvement trajectories, wildfire-driven grid outage frequency patterns, and OSHA workplace deployment guideline evolution.
EPA enforcement discretion, lithium supply disruption events, and inverter interoperability standard finalization are the dominant revision risks to projection assumptions. Forecasts reflect documented assumptions subject to revision from these triggers. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
China Gas Generator Market
Generators
Wind Turbine Alternator Market
Generators
Heat Recovery System Generator Market
Generators
Military Generator Market
Generators
Telecom Generator Market
Generators
Reciprocating Power Generating Engine Market
Generators
India Portable Generator Market
Generators
North America Generator Sets Market
Generators
Nuclear Turbine Generators Market
Generators
Gulf Cooperation Council (GCC) Diesel Generator Market
Generators
Gasoline Gensets Market
Generators
Commercial Standby Generator Sets Market
Generators
Marine Gensets Market
Generators
Gasoline Generator Market
Generators
East Africa Diesel Generator Market
Generators
North America Gasoline Gensets Market