
 Telecom Generator Market | 2026-2036
Telecom Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Telecom Generator Market Intelligence
Data center power reliability is shifting from pure diesel backup toward hybrid configurations across developed telecom markets. Cummins leverages its integrated power systems division to anchor large-scale data center contracts in North America. Kohler-SDMO competes through specialized low-emission diesel units that sustain market presence in European tower fleets. Himoinsa differentiates with compact gas generator designs that occupy rooftop installation niches in urban Latin American networks.
A telecom generator is a dedicated stationary or portable power unit engineered to deliver continuous or emergency electrical supply for telecommunications infrastructure, typically operating at 50-60 Hz with voltage regulation within ±1% to protect sensitive switching equipment. Diesel generators retain dominant installed base across legacy tower portfolios, though hybrid generators incorporating battery storage and solar PV represent the fastest-expanding product category as operators target fuel cost reduction. The 10-50 kW power capacity band captures the highest volume in emerging market tower deployments, while above 250 kW units concentrate margin pools at hyperscale data center campuses.
EPA Tier 4 Final standards in the United States and EU Stage V emission regulations constrain conventional diesel generator deployments, accelerating manufacturer investment in gas and bi-fuel alternatives. India's Central Electricity Authority mandates dual-fuel compatibility for new telecom tower installations in designated air quality control regions. Stakeholders must monitor evolving carbon border adjustment mechanisms and local renewable energy mandates that will reshape generator specification requirements across major deployment geographies.
Market Dynamics
Hybrid power architectures are compressing diesel-only generator deployments across telecom infrastructure, as operators retrofit legacy towers with battery-solar integration to meet emission mandates and reduce fuel logistics costs.
Growth Catalysts
- EPA Tier 4 Final standards:United States emission limits are accelerating manufacturer R&D into bi-fuel and gas generator variants that maintain backup reliability while cutting particulate output.
- Rural Africa tower densification:Mobile network operators are expanding backup power installations across off-grid sites where grid extension remains economically unviable.
- Lithium-ion battery cost curves:Declining cell prices are enabling solar-hybrid system economics that were previously restricted to premium urban deployments.
Market Restraints
- Steel and copper volatility:Generator enclosures and winding materials face input cost swings that compress manufacturing margins and complicate long-term contract pricing.
- EU Stage V compliance costs:European emission regulations impose after-treatment hardware requirements that add 15-25% to diesel unit bill-of-materials.
- Grid extension programs:Rural electrification initiatives in India and Southeast Asia threaten addressable market for backup generator installations at tower sites.
Strategic Opportunities
- India CEA dual-fuel mandate:Central Electricity Authority regulations in designated air quality zones create mandatory retrofit demand for bi-fuel compatible units.
- Data center edge computing:Distributed compute nodes require sub-250 kW modular power systems that favor containerized gas generator configurations.
- Green hydrogen pilots:Electrolyzer-fuel cell integration trials at European telecom campuses are opening long-term substitution pathways for diesel backup.
Industry Challenges
- Hybrid system integration complexity:Battery management system synchronization with legacy diesel controls requires specialized commissioning expertise that remains scarce in emerging market service networks.
- Emission certification timelines:EPA and EU type-approval processes for new bi-fuel architectures extend product launch cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Telecom Generator Market |
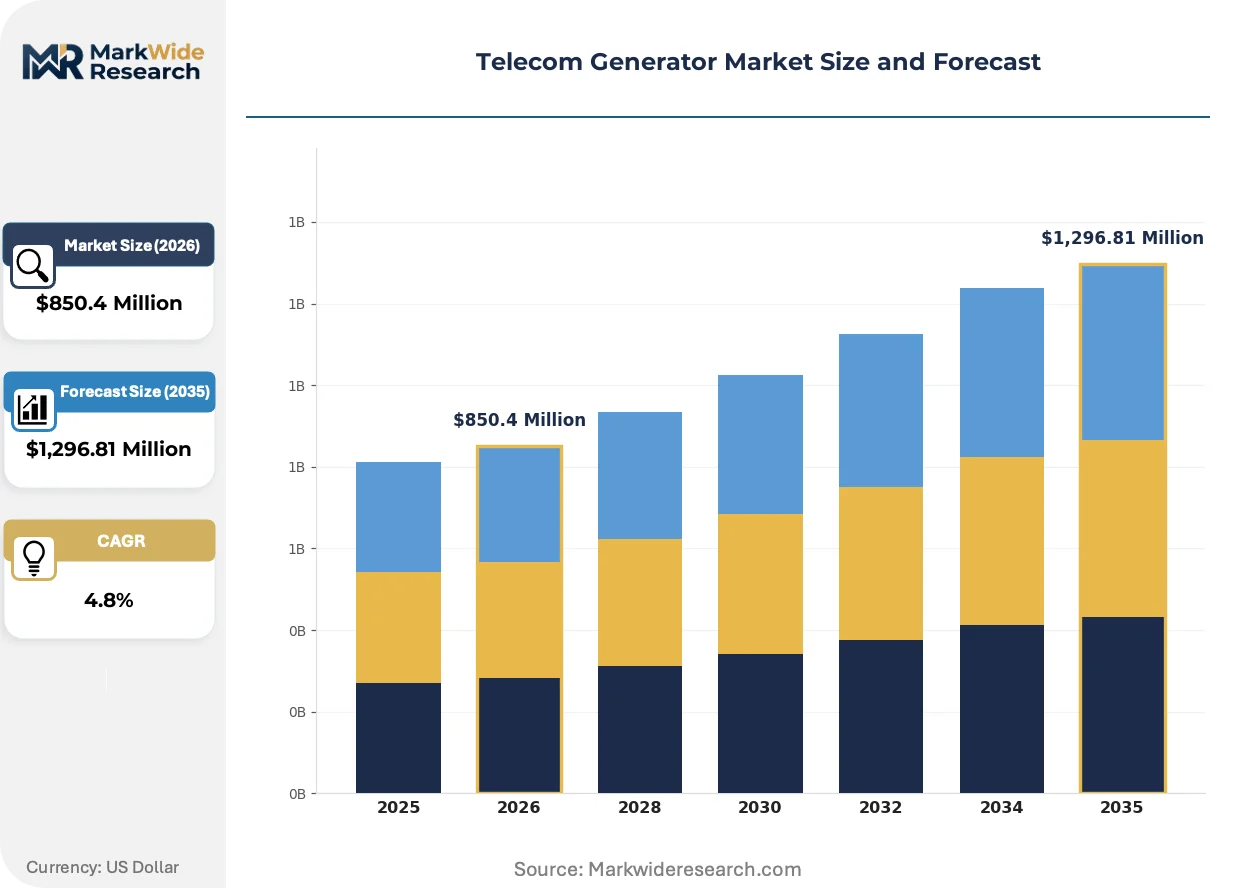
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,296.81 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diesel Generators, Gas Generators, Solar Generators, Hybrid Generators, Bi-Fuel Generators Power Capacity: Below 10 kW, 10-50 kW, 50-250 kW, Above 250 kW End User: Telecom Towers, Data Centers, Network Operations Centers, Mobile Switching Centers Installation Type: Rooftop, Ground Mounted, Indoor, Outdoor |
| Companies Covered | Aggreko, Kohler-SDMO, Cummins, Wärtsilä, Himoinsa, Caterpillar, Atlas Copco, FG Wilson, Generac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Telecom Generator Market Strategic Shifts & Innovations
Telecom power infrastructure is transitioning from standalone diesel backup toward intelligent multi-source systems that optimize fuel consumption through predictive load management and renewable integration.
Containerized battery-diesel hybrid units are rewriting capital deployment patterns for tower operators. These integrated systems combine lithium-ion storage with downsized prime movers to cut fuel consumption by 40-60% at rural African and Southeast Asian sites. Tower infrastructure companies in India are adopting these configurations fastest, compressing payback periods for solar-hybrid retrofits.
EU Stage V emission regulations are forcing diesel generator manufacturers to redesign exhaust after-treatment systems for European tower fleets. Selective catalytic reduction and diesel particulate filter integration adds cost and packaging constraints. Low-emission gas generator variants are capturing retrofit share in Germany, France, and the Netherlands where urban air quality restrictions are tightest.
Power purchase agreement structures are displacing capital purchase models for backup power at hyperscale data centers. Colocation operators in the United States and Ireland now procure generator capacity as bundled resiliency services rather than owning assets. This shifts operational risk to equipment providers and accelerates technology refresh cycles at campus deployments.
Telecom Generator Market Segmentation
Telecom generator procurement patterns diverge sharply across power architectures and deployment scales. Equipment specification requirements shift with grid reliability profiles, emission mandates, and fuel logistics constraints in each operating environment.
Product Type:
Upgrade cycles favor hybrid architectures over conventional diesel replacements as operators face tightening emission budgets and renewable integration targets.
- Diesel Generators:Compression-ignition prime movers with mechanical or electronic fuel injection systems dominate legacy installed bases across rural African and Southeast Asian tower portfolios. Demand concentrates in off-grid installations across Nigeria, Kenya, and Indonesia where fuel logistics networks remain mature and first-cost sensitivity blocks hybrid alternatives.
- Hybrid Generators:Integrated battery-diesel or battery-solar-diesel systems with intelligent load management controllers are displacing pure diesel at Indian tower sites under CEA dual-fuel mandates. Containerized configurations from Himoinsa and competitors compress installation timelines and reduce civil works requirements.
- Gas Generators:Spark-ignited natural gas or LPG units with stoichiometric or lean-burn combustion architectures serve urban European networks facing EU Stage V particulate limits.
- Bi-Fuel Generators:Dual-fuel diesel-gas systems with electronic ratio controllers enable compliance with India's air quality control region mandates while preserving diesel backup security.
- Solar Generators:PV-battery systems without fossil prime movers occupy niche applications at remote relay stations with predictable diurnal load profiles and sufficient solar resource.
Volume placements concentrate in diesel generators across legacy maintenance markets; the faster expansion belongs to hybrid generators as retrofit economics improve.
Power Capacity:
Cost tier segmentation separates commodity volume plays from engineered margin opportunities across the power spectrum.
- 10-50 kW:Single-phase or three-phase synchronous alternator sets with mechanical governing capture highest unit volumes in emerging market tower densification programs. Tower companies in India deploy this band extensively for macro-cell installations in rural Maharashtra and Uttar Pradesh where grid availability averages 8-12 hours daily.
- Above 250 kW:Medium-speed diesel or gas engines with permanent magnet alternators serve hyperscale data center campuses requiring N+1 or 2N redundancy configurations. Cummins and Kohler-SDMO concentrate engineering resources here for North American and Irish colocation contracts.
- Below 10 kW:Portable or skid-mounted sets with air-cooled engines address micro-cell and temporary coverage requirements.
- 50-250 kW:Industrial diesel or gas units with electronic governing and remote monitoring capabilities serve regional data centers and large switching facilities.
Unit economics favor the 10-50 kW band for volume manufacturing scale; margin pools deepen fastest above 250 kW where specification engineering and service bundling differentiate suppliers.
End User:
Application-specific duty cycles and redundancy requirements reshape generator sizing and fuel strategy across infrastructure types.
- Telecom Towers:Standby or prime-rated sets with extended tank autonomy address grid instability across sub-Saharan Africa and South Asia. Tower infrastructure companies in India retrofit diesel units with bi-fuel kits to meet CEA mandates in Delhi-NCR and Mumbai air quality zones.
- Data Centers:Tier III/IV uptime requirements drive redundant generator configurations with 10-15 minute battery bridging and automatic transfer switching. Colocation operators in Virginia, Texas, and Frankfurt specify containerized gas units for emission compliance.
- Network Operations Centers:Continuous-duty rated sets with 99.999% availability targets serve centralized monitoring facilities.
- Mobile Switching Centers:Medium-capacity standby systems with rapid start requirements protect core network signaling infrastructure.
Deployment volume clusters at telecom towers for geographic expansion; specification intensity climbs fastest at data centers where uptime contracts govern equipment selection.
Installation Type:
Physical mounting constraints filter product form factors and acoustic treatment requirements across deployment contexts.
- Outdoor:Weatherproof enclosures with IP54+ ratings and integral fuel tanks dominate rural tower installations across all climate zones. Ground-mounted configurations in India and Nigeria accommodate larger tank volumes for extended autonomy.
- Rooftop:Compact gas generator packages with low-vibration mounting and reduced footprint serve urban Latin American networks where ground space is unavailable. Himoinsa specializes in this configuration for Mexico City and São Paulo deployments.
- Indoor:Acoustically treated packages with ventilation and exhaust ducting serve urban switching centers and legacy central office buildings.
- Ground Mounted:Standard skid or trailer configurations with weather protection for temperate climate data center campuses.
Outdoor placements dominate emerging market volume; rooftop specifications expand fastest in dense urban environments where real estate constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and designated air quality control regions concentrate hybrid generator deployments through regulatory mandates and tax incentives for clean technology adoption.
United States
Hyperscale data center construction in Northern Virginia and Texas drives demand for above-250 kW gas generator configurations. EPA Tier 4 Final emission standards force after-treatment integration that adds cost but opens bi-fuel retrofit opportunities. Dallas-Fort Worth and Phoenix campus clusters anchor Cummins and Kohler-SDMO contract activity.
India
Tower infrastructure companies retrofit diesel units with bi-fuel kits across Maharashtra and Uttar Pradesh to comply with Central Electricity Authority mandates. The Delhi-NCR air quality control region enforces dual-fuel compatibility for new installations. Mumbai and Bangalore urban networks accelerate solar-hybrid adoption through containerized battery-diesel systems.
Germany
EU Stage V regulations constrain diesel generator deployments across urban tower fleets in North Rhine-Westphalia and Bavaria. Selective catalytic reduction requirements push operators toward low-emission gas variants. Frankfurt data center campuses specify containerized natural gas units for emission compliance in colocation contracts.
Nigeria
Mobile network operators expand backup power installations across Lagos and Kano where grid availability averages 4-6 hours daily. Diesel logistics networks remain mature despite hybrid system pilots. Tower companies deploy 10-50 kW units extensively for macro-cell densification in off-grid corridors.
Brazil
Rooftop installation constraints in São Paulo and Mexico City favor compact gas generator packages with reduced footprint and vibration isolation. Urban real estate scarcity intensifies specification requirements for Latin American network operators. Himoinsa specializes in this configuration for dense metropolitan deployments.
Telecom Generator Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated power systems divisions capturing premium data center contracts while regional fabricators serve price-sensitive tower markets. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive generator divisions, pure-play power equipment specialists, and regional assembly houses serving emerging market price points. Consolidation pressure intensifies through strategic partnerships between battery integrators and engine manufacturers, plus geographic expansion into African and Southeast Asian tower markets.
Within the diversified industrial tier, Cummins and Caterpillar anchor North American hyperscale data center procurement through integrated power systems capabilities. Kohler-SDMO occupies a position among European specialists targeting EU Stage V compliance through low-emission diesel architectures. Himoinsa represents the compact gas generator archetype for urban Latin American rooftop constraints.
| Leading Market Players |
|---|
| Aggreko |
| Kohler-SDMO |
| Cummins |
| Wärtsilä |
| Himoinsa |
| Caterpillar |
| Atlas Copco |
| FG Wilson |
| Generac |
| Others |
Cost & Logistics Intelligence
Hyperscale data center operators in Northern Virginia and Texas anchor procurement volume and negotiate multi-year service contracts that compress spot-market premiums for backup generator capacity. This buyer concentration shifts pricing power toward equipment bundling and away from unit transactional models.
Pricing Analysis
Short lead-time premiums dominate pricing differentiation for EPA Tier 4 Final and EU Stage V compliant units, where certification backlogs stretch manufacturer capacity. Three-tier pricing structure across premium, standard, and economy levels separates containerized hybrid systems with full commissioning from skid-mounted diesel sets with basic enclosures. Pricing pressure stems from steel and copper input volatility that compresses manufacturing margins. Tower operators in India and Nigeria exhibit highest price sensitivity, while hyperscale data center procurement teams prioritize uptime guarantees over unit cost.
Supply Chain Analysis
EPA and EU type-approval certifications gate supplier entry, forcing regional fabricators to partner with established engine manufacturers for compliant architectures. Diesel engine block casting concentrates in China, India, and the United States, while alternator winding copper draws from Chilean and Indonesian smelter output. Single-source vulnerability in semiconductor-based engine control modules creates procurement risk for electronic governing systems. Distribution runs through tower infrastructure company framework agreements in emerging markets and direct OEM contracts for data center campus deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as emission certification costs and hybrid system R&D investments force weaker regional assemblers toward strategic exits or partnership absorption.
For Market Incumbents: Cement market position through captive alternator winding capabilities that insulate margin structures from copper volatility. Secure EPA and EU type-approval pipelines for bi-fuel architectures before regulatory timelines compress competitive windows. Defensive consolidation into battery management system expertise addresses hybrid integration complexity that threatens aftermarket service revenue. For New Entrants and Emerging Players: Direct-to-tower-operator digital sales channels bypass incumbent distributor networks that dominate African and Southeast Asian markets. Target rooftop gas generator niches in São Paulo and Mexico City where real estate constraints favor compact footprints over established diesel configurations. White-space opportunity concentrates in containerized solar-hybrid retrofits for Indian CEA mandate compliance. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with EPA Tier 4 Final certification pipelines and existing African service networks. Long-term viability hinges on gas generator and hybrid system portfolios that displace pure diesel exposure. Watch EU carbon border adjustment mechanism expansion as the inflection signal for accelerated bi-fuel adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid System Certification Pipeline | EPA Tier 4 Final and EU Stage V approvals compress competitive timelines for new entrants. |
| Backward Integration into Alternator Manufacturing | Copper winding capacity insulates margin structures from commodity volatility in generator production. |
| Battery Management System Acquisition | Hybrid integration complexity creates service revenue pools beyond hardware margins. |
| African Service Network Expansion | Rural tower densification demands localized commissioning expertise for solar-hybrid deployments. |
| Gas Generator Platform Development | Urban air quality mandates in EU and India displace diesel-only architectures. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with tower infrastructure procurement directors, data center facility managers, generator OEM product planners, and EPC contractors active in African markets validated demand assumptions. EPA certification databases, EU Stage V type-approval registries, and Indian CEA mandate notifications provided regulatory constraint parameters. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows from mobile network operator capex disclosures.
Segment-level granularity modeled power capacity tiers, fuel architecture types, and installation configurations across the projection horizon. CAGRs derived from regression analysis of historical deployment patterns against regulatory phase-in schedules and fuel cost trajectories. Lithium-ion battery cost curves and diesel logistics network maturity served as industry-specific forecast inputs for hybrid system adoption rates.
The model holds under stable emission regulatory phase-in timelines; deviation in carbon border adjustment mechanism coverage or battery cell supply disruptions would shift hybrid system payback calculations. Forecasts reflect assumptions regarding grid extension program pacing in India and Southeast Asia. A model refresh is warranted upon material change in EU Stage V enforcement stringency or Indian CEA mandate geographic expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Wind Turbine Alternator Market
Generators
Dual-Fuel Generator Market
Generators
Generator Rental Market
Generators
Wind Power Generators Market
Generators
Residential Gas Generator Market
Generators
Global Portable Generator Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Railway Generators Market
Generators
North West Europe Diesel Generator Market
Generators
Electric Generators Market
Generators
North America Diesel Generator Market
Generators
Gas Generator Market
Generators
US Generator Sales Market
Generators
Silent Generator Market
Generators
Marine Gensets Market
Generators
Southeast Asia Portable Generator Market