
 Generator Belt Market | 2026-2036
Generator Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Generator Belt Market Analysis
Southeast Asian rubber processing capacity is rebalancing after plantation yield disruptions shifted compound sourcing toward synthetic alternatives. Gates Corporation leverages backward integration into EPDM compound development to secure formulation consistency across climate zones. Continental AG sustains dual manufacturing footprints in Europe and Mexico to service just-in-time automotive assembly schedules. Mitsuboshi Belting Ltd. anchors its position through JIS-certified timing belt production for Japanese OEM transplant factories.
A generator belt is a power transmission component manufactured from rubber-EPDM compounds reinforced with polyester or aramid cord layers, engineered to transfer rotational force from engine crankshafts to alternators, cooling pumps, and auxiliary systems while maintaining precise tension across temperature ranges from minus forty to one hundred twenty degrees Celsius. Poly-V belt configurations dominate automotive alternator drives due to their high friction coefficient and compact pulley engagement, while timing belt segments command premium positioning through exacting tooth profile tolerances that prevent valve train interference. Ribbed belts occupy the replacement channel volume tier where price sensitivity favors standardized constructions over OEM-specified multi-rib geometries.
EPA emission certification protocols and EU F-Gas Regulation accessory efficiency mandates are forcing belt redesigns toward reduced rolling resistance compounds that lower engine parasitic loads. China's MIIT fuel consumption standards and NMPA component certification requirements create parallel compliance pathways for suppliers seeking domestic OEM qualification. NHTSA defect investigation procedures and recall authority shape aftermarket liability exposure for belt failure modes. Stakeholders must monitor evolving electrification architectures where integrated starter-generator units may eliminate mechanical accessory drives entirely.
Market Dynamics
Hybrid drivetrain proliferation is fragmenting generator belt specifications as automotive OEMs demand compound formulations tolerant of stop-start thermal cycling and integrated starter-generator torque profiles.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Tightening accessory load requirements are mandating reduced rolling resistance belt compounds that lower engine parasitic losses. Automotive OEM procurement teams are expanding qualification protocols for hybrid-compatible constructions.
- EPDM compound development:Backward integration into synthetic rubber formulation is securing batch consistency across climate zones from minus forty to one hundred twenty degrees Celsius. Compound suppliers are certifying multi-rib geometries for extreme temperature durability.
- China MIIT fuel consumption standards:Domestic OEM qualification pathways are accelerating belt redesign cycles for suppliers seeking NMPA component certification. Engine manufacturing clusters in Shanghai and Guangzhou are concentrating sourcing decisions.
Market Restraints
- Natural rubber yield volatility:Southeast Asian plantation disruptions are forcing compound reformulation toward synthetic alternatives at elevated input costs. EPDM feedstock price swings are compressing margin buffers for non-integrated manufacturers.
- Integrated starter-generator displacement:Beltless accessory drive architectures in full-hybrid and battery-electric platforms are eliminating mechanical power transmission components entirely. Electrification roadmaps threaten long-term category relevance.
- EU F-Gas Regulation compliance friction:Accessory efficiency mandates are requiring expensive compound testing and certification cycles that extend OEM qualification timelines. Smaller compounders lack capital for parallel regulatory pathways.
Strategic Opportunities
- Aftermarket channel digitization:E-commerce platforms are disintermediating traditional wholesale distribution for ribbed belt replacement volume. Independent repair networks in Germany and the United States are consolidating procurement through specialized vertical marketplaces.
- JIS-certified timing belt white space:Japanese OEM transplant factories in Mexico and the southeastern United States require localized supply for exacting tooth profile tolerances. Certified producers can capture premium positioning through transplant supply agreements.
- Aramid cord-polyester hybrid reinforcement:Convergence of high-strength synthetic fibers with traditional cord constructions is enabling lighter belt designs for downsized turbocharged engines. Material suppliers are qualifying hybrid layup configurations for OEM specification.
Industry Challenges
- Compound formulation expertise scarcity:EPDM-synthetic rubber blending and climate-zone durability testing require specialized polymer chemists that belt manufacturers struggle to recruit. Technical talent pipelines are thinning as materials science graduates pivot toward battery chemistry.
- OEM qualification timeline compression:Simultaneous EPA, EU F-Gas, and China MIIT certification requirements are stretching engineering resources across incompatible testing protocols. Parallel regulatory submissions are delaying program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generator Belt Market |
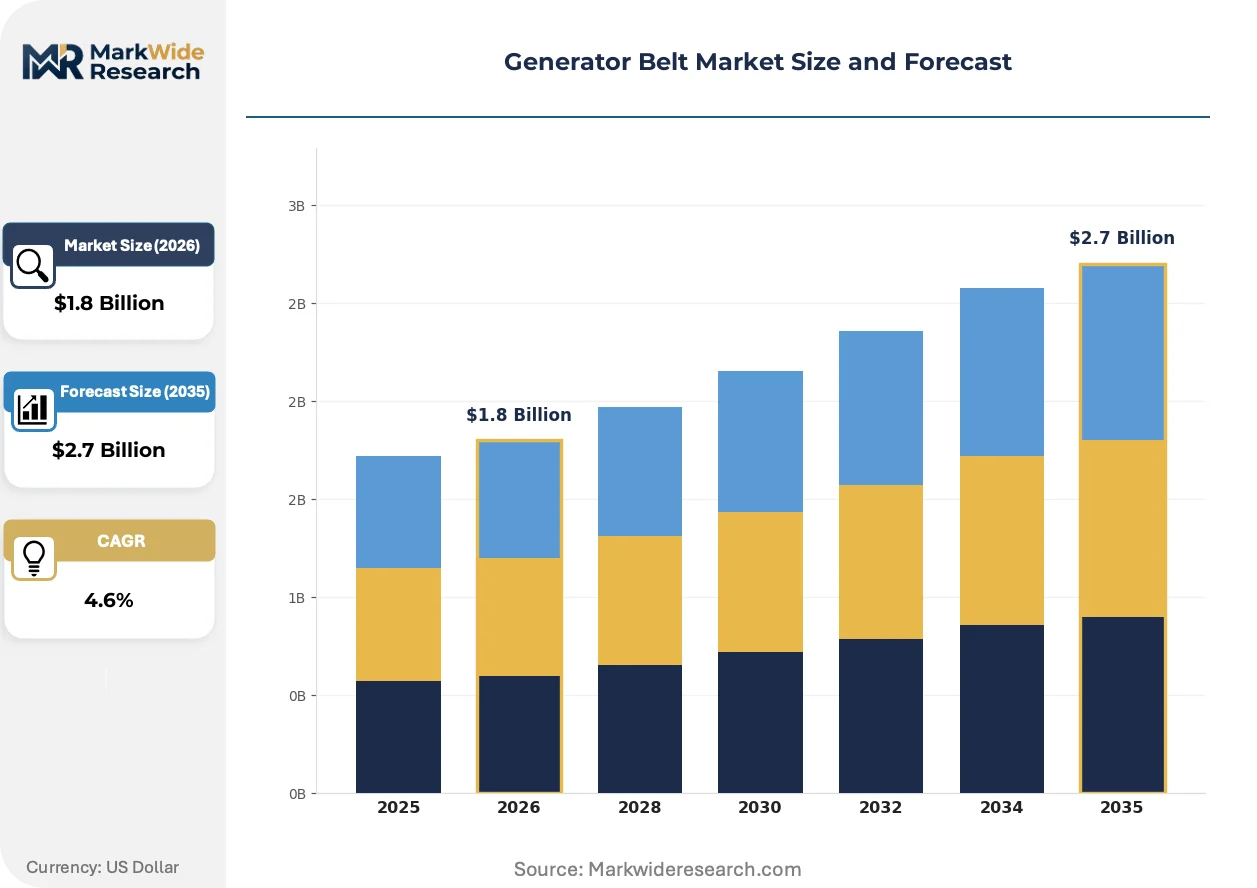
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poly-V Belt, Timing Belt, Ribbed Belt, Flat Belt Material: Rubber, Polyester, Nylon, Steel End User: Automotive, Industrial, Marine, Construction Distribution Channel: Online, Retail, Wholesaler, Direct Sales |
| Companies Covered | Gates Corporation, Bando USA, Tsubakimoto Chain Co., Hutchinson, Continental AG, Mitsuboshi Belting Ltd., Dayco Corporate, Schaeffler Group, Optibelt GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generator Belt Market Emerging Trajectories
Material science breakthroughs and regulatory efficiency mandates are converging to redefine compound specifications, manufacturing processes, and procurement patterns across automotive power transmission systems.
Aramid fiber reinforcement is electrifying belt construction by replacing conventional polyester cord in high-load alternator applications. Tier 1 suppliers are adopting hybrid aramid-polyester layups for downsized turbocharged engines operating at elevated thermal stress. The technology is electrifying competitive positioning as compounders with captive fiber integration capture specification authority from generic belt assemblers.
EU F-Gas Regulation accessory efficiency mandates are forcing reformulation of EPDM compounds toward reduced hysteresis and lower rolling resistance coefficients. Belt manufacturers are redesigning multi-rib geometries to minimize energy loss across pulley engagement surfaces. The regulation is compressing qualification timelines most severely for European OEM supply chains, where just-in-time assembly schedules leave minimal buffer for compound revalidation.
Automotive OEM procurement teams are consolidating supplier panels around compounders with backward integration into EPDM development and climate-zone testing infrastructure. Tier 2 belt assemblers without captive compound supply are losing specification influence to integrated manufacturers. This concentration is most visible in German and US Midwest engine manufacturing clusters, where OEM technical audits now prioritize formulation consistency over unit pricing.
Generator Belt Market Segmentation
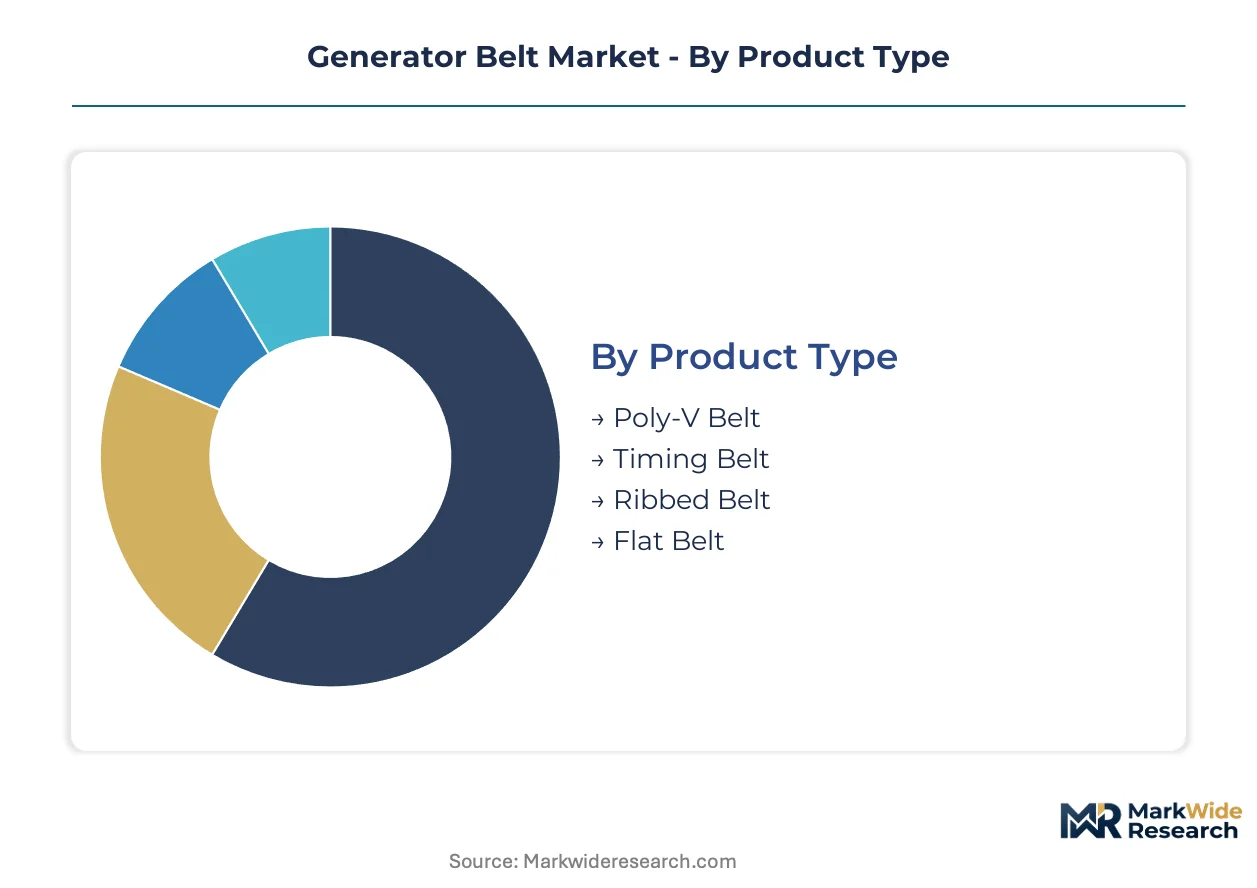
Generator belt procurement patterns diverge sharply across technical specifications, material compositions, and channel structures. OEM qualification protocols and aftermarket replacement cycles create distinct margin profiles that suppliers must navigate simultaneously.
Product Type:
Supply concentration in German and US Midwest engine manufacturing clusters favors belt configurations optimized for just-in-time automotive assembly schedules.
- Poly-V Belt:Multi-ribbed constructions with high friction coefficients dominate alternator drives in downsized turbocharged engines. Demand concentrates in automotive OEM channels where EPA fuel economy standards mandate reduced parasitic loads.
- Timing Belt:Exacting tooth profile tolerances prevent valve train interference in interference engines. Japanese transplant factories in Mexico and the southeastern United States anchor premium sourcing for JIS-certified constructions.
- Ribbed Belt:Standardized multi-rib geometries serve price-sensitive aftermarket replacement volume.
- Flat Belt:Legacy industrial applications retain niche demand outside automotive power transmission.
Today's leader: Poly-V Belt. Tomorrow's challenger: Timing Belt.
Material:
Compound formulation expertise scarcity is reshaping competitive positioning as integrated manufacturers capture specification authority from generic assemblers.
- Rubber:EPDM-synthetic blends dominate automotive specifications for temperature durability across minus forty to one hundred twenty degrees Celsius. Gates Corporation's backward integration into compound development secures batch consistency for climate-zone certification.
- Polyester:Traditional cord reinforcement maintains cost competitiveness in high-volume ribbed belt production for aftermarket channels.
- Nylon:Emerging hybrid layup configurations target lighter belt designs for hybrid drivetrain stop-start thermal cycling.
- Steel:Heavy-duty industrial applications retain limited penetration outside marine and construction equipment.
EPDM rubber formulations anchor current procurement. Aramid-polyester hybrid reinforcement is climbing the fastest as OEMs specify lighter constructions.
End User:
Application-specific durability requirements fragment demand across divergent operating environments and regulatory compliance pathways.
- Automotive:Integrated starter-generator displacement in full-hybrid platforms threatens long-term mechanical accessory drive relevance. China MIIT fuel consumption standards and EPA certification protocols dominate qualification cycles.
- Industrial:Continuous-duty operating profiles favor heavy-duty constructions with extended service intervals. EU F-Gas Regulation efficiency mandates force compound reformulation toward reduced hysteresis.
- Marine:Corrosion-resistant specifications for saltwater environments command premium positioning.
- Construction:Severe-duty thermal stress in equipment applications requires reinforced cord constructions.
Automotive volume dominates present sourcing. Industrial aftermarket replacement is gaining share fastest as fleet maintenance intervals compress.
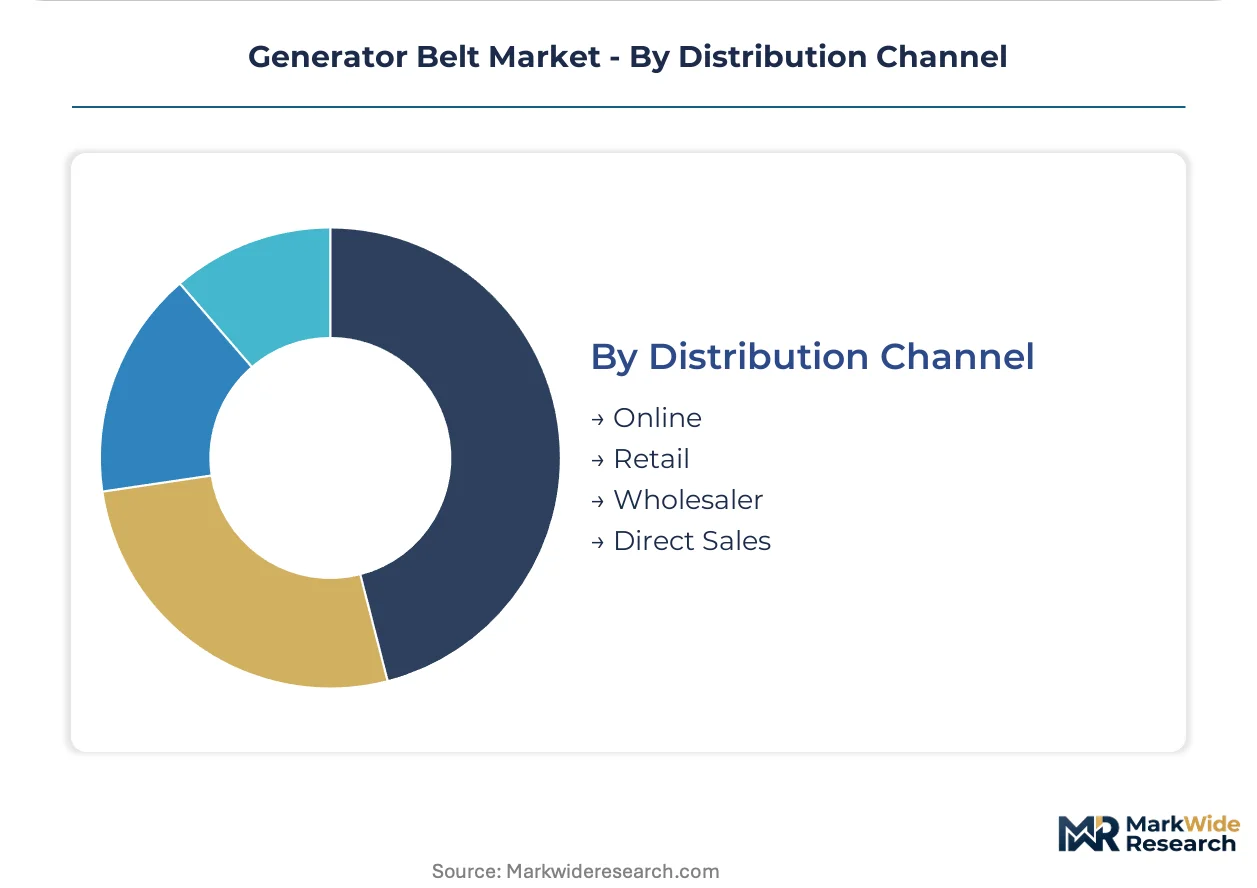
Distribution Channel:
Channel digitization is disintermediating traditional wholesale structures for standardized replacement volume.
- Online:E-commerce platforms consolidate independent repair network procurement in Germany and the United States. Vertical marketplaces disintermediate traditional wholesale markups for ribbed belt specifications.
- Retail:Counter sales serve emergency replacement demand with immediate availability premiums.
- Wholesaler:Traditional distribution retains lock on OEM-specified multi-rib geometries requiring technical support.
- Direct Sales:Tier 1 suppliers maintain dedicated account management for transplant factory just-in-time schedules.
Wholesale lock on OEM specifications holds today. Online channel expansion represents the steepest trajectory for aftermarket volume migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing generator belt manufacturing capacity as suppliers seek cost-of-compliance advantages across divergent certification regimes. Compound formulation expertise scarcity accelerates migration toward jurisdictions with established polymer chemistry infrastructure.
United States
EPA Corporate Average Fuel Economy standards tighten accessory load requirements for alternator drive systems. NHTSA defect investigation procedures shape aftermarket liability exposure for belt failure modes. Detroit and Midwest engine manufacturing clusters concentrate OEM procurement decisions around just-in-time assembly schedules.
Germany
EU F-Gas Regulation accessory efficiency mandates force EPDM compound reformulation toward reduced hysteresis coefficients. KBA type-approval protocols extend qualification timelines for multi-rib geometries. Stuttgart and Munich automotive engineering centers anchor Continental AG's dual manufacturing footprint for European OEM supply.
China
MIIT fuel consumption standards accelerate belt redesign cycles for domestic OEM qualification. NMPA component certification requirements create parallel compliance pathways for suppliers. Shanghai and Guangzhou engine manufacturing clusters dominate sourcing decisions for regional automotive production.
Japan
METI energy efficiency guidelines drive specification authority toward integrated compounders with climate-zone testing infrastructure. JIS-certified timing belt production anchors Mitsuboshi Belting Ltd.'s position for transplant factory supply. Nagoya and Osaka industrial corridors concentrate precision rubber processing capacity.
Mexico
Japanese OEM transplant factories in central Mexico require localized supply for exacting tooth profile tolerances. NAFTA-origin content rules influence procurement patterns for US-bound automotive exports. Querétaro and Guanajuato manufacturing corridors attract belt assembly operations serving North American just-in-time networks.
Generator Belt Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid drivetrain compatibility specializations. The vendor base stratifies around three structural positions: integrated compounders with backward EPDM development, certified timing belt specialists, and price-driven aftermarket assemblers. Two dominant competitive moves reshape positioning: geographic expansion through transplant factory proximity, and portfolio diversification into aramid-polyester hybrid reinforcement systems.
Among integrated compounders, Gates Corporation exemplifies the backward-integrated archetype through captive EPDM formulation control. Continental AG occupies a position within the dual-footprint tier, while Mitsuboshi Belting Ltd. represents the JIS-certified specialist segment. These three anchors illustrate how specification authority concentrates around manufacturers with climate-zone testing infrastructure and regulatory certification depth.
| Leading Market Players |
|---|
| Gates Corporation |
| Bando USA |
| Tsubakimoto Chain Co. |
| Hutchinson |
| Continental AG |
| Mitsuboshi Belting Ltd. |
| Dayco Corporate |
| Schaeffler Group |
| Optibelt GmbH |
| Others |
Supply Flow & Price Mechanics
EPDM synthetic rubber feedstock price volatility cascades through compound formulation tiers into three distinct pricing bands: OEM-specified multi-rib geometries commanding premium positioning, JIS-certified timing belts occupying mid-tier value, and standardized ribbed constructions competing on replacement-channel cost.
Pricing Analysis
Distributor margin layers absorb the steepest compression as e-commerce platforms disintermediate traditional wholesale markups for aftermarket volume. Three-tier pricing structure across premium, standard, and economy levels separates OEM-qualified compound formulations from generic aftermarket assemblies from unbranded import alternatives. Cost compression in the economy tier is intensifying because Southeast Asian synthetic rubber sourcing faces plantation yield disruptions. Fleet maintenance managers exhibit highest price sensitivity, while OEM procurement teams prioritize batch consistency over unit cost.
Supply Chain Analysis
NAFTA-origin content rules and China's NMPA domestic-content mandates are reshaping sourcing toward regional compound development facilities. Manufacturing gravity centers on Germany, China, and Mexico, with EPDM feedstock, aramid fiber, and polyester cord anchoring material dependencies. Single-source vulnerability concentrates in climate-zone testing infrastructure, where qualified polymer chemists remain scarce. Distribution runs through Tier 1 direct account management for transplant factories, with aftermarket volume migrating toward specialized vertical marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generator belt procurement functions as a stable compounder, with EPA and EU regulatory tightening ensuring steady specification upgrade cycles regardless of automotive production cyclicality.
For Market Incumbents: Extend backward integration into EPDM compound development to defend against Gates Corporation's formulation consistency advantage. Secure captive climate-zone testing infrastructure before talent scarcity worsens, as materials science graduates pivot toward battery chemistry. Anchor OEM panel consolidation by qualifying hybrid aramid-polyester constructions for downsized turbocharged engine specifications. For New Entrants and Emerging Players: The price-point gap between JIS-certified timing belt premiums and generic ribbed belt economy tiers offers white-space entry through certified aftermarket specialization. Target Mexican transplant factory supply corridors where localized tooth profile tolerance production remains undersupplied. Pursue vertical marketplace partnerships with German and US independent repair networks to bypass traditional wholesale lock. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated compounders possessing captive EPDM formulation and climate-zone certification depth. Long-term viability hinges on hybrid drivetrain transition pacing, with beltless accessory drive architectures threatening mechanical component relevance. Monitor integrated starter-generator penetration rates in full-hybrid platforms as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Compound Development | Gates Corporation's captive formulation control secures batch consistency across minus forty to one hundred twenty degrees Celsius certification. |
| Dual Manufacturing Footprint Expansion | Continental AG's Europe-Mexico positioning services just-in-time schedules for Stuttgart engineering centers and transplant factories. |
| JIS-Certified Timing Belt Localization | Mitsuboshi Belting Ltd.'s Nagoya precision capacity anchors premium supply agreements for southeastern US transplant operations. |
| Aramid-Polyester Hybrid Reinforcement Investment | Material suppliers qualifying hybrid layup configurations capture specification authority for downsized turbocharged engine programs. |
| Aftermarket Channel Digitization | Vertical marketplace partnerships disintermediate traditional wholesale markups for ribbed belt replacement volume in Germany. |
Methodological Framework
Multiple input streams — primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, and aftermarket distribution heads; secondary validation through customs trade data, vehicle production databases, and SEC automotive supplier filings; and technical compound specification reviews — were reconciled through bottom-up and top-down triangulation to construct market estimates.
Data-stream reconciliation applied analytical frameworks across product type, material composition, end-use application, and regional production cluster dimensions throughout the forecast period. CAGRs were derived from segment-level growth trajectories anchored to EPA fuel economy standard phase-ins, EU F-Gas Regulation compliance timelines, and China MIIT certification pathway acceleration.
Caveats apply where integrated starter-generator displacement in full-hybrid platforms, EPDM feedstock price volatility, or polymer chemist talent pipeline collapse could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Hand Crank Power Generator Market
Generators
Marine Gensets Market
Generators
South America Portable Generator Market
Generators
Boiler Turbine and Generator BTG Sales Market
Generators
Boiler, Turbine, and Generator (BTG) Market
Generators
Europe Turbo Generator Market
Generators
India Diesel Generator Market
Generators
Portugal Gas Generator Market
Generators
Nuclear Turbine Generators Market
Generators
Generator Sales Market
Generators
Industrial Generator Sets Market
Generators
Emergency Power Generators Sales Market
Generators
Silent Generator Market
Generators
Europe Portable Generator Market
Generators
Saudi Arabia Diesel Generator Market
Generators
India Generator Sets Market