
 Global Diesel Gensets Market | 2026-2036
Global Diesel Gensets Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diesel Gensets Market Analysis
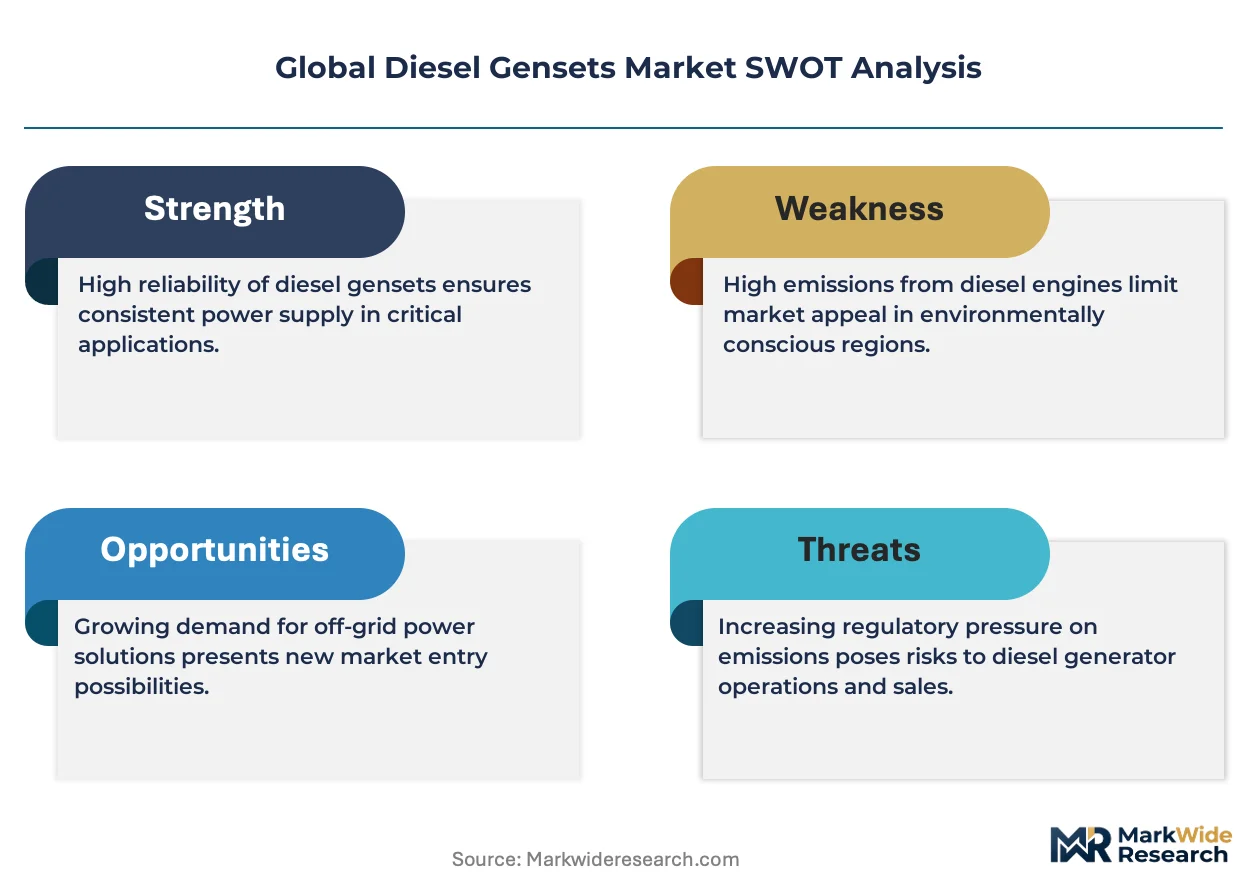
EPA Tier 4 Final is pivoting the competitive calculus for diesel genset manufacturers by mandating advanced after-treatment systems that add material cost and engineering complexity. Cummins Inc. leverages its integrated engine-aftertreatment platform to sustain pricing power across North American infrastructure projects. Caterpillar Inc. anchors its position through captive manufacturing of high-horsepower blocks and alternators. Wartsila Corporation competes in the above-500 kVA utility segment with medium-speed engine architectures optimized for continuous duty cycles.
Diesel gensets are internal-combustion-driven electromechanical units that convert diesel fuel into electrical energy through reciprocating engines coupled to synchronous alternators, typically operating at 1500 or 1800 RPM depending on grid frequency requirements. These systems deliver prime, standby, or continuous power across industrial, commercial, and institutional applications where grid reliability is insufficient or absent. The standby product type dominates revenue share due to mandatory backup requirements for hospitals, data centers, and financial institutions. The above-500 kVA capacity band captures disproportionate margin pools as mining and utility customers prioritize uptime over capital expenditure. Containerized installations are gaining traction in remote telecommunications and construction deployments where site preparation is minimal.
The US EPA, the EU F-Gas Regulation, and India's CEA technical standards collectively shape emission compliance timelines, refrigerant restrictions in ancillary cooling systems, and grid-interconnection protocols for captive power assets. Product certification under CE marking and EPA Tier 4 Final determines market access across developed economies, while India's BIS efficiency norms are tightening for sub-500 kVA units deployed in commercial buildings. Stakeholders must monitor the pace of dual-fuel retrofit adoption and hybrid integration mandates as these technologies threaten to displace pure diesel architectures in prime power applications before the forecast horizon concludes.
Market Dynamics
EPA Tier 4 Final compliance costs are compressing the supplier base by forcing integrated after-treatment architectures that smaller engine builders cannot engineer independently. This regulatory wall favors OEMs with captive emissions technology and in-house turbocharger manufacturing.
Growth Catalysts
- Data center buildouts:Hyperscale operators in India are mandating N+1 redundancy standards that require dedicated diesel backup for every megawatt of IT load. India's CEA technical standards for grid interconnection accelerate captive power deployment.
- Mining electrification gaps:Indonesian nickel and copper extraction corridors lack grid extension timelines, forcing prime-power diesel installations above 500 kVA for crushing and processing equipment.
- Containerized modularity:Plug-and-play genset enclosures are cutting site preparation costs for telecom tower operators across remote Southeast Asian archipelagos.
Market Restraints
- Platinum group metal volatility:Diesel oxidation catalysts and selective catalytic reduction systems depend on palladium and rhodium prices that swung 40% annually through recent trading cycles.
- High-horsepower block concentration:Foundry capacity for castings above 20 liters displacement concentrates in Germany, Japan, and the United States, creating single-source vulnerabilities.
- Dual-fuel retrofit economics:LNG and methanol conversion kits for existing engines threaten pure diesel architectures in prime power applications where fuel arbitrage justifies capital expenditure.
Strategic Opportunities
- Vietnam manufacturing corridors:Northern industrial zones around Hai Phong and Bac Ninh are attracting electronics assembly that requires uninterrupted power for cleanroom environments.
- Hybrid integration mandates:EU Green Deal financing mechanisms are subsidizing genset-battery hybrid systems for industrial microgrids that optimize load following and fuel consumption.
- Digital twin remote monitoring:Predictive maintenance platforms are opening recurring revenue streams for OEMs serving distributed telecom and mining fleets.
Industry Challenges
- Emissions calibration expertise:EPA Tier 4 Final and EU Stage V certification require software engineers capable of mapping engine control units across altitude and temperature variants, a skill set concentrated at incumbent OEMs.
- Legacy alternator interoperability:New engine platforms must maintain shaft alignment and voltage regulation compatibility with alternator fleets installed across existing customer bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diesel Gensets Market |
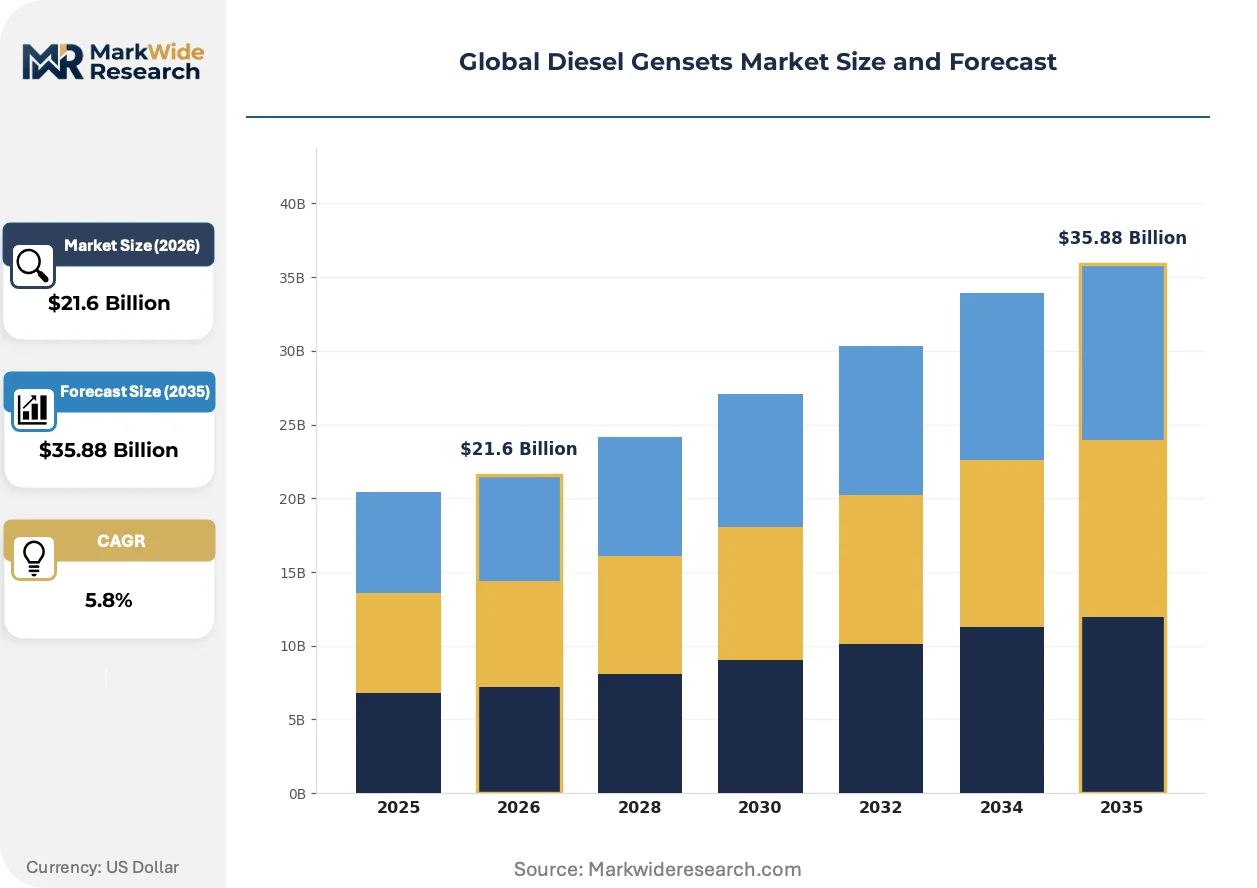
| Market Size in 2026 | $21.6 Billion |
| Market Size in 2035 | $35.88 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Prime Power, Continuous End User: Construction, Telecommunications, Mining, Hospitals Capacity: 1-100 kVA, 101-300 kVA, 301-500 kVA, Above 500 kVA Installation: Onsite, Offsite, Containerized, Mobile |
| Companies Covered | Caterpillar Inc., Cummins Inc., Rolls-Royce Holdings plc, Generac Power Systems Inc., Kohler Co., Mitsubishi Heavy Industries Ltd., Atlas Copco AB, Wartsila Corporation, Yanmar Holdings Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diesel Gensets Market Emerging Trajectories
After-treatment integration and digital connectivity are redefining competitive differentiation in diesel power systems. Manufacturers now compete on emissions compliance architecture and predictive service platforms rather than engine displacement alone.
Integrated selective catalytic reduction with diesel particulate filter systems is expanding into standby applications below 300 kVA that previously avoided after-treatment complexity. Hospital and financial institution buyers in California and Texas are accepting higher capital costs to secure EPA Tier 4 Final certification that guarantees air quality permits. This technology is expanding into smaller displacement segments previously dominated by mechanically governed engines, compressing the addressable market for carbureted architectures.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in genset ancillary cooling systems, forcing redesign of radiator and heat exchanger specifications. Engine OEMs must now validate alternative cooling fluids or enlarged air-cooled packages for European deployment. The above-500 kVA continuous duty segment is responding with closed-loop glycol systems that eliminate refrigerant dependency entirely.
Power-as-a-service contracting is displacing traditional equipment ownership in remote mining and oilfield applications. Caterpillar and Cummins are building captive financing arms that bundle fuel supply, maintenance, and uptime guarantees into per-kilowatt-hour tariffs. This model is most visible in Western Australian iron ore operations and Permian Basin drilling camps where capital discipline favors operational expenditure treatment.
Global Diesel Gensets Market Segmentation
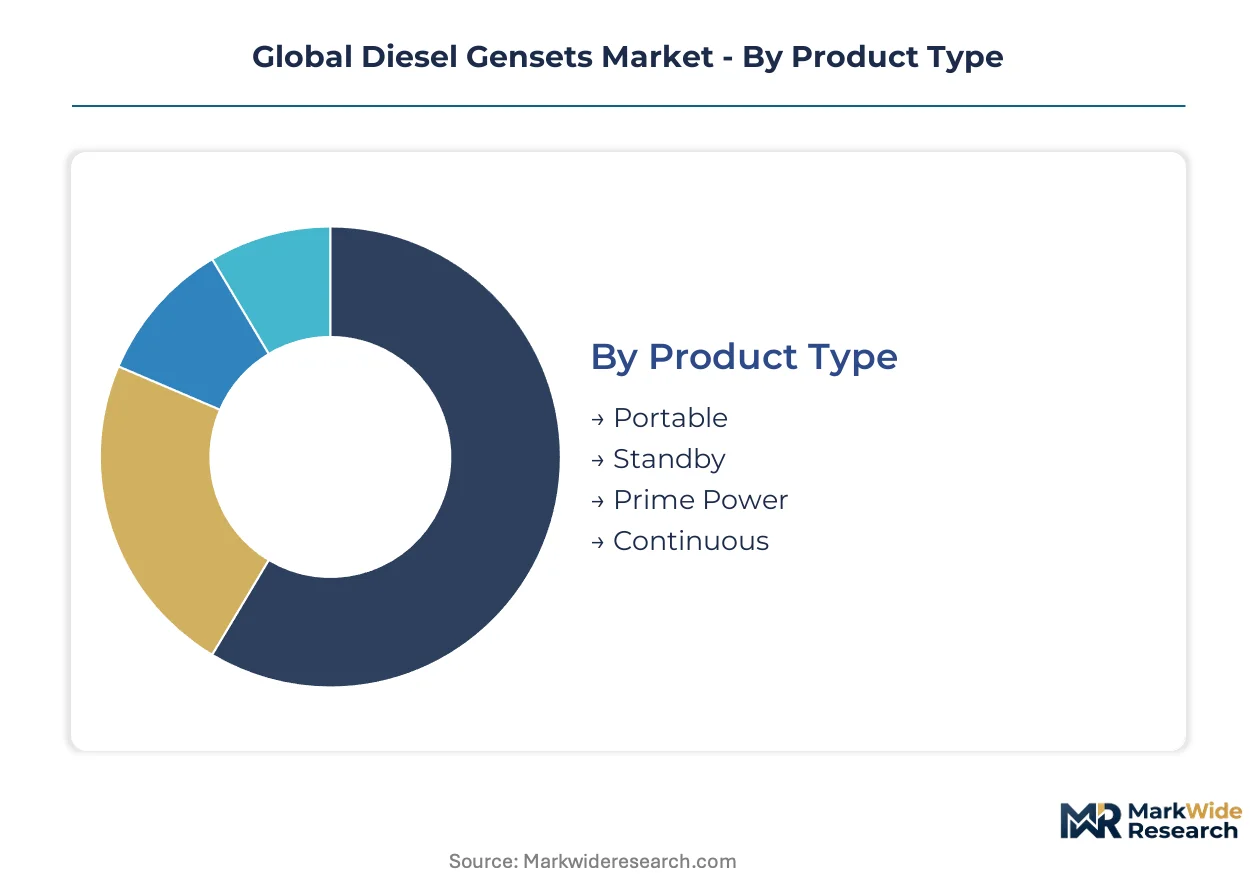
Diesel genset segmentation reflects divergent duty-cycle requirements and regulatory exposure across backup, prime, and continuous applications. Equipment replacement cycles vary dramatically—from intermittent standby testing to 8,000+ annual operating hours in mining corridors—creating distinct margin and service attach-rate profiles for each segment category.
Product Type:
Upgrade cycles accelerate where EPA Tier 4 Final and EU Stage V force engine platform obsolescence, compressing replacement windows for mechanically governed architectures.
- Standby:Units designed for emergency power delivery with automatic transfer switch integration and NFPA 110 compliance. Demand concentrates in Indian data center buildouts where N+1 redundancy mandates require dedicated backup capacity for every megawatt of IT load, with CEA technical standards accelerating captive power deployment timelines.
- Continuous:Engine-generator sets rated for unlimited annual hours at variable load, deployed where grid extension is uneconomical. Indonesian nickel and copper extraction corridors drive procurement above 500 kVA for crushing and processing equipment, with mining operators prioritizing uptime guarantees over capital expenditure.
- Portable:Trailer-mounted or skid-based units for temporary power in construction and event applications.
- Prime Power:Systems rated for variable load operation with unlimited annual hours, common in remote industrial camps.
Standby sits at the top of the volume ranking, with Continuous climbing the fastest.
End User:
Cost tier stratification separates price-sensitive construction rental fleets from premium uptime contracts in healthcare and hyperscale computing.
- Data Centers:Hyperscale operators in India mandate N+1 redundancy with dedicated diesel backup per megawatt of IT load. Northern Virginia, Frankfurt, and Mumbai clusters drive procurement of EPA Tier 4 Final and CEA-certified units where air quality permits and grid interconnection protocols constrain equipment selection.
- Mining:Prime-power installations above 500 kVA dominate where grid extension lacks economic justification. Western Australian iron ore operations and Indonesian nickel corridors favor power-as-a-service contracting with bundled fuel supply and uptime guarantees over equipment ownership.
- Construction:Rental fleet demand for portable and mobile units across Southeast Asian infrastructure projects.
- Telecommunications:Remote tower backup requirements across Indonesian and Philippine archipelagos favor containerized plug-and-play deployments.
- Hospitals:NFPA 99 and Joint Commission mandates for emergency power in California and Texas healthcare systems.
Mining captures the steepest expansion trajectory, while Data Centers command premium pricing tiers.
Capacity:
Application requirements scale from single-phase commercial backup to utility-grade continuous duty, with foundry capacity for large displacement blocks concentrating supply risk.
- Above 500 kVA:High-horsepower blocks for continuous mining and utility applications where uptime economics dominate procurement decisions. Foundry capacity for castings above 20 liters displacement concentrates in Germany, Japan, and the United States, creating single-source vulnerabilities for mining electrification gaps in Southeast Asia.
- 301-500 kVA:Mid-range segment bridging commercial standby and light industrial prime power.
- 101-300 kVA:Commercial building and small data center standby where integrated SCR-DPF after-treatment is expanding from larger segments.
- 1-100 kVA:Residential and small commercial backup where mechanical governing persists in price-sensitive markets.
Above 500 kVA leads margin pools, with 101-300 kVA gaining share fastest as after-treatment integration penetrates smaller segments.
Installation:
Site preparation cost and deployment velocity determine competitive positioning between permanent enclosures and modular plug-and-play systems.
- Containerized:ISO-frame or custom enclosures housing engine, alternator, fuel system, and control panel in weatherproof assemblies. Telecom tower operators across remote Southeast Asian archipelagos favor these configurations for minimal civil works and rapid commissioning timelines.
- Onsite:Permanent installation with dedicated foundation, acoustic enclosure, and fixed fuel storage for hospital and data center applications.
- Mobile:Trailer-mounted units for construction rental fleets requiring frequent relocation.
- Offsite:Prefabricated power modules delivered as complete systems for rapid deployment in disaster recovery scenarios.
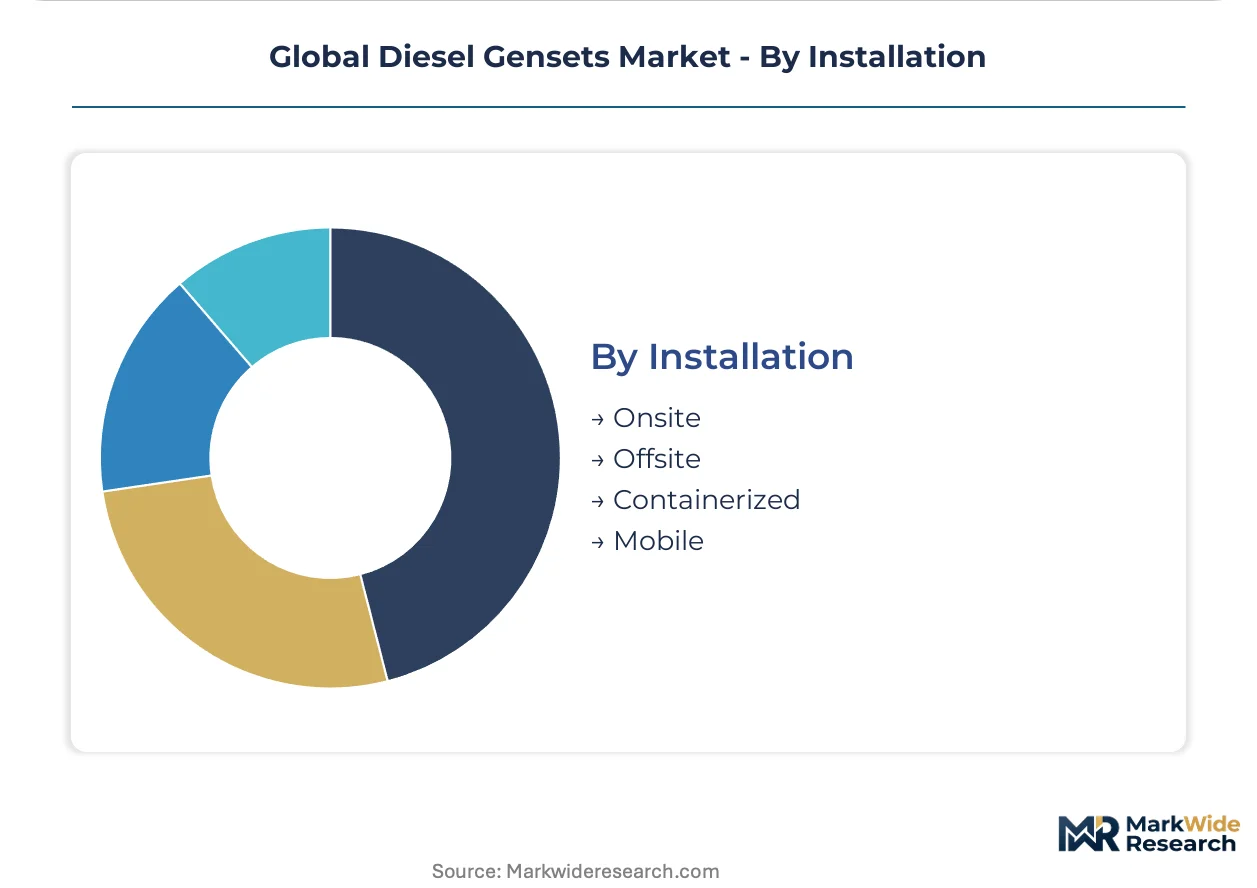
Onsite retains the largest installed base, with Containerized expanding most quickly in remote telecommunications infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools for emissions calibration and after-treatment integration concentrate in Germany, the United States, and Japan, anchoring the geographic distribution of high-complexity manufacturing.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives standby genset procurement for N+1 redundancy compliance. EPA Tier 4 Final certification requirements filter equipment selection for California and Texas healthcare systems. Houston's energy corridor hosts service infrastructure for Permian Basin oilfield power-as-a-service deployments.
India
Hyperscale operators in Mumbai and Delhi-NCR mandate dedicated diesel backup per megawatt of IT load under CEA technical standards. BIS efficiency norms tighten for sub-500 kVA units in commercial buildings. Chennai and Hyderabad data center clusters accelerate captive power deployment timelines.
Germany
Foundry capacity for high-horsepower engine blocks above 20 liters displacement anchors European supply security. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants in ancillary cooling systems. Bavaria's industrial automation sector drives continuous-duty genset demand for manufacturing resilience.
Indonesia
Nickel and copper extraction corridors in Sulawesi and Papua lack grid extension timelines, forcing prime-power diesel installations above 500 kVA. Mining operators prioritize uptime guarantees over capital expenditure in crushing and processing applications. Remote telecommunications towers across the archipelago favor containerized plug-and-play configurations.
Vietnam
Electronics assembly in Hai Phong and Bac Ninh industrial zones requires uninterrupted power for cleanroom environments. Northern manufacturing corridors attract foreign direct investment with dedicated captive power infrastructure. Samsung and LG supply chain clusters drive precision manufacturing backup requirements.
Global Diesel Gensets Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capacity bands and duty-cycle applications. The supplier base compresses as EPA Tier 4 Final compliance costs eliminate smaller engine builders lacking integrated after-treatment capabilities. Three strategic archetypes dominate: integrated engine-aftertreatment platforms, captive high-horsepower foundry operations, and power-as-a-service financing arms. Competitive moves concentrate on hybrid system integration partnerships and predictive maintenance platform deployment.
Within the integrated platform tier, Caterpillar Inc. and Cummins Inc. exemplify manufacturers with captive emissions technology and in-house turbocharger production. Wartsila Corporation occupies a position in the above-500 kVA utility segment with medium-speed engine architectures. These three anchors represent divergent approaches to regulatory compliance—captive manufacturing, integrated after-treatment, and continuous-duty optimization—each capturing distinct margin pools across standby, prime, and continuous applications.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Rolls-Royce Holdings plc |
| Generac Power Systems Inc. |
| Kohler Co. |
| Mitsubishi Heavy Industries Ltd. |
| Atlas Copco AB |
| Wartsila Corporation |
| Yanmar Holdings Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
EPA Tier 4 Final certification bifurcation separates premium OEMs with integrated after-treatment platforms from commodity assemblers dependent on third-party emissions hardware. This certification ladder manifests in pricing power concentration among engine manufacturers with captive turbocharger production and in supply chain configurations that source high-horsepower castings from German, Japanese, and American foundries while routing smaller displacement blocks through Southeast Asian machining centers.
Pricing Analysis
Bundled power-as-a-service contracts diverge sharply from unbundled equipment transactions across mining and oilfield applications. Three-tier pricing structure across EPA-certified premium, CEA-compliant standard, and mechanically governed economy levels reflects after-treatment complexity and software calibration investment. Cost compression in the sub-300 kVA standby segment intensifies as integrated SCR-DPF systems expand downward from utility-scale architectures. Data center operators in India exhibit lowest price sensitivity due to N+1 redundancy mandates, while Southeast Asian construction rental fleets prioritize capital expenditure minimization over certification tier.
Supply Chain Analysis
Warehouse-distribution layers concentrate in Houston, Singapore, and Rotterdam as regional hubs for spare parts and remanufactured components. Foundry capacity for castings above 20 liters displacement anchors in Germany, Japan, and the United States, creating single-source vulnerabilities for mining electrification gaps in Indonesia. Palladium and rhodium feedstock for diesel oxidation catalysts draws from South African and Russian extraction corridors. Tariff exposure on precision-machined engine components threatens margin stability. Distribution runs through authorized dealer networks with captive service infrastructure rather than open wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diesel genset demand functions as a regulatory compounder where EPA Tier 4 Final and India's CEA technical standards accelerate replacement cycles and compress supplier viability windows.
For Market Incumbents: Acquire emissions calibration software engineering teams to defend against dual-fuel retrofit technologies threatening pure diesel architectures in prime power applications. Deepen backward integration into turbocharger manufacturing to sustain pricing power as after-treatment integration mandates expand into sub-300 kVA segments. Channel control through captive financing arms locks in mining and data center customers against emerging hybrid system integrators.
For New Entrants and Emerging Players: Containerized plug-and-play architectures offer a technology-first wedge into Indonesian and Philippine telecommunications infrastructure where site preparation constraints favor rapid deployment. White-space concentration sits in Vietnam's northern industrial zones around Hai Phong and Bac Ninh, where electronics assembly cleanroom power requirements outpace local grid reliability. Go-to-market positioning through EPC contractor partnerships bypasses incumbent dealer network lock-in.
For Investors and Strategic Acquirers: Consolidation pressure builds where EPA Tier 4 Final compliance costs eliminate smaller engine builders lacking integrated after-treatment capabilities. Long-term viability favors OEMs with hybrid integration roadmaps and predictive maintenance platform deployment. Acquisition targets should demonstrate captive foundry relationships or software-defined engine control unit capabilities. The signal to watch is dual-fuel retrofit adoption velocity in Western Australian iron ore corridors as a leading indicator for prime power displacement risk.
| Strategic Initiative | Industry Significance |
|---|---|
| After-Treatment Platform Integration | EPA Tier 4 Final compliance anchors market access across North American infrastructure procurement. |
| Hybrid System Development Partnership | EU Green Deal financing mechanisms subsidize genset-battery configurations for industrial microgrids. |
| Predictive Maintenance Platform Deployment | Digital twin remote monitoring opens recurring revenue streams for distributed telecom and mining fleets. |
| Power-as-a-Service Financing Arm Buildout | Caterpillar and Cummins captive financing bundles fuel supply and uptime guarantees in Permian Basin drilling camps. |
| Regional Distribution Hub Expansion | Singapore and Rotterdam warehousing positions service infrastructure for Southeast Asian archipelago deployments. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with data center engineering directors, mining procurement leads, OEM aftermarket service heads, and EPC contractor project managers alongside secondary validation. Triangulation draws from EPA certification databases, India's CEA technical standards filings, EU F-Gas Regulation implementation reports, and customs trade data on engine block imports. Bottom-up equipment shipment analysis and top-down power demand modeling converge across segmentation dimensions.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation modeling incorporates product type, end-use application, capacity tier, and installation configuration as core dimensions. CAGRs derive from regression analysis against macroeconomic indicators and regulatory compliance timelines. Industry-specific forecast inputs include data center power density trends and mining electrification gap persistence in Indonesian nickel corridors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to dual-fuel retrofit economics and battery storage cost curves. Outputs reflect documented assumptions regarding EPA enforcement consistency and India's CEA implementation pace. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
South America Generator Sets Market
Generators
South America Gas Generator Market
Generators
Silent Generator Market
Generators
Commercial Generator Market
Generators
Kuwait Diesel Gensets Market
Generators
Africa Portable Generator Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Asia-Pacific Generator Sets Market
Generators
Residential Gas Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Construction Generator Sets Market
Generators
Telecom Generator Market
Generators
Halogenerator Market
Generators
Southeast Asia Portable Generator Market
Generators
Electric Generators Market
Generators
Marine Gensets Market