
 East Africa Diesel Generator Market | 2026-2036
East Africa Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Diesel Generator Market Foresight
Kenya's Energy Regulatory Authority emission guidelines for stationary engines is decoupling procurement from unregulated open-type units. Caterpillar Inc. leverages its East African dealer network to sustain aftermarket parts availability. Kirloskar Oil Engines Limited anchors its position through localized assembly partnerships. African Power Machinery (TZ) Ltd dominates Tanzania's mining belt with mobile generator fleets.
East Africa diesel generators are internal combustion engine systems converting diesel fuel into electrical energy through electromagnetic induction, typically operating at 1500 RPM for 50 Hz output to match regional grid standards. Silent-type enclosures with integrated fuel tanks and automatic transfer switches serve hospitals and telecom towers where noise and uptime are critical. The commercial end-user segment leads volume as Nairobi and Dar es Salaam banking headquarters deploy redundant standby systems. Above 500 kVA units command premium margins from cement manufacturers and port operators requiring baseload displacement during grid failures.
Kenya's Energy Regulatory Authority, Tanzania's Energy and Water Utilities Regulatory Authority, and Rwanda's Rwanda Utilities Regulatory Authority enforce national grid codes that mandate automatic synchronization protocols for backup generators above 100 kVA. These frameworks shape product certification requirements and installation permitting timelines across the region. Stakeholders must monitor how Ethiopia's ongoing grid expansion and Uganda's rural electrification programs alter the addressable market for prime-power versus standby configurations.
Market Dynamics
Grid instability across Kenya, Tanzania, and Uganda is forcing commercial and industrial buyers to treat diesel generators as primary power assets rather than emergency backup, restructuring procurement priorities and service contract terms throughout the region.
Growth Catalysts
- Mining expansion in Tanzania's Lake Victoria zone:Gold and graphite extraction operations require mobile prime-power units for remote sites lacking grid connectivity, driving fleet procurement above 500 kVA.
- Kenya's Energy Regulatory Authority emission guidelines:Stationary engine standards are phasing out unregulated open-type generators, creating replacement demand for compliant silent-type configurations in Nairobi's commercial districts.
- Automatic transfer switch integration:Hospitals and telecom towers now mandate seamless grid-to-generator switching, elevating specification requirements for integrated control systems.
Market Restraints
- Diesel fuel price volatility:Import-dependent supply chains expose operators to currency fluctuation and regional taxation shifts, compressing operating margins for continuous-use applications.
- Chinese manufacturer concentration:Mid-range generator assembly relies heavily on engine block imports from single-source geographies, creating vulnerability to shipping disruption and tariff adjustment.
- Battery energy storage substitution:Lithium-ion paired with solar PV is displacing diesel for daytime baseload in Rwanda's commercial installations, narrowing the addressable market for prime-power configurations.
Strategic Opportunities
- Ethiopia's grid expansion gaps:Industrial parks outside Addis Ababa's transmission network present unserved demand for hybrid diesel-solar systems in manufacturing zones.
- East African Community harmonized standards:Cross-border certification alignment reduces compliance duplication, enabling Kenya-based distributors to scale into Uganda and Rwanda without product re-engineering.
- Telecom tower consolidation:Tower companies are unbundling power-as-a-service from infrastructure ownership, creating recurring revenue streams for generator fleet operators.
Industry Challenges
- Certification timeline compression:Rwanda Utilities Regulatory Authority grid code compliance for units above 100 kVA requires extended testing protocols, delaying installation and revenue recognition.
- Synchronization engineering scarcity:Qualified technicians for paralleling multiple generators in data center applications command premium wages, constraining deployment velocity for redundant systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Diesel Generator Market |
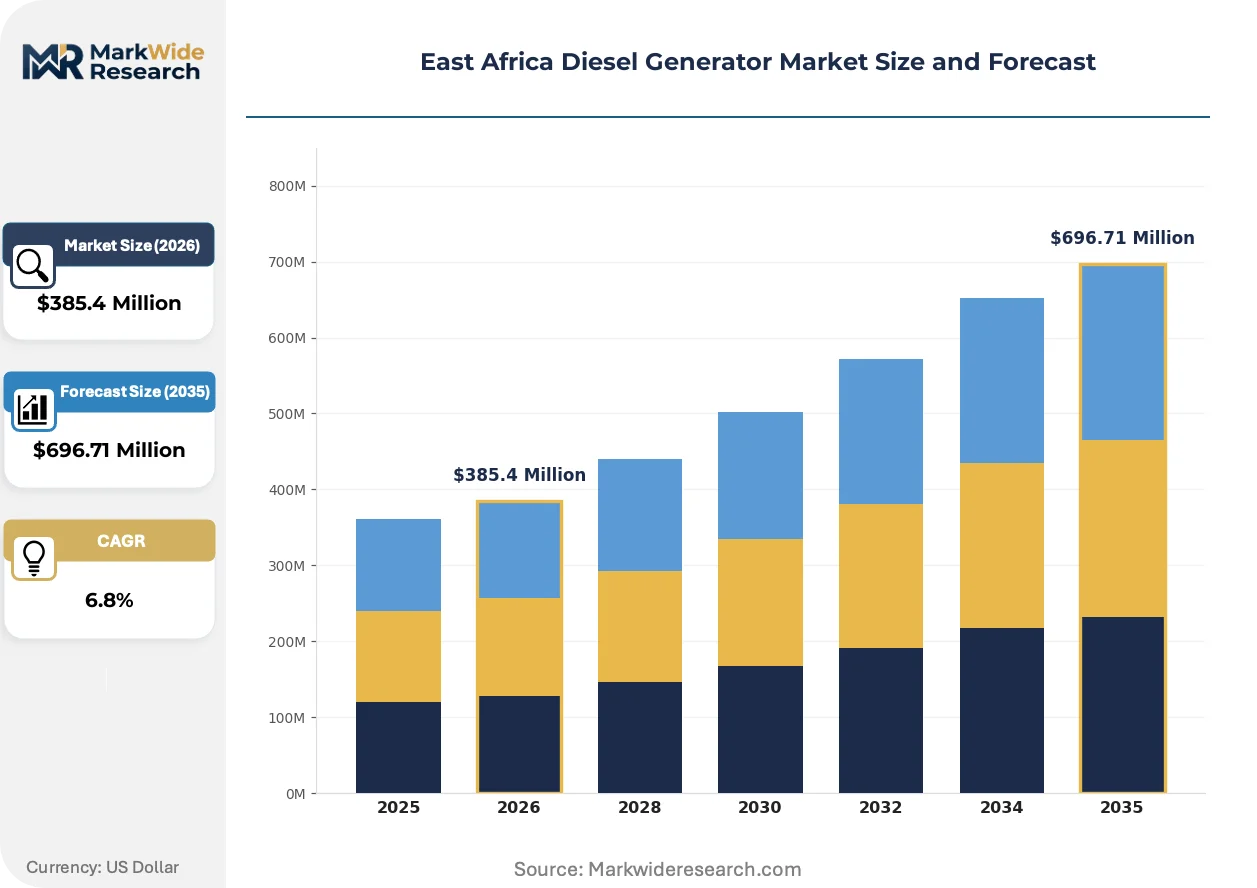
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Type, Silent Type, Mobile Type, Standby Type Application: Construction, Mining, Agriculture, Hospitality End User: Residential, Commercial, Industrial, Government Power Rating: Below 100 kVA, 100-300 kVA, 300-500 kVA, Above 500 kVA |
| Companies Covered | Caterpillar Inc., Ettes Power Machinery Co Ltd, African Power Machinery (TZ) Ltd, Kirloskar Oil Engines Limited, General Electric Company, AKSA Power Generation, Deutz Dieselpower, Masterpower Generator Industry and Trading Inc, Car and General (Kenya) PLC, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Diesel Generator Market Shifts & Advancements
Silent-type enclosure engineering and digital load management are converging to redefine generator specifications, with buyers prioritizing noise attenuation and remote monitoring over raw power output ratings.
Integrated fuel polishing systems are unifying diesel storage and filtration within generator enclosures, eliminating separate tank maintenance contracts. Nairobi hospital procurement teams specify these configurations to reduce infection control risks from external fuel handling. The technology is compressing total cost of ownership calculations by consolidating service intervals.
Tanzania's Energy and Water Utilities Regulatory Authority is enforcing automatic synchronization protocols for backup units above 100 kVA, mandating paralleling capability that previously served only prime-power segments. Cement manufacturers in Dar es Salaam are retrofitting existing fleets to comply, triggering aftermarket controller upgrades. The regulation is reshaping product roadmaps for regional distributors.
Power-as-a-service contracts are displacing capital purchase models for telecom infrastructure operators, with tower companies outsourcing generator ownership to specialized fleet managers. MTN and Airtel subsidiaries across Kenya and Uganda now lease uptime guarantees rather than equipment. This shift concentrates buying power among fewer procurement decision-makers.
East Africa Diesel Generator Market Segmentation
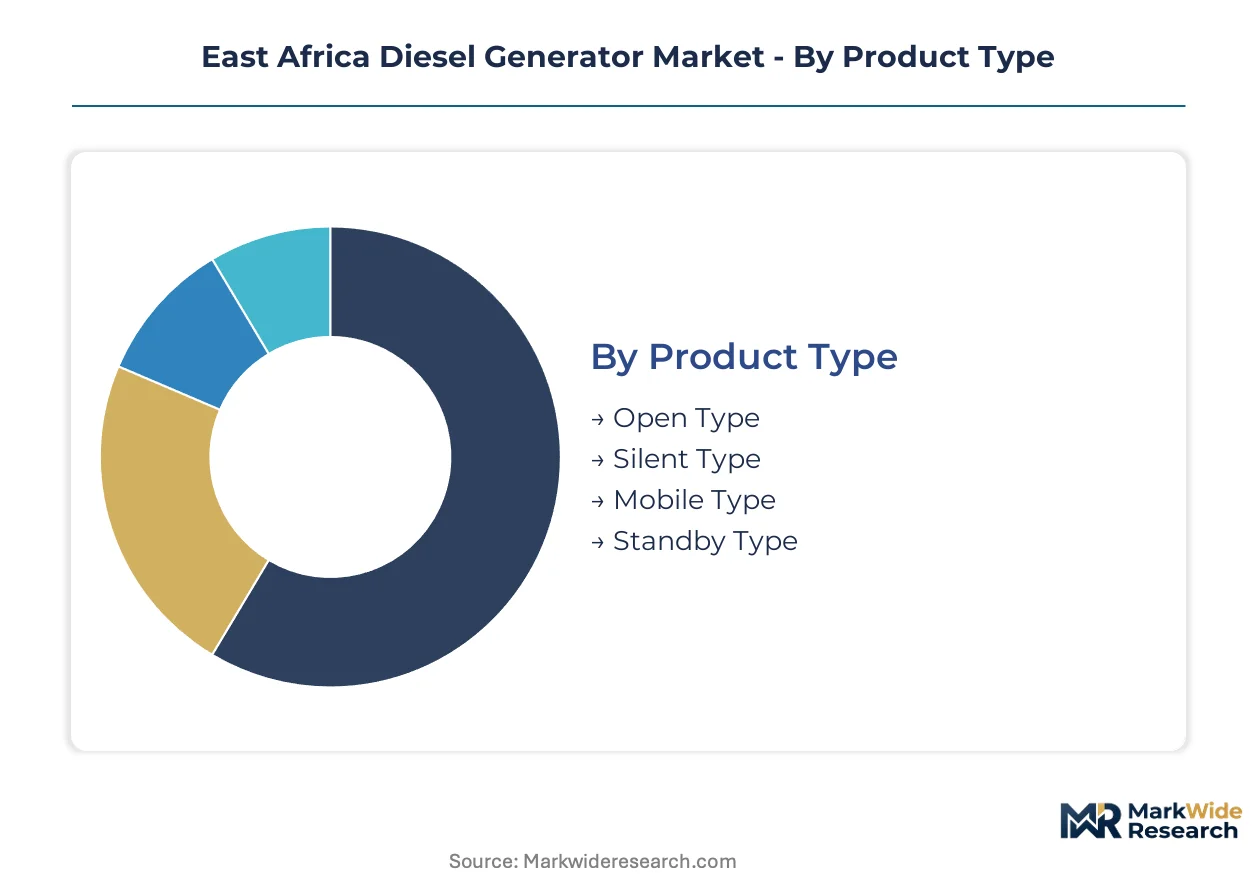
Segmentation in East Africa's diesel generator market reveals how capital deployment, regulatory pressure, and grid reliability gaps reshape procurement patterns across product configurations and power ratings. Buyers prioritize silent-type enclosures in urban Kenya and mobile fleets in Tanzania's mining corridors, creating divergent specification requirements.
Product Type:
Capital intensity varies sharply across enclosure configurations, with integrated silent-type systems demanding premium upfront investment for acoustic engineering and fuel tank integration.
- Open Type:Unenclosed engine-generator sets expose moving components to dust and moisture, limiting deployment to industrial yards and temporary construction sites in Kenya's Athi River manufacturing zone where noise restrictions remain unenforced.
- Silent Type:Acoustic enclosures with integrated fuel tanks and attenuated exhaust systems command 40-60% capital premiums over open equivalents. Nairobi's hospital procurement teams mandate these configurations to comply with Kenya Energy Regulatory Authority noise guidelines while maintaining infection control protocols.
- Mobile Type:Trailer-mounted or skid-based units serve Tanzania's Lake Victoria gold belt where grid infrastructure is absent.
- Standby Type:Automatic transfer switch integration elevates specification complexity for data centers and banking headquarters along Kenya's Nairobi-Mombasa corridor.
Most installed capacity flows through Silent Type configurations. Expansion is steepest in Mobile Type.
Application:
Application segmentation tracks where continuous prime-power operation displaces intermittent standby use, restructuring service contract economics and fuel logistics requirements.
- Construction:Temporary power for building sites favors rental fleet deployment over ownership, with Chinese contractors in Ethiopia's industrial parks driving short-term procurement cycles.
- Mining:Remote extraction operations in Tanzania's graphite and gold sectors require 500+ kVA prime-power units operating 20+ hours daily. Barrick Gold and Shanta Gold maintain captive diesel fleets where grid extension timelines exceed project horizons.
- Agriculture:Tea processing cooperatives in Kenya's Rift Valley deploy mid-range standby units for irrigation pump backup during dry season grid instability.
- Hospitality:Safari lodges and coastal resorts prioritize silent-type specifications to preserve guest experience, with Zanzibar's hospitality sector accelerating replacement of aging open-type inventory.
Revenue concentrates in Mining applications. Procurement velocity is climbing fastest in Hospitality.
End User:
End-user segmentation exposes divergent buying power and technical sophistication, with industrial purchasers commanding customization while residential buyers accept standardized configurations.
- Residential:Single-family and small commercial installations below 50 kVA dominate unit volume but generate thin margins. Kenyan middle-class households in Nairobi's satellite towns drive demand for compact silent-type sets during scheduled grid maintenance.
- Commercial:Banking headquarters, retail chains, and telecom towers constitute the revenue core. Safaricom and Equity Bank maintain redundant standby systems across branch networks, with automatic synchronization now mandatory per Rwanda Utilities Regulatory Authority codes.
- Industrial:Cement manufacturers and port operators in Dar es Salaam and Mombasa specify above-500 kVA units for baseload displacement, commanding premium pricing and multi-year service contracts.
- Government:Public procurement favors lowest-compliant-bid mechanisms, compressing supplier margins on hospital and school installations despite stringent certification requirements.
Commercial end users absorb the largest share of generator value. Industrial buyers are expanding fleet size most aggressively.
Power Rating:
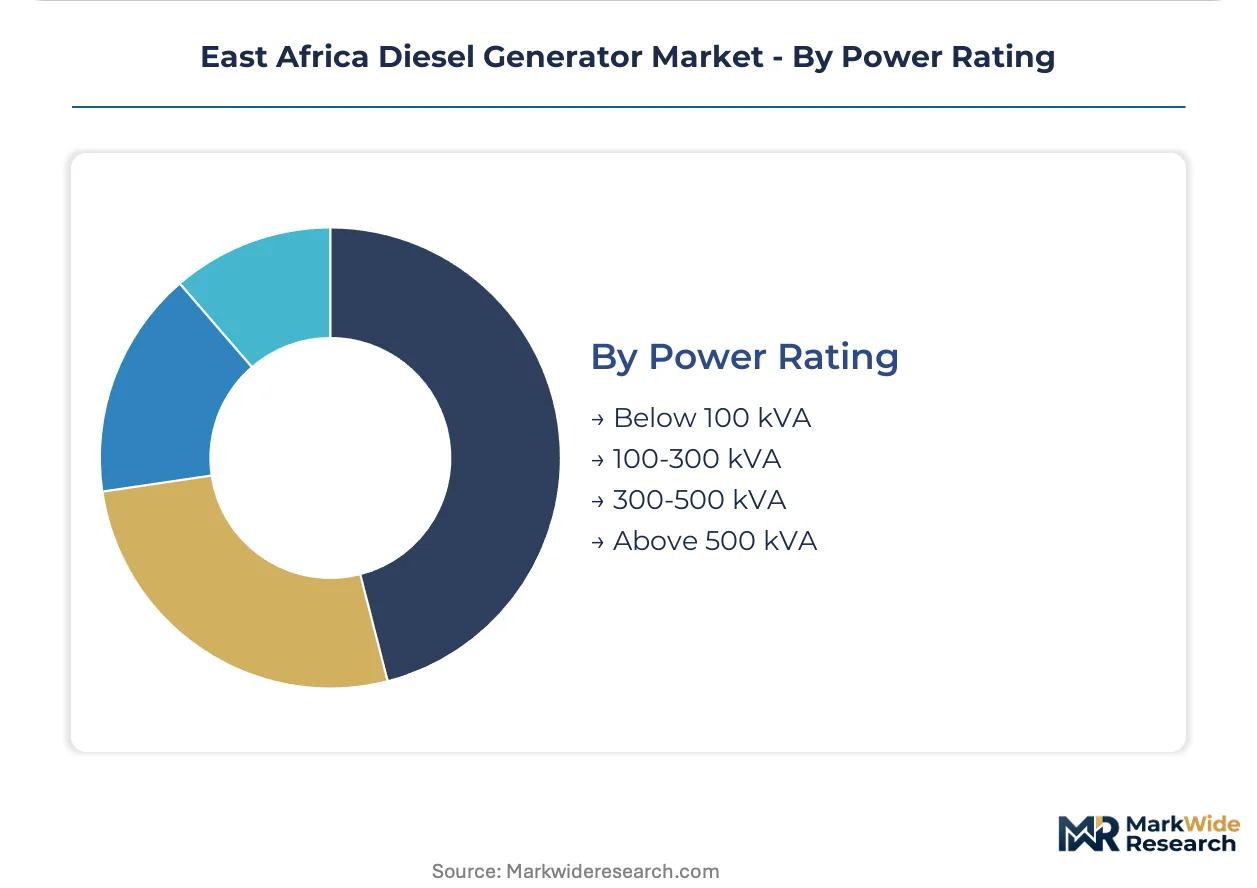
Power rating segmentation aligns with site-scale economics, where threshold effects at 100 kVA and 500 kVA trigger regulatory compliance steps and synchronization engineering requirements.
- Below 100 kVA:Compact single-phase or three-phase units serve residential and small commercial loads. These configurations escape Rwanda's mandatory synchronization protocols, simplifying installation but limiting paralleling flexibility for future expansion.
- 100-300 kVA:Mid-range industrial and commercial standby systems represent the volume sweet spot. Nairobi's logistics hubs and Kampala's manufacturing zones standardize on this band for cost-efficient redundancy without full prime-power engineering.
- 300-500 kVA:Large commercial and light industrial applications requiring sustained operation. Tanzania's graphite processing plants deploy these units for process-critical loads where grid quality fluctuates seasonally.
- Above 500 kVA:Heavy industrial prime-power and data center applications command engineering-intensive paralleling controls. Kenya's Konza Technopolis data center operators specify this tier for N+1 redundancy, with synchronization capability now mandatory across East African Community harmonized standards.
Unit shipments peak in the 100-300 kVA band. Value expansion is most pronounced Above 500 kVA.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified technicians for generator synchronization and paralleling systems concentrate in Nairobi and Dar es Salaam, creating service delivery advantages for distributors headquartered in these commercial hubs.
Kenya
Data center construction in Konza Technopolis and logistics hub expansion along the Nairobi-Mombasa corridor drive demand for above-500 kVA standby systems. Kenya's Energy Regulatory Authority enforces emission guidelines for stationary engines that phase out unregulated open-type generators. Banking headquarters in Nairobi's Upper Hill district deploy redundant silent-type configurations to comply with noise restrictions while maintaining uptime guarantees.
Tanzania
Gold and graphite extraction operations in the Lake Victoria zone require mobile prime-power units for remote sites lacking grid connectivity. Tanzania's Energy and Water Utilities Regulatory Authority mandates automatic synchronization protocols for backup generators above 100 kVA. Cement manufacturers in Dar es Salaam retrofit existing fleets with paralleling controllers to meet compliance deadlines.
Uganda
Kampala's manufacturing zones and telecom infrastructure operators standardize on mid-range standby systems for cost-efficient redundancy. The country's national energy regulator applies grid code requirements adapted from East African Community harmonized standards. Industrial parks in Namanve and Luzira concentrate procurement of 100-300 kVA units for process-critical loads.
Ethiopia
Industrial parks outside Addis Ababa's transmission network present unserved demand for hybrid diesel-solar configurations in manufacturing zones. The Ethiopian Electric Power utility's grid expansion timeline leaves gaps that prime-power generators fill for textile and leather processors. Chinese contractors in Hawassa and Bole Lemi industrial parks drive short-term rental fleet deployment.
Rwanda
Commercial installations in Kigali's central business district displace diesel daytime baseload with lithium-ion paired with solar PV. Rwanda Utilities Regulatory Authority enforces mandatory synchronization protocols that extend testing timelines for units above 100 kVA. Telecom tower operators in the country's hilly terrain lease power-as-a-service rather than owning generator assets directly.
East Africa Diesel Generator Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the East Africa diesel generator market. Integrated manufacturers with captive engine foundries and acoustic engineering capabilities command premium positioning in silent-type segments. The vendor base stratifies into three archetypes: global engine licensors with regional distribution networks, localized assemblers with government procurement relationships, and specialized fleet operators serving mining and telecom verticals. Competitive intensity centers on aftermarket parts availability and service contract bundling rather than equipment pricing alone.
Within the global engine licensor tier, Caterpillar Inc. and General Electric Company anchor premium positioning through established East African dealer infrastructure. Kirloskar Oil Engines Limited exemplifies the localized assembler archetype, leveraging Indian manufacturing scale with regional assembly partnerships. African Power Machinery (TZ) Ltd occupies a specialized position serving Tanzania's mining belt with mobile generator fleets. Ettes Power Machinery Co Ltd represents Chinese manufacturing scale competing on capital cost for mid-range commercial applications.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Ettes Power Machinery Co Ltd |
| African Power Machinery (TZ) Ltd |
| Kirloskar Oil Engines Limited |
| General Electric Company |
| AKSA Power Generation |
| Deutz Dieselpower |
| Masterpower Generator Industry and Trading Inc |
| Car and General (Kenya) PLC |
| Others |
Supply & Pricing Matrix
Qualified synchronization technicians concentrated in Nairobi and Dar es Salaam create labor-cost differentials that widen pricing-tier spreads between premium paralleling systems and basic standby configurations across East Africa.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by certification grade against East African Community harmonized standards and after-sales service bundling. Price erosion runs through economy-tier open-type units as Chinese imports compress capital costs for construction-site buyers. Commercial banking and telecom tower operators show lowest price sensitivity, prioritizing uptime guarantees and automatic transfer switch integration over unit economics.
Supply Chain Analysis
Engine block supply rests on manufacturing concentration in China, India, and Japan, with acoustic enclosure fabrication anchored in South African and Kenyan metalworking clusters. Diesel generator assembly draws from imported engine castings, copper windings, and electronic controller modules. Single-source vulnerability in Chinese engine supply creates exposure to shipping disruption and tariff adjustment. Distribution runs through Nairobi-based dealer networks serving Kenya, Uganda, and Rwanda, with Dar es Salaam distributors commanding Tanzania's mining corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
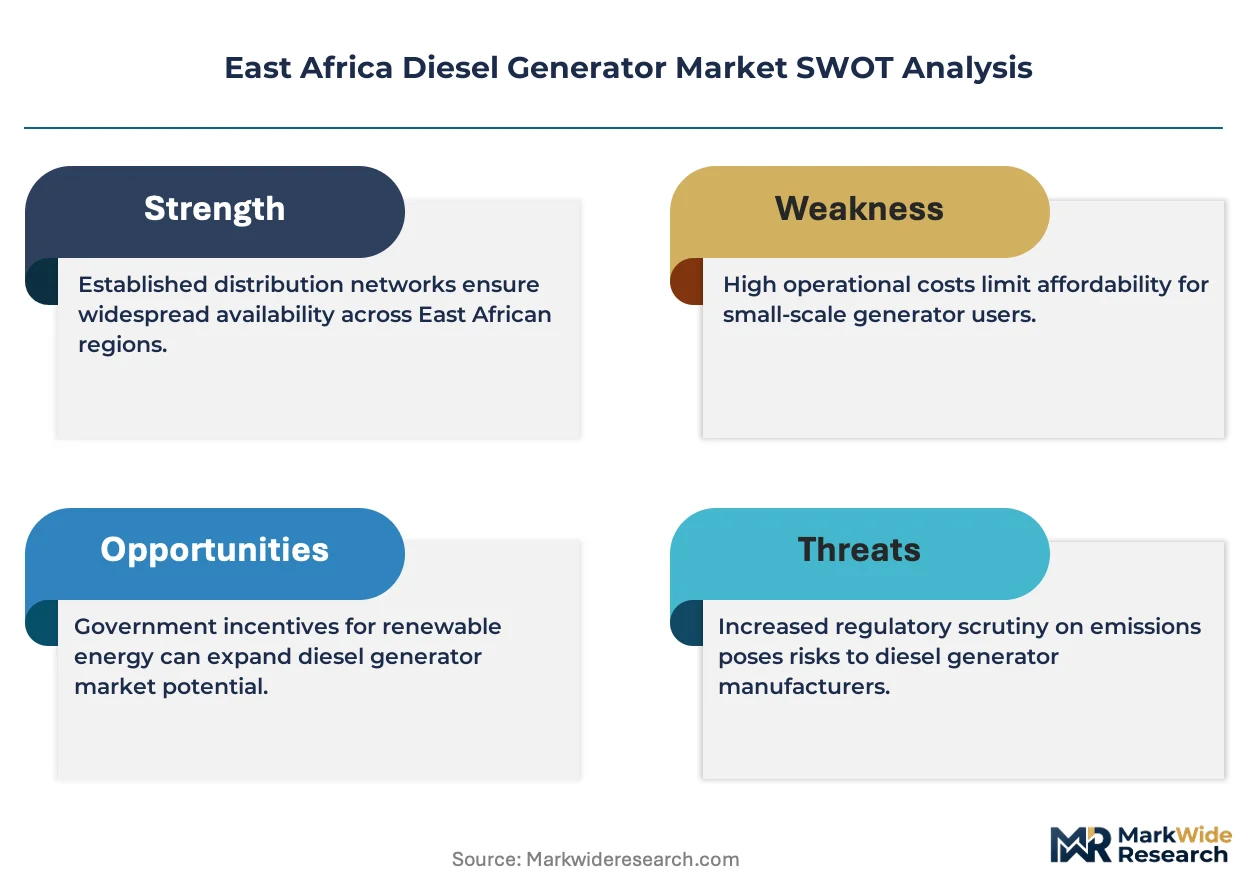
Margin expansion in East Africa's diesel generator market stems from premium-tier shift toward silent-type configurations with integrated fuel polishing and remote monitoring capabilities.
For Market Incumbents: Hedge against battery-solar substitution in Rwanda's commercial segment by deepening service contract penetration in Tanzania's mining belt. Secure backward integration into controller module supply to reduce exposure to Chinese single-source vulnerability. Invest in synchronization engineering certification programs to capture premium pricing for data center deployments above 500 kVA. For New Entrants and Emerging Players: Capture white-space demand in Ethiopia's industrial park zones outside Addis Ababa's transmission network, where hybrid diesel-solar configurations face limited incumbent presence. Target mobile prime-power rentals for Chinese contractors in Hawassa and Bole Lemi. Build go-to-market through power-as-a-service contracts with tower companies unbundling infrastructure ownership. For Investors and Strategic Acquirers: Specialized fleet operators serving mining and telecom verticals are the most active acquirer targets in this space. Long-term viability hinges on service revenue share expansion versus equipment sales dependence. Watch Rwanda Utilities Regulatory Authority grid code enforcement timelines as inflection indicator for synchronization capability demand.| Strategic Initiative | Industry Significance |
|---|---|
| Silent-Type Configuration Expansion | Acoustic engineering investment captures Kenya Energy Regulatory Authority compliance premiums in Nairobi commercial districts. |
| Power-as-a-Service Contracting | Recurring revenue models align with MTN and Airtel tower unbundling strategies across Kenya and Uganda. |
| Automatic Synchronization Capability | Paralleling controller upgrades satisfy Tanzania Energy and Water Utilities Regulatory Authority mandates above 100 kVA. |
| Hybrid Diesel-Solar Integration | Dual-fuel configurations address Ethiopia industrial park gaps outside Addis Ababa transmission network. |
| Regional Certification Harmonization | East African Community standards alignment enables Kenya-based distributors to scale into Uganda and Rwanda without re-engineering. |
Research Methodology
Multiple input streams — procurement directors at Nairobi banking headquarters, maintenance engineers at Tanzania mining operations, and regulatory affairs specialists at East African Community bodies — were reconciled against customs import records, national grid code filings, and EPC contractor project databases. Bottom-up unit shipment estimates from distributor channel checks were triangulated with top-down diesel fuel consumption models across prime-power and standby applications.
Historical installation data cross-referenced against panel input from generator fleet operators and tower company power managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include enclosure configuration, power rating tier, application vertical, and end-user sophistication level. CAGRs were derived from elasticity-adjusted demand curves incorporating grid reliability indices and mining project pipeline data.
Currency fluctuation, regulatory timeline compression, and battery substitution acceleration are the dominant revision risks to forecast assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Europe Gas Turbine Market
Generators
Containerized Solar Generators Market
Generators
India Generator Sets Market
Generators
South America Generator Sets Market
Generators
Europe Gas Generator Market
Generators
Global Diesel Gensets Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Turbo Generator Market
Generators
Generator Sets Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Portugal Gas Generator Market
Generators
Halogenerator Market
Generators
Commercial Standby Generator Sets Market
Generators
Natural Gas Generator Market
Generators
Residential Generators Market
Generators
Africa Diesel Generator Market