
 Residential Generators Market | 2026-2036
Residential Generators Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Generators Market Outlook
Single-family home construction is broadening the addressable base for residential generators as builders pre-wire homes for standby systems in storm-belt counties. Generac Holdings dominates the North American standby segment through captive dealer networks and direct-to-consumer channels. Honda leverages its inverter-engine expertise to command premium pricing in the portable category for recreational and emergency use. Champion Power Equipment competes aggressively on value-engineered propane units sold through big-box retail.
A residential generator is an electromechanical device that converts chemical fuel energy into alternating-current electricity through an internal-combustion engine coupled to an alternator, typically producing 1 kW to 50 kW of continuous output for household loads. Its primary purpose is to provide autonomous backup power during utility grid failures, protecting critical circuits for refrigeration, medical equipment, HVAC, and sump pumps. Standby systems with automatic transfer switches capture the highest-margin installations, while portable gasoline units remain the largest volume segment despite shorter runtimes and higher noise levels. Inverter generators are gaining share among suburban buyers prioritizing clean power for electronics and fuel efficiency at partial load. Solar-hybrid configurations are emerging as a structural growth vector where net-metering policies and battery cost declines enable whole-home resilience without fossil-fuel dependence.
EPA Tier 4 final emissions standards for nonroad engines shape product development timelines and compliance costs for gasoline and diesel models sold in the United States. The California Air Resources Board imposes additional certification hurdles that effectively bifurcate national product portfolios. UL 2200 and NFPA 37 installation codes govern standby system safety and placement, creating barrier-to-entry for unlicensed installers and aftermarket competitors. Stakeholders must monitor state-level building code adoptions and utility interconnection rules that determine whether solar-integrated generators qualify for demand-response incentives or face net-billing restrictions.
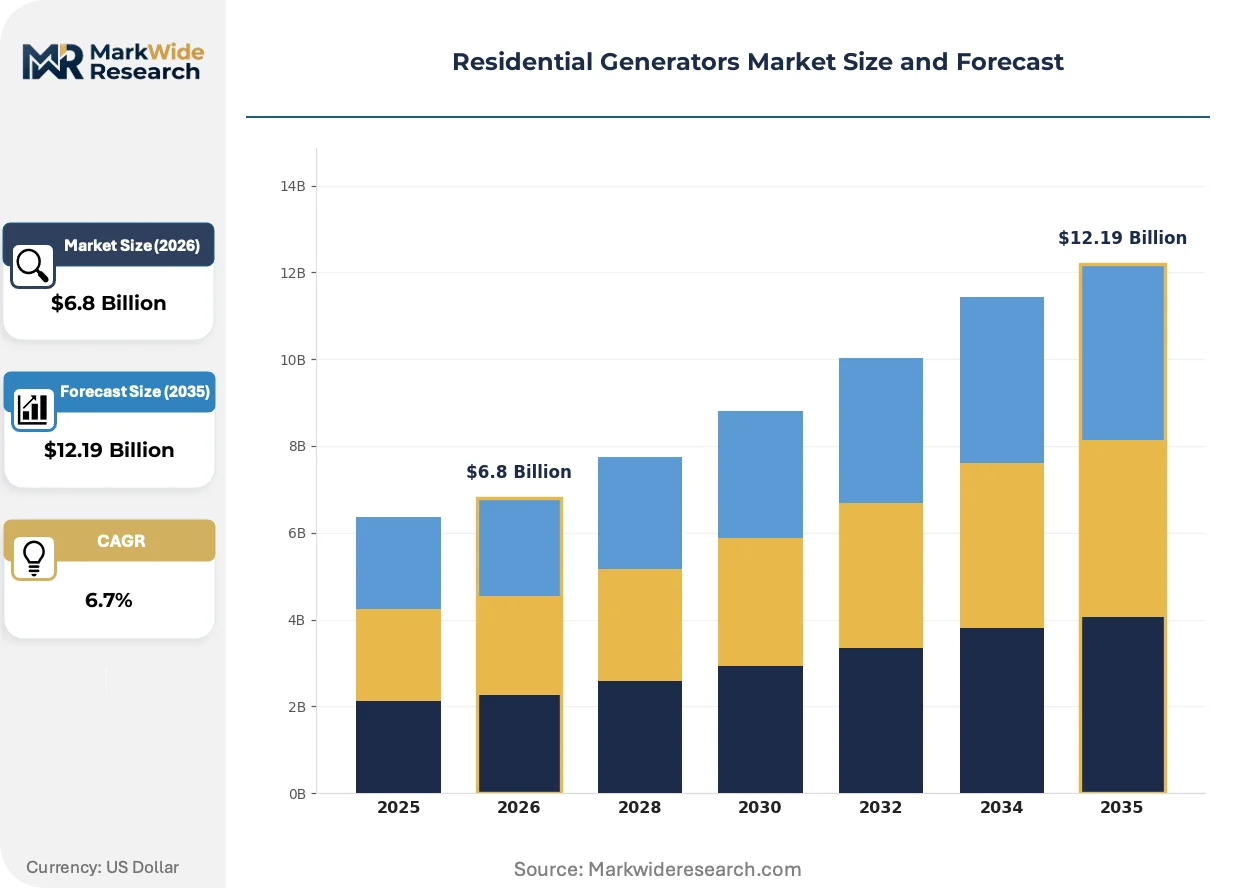
Market Dynamics
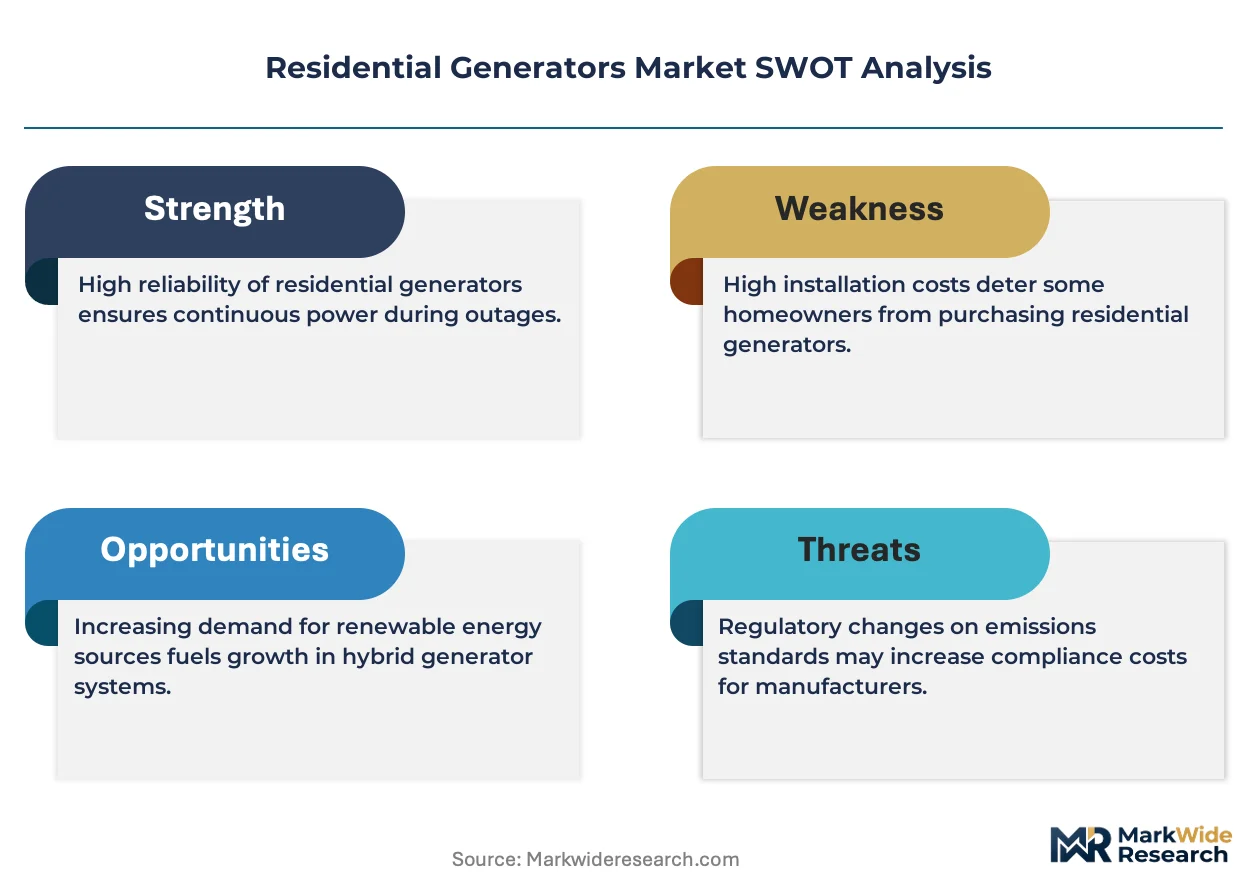
Grid instability across hurricane-prone coastal zones is compressing replacement cycles and forcing homeowners toward automatic standby systems with integrated transfer switches. This structural pressure is reshaping product mix away from portable gasoline units toward permanently installed propane and natural-gas configurations.
Growth Catalysts
- EPA Tier 4 Final Emissions Standards:Certification requirements for stationary engines are filtering out marginal suppliers and concentrating demand among compliant manufacturers with certified product portfolios.
- Medical Equipment Dependence:Home-based healthcare expansion is mandating uninterrupted power for oxygen concentrators and dialysis machines, elevating standby generators from convenience to clinical necessity.
- Southeastern United States Storm Belt:Grid infrastructure aging in Florida, Louisiana, and Texas is accelerating preemptive installations before hurricane season peaks.
Market Restraints
- Copper and Steel Input Volatility:Alternator windings and enclosure fabrication face commodity price swings that compress margin predictability for manufacturers.
- California Air Resources Board Certification:CARB's supplemental testing requirements bifurcate national product lines, forcing dual-SKU strategies that inflate inventory carrying costs.
- Solar-Plus-Storage Substitution:Declining lithium-ion battery costs and net-metering incentives are capturing resilience-seeking buyers who previously defaulted to fossil-fuel backup.
Strategic Opportunities
- Texas Hill Country and Panhandle:Underpenetrated rural electrification zones with frequent ice-storm outages represent whitespace for propane standby systems beyond traditional coastal markets.
- Smart Load Management Integration:Convergence of generator controllers with home energy management systems enables demand-responsive cycling that reduces fuel consumption during extended outages.
- IRA Residential Clean Energy Credits:Battery storage add-ons paired with solar-hybrid generators qualify for federal tax incentives, expanding addressable wallet share per installation.
Industry Challenges
- Licensed Electrician Scarcity:Automatic transfer switch installation requires certified contractors, and storm-season demand surges exhaust available technician capacity in affected counties.
- UL 2200 Certification Timelines:Safety testing protocols for standby alternators extend product launch windows, delaying revenue recognition for redesigned engine platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Generators Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Standby, Inverter, Solar Fuel Type: Gasoline, Propane, Diesel, Natural Gas Power Rating: 1-5 kW, 5-10 kW, 10-20 kW, 20-50 kW Installation Type: Permanent, Temporary, Mobile, Fixed |
| Companies Covered | Briggs & Stratton, Caterpillar, Generac Holdings, Westinghouse, Honda, Kohler, Champion Power Equipment, DuroMax, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Generators Market Strategic Shifts
Power electronics and connectivity modules are penetrating generator architectures at accelerating pace. These embedded capabilities are shifting competitive differentiation from raw kilowatt output toward intelligent load orchestration and remote monitoring services.
Inverter generator technology is rewriting the economics of partial-load operation. These systems modulate engine speed to match electrical demand rather than running at fixed RPM, delivering fuel efficiency gains that suburban buyers with sensitive electronics prioritize. The technology is compressing the traditional premium gap between portable and standby categories.
REACH restrictions on hazardous substances in electrical equipment are forcing enclosure and wiring harness redesigns across European-sourced components. Manufacturers serving multiple geographies must maintain parallel material specifications, complicating supply chain consolidation efforts. The regulatory friction is most acute for mid-tier producers without dedicated compliance teams.
Homebuilder pre-wiring partnerships are displacing aftermarket retrofit as the dominant standby generator acquisition channel. Production home developers in storm-belt counties now specify generator-ready electrical panels and concrete pads as standard features, capturing buyers before independent contractor relationships form. This channel rotation is most visible in Florida master-planned communities and Texas exurban subdivisions.
Residential Generators Market Segmentation
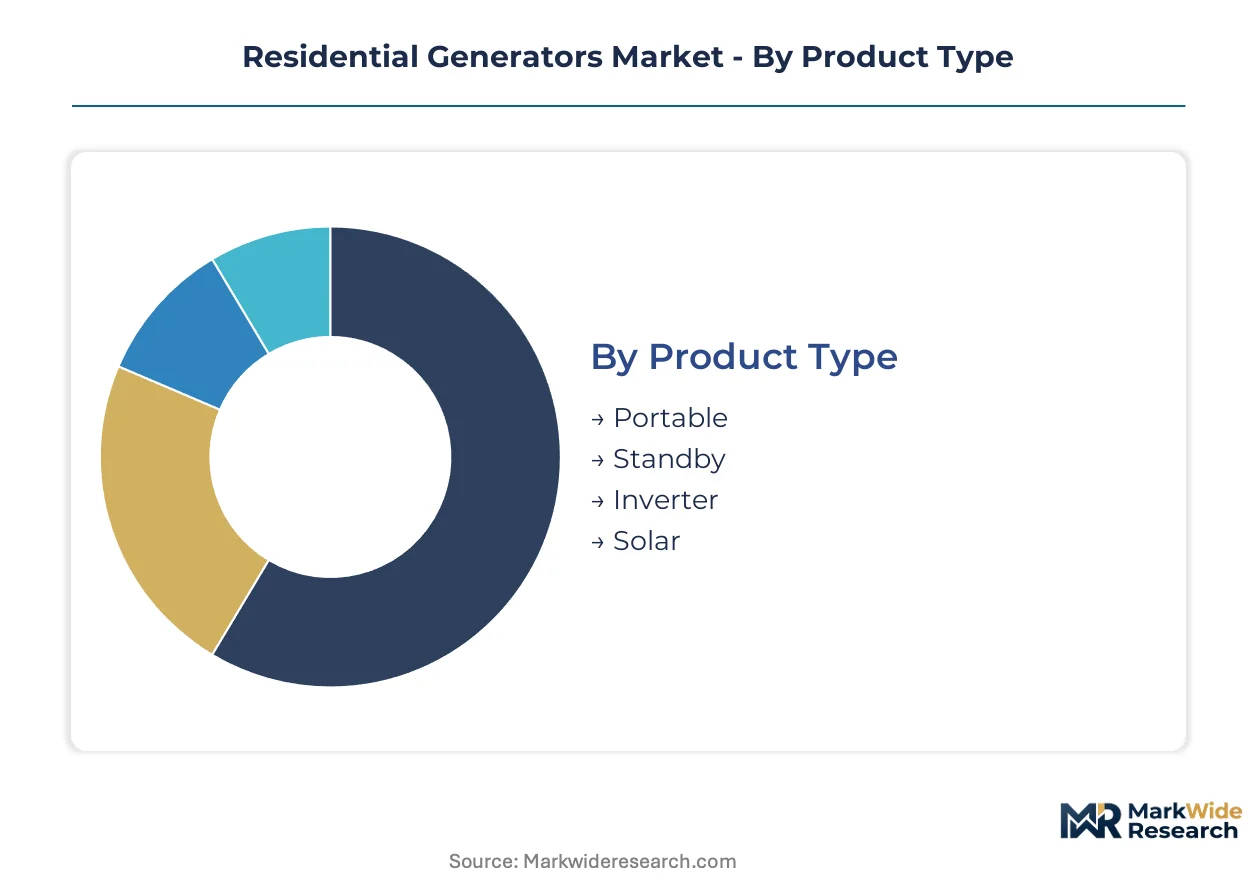
Segmentation in residential generators reveals how backup power solutions fragment across technical specifications, fuel infrastructure, and installation permanence. These divisions determine margin profiles, regulatory exposure, and channel strategy for manufacturers competing across storm-belt geographies.
Product Type:
Customization versus standardization spans a spectrum from mass-produced portable units to site-engineered standby systems with automatic transfer switches.
- Portable:Gasoline-powered units with manual startup dominate recreational and emergency use cases. Demand clusters in suburban households seeking intermittent backup for essential circuits during seasonal outages in Florida and Texas coastal counties, constrained by noise ordinances and fuel storage limitations.
- Standby:Permanently installed systems with automatic transfer switches deliver whole-home resilience through propane or natural gas connections. Hurricane-prone southeastern states drive replacement cycles as grid instability elevates these from convenience to infrastructure necessity.
- Inverter:Variable-speed engines modulate output to match electrical load, delivering clean power for sensitive electronics. Fuel efficiency gains attract suburban buyers with medical equipment and home office dependencies.
- Solar:Battery-integrated configurations paired with photovoltaic arrays eliminate fossil-fuel dependence where net-metering policies support whole-home resilience.
Most installed capacity flows through Standby systems. Expansion is steepest in Solar configurations as lithium-ion cost declines accelerate.
Fuel Type:
Cost tier stratification separates premium natural gas infrastructure from value-engineered gasoline alternatives, with diesel occupying specialized high-reliability niches.
- Gasoline:Lowest first-cost fuel dominates portable unit sales through big-box retail channels. Suburban homeowners in Texas and Louisiana purchase these for seasonal storm preparation despite shorter runtimes and storage safety constraints.
- Propane:Clean-burning fuel with indefinite shelf stability powers standby systems in rural electrification zones beyond natural gas pipeline reach. Texas Hill Country and Panhandle counties represent whitespace as ice-storm frequency rises.
- Diesel:High-torque engines deliver extended runtime reliability for agricultural and remote property applications. EPA Tier 4 certification costs limit this segment to commercial-grade residential installations.
- Natural Gas:Unlimited runtime through utility pipeline connections commands premium positioning in master-planned Florida communities where homebuilder pre-wiring partnerships dominate acquisition channels.
Natural Gas captures the highest-margin installations. Propane is gaining share fastest in underpenetrated rural markets lacking pipeline infrastructure.
Power Rating:
Application scope determines kilowatt specification, from single-circuit portable support to whole-home HVAC and medical equipment loads.
- 1-5 kW:Compact portable units address recreational camping and minimal emergency circuits. Weekend property owners in storm-belt counties purchase these for refrigeration and lighting backup.
- 5-10 kW:Mid-range standby systems cover essential household loads including sump pumps and medical devices. Home-based healthcare expansion elevates this specification to clinical necessity in Florida retirement communities.
- 10-20 kW:Whole-home coverage including central air conditioning dominates suburban single-family installations. Texas exurban subdivisions specify these as standard features in new construction.
- 20-50 kW:Estate-scale systems address large residences with multiple HVAC zones and pool equipment. High-net-worth coastal properties in Louisiana and Florida drive demand for this capacity tier.
10-20 kW ratings absorb the majority of new standby installations. 5-10 kW systems are expanding most quickly as medical equipment dependence broadens the addressable base.
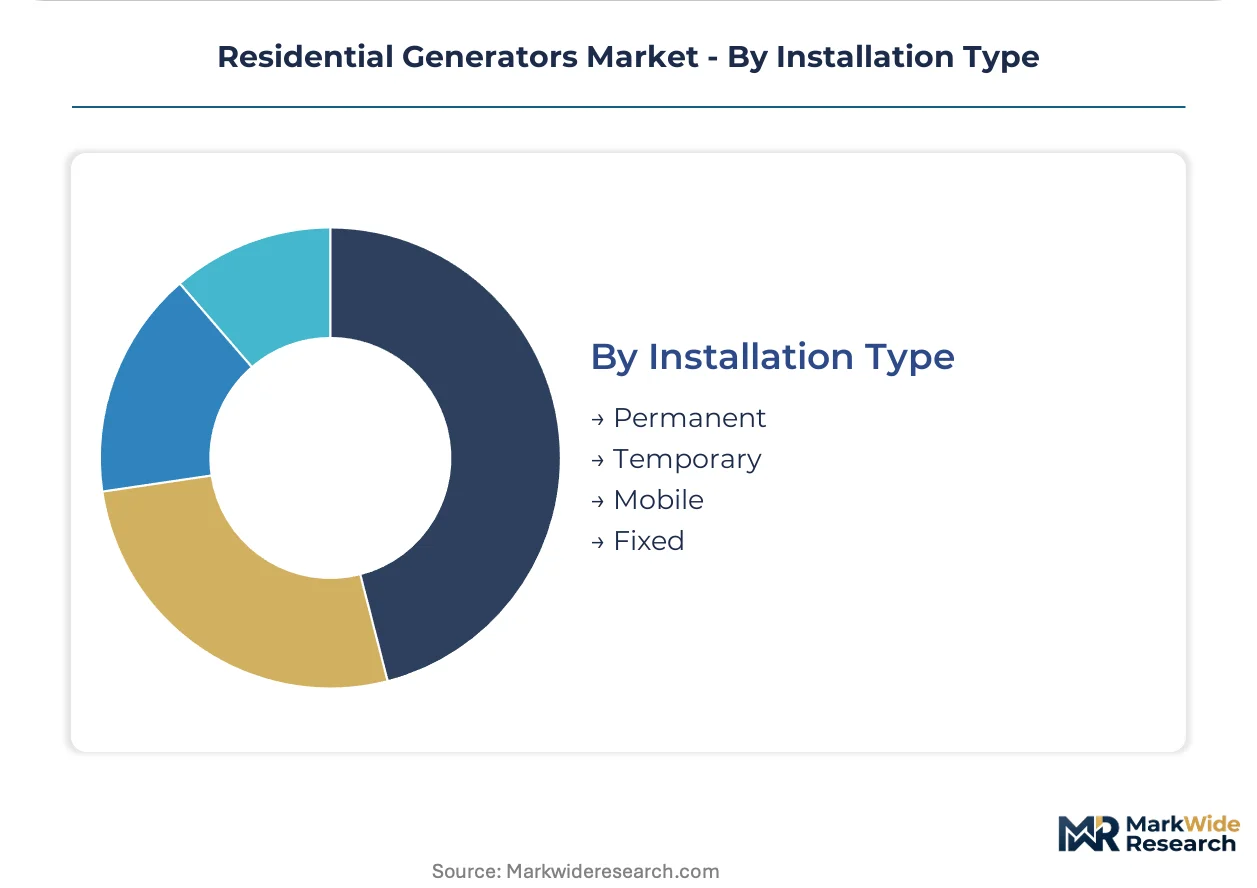
Installation Type:
Permanence correlates directly with customer lifetime value and service attachment rates across the ownership cycle.
- Permanent:Concrete pad-mounted standby systems with automatic transfer switches generate recurring maintenance revenue. Florida homebuilder partnerships now specify these pre-construction.
- Temporary:Rental and lease arrangements serve seasonal residents and construction sites. Gulf Coast vacation property markets sustain this channel.
- Mobile:Trailer-mounted commercial-grade units address agricultural and estate-scale residential applications. Texas ranch properties utilize these for workshop and outbuilding power.
- Fixed:Hardwired portable installations with manual transfer switches occupy a mid-market position for cost-conscious homeowners seeking upgrade pathways.
Permanent installations command the highest service contract attachment. Temporary arrangements are climbing fastest as storm-season rental demand surges exceed technician installation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are reshaping production footprints as manufacturers seek compliance cost advantages. EPA Tier 4 certification expenses in the United States push value-engineered assembly toward Mexico, while European REACH restrictions on hazardous substances redirect component sourcing to Asian suppliers with parallel specification capabilities.
United States
Hurricane-prone coastal zones from Florida to Texas drive standby generator installations as grid instability elevates backup power to infrastructure necessity. EPA Tier 4 final emissions standards filter marginal suppliers and concentrate demand among certified manufacturers with compliant stationary engine portfolios. Southeast master-planned communities now specify generator-ready electrical panels as standard construction features.
Canada
Rural electrification gaps and ice-storm vulnerability in Ontario and Quebec sustain demand for propane standby systems beyond natural gas pipeline reach. Health Canada and PMRA oversee product safety certification parallel to UL standards, creating streamlined cross-border approval pathways for US manufacturers. Prairie provinces utilize mobile trailer-mounted units for agricultural estate applications.
Mexico
Manufacturing cost advantages attract assembly operations for gasoline portable units serving North American big-box retail channels. Mexican regulatory frameworks for stationary engines remain less stringent than EPA Tier 4 requirements, enabling competitive positioning for value-engineered product lines. Monterrey and Tijuana industrial corridors host contract manufacturing for US-branded portable generators.
Germany
REACH restrictions on hazardous substances in electrical equipment force enclosure and wiring harness redesigns across European-sourced components. ECHA compliance requirements complicate supply chain consolidation for manufacturers serving multiple geographies. Bavaria and Baden-Württemberg industrial clusters specialize in precision alternator components and inverter control systems.
China
Component manufacturing concentration for alternator windings and power electronics modules supplies global generator assembly networks. GB standards and MIIT oversight govern domestic product certification, with export-oriented production aligned to EPA and CARB requirements for North American market access. Yangtze River Delta manufacturing hubs produce engine control units and connectivity modules.
Residential Generators Market Competitive Environment
Strategic partnerships dominate the current landscape as manufacturers seek technology convergence with home energy management and solar-hybrid systems. The vendor base stratifies across three tiers: integrated power equipment conglomerates with captive engine foundries, specialized standby system assemblers with dealer network lock-in, and value-engineered portable specialists leveraging contract manufacturing. Capacity expansion and portfolio diversification represent the dominant competitive moves as participants address solar-plus-storage substitution threats.
Within the integrated power equipment tier, Generac Holdings and Cummins exemplify archetypes with comprehensive stationary engine capabilities and service infrastructure depth. Honda occupies a position representing premium inverter-engine expertise for portable applications. Champion Power Equipment anchors the value-engineered segment with aggressive propane unit positioning through mass retail channels.
| Leading Market Players |
|---|
| Briggs & Stratton |
| Caterpillar |
| Generac Holdings |
| Westinghouse |
| Honda |
| Kohler |
| Champion Power Equipment |
| DuroMax |
| Cummins |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EPA Tier 4 compliant standby systems and portable gasoline units manifests in both margin structures and sourcing complexity. Premium natural gas installations command substantial installation bundling value, while commodity portable units face relentless cost engineering pressure that reshapes component procurement strategies across Asian assembly networks.
Pricing Analysis
Distributor margin layers absorb 25-35 points between factory gate and homeowner installation, with captive dealer networks extracting premium service attachment. Three-tier pricing structure separates UL 2200 certified standby systems from CARB-compliant portable units from economy gasoline models lacking emissions certification. Price differentiation rests on automatic transfer switch integration and remote monitoring capability, not raw kilowatt output alone. Cost compression in the portable segment intensifies as big-box retail buyers consolidate purchase volumes, while standby pricing holds firmer due to licensed electrician scarcity constraining installation capacity.
Supply Chain Analysis
Domestic-content thresholds in Buy American provisions for federal disaster relief procurement are redirecting alternator winding and enclosure fabrication toward US-based metalworking shops. Engine block casting concentrates in China and Mexico, with precision alternator components sourced from Germany and Japan. Copper magnet wire and steel enclosures represent 40-50 percent of bill-of-materials exposure, tethering margins to London Metal Exchange volatility. Single-source vulnerability runs through Yangtze River Delta engine control unit suppliers, where semiconductor content creates chokepoint risk. Distribution runs through big-box retail for portable units and captive dealer networks for standby installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The residential generators market compounds steadily as climate-driven grid instability elevates backup power from discretionary purchase to household infrastructure necessity.
For Market Incumbents: To counter solar-plus-storage substitution, deepen captive dealer network lock-in through predictive maintenance subscriptions and smart load management integration. Prioritize backward integration into alternator winding and engine control unit production to buffer commodity volatility and secure EPA Tier 4 certification timelines against supply disruption. For New Entrants and Emerging Players: Rural propane-dependent households in Texas Hill Country and Panhandle counties represent the most penetrable buyer archetype, lacking natural gas pipeline access and facing rising ice-storm frequency. Target homebuilder pre-wiring partnerships in Florida master-planned communities before independent contractor relationships solidify, positioning inverter-generator expertise as a bridge technology toward eventual solar-hybrid conversion. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier assemblers lack captive engine foundries and struggle with dual-SKU inventory costs from CARB bifurcation. The five-to-ten year viability window favors platforms with UL 2200 certification depth and service infrastructure density. Watch battery cost decline curves and net-metering policy stability as the primary signal for fossil-fuel backup displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Load Management Integration | Convergence with home energy management systems reduces fuel consumption during extended outages. |
| Propane Standby System Expansion | Texas Hill Country and Panhandle whitespace captures rural electrification gaps beyond pipeline reach. |
| Solar-Hybrid Generator Development | IRA Residential Clean Energy Credits expand addressable wallet share per installation through battery pairing. |
| Dealer Network Capacity Buildout | Licensed electrician scarcity in storm-belt counties constrains installation throughput and captures margin. |
| EPA Tier 4 Certification Investment | Emissions compliance filters marginal suppliers and concentrates demand among certified manufacturers. |
Study Parameters
Direct dialogue with standby system installers, portable equipment distributors, homebuilder procurement directors, and EPA certification engineers grounded the qualitative foundation. Secondary validation drew from EIA grid reliability data, UL certification registries, FEMA disaster relief procurement records, and SEC filings from publicly traded power equipment manufacturers. Bottom-up and top-down triangulation cross-checked channel shipment estimates against residential construction permits and storm-loss insurance claims.
Bottom-up modeling built from unit economics across product type, fuel configuration, power rating, and installation permanence segments, then aggregated to market totals. Top-down validation triangulated against macro indicators including grid outage frequency indices, residential construction spending, and commodity price trajectories. CAGRs were derived from segment-level growth rate differentials applied across the projection horizon. Forecast inputs incorporated EPA regulatory timelines, lithium-ion battery cost curves, and state-level net-metering policy trajectories.
Underlying measurement precision varies by segment; standby system installations with automatic transfer switches carry tighter precision than portable unit retail sales given channel consolidation. Forecasts reflect documented assumptions regarding regulatory enforcement timing and battery substitution elasticity. Hurricane frequency variability and copper price volatility represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
India Diesel Generator Market
Generators
North West Europe Diesel Generator Market
Generators
China Diesel Generator Market
Generators
Tri Fuel Generators Market
Generators
Saudi Arabia Diesel Generator Market
Generators
Power Generator for Military Market
Generators
Construction Prime Power Generators Market
Generators
Asia Pacific Electric Generators Market
Generators
Dual-Fuel Generator Market
Generators
East Africa Diesel Generator Market
Generators
Commercial Generator Market
Generators
United States Diesel Generator Market
Generators
Onboard Marine Gensets Market
Generators
Europe Turbo Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Africa Diesel Generator Market