
 Gulf Cooperation Council (GCC) Diesel Generator Market | 2026-2036
Gulf Cooperation Council (GCC) Diesel Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Gulf Cooperation Council (GCC) Diesel Generator Market Insights
ISO 8528-1 load acceptance criteria is reorganizing supplier qualification across the GCC, forcing distributors to recalibrate test protocols before customs release. Caterpillar Inc leverages its regional parts depot network to sustain uptime commitments for oil field operators. Jubaili Bros anchors its position through localized assembly operations in the UAE and Saudi Arabia. Kirloskar Oil Engines Ltd competes on compact footprint designs suited for urban telecom shelters where space constraints dominate.
Gulf Cooperation Council diesel generators are internal combustion engine systems that convert diesel fuel into electrical energy through reciprocating piston action, typically operating at 50 Hz with voltage outputs of 220-415 V for commercial and industrial applications. Standby generators command the largest installed base across healthcare and data center installations where regulatory uptime mandates create resilient demand pools. Prime generators serving remote oil and gas wellheads represent the fastest-expanding category as marginal field development accelerates across Saudi Arabia and Kuwait. Above 500 kVA units concentrate margin capture due to custom engineering requirements and limited certified service networks.
SASO efficiency regulations and UAE's Ministry of Energy and Infrastructure emission benchmarks shape product homologation timelines, while Gulf Standardization Organization (GSO) conformity certificates gate market entry for non-regional manufacturers. These frameworks elevate total cost of ownership calculations and favor suppliers with in-country technical support infrastructure. Stakeholders must monitor how carbon intensity disclosure requirements from EU-linked trade partners propagate into procurement specifications for GCC-linked contractors.
Market Dynamics
ISO 8528-1 load acceptance criteria is reorganizing supplier qualification across the GCC, forcing distributors to recalibrate test protocols before customs release. This technical mandate compresses homologation timelines and elevates capital requirements for market entry.
Growth Catalysts
- Data center construction:Cloud computing expansion across Saudi Arabia's Riyadh and Jeddah corridor sustains standby generator procurement for hyperscale facilities requiring 99.999% uptime guarantees.
- SASO efficiency mandates:Tightening emission thresholds for imported generator sets are accelerating fleet replacement cycles among commercial operators seeking import clearance.
- Marginal oil field development:Remote wellhead electrification in Kuwait and Saudi Arabia's Eastern Province drives prime generator deployment for drilling and artificial lift operations.
Market Restraints
- Steel and copper price volatility:Alternator winding materials and enclosure-grade steel subject generator OEMs to input cost swings that compress margin buffers on fixed-price contracts.
- Service network concentration:Above 500 kVA unit maintenance depends on a thin layer of certified technicians concentrated in Dubai and Dammam, creating geographic coverage gaps.
- Grid extension programs:Saudi Arabia's National Renewable Energy Program and UAE utility expansion threaten remote-site diesel dependence by bringing centralized power to previously off-grid industrial zones.
Strategic Opportunities
- Bahrain telecom infrastructure:5G network densification creates shelter-grade generator demand for base transceiver stations in Manama's urban corridors where footprint constraints dominate.
- GSO conformity acceleration:Gulf Standardization Organization mutual recognition agreements enable single-test market access across all six member states, reducing duplicate certification costs.
- Hybrid diesel-solar integration:Converging photovoltaic inverters with traditional generator controls opens microgrid opportunities for islanded industrial facilities in Oman's interior.
Industry Challenges
- Technician certification pipelines:Factory-authorized service training for electronic engine management systems remains underdeveloped across GCC technical institutes, extending repair turnaround times.
- Legacy control system integration:SCADA retrofit requirements for existing generator fleets in Qatar's liquefied natural gas facilities create commissioning complexity and downtime risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gulf Cooperation Council (GCC) Diesel Generator Market |
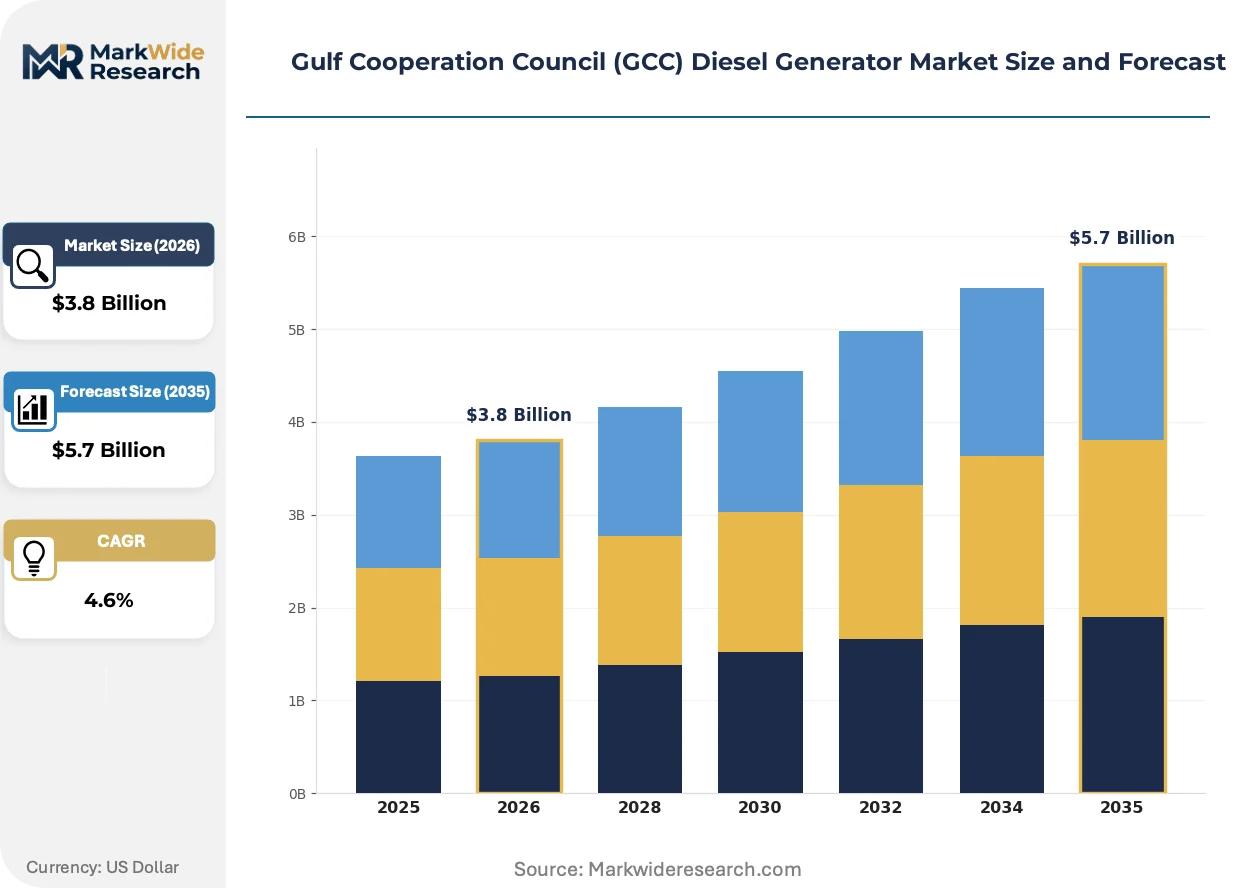
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standby Generators, Prime Generators, Portable Generators, Industrial Generators Power Rating: Up to 100 kVA, 100-300 kVA, 300-500 kVA, Above 500 kVA End User: Construction, Telecommunications, Healthcare, Oil & Gas Installation: On-site, Off-site, Mobile, Fixed |
| Companies Covered | Atlas Copco AB, Caterpillar Inc, Cummins Inc, Generac Power Systems Inc, Kohler Co, Jubaili Bros, Kirloskar Oil Engines Ltd, Mitsubishi Heavy Industries Ltd, Perkins Engines Company Ltd, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gulf Cooperation Council (GCC) Diesel Generator Market Trends and Innovations
Digital load management and emission control technologies are compressing the traditional trade-off between generator footprint and performance output across GCC installations. These shifts favor suppliers with embedded electronics capabilities over pure mechanical specialists.
Containerized generator enclosures with integrated fuel polishing and heat recovery systems are miniaturizing backup power infrastructure for urban data centers. Dubai-based colocation operators deploy these units in constrained substation yards where every square meter carries lease cost implications. The technology is compressing project civil works budgets and accelerating deployment schedules for facilities requiring sub-90-day commissioning.
SASO's implementation of EU-linked carbon intensity disclosure requirements for imported equipment is tightening product documentation standards. Industrial buyers in Saudi Arabia now require scope-three emissions data from generator suppliers to satisfy contractor procurement specifications. The policy most affects rental fleet operators serving gigaproject sites where European EPC contractors enforce sustainability clauses.
After-sales service unbundling is fragmenting traditional OEM-captive maintenance relationships. Independent service providers in the UAE now offer hourly-rate overhaul contracts for Caterpillar and Cummins engines, displacing long-term service agreements. This shift concentrates in Abu Dhabi's oil field services sector where procurement teams prioritize operational expenditure flexibility over capitalized maintenance reserves.
Gulf Cooperation Council (GCC) Diesel Generator Market Segmentation
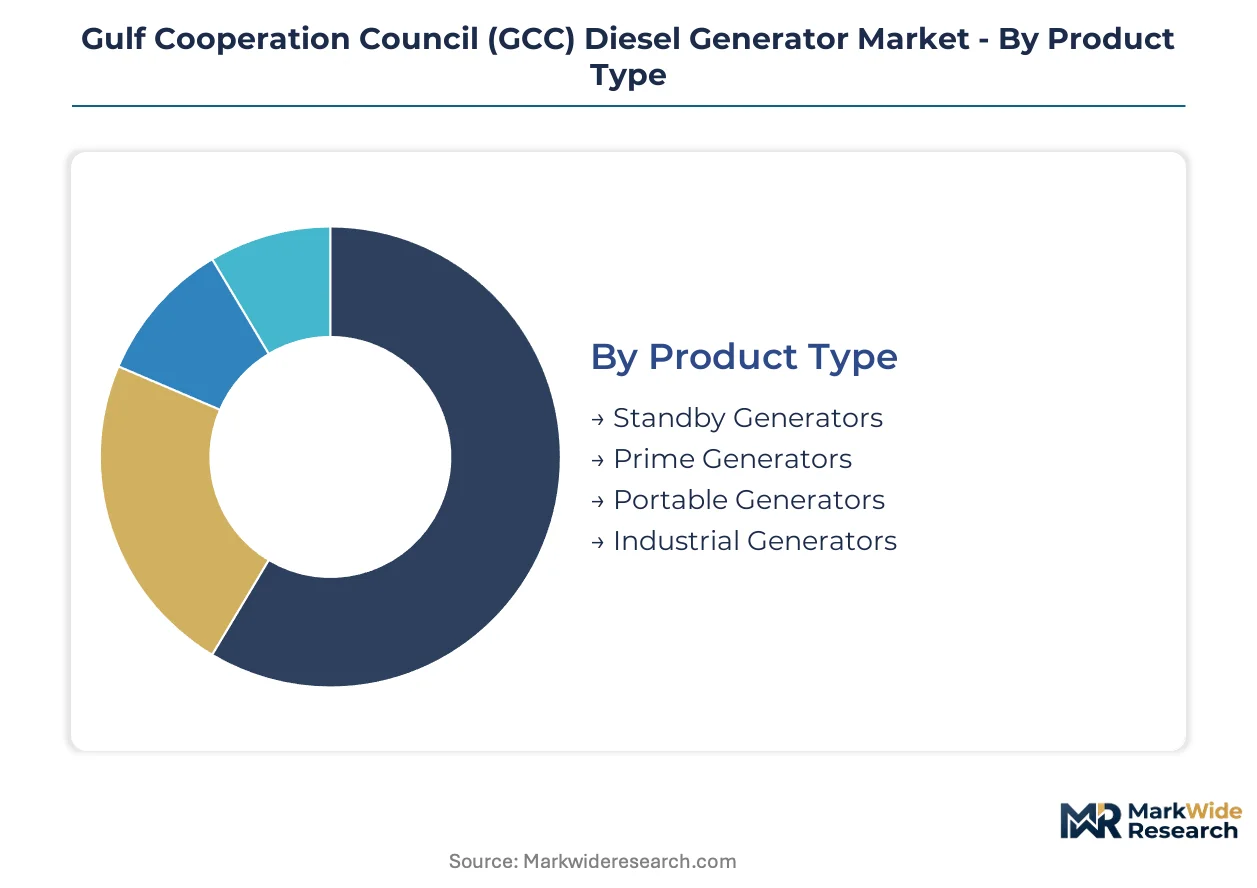
Segmentation in the GCC diesel generator market reveals how regulatory mandates and infrastructure buildouts concentrate procurement across distinct technical specifications. Each dimension carries divergent margin profiles and substitute pressures that reshape supplier positioning across Saudi Arabia, the UAE, and neighboring states.
Product Type:
Standby generators face the strongest substitution threat from battery energy storage systems in data center applications, while prime generators serving remote oil fields remain insulated from grid alternatives.
- Standby Generators:Engine systems designed for emergency power delivery within 10 seconds of grid failure, operating at partial load for limited annual hours. Demand concentrates in Riyadh's hyperscale data centers where SASO mandates 99.999% uptime guarantees for critical digital infrastructure.
- Prime Generators:Continuous-duty units engineered for sustained operation as the primary power source, typically deployed at 70-100% rated load. Remote wellhead electrification across Kuwait's Burgan field and Saudi Arabia's Empty Quarter drives fleet expansion as marginal oil development accelerates.
- Portable Generators:Trailer-mounted or skid-based units below 150 kVA for temporary construction and event power.
- Industrial Generators:Heavy-duty stationary systems with extended maintenance intervals for manufacturing and processing facilities.
Standby generators anchor the volume base while prime generators gain share at the steepest rate.
Power Rating:
Cost tier stratification separates commodity procurement in the sub-100 kVA band from engineered solutions above 500 kVA where service network scarcity elevates supplier power.
- Up to 100 kVA:Compact single-phase or three-phase units for residential backup and small commercial premises. Bahrain's 5G shelter densification and Qatar's retail mall construction sustain import volumes despite thin margins.
- 100-300 kVA:Mid-range three-phase systems balancing footprint constraints with load coverage for mid-tier healthcare clinics and educational facilities.
- 300-500 kVA:Transition-class units bridging commercial and industrial applications with enhanced voltage regulation.
- Above 500 kVA:Custom-engineered low-speed engines with dedicated fuel systems and synchronized paralleling controls. Jeddah's gigaproject construction sites and Dubai's district cooling plants concentrate procurement where factory-authorized technicians in Dammam and Dubai command premium service rates.
Above 500 kVA units capture the highest margin pool while up to 100 kVA segments expand most quickly through telecom infrastructure rollout.
End User:
Application-specific duty cycles and regulatory exposure create divergent replacement rhythms across verticals, with healthcare and oil & gas presenting the most resilient demand profiles.
- Construction:Rental fleet deployment for temporary power at gigaproject sites with high equipment utilization rates and rapid depreciation schedules.
- Telecommunications:Shelter-grade units for base transceiver stations requiring 24/7 availability with minimal site visits. Manama's urban 5G corridors and Riyadh's suburban macro towers concentrate demand where footprint constraints favor compact canopy designs.
- Healthcare:Life-safety certified systems with automatic transfer switches and NFPA 110 compliance for hospitals and surgical centers. Dubai's medical city expansion and Saudi Arabia's healthcare privatization sustain procurement despite solar-battery hybrid encroachment on non-critical loads.
- Oil & Gas:Explosion-proof enclosures and rig-rated packages for drilling, well testing, and artificial lift operations in Kuwait's northern fields and Oman's Block 6 developments.
Oil & gas anchors the volume base while telecommunications gains share fastest through network densification mandates.
Installation:
Customer type differentiation separates capital-expenditure buyers seeking permanent infrastructure from operational-expenditure renters prioritizing fleet flexibility and rapid redeployment.
- On-site:Permanent civil works with concrete pads, fuel tanks, and exhaust systems integrated into building infrastructure. Saudi Arabia's NEOM and Red Sea Project developments drive specification-heavy procurement with extended warranty requirements.
- Off-site:Modular power plants and rental yard staging areas serving multiple concurrent projects.
- Mobile:Rapid-deployment trailer units for emergency response and seasonal demand spikes.
- Fixed:Stationary installations with hard-piped fuel delivery and automated building management system integration for Qatar's liquefied natural gas facilities and Abu Dhabi's industrial free zones.
Fixed installations anchor the volume base while mobile configurations climb the fastest through emergency preparedness programs and rental fleet modernization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes concentrate around oil field operators, data center developers, and gigaproject construction consortia, each demanding divergent service response times and certification standards across the six member states.
Saudi Arabia
NEOM and Red Sea Project developments sustain procurement of above 500 kVA fixed installations with extended warranty requirements. SASO efficiency mandates tighten emission thresholds for imported generator sets, compressing homologation timelines. Riyadh and Jeddah corridor data centers anchor standby generator demand as hyperscale facilities require 99.999% uptime guarantees.
United Arab Emirates
Dubai's district cooling plants and colocation operators deploy containerized generator enclosures in constrained substation yards. Ministry of Energy and Infrastructure emission benchmarks shape product homologation timelines alongside GSO conformity certificates. Abu Dhabi's oil field services sector drives after-sales service unbundling as procurement teams prioritize operational expenditure flexibility.
Kuwait
Marginal field development across the Burgan field accelerates prime generator deployment for drilling and artificial lift operations. The country's national energy regulator enforces grid interconnection standards that affect remote-site power planning. Northern oil field industrial zones concentrate demand for explosion-proof enclosures and rig-rated packages.
Qatar
Liquefied natural gas facilities drive fixed installation procurement with SCADA retrofit requirements for existing generator fleets. Healthcare privatization sustains life-safety certified system demand despite solar-battery hybrid encroachment on non-critical loads. Doha's medical city expansion and industrial free zones anchor mid-range three-phase system deployments.
Oman
Block 6 developments and interior islanded industrial facilities create hybrid diesel-solar microgrid opportunities converging photovoltaic inverters with traditional generator controls. The Sultanate's rural electrification programs threaten remote-site diesel dependence in previously off-grid zones. Muscat's telecom infrastructure densification sustains shelter-grade compact canopy designs for 5G base transceiver stations.
Gulf Cooperation Council (GCC) Diesel Generator Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive engine technology and regional assembly operations. Market structure concentrates margin capture above 500 kVA where certified service network scarcity elevates supplier power. Three archetypes dominate: global OEMs with regional parts depot networks, localized assemblers leveraging in-country technical support infrastructure, and compact footprint specialists serving space-constrained urban applications. Competitive moves center on GSO conformity acceleration to reduce duplicate certification costs and hybrid system integration to capture microgrid opportunities.
Within the global OEM tier, Caterpillar Inc and Cummins Inc exemplify scale-driven players with extensive regional service infrastructure. Jubaili Bros anchors the localized assembler archetype through UAE and Saudi Arabia assembly operations. Kirloskar Oil Engines Ltd occupies a position among compact footprint specialists targeting urban telecom shelters where space constraints dominate procurement specifications.
| Leading Market Players |
|---|
| Atlas Copco AB |
| Caterpillar Inc |
| Cummins Inc |
| Generac Power Systems Inc |
| Kohler Co |
| Jubaili Bros |
| Kirloskar Oil Engines Ltd |
| Mitsubishi Heavy Industries Ltd |
| Perkins Engines Company Ltd |
| Others |
Pricing and Supply Chain Analysis
SASO efficiency certification gates both supplier qualification and price differentiation across the GCC diesel generator market, compressing homologation timelines while elevating capital requirements that filter out marginal competitors. This regulatory framework concentrates pricing power among distributors with in-country testing infrastructure, forcing buyers to absorb premium tiers for rapid customs clearance.
Pricing Analysis
Cost-plus contracts with steel and copper indexation dominate procurement for above 500 kVA units, insulating OEMs from raw material volatility while exposing mid-tier buyers to pass-through clauses. Price differentiation rests on ISO 8528-1 test protocol completion speed and factory-authorized technician availability. Cost compression in the sub-100 kVA segment intensifies as Chinese manufacturers bypass traditional distribution layers. Rental fleet operators serving gigaproject sites exhibit highest price sensitivity due to depreciation pressures, while healthcare facilities prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability fluctuations on Asia-Gulf trade lanes extend inbound logistics cycles for alternator windings and electronic engine management modules. Manufacturing concentration clusters in China, India, and Germany for prime mover engines, while enclosure-grade steel feeds from Turkish and South Korean mills. Single-source vulnerability concentrates in high-horsepower crankshaft forgings from European specialist foundries. Distribution runs through Dubai-based parts depots serving field service networks across Dammam, Riyadh, and Kuwait City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC diesel generator market represents an early-cycle expansion story, with data center construction and marginal oil field electrification sustaining procurement velocity ahead of grid extension timelines.
For Market Incumbents: Compound service network density in Dammam and Dubai to defend against independent hourly-rate overhaul providers displacing long-term maintenance agreements. Extend factory-authorized technician certification pipelines through technical institute partnerships in Saudi Arabia. Secure GSO conformity acceleration to reduce duplicate testing costs across all six member states. For New Entrants and Emerging Players: Differentiate on hybrid diesel-solar integration capabilities for Oman's islanded industrial facilities, where photovoltaic inverter convergence with generator controls remains undersupplied. Target Bahrain's 5G shelter densification corridor with compact canopy designs under 100 kVA. Pursue direct EPC contractor relationships to bypass incumbent distributor margins on NEOM and Red Sea Project sites. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across above 500 kVA custom engineering segments due to extended warranty requirements and SCADA integration complexity. Acquisition targets should display captive in-country assembly operations with SASO pre-certification capabilities. Monitor Saudi Arabia's National Renewable Energy Program grid extension announcements as inflection indicators for remote-site diesel demand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| GSO Conformity Acceleration | Single-test market access across all six GCC member states reduces homologation costs for non-regional manufacturers. |
| Hybrid System Integration | Converging photovoltaic inverters with generator controls captures microgrid opportunities in Oman's interior facilities. |
| Service Network Densification | Factory-authorized technician expansion in Dammam and Dubai addresses geographic coverage gaps for above 500 kVA maintenance. |
| Containerized Enclosure Deployment | Miniaturized backup power infrastructure compresses civil works budgets for Dubai colocation operators in constrained substation yards. |
| Technician Certification Pipeline | Technical institute partnerships in Saudi Arabia extend electronic engine management repair capabilities and reduce turnaround times. |
Research Methodology
Initial hypotheses were tested against primary input from data center engineering directors, oil field services procurement managers, EPC contractor equipment specialists, and rental fleet operations heads, then refined through secondary validation. Primary fieldwork combined structured interviews with maintenance technicians at Dammam and Dubai service depots alongside facility assessments at Riyadh hyperscale data centers and Kuwait's Burgan field installations. Secondary sources encompassed SASO technical regulations, GSO conformity certificate databases, customs import manifests for generator sets, and EPC contractor sustainability disclosure filings. Bottom-up unit deployment estimates were triangulated against top-down energy demand projections for off-grid industrial zones.
Variance decomposition across product type, power rating tier, end-use vertical, and installation mode anchored the analytical framework over the projection horizon. Segmentation modeling incorporated duty cycle patterns, regulatory compliance tiers, and service network proximity as demand determinants. CAGRs were derived from installed base growth rates net of retirement schedules and substitution effects. Forecast inputs included gigaproject construction timelines from Saudi Arabia's Public Investment Fund disclosures and 5G base transceiver station rollout plans from Bahrain's Telecommunications Regulatory Authority.
Material uncertainties — steel and copper price volatility, grid extension program acceleration, and EU-linked carbon intensity disclosure propagation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding SASO enforcement consistency and GSO mutual recognition agreement stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
Africa Portable Generator Market
Generators
India Generator Sets Market
Generators
Military Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Commercial Standby Generator Sets Market
Generators
Telecom Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Asia Pacific Electric Generators Market
Generators
Halogenerator Market
Generators
Kuwait Diesel Gensets Market
Generators
Commercial Generator Market
Generators
Onboard Marine Gensets Market
Generators
Asia-Pacific Generator Sets Market
Generators
South Africa Diesel Generator Market
Generators
Generator Sales Market
Generators
Europe Turbo Generator Market