
 Bifacial Solar Cells Market | 2026-2036
Bifacial Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Bifacial Solar Cells Market Insights
China is narrowing its cost advantage in bifacial cell manufacturing as Southeast Asian nations scale PERC and TOPCon capacity. LONGi sustains technology leadership through in-house wafer-to-module integration and aggressive R&D spending on heterojunction architectures. Trinasolar leverages its Vertex platform to dominate utility-scale tenders across emerging markets. Jinko Solar anchors global shipment volumes with manufacturing footprints spanning Malaysia, Vietnam, and the United States.
Bifacial solar cells capture photons from both front and rear surfaces using transparent backsheet or dual-glass encapsulation, with rear-side gain typically adding 5-30% energy yield depending on albedo and installation geometry. Monocrystalline silicon dominates product type segmentation due to superior conversion efficiency and compatibility with passivated contact architectures. Heterojunction technology represents the fastest-growing product category as manufacturers target efficiency thresholds above 24% with lower temperature coefficients. Utility-scale application leads absolute volume, though floating installations on reservoirs and coastal sites command premium pricing for specialized frame and encapsulant requirements.
China's MIIT enforces GB standards for bifacial module certification and performance testing, while the EU F-Gas Regulation and CE marking requirements shape import compliance for European project developers. India's BIS mandates local testing protocols under its solar photovoltaic product order, creating non-tariff barriers for non-compliant suppliers. Saudi Arabia's national renewable program and associated local content rules are redirecting supply chain investments toward Red Sea manufacturing zones. Stakeholders must monitor evolving anti-circumvention investigations and domestic content thresholds across multiple jurisdictions to protect market access.
Market Dynamics
Passivated contact architectures are compressing manufacturing cost curves while heterojunction cell efficiency thresholds above 24% reset competitive benchmarks across utility-scale procurement.
Growth Catalysts
- Dual carbon goals:China's MIIT enforcement of updated grid interconnection standards accelerates domestic deployment of high-efficiency bifacial arrays.
- Desert solar parks:Utility-scale developers in Saudi Arabia and the UAE are expanding procurement across gigawatt-scale renewable tenders with premium albedo conditions.
- Albedo optimization:Rear-side gain capture of 5-30% energy yield depending on installation geometry improves project IRRs for floating reservoir installations.
Market Restraints
- Polysilicon price volatility:Input cost swings for metallurgical-grade silicon concentrate margin pressure across PERC and TOPCon production lines.
- Southeast Asian supply concentration:Malaysia and Vietnam now host dominant PERC and TOPCon capacity, creating single-point-of-failure exposure for non-Chinese buyers.
- CE marking friction:EU F-Gas Regulation compliance timelines extend certification cycles for dual-glass encapsulation imports.
Strategic Opportunities
- Red Sea manufacturing zones:Saudi Arabia's local content rules redirect supply chain investments toward captive module assembly serving MENA utility tenders.
- Floating solar specialization:Coastal reservoir applications command premium pricing for corrosion-resistant frame architectures and marine-grade encapsulants.
- India's PLI scheme:Production-linked incentives for domestic cell and module manufacturing create tariff-advantaged supply for BIS-compliant project developers.
Industry Challenges
- Anti-circumvention investigations:US Commerce Department probes into Southeast Asian origin claims force supply chain reconfiguration and documentation overhead.
- Heterojunction equipment capex:PECVD toolsets for passivated contact deposition require 40-60% higher upfront investment versus legacy diffusion furnaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bifacial Solar Cells Market |
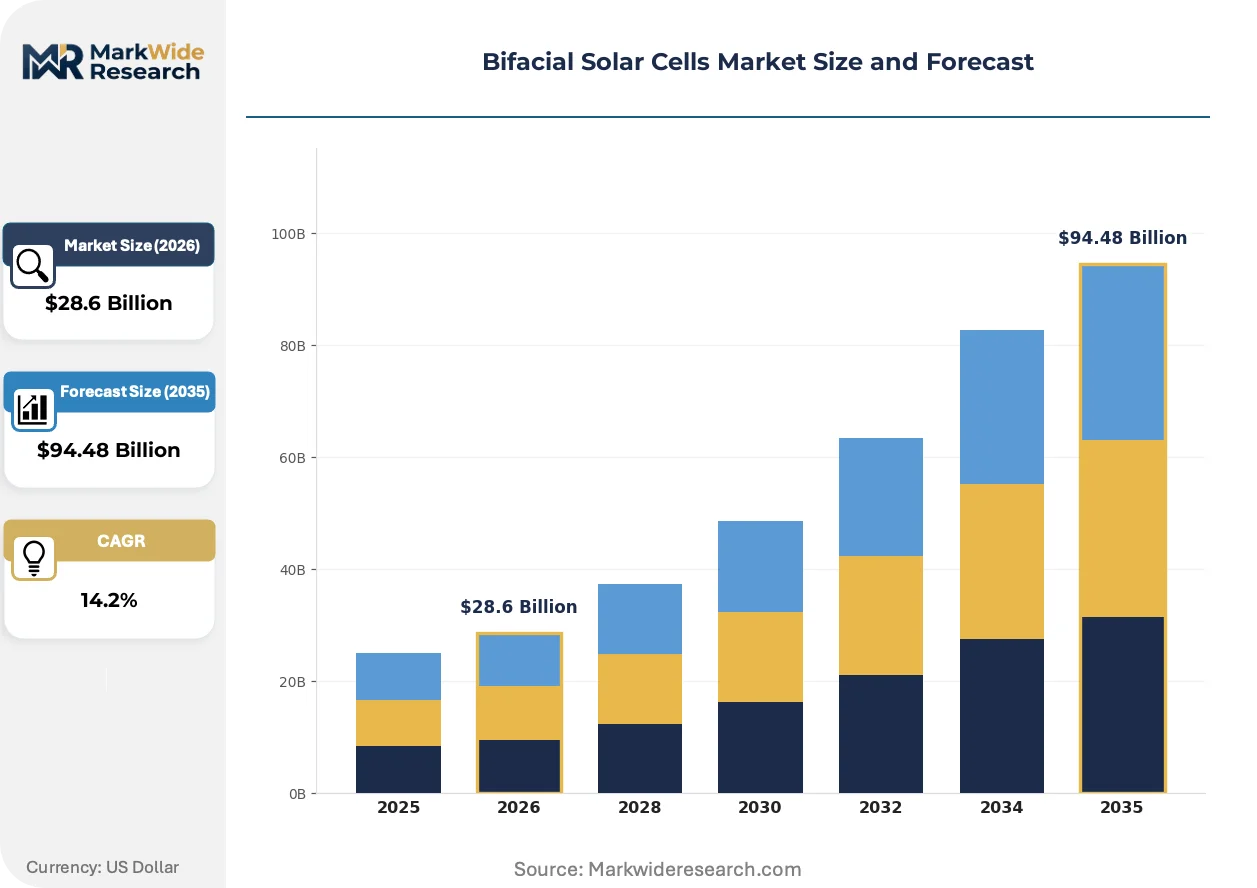
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Heterojunction Application: Utility-Scale, Commercial, Residential, Off-Grid Installation Type: Ground-Mounted, Roof-Mounted, Floating, Integrated End User: Energy Providers, Industrial Users, Residential Customers, Government |
| Companies Covered | LONGi, Trinasolar, Canadian Solar, JA Solar Technology Co., Ltd., Jinko Solar, SHARP, LG Electronics, Risen Energy, Hanwha Q CELLS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifacial Solar Cells Market Trends and Innovations
Cell architecture migration and encapsulation material advances are compressing levelized cost trajectories while procurement models favor performance-guaranteed supply contracts over commodity spot purchases.
Transparent backsheet formulations are migrating from fluoropolymer composites to co-extruded polyolefin structures. European project developers under EU Green Deal procurement mandates now specify these materials for reduced end-of-life fluorinated waste. This migration from dual-glass to lightweight backsheet designs is enabling single-axis tracker compatibility and reducing structural steel requirements.
China's GB standards for bifacial module certification now mandate rear-side irradiance testing protocols under MIIT enforcement. Domestic manufacturers must submit to third-party witnessed performance validation before grid interconnection approval. Utility-scale developers in Inner Mongolia and Qinghai provinces face extended commissioning timelines as testing laboratory capacity constrains throughput.
Long-term power purchase agreements with degradation warranties now dominate utility-scale procurement. Independent power producers in Saudi Arabia and the UAE are abandoning spot module purchases for 10-15 year supply contracts with guaranteed output. This preference shift is most visible in Saudi Arabia's renewable tender program where developers must demonstrate 25-year performance guarantees to qualify for offtake agreements.
Bifacial Solar Cells Market Segmentation
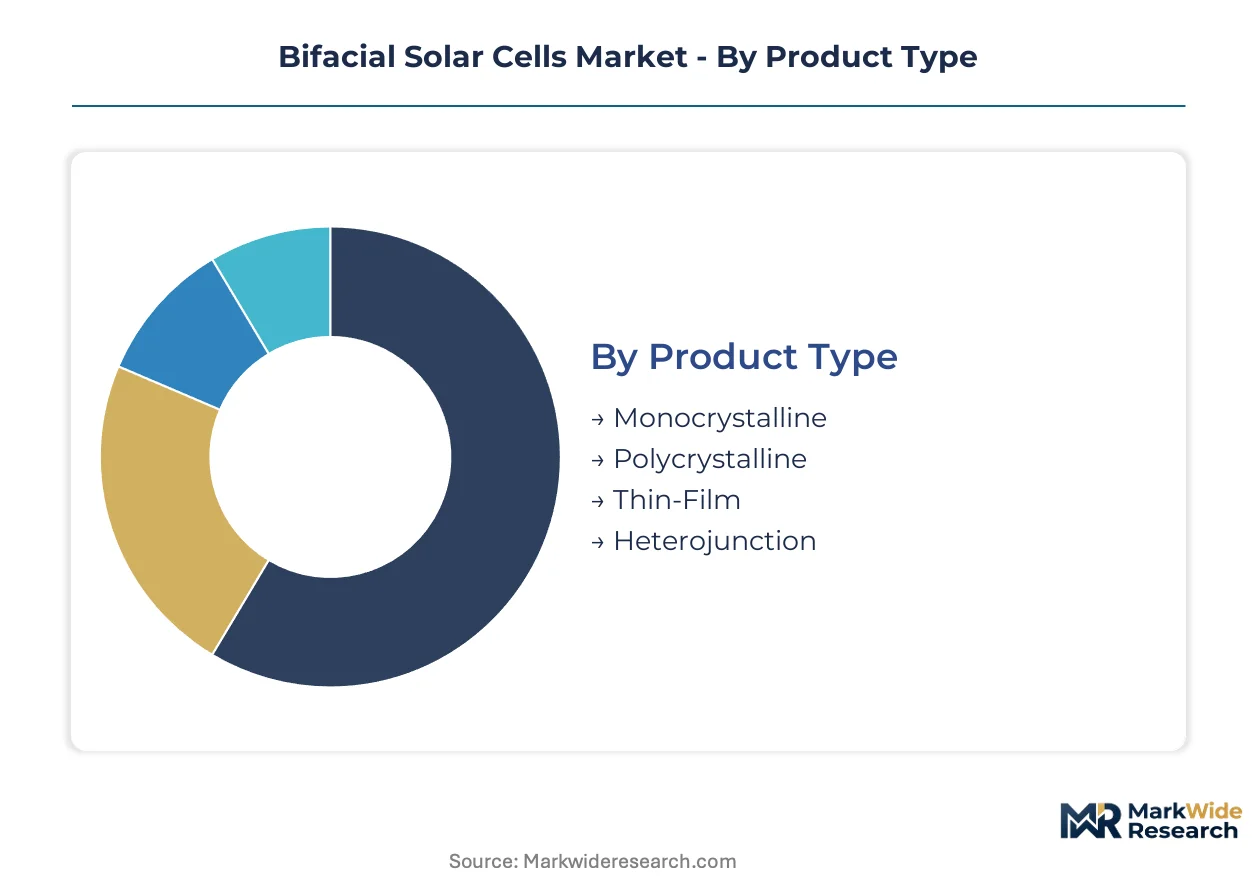
Bifacial solar cell procurement patterns diverge sharply across installation contexts and buyer sophistication levels. Technical specifications, warranty terms, and performance guarantees vary significantly by segment, creating distinct service intensity requirements throughout the product lifecycle.
Product Type:
After-sales service intensity escalates with cell architecture complexity and efficiency tier, as premium technologies demand specialized maintenance protocols and degradation monitoring systems.
- Monocrystalline:Passivated contact architectures dominate utility-scale deployment due to superior conversion efficiency and compatibility with PERC and TOPCon production lines. Demand concentrates in Saudi Arabia's gigawatt-scale renewable tenders where project developers specify 25-year performance guarantees. By volume, Monocrystalline leads. By growth pace, Heterojunction is expanding most quickly.
- Heterojunction:Amorphous silicon layers deposited on crystalline substrates enable efficiency thresholds above 24% with lower temperature coefficients. China's MIIT enforcement of updated grid interconnection standards accelerates domestic deployment of these high-performance arrays across Inner Mongolia and Qinghai provinces.
- Polycrystalline:Multi-crystalline silicon wafers offer cost-advantaged production for price-sensitive procurement in emerging markets.
- Thin-Film:Cadmium telluride and CIGS architectures serve niche applications requiring lightweight flexibility or spectral response optimization.
Technology migration favors passivated contact architectures as manufacturers compress manufacturing cost curves while resetting competitive benchmarks.
Application:
Project scale determines procurement modality, with large developers abandoning spot purchases for long-term supply contracts while smaller buyers remain exposed to commodity pricing cycles.
- Utility-Scale:Independent power producers in Saudi Arabia and the UAE now mandate 10-15 year supply contracts with guaranteed output rather than spot module purchases. Desert solar parks across the Middle East and North Africa exploit premium albedo conditions to maximize rear-side energy yield capture.
- Commercial:Corporate offtakers under EU Green Deal procurement mandates specify transparent backsheet formulations for reduced end-of-life fluorinated waste.
- Residential:Distributed generation systems favor lightweight backsheet designs enabling single-axis tracker compatibility and reduced structural steel requirements.
- Off-Grid:Remote installations prioritize reliability and simplified maintenance protocols over peak efficiency metrics.
Utility-scale commands absolute volume leadership while floating installations on reservoirs and coastal sites capture premium pricing for specialized requirements.
Installation Type:
Structural configuration dictates encapsulant selection, frame architecture, and corrosion resistance specifications across divergent environmental exposures.
- Ground-Mounted:Fixed-tilt and tracking systems dominate Saudi Arabia's national renewable program where local content rules redirect supply chain investments toward Red Sea manufacturing zones.
- Floating:Coastal reservoir applications command premium pricing for corrosion-resistant frame architectures and marine-grade encapsulants under extended degradation warranties.
- Roof-Mounted:Distributed commercial and residential systems require lightweight module designs compatible with existing structural load constraints.
- Integrated:Building-integrated photovoltaics merge architectural requirements with energy generation functions.
Ground-mounted systems anchor procurement volume while floating installations gain share fastest on specialized performance premiums.
End User:
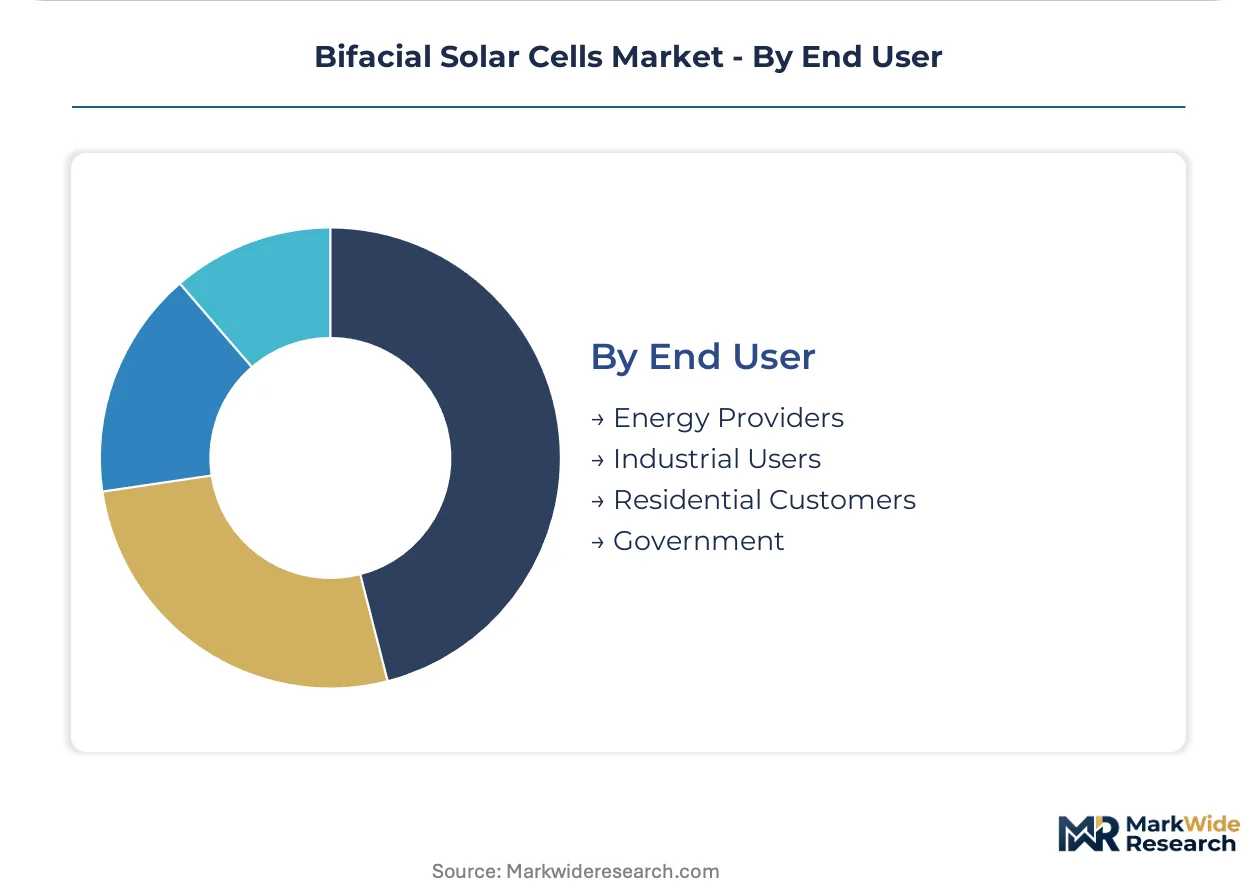
Buyer category shapes contract structure, with institutional offtakers driving standardization while fragmented residential demand sustains distribution channel complexity.
- Energy Providers:Saudi Arabia's renewable tender program requires developers to demonstrate 25-year performance guarantees to qualify for offtake agreements. China's dual carbon goals accelerate domestic deployment through MIIT enforcement of GB standards for bifacial module certification.
- Government:India's BIS mandates local testing protocols under its solar photovoltaic product order, creating non-tariff barriers for non-compliant suppliers.
- Industrial Users:Corporate renewable energy buyers specify transparent backsheet formulations under EU Green Deal procurement mandates.
- Residential Customers:Price-sensitive distributed generation demand concentrates in markets with net metering policy support.
Energy providers dominate procurement volume while government tenders are climbing the fastest on policy-mandated renewable targets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters heavily in East Asia while procurement demand concentrates across desert solar zones in the Middle East and subsidized renewable corridors in India and the United States. Regulatory divergence around carbon accounting, local content mandates, and grid interconnection standards is fragmenting competitive access across major demand centers.
China
Domestic deployment accelerates through MIIT enforcement of updated GB standards for bifacial module certification and grid interconnection. The dual carbon goals mandate rear-side irradiance testing protocols before commissioning approval. Manufacturing concentrates in the Yangtze River Delta and Inner Mongolia where polysilicon-to-module integration achieves lowest-in-class production economics.
Saudi Arabia
Gigawatt-scale renewable tenders under the national renewable program drive procurement volume with strict 25-year performance guarantee requirements. Local content rules redirect supply chain investments toward Red Sea manufacturing zones. Project development clusters in the Eastern Province and Western Region where premium albedo conditions maximize rear-side energy yield capture.
India
Production-linked incentives under the PLI scheme subsidize domestic cell and module manufacturing for BIS-compliant project developers. The Central Electricity Authority mandates local testing protocols that create non-tariff barriers for non-compliant suppliers. Industrial deployment concentrates in Gujarat and Rajasthan where state-level renewable purchase obligations enforce procurement quotas.
United States
Anti-circumvention investigations into Southeast Asian origin claims force supply chain reconfiguration and documentation overhead for utility-scale developers. The Inflation Reduction Act domestic content bonuses reshape procurement toward qualifying North American assembly. Project pipelines concentrate in Texas and California where interconnection queue reforms aim to accelerate grid access timelines.
Germany
EU F-Gas Regulation compliance timelines extend certification cycles for dual-glass encapsulation imports under CE marking requirements. The EU Green Deal procurement mandates specify transparent backsheet formulations for reduced end-of-life fluorinated waste. Industrial offtakers in Bavaria and North Rhine-Westphalia drive commercial segment demand through corporate renewable energy targets.
Bifacial Solar Cells Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on wafer and cell supply. The vendor base separates into three functional layers: vertically integrated giants controlling wafer-to-module production, technology licensors monetizing process IP, and regional assemblers serving protected domestic markets. Strategic moves concentrate on backward integration into polysilicon refining and captive tracker system development to capture balance-of-plant value.
Among Chinese-integrated manufacturers, LONGi and Trinasolar occupy positions as archetype representatives of the wafer-to-module platform model, while Jinko Solar exemplifies the geographically diversified assembler strategy through manufacturing footprints spanning Southeast Asia and the United States. These three anchors illustrate how competitive positioning diverges between technology-led efficiency plays and tariff-optimized supply chain configuration.
| Leading Market Players |
|---|
| LONGi |
| Trinasolar |
| Canadian Solar |
| JA Solar Technology Co., Ltd. |
| Jinko Solar |
| SHARP |
| LG Electronics |
| Risen Energy |
| Hanwha Q CELLS |
| Others |
Pricing and Supply Chain Analysis
The Yangtze River Delta's polysilicon-to-module integration clusters concentrate manufacturing scale, translating upstream capacity control into pricing leverage for tier-one suppliers negotiating long-term offtake contracts with Saudi and UAE utility developers.
Pricing Analysis
China's MIIT enforcement of GB standards for bifacial module certification dictates the pricing tier structure across the industry. Three-tier pricing structure across premium heterojunction, standard TOPCon, and economy PERC levels separates efficiency-grade offerings. Price differentiation hinges on rear-side irradiance testing compliance and 25-year performance guarantee backing. Pricing pressure stems from polysilicon input cost swings, with margins tightening most acutely for non-integrated assemblers exposed to metallurgical-grade silicon concentrate volatility. Utility-scale IPPs show least price sensitivity due to long-term PPA security, while distributed commercial buyers in Europe exhibit highest elasticity under EU Green Deal procurement mandates.
Supply Chain Analysis
Contract manufacturing concentration rests with LONGi, Trinasolar, and Jinko Solar's in-house wafer-to-module platforms rather than third-party foundries. Geographic supply concentration draws from China, Malaysia, and Vietnam where PERC and TOPCon capacity dominates. Raw material dependencies center on metallurgical-grade polysilicon, transparent backsheet formulations, and dual-glass encapsulation materials. Supply chain risk manifests as single-source vulnerability from Southeast Asian concentration exposed to US Commerce Department anti-circumvention investigations. Distribution runs through direct long-term supply contracts for utility-scale procurement, with spot market channels serving fragmented commercial and residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology architecture fragmentation creates entry niches as heterojunction efficiency thresholds reset competitive benchmarks and procurement models shift from commodity spot purchases to performance-guaranteed contracts.
For Market Incumbents: Build certification moats by securing BIS compliance for Indian PLI scheme access and MIIT GB standard pre-approval for Chinese grid interconnection. Incumbent suppliers should anchor backward integration into polysilicon refining to defend against input cost volatility, while expanding Red Sea manufacturing footprints to satisfy Saudi local content rules and neutralize tariff exposure from Southeast Asian origin investigations. For New Entrants and Emerging Players: Floating solar installations on coastal reservoirs in Southeast Asia represent the most penetrable entry point, commanding premium pricing for corrosion-resistant frame architectures that established players under-serve. New entrants should target India's PLI-subsidized domestic manufacturing capacity for BIS-compliant supply to Gujarat and Rajasthan state markets. A technology licensing partnership with heterojunction equipment providers offers the fastest go-to-market angle versus greenfield PECVD toolset deployment. For Investors and Strategic Acquirers: Long-term, this sits as a utility-scale infrastructure play because desert solar park procurement in Saudi Arabia and the UAE locks in decade-long offtake visibility with sovereign-backed counterparty risk. Acquisition targets should screen for captive tracker system development capabilities and Red Sea manufacturing zone operational presence. The signal to watch is commissioning timeline compression in Inner Mongolia and Qinghai provinces as testing laboratory capacity expansion indicates demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Heterojunction Capacity Buildout | PECVD toolset deployment targets efficiency thresholds above 24% with lower temperature coefficients. |
| Red Sea Manufacturing Zone Establishment | Saudi local content rules redirect supply chain investments toward captive module assembly serving MENA tenders. |
| Transparent Backsheet Formulation Migration | EU Green Deal procurement mandates specify polyolefin structures for reduced end-of-life fluorinated waste. |
| Long-term Power Purchase Agreement Structuring | Saudi renewable tender program requires 25-year performance guarantees to qualify for offtake agreements. |
| Anti-Circumvention Documentation Infrastructure | US Commerce Department probes force supply chain reconfiguration and origin certification overhead. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA project databases, IEA renewable deployment reports, FERC interconnection filings, and customs trade records. Primary interviews engaged utility planning officers at Saudi and UAE IPPs, EPC contractors active in MENA desert solar parks, polysilicon procurement leads at integrated manufacturers, and grid operators managing Inner Mongolia and Qinghai province interconnection queues. Bottom-up shipment volume analysis triangulates against top-down capacity buildout modeling across the analysis window.
Forecast inputs span cell architecture migration rates, albedo-optimized installation geometry adoption, and procurement contract duration shifts. Segmentation dimensions modeled include product type heterogeneity, application scale tier, installation configuration, and end-user category across regional regulatory clusters. CAGRs derive from installed capacity trajectory analysis and module pricing elasticity assumptions. Industry-specific inputs incorporate MIIT GB standard enforcement timelines and Saudi renewable tender program procurement pacing.
Macroeconomic conditions sit as an overlay; deviation in polysilicon spot pricing, freight rate indices, or emerging market currency volatility would shift the trajectory. Forecasts reflect assumptions around technology migration pace and regulatory compliance timeline adherence. Quarterly review of Southeast Asian capacity utilization rates, US Commerce Department investigation dockets, and Saudi PPA award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Printable Solar Cells Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Collector Panels Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market