
 Europe Lithium Foil Market | 2026-2036
Europe Lithium Foil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lithium Foil Market Insights
Performance-based material certification is pivoting how European lithium foil suppliers contract with cell manufacturers. Albemarle Corporation leverages its Kings Mountain processing heritage to sustain qualification pathways with German OEMs. Ganfeng Lithium Co., Ltd. anchors its European push through Rotterdam distribution hubs, while BASF SE differentiates via polymer-coated foil architectures for solid-state prototypes.
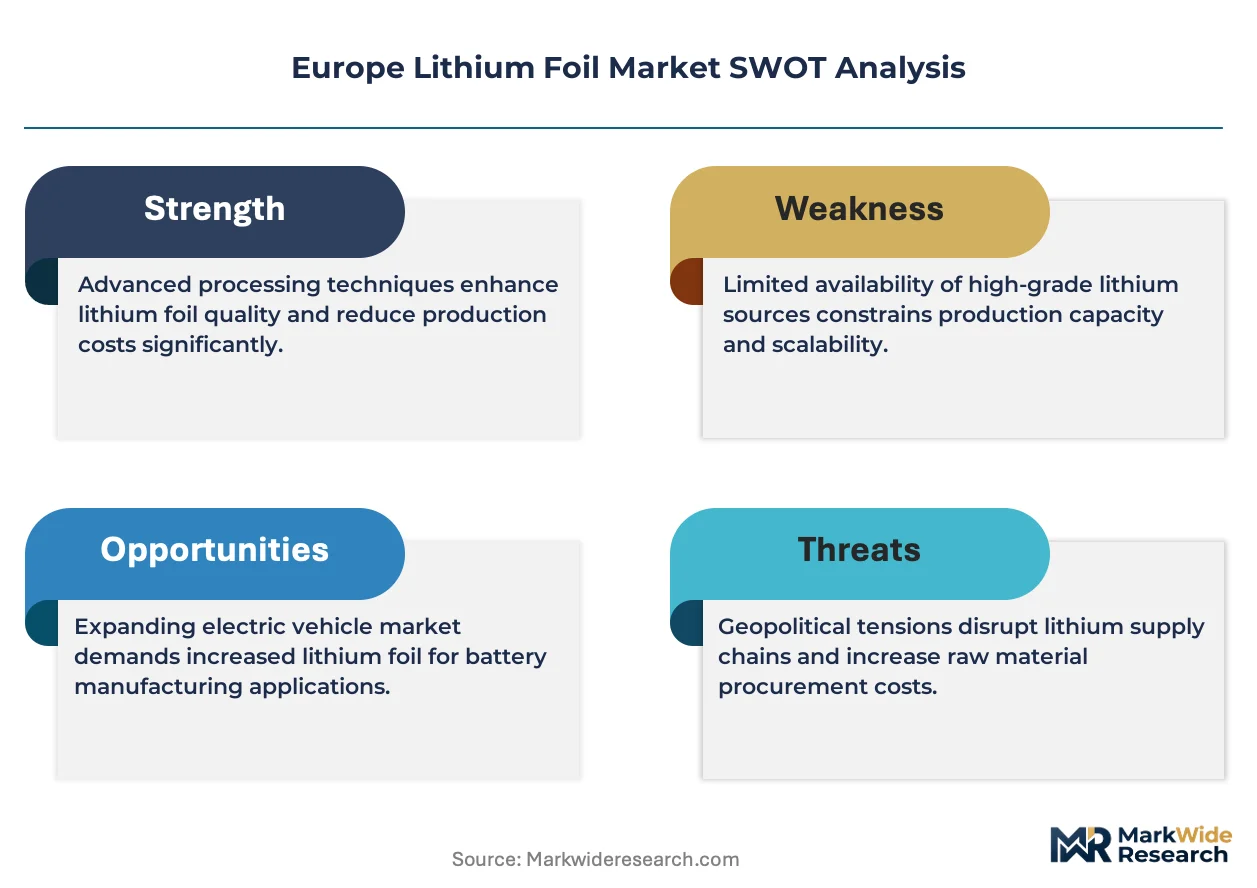
Europe lithium foil comprises rolled or cast lithium metal strips, typically ranging from sub-20-micron ultra-thin gauges to 200-micron formats, serving as anode current collectors or lithium reservoirs in next-generation electrochemical cells. Specialty foil commands premium positioning among European buyers due to surface-oxide control and thickness uniformity requirements for solid-state applications. Automotive batteries absorbs the dominant share of regional volume, though aerospace applications generates disproportionate margin pools given qualification barriers and lot-traceability standards. Thin foil and ultra-thin foil segments are expanding fastest as European cell developers pursue energy-density targets through lithium-metal anode architectures.
The EU Battery Regulation and ECHA REACH frameworks govern chemical safety, carbon-footprint disclosure, and recycled-content thresholds for lithium materials placed on the European market. CE marking requirements under the EU's industrial strategy shape product conformity pathways, while Germany's national battery cell production initiative channels public funding toward domestic foil-conversion capacity. Stakeholders must monitor how the EU Critical Raw Materials Act alters sourcing obligations for non-European lithium feedstock before committing to long-term offtake structures.
Market Dynamics
The EU Battery Regulation's carbon-footprint disclosure mandates and recycled-content thresholds are forcing cell manufacturers to requalify their entire lithium foil supply base, compressing supplier consolidation timelines across Germany, France, and Poland.
Growth Catalysts
- Solid-state battery prototyping:German and French OEMs are scaling lithium-metal anode pilot lines, pulling ultra-thin foil demand into automotive cell gigafactories.
- REACH chemical safety frameworks:ECHA compliance pathways now favor European-based foil converters with established substance registration dossiers.
- France's national battery strategy:Public funding channels are accelerating domestic foil-conversion capacity near Dunkirk and Verkor's production sites.
Market Restraints
- Lithium carbonate price volatility:Feedstock cost swings from South American brine operations transmit directly into European foil pricing structures.
- Single-source dependency:Ultra-thin gauge rolling capacity concentrates among a handful of specialty metal processors in Germany and Scandinavia.
- Substitution by silicon-anode architectures:Some solid-state developers are pivoting to silicon-composite anodes to bypass lithium-metal handling complexity.
Strategic Opportunities
- Poland's emerging battery corridor:LG Energy Solution and SK On operations near Wrocław are creating localized foil demand without German supply chain congestion.
- Aerospace qualification pathways:Satellite and electric aviation battery developers are establishing separate certification tracks for high-purity lithium reservoirs.
- EU Critical Raw Materials Act sourcing obligations:Strategic stockpiling mandates are creating offtake guarantees for European-based foil producers.
Industry Challenges
- Thin-rolling technician scarcity:The sub-50-micron gauge specialization requires skills concentrated among retiring workforce cohorts in German metalworking regions.
- Surface-oxide certification timelines:Solid-state cell developers demand lot-level traceability documentation that extends qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lithium Foil Market |
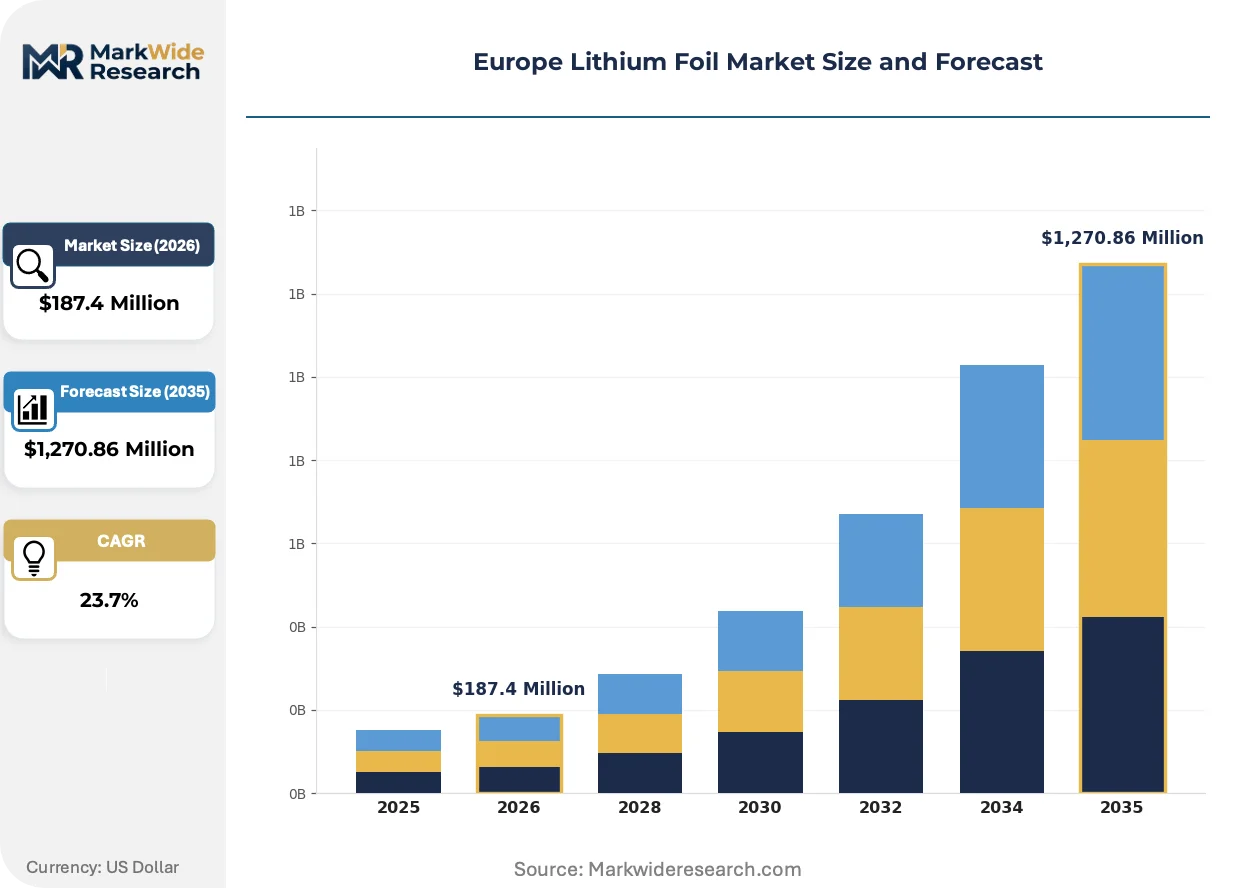
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Foil, Specialty Foil, Anode Foil, Cathode Foil End User: Automotive Batteries, Consumer Electronics, Renewable Energy Storage, Aerospace Applications Thickness: Thin Foil, Medium Foil, Thick Foil, Ultra-Thin Foil Packaging Type: Roll, Sheet, Custom Sizes, Bulk Packaging |
| Companies Covered | Albemarle Corporation, Ganfeng Lithium Co., Ltd., BASF SE, Merck KGaA, American Elements, Thermo Fisher Scientific, Nanoshel LLC, The Honjo Chemical Corporation, UACJ Foil Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lithium Foil Market Trends and Innovations
Electrochemical cell architectures are fragmenting procurement specifications, forcing foil suppliers to maintain parallel production lines for diverging thickness and purity requirements across automotive and aerospace buyers.
Polymer-coated lithium foil architectures are decentralizing how cell developers manage interface stability in solid-state prototypes. BASF SE and specialty chemical partners are piloting nanometer-scale ceramic-polymer interlayers that reduce dendrite formation risk. Automotive OEMs in Stuttgart and Munich are adopting these formats for 2028 platform pre-development, compressing traditional bare-foil qualification timelines.
EU Battery Regulation carbon-footprint thresholds are restructuring supplier qualification protocols. Cell manufacturers must now document cradle-to-gate emissions for lithium feedstock, favoring European converters with renewable energy-powered rolling mills. German OEM procurement teams are rewriting technical specifications to prioritize low-carbon foil sources for premium vehicle segments.
Buyer concentration around cell gigafactories is consolidating order patterns. Automotive battery manufacturers in Germany's Baden-Württemberg and Lower Saxony corridors are moving from spot purchasing to multi-year offtake frameworks with volume commitments. This compresses working capital cycles for foil converters while locking in capacity allocation years ahead of production ramp.
Europe Lithium Foil Market Segmentation
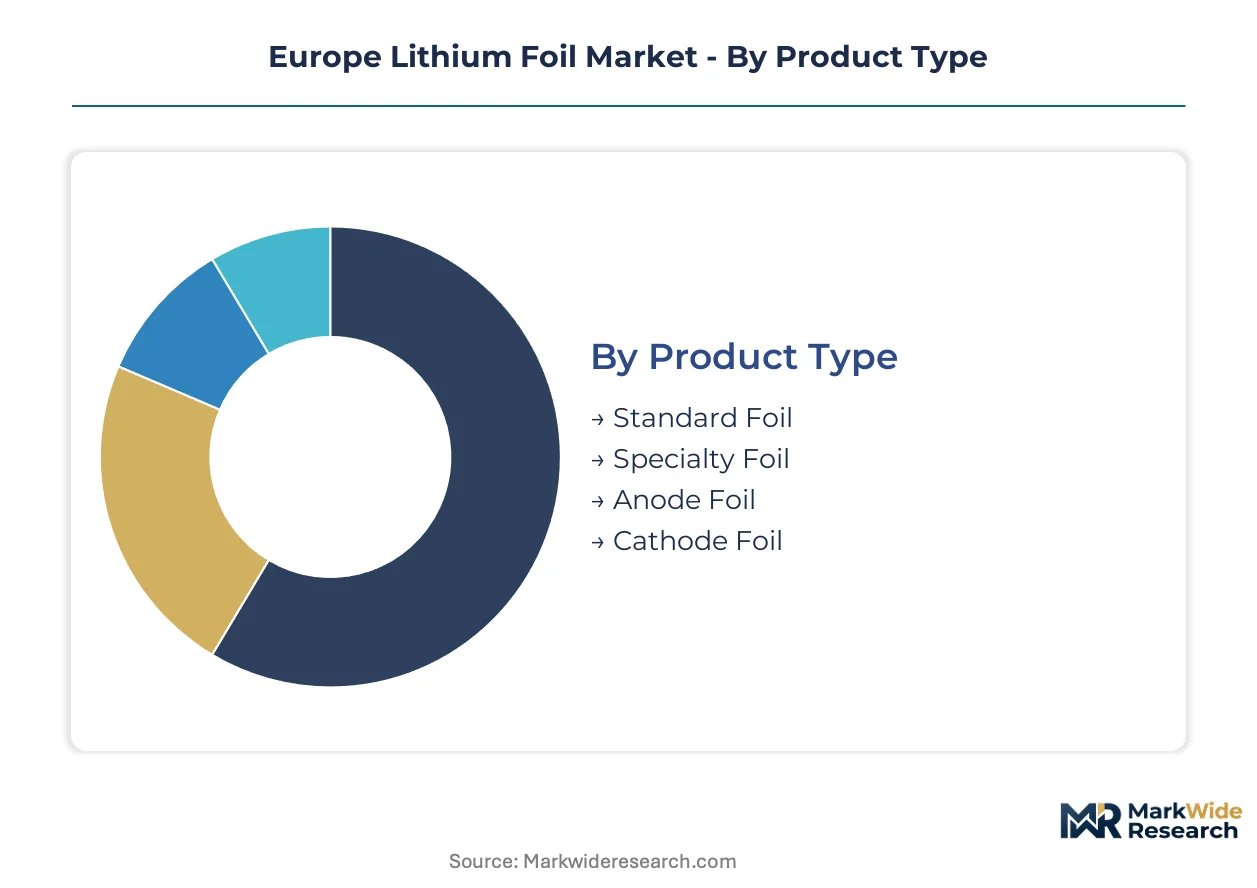
Lithium foil procurement in Europe fragments across technical specifications and end-use requirements, with solid-state battery developers imposing stricter qualification protocols than conventional cell manufacturers. Segmentation reveals where margin pools concentrate and where volume scale accumulates across the value chain.
Product Type:
Customization intensity spans from commodity-grade formats to engineered architectures with polymer interlayers or oxide-controlled surfaces.
- Specialty Foil:Engineered with nanometer-scale surface treatments and strict oxide-layer control for solid-state cell interfaces. Demand concentrates among Stuttgart and Munich OEMs pursuing lithium-metal anode platforms, with qualification cycles extending 12-18 months due to lot-traceability requirements.
- Anode Foil:Serves as the lithium reservoir in next-generation cells, requiring precise thickness uniformity for dendrite suppression. German automotive battery corridors are scaling pilot lines around Heilbronn and Salzgitter, pulling ultra-thin gauge formats into pre-development contracts.
- Standard Foil:Conventional rolled lithium metal for legacy battery architectures and industrial applications.
- Cathode Foil:Specialized formats for lithium-sulfur and lithium-air experimental cell chemistries.
Leading the category by volume: Standard Foil. Expanding most quickly: Specialty Foil.
End User:
Application-driven specifications separate automotive scale from aerospace margin premiums.
- Automotive Batteries:Cell gigafactories across Baden-Württemberg and Lower Saxony absorb the dominant regional volume, with multi-year offtake frameworks replacing spot purchasing. EU Battery Regulation carbon-footprint thresholds are rewriting procurement specifications to prioritize low-carbon foil sources.
- Aerospace Applications:Satellite and electric aviation developers demand high-purity lithium reservoirs with full lot documentation. Qualification barriers and traceability standards generate disproportionate margin pools compared to automotive volume.
- Consumer Electronics:Portable device battery manufacturers in Eastern Europe seeking thinner form factors.
- Renewable Energy Storage:Grid-scale battery projects evaluating lithium-metal architectures for long-duration applications.
Dominant volume share: Automotive Batteries. Steepest margin expansion: Aerospace Applications.
Thickness:
Gauge selection directly determines energy-density potential and manufacturing yield in solid-state cell assembly.
- Ultra-Thin Foil:Sub-20-micron gauges enabling maximum anode energy density for premium electric vehicle platforms. French and German OEMs are accelerating procurement as 2028 platform pre-development advances, though rolling capacity concentrates among specialty metal processors in Germany and Scandinavia.
- Thin Foil:20-50 micron range balancing manufacturability with performance targets in prototype cells.
- Medium Foil:50-150 micron formats for experimental and industrial battery applications.
- Thick Foil:150-200 micron gauges for lithium reservoirs in non-automotive electrochemical systems.
Current production concentration: Thin Foil. Gaining share fastest: Ultra-Thin Foil.
Packaging Type:
Logistics configuration reflects customer scale and handling requirements across the supply chain.
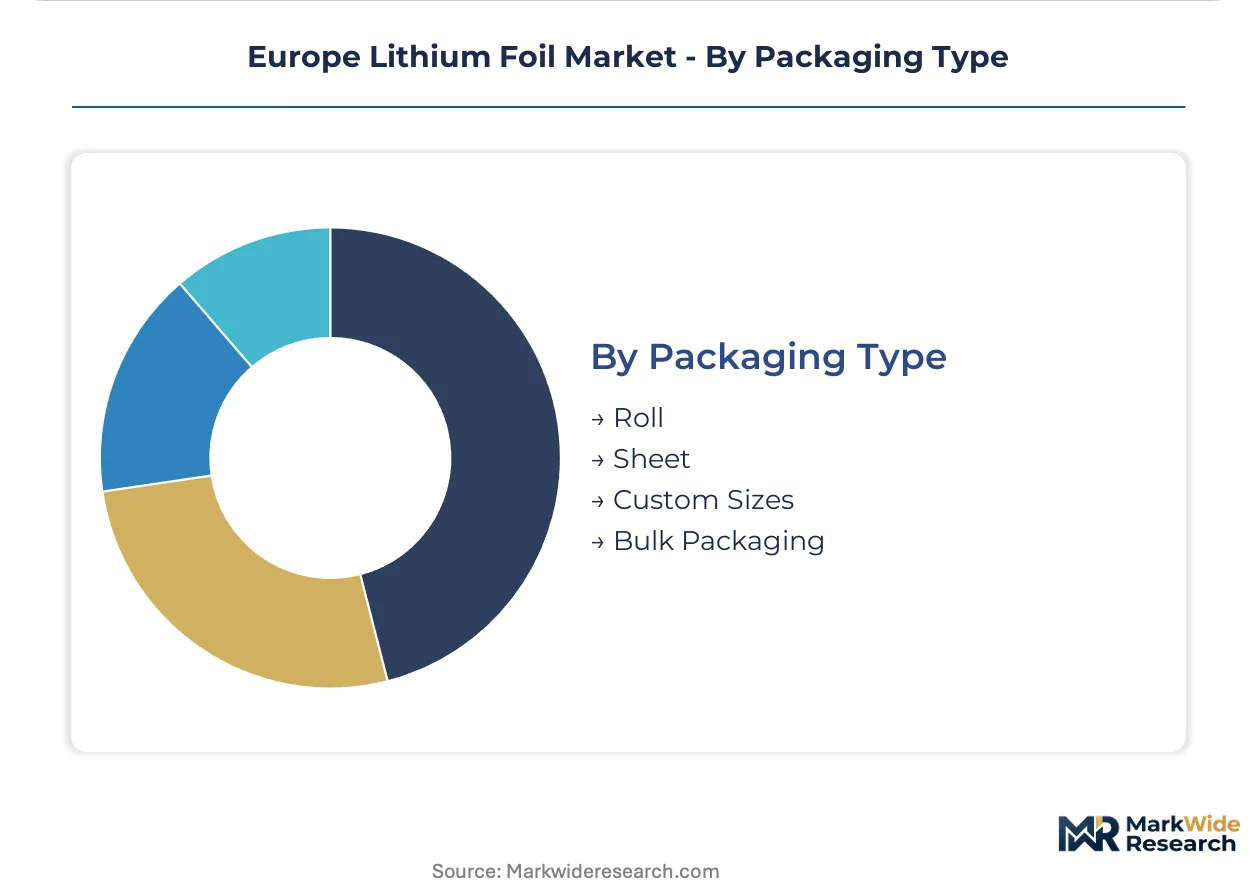
- Roll:Continuous-format supply for high-volume cell manufacturing lines. German gigafactories are standardizing on specified roll diameters and core materials to automate feeding into coating and assembly equipment.
- Sheet:Precut formats for prototype development and small-batch solid-state cell production.
- Custom Sizes:Application-specific dimensions for aerospace and specialty industrial buyers.
- Bulk Packaging:Large-quantity shipments for chemical processing and industrial lithium applications.
Standard procurement format: Roll. Fastest-growing configuration: Custom Sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's lithium foil production capacity lags behind consumption growth, creating import dependency on Asian and North American converters while domestic rolling mills scale up across Germany and France.
Germany
Automotive OEMs in Stuttgart and Munich are accelerating ultra-thin foil procurement for 2028 lithium-metal anode platforms. The KBA enforces battery safety certification that favors domestic converters with established substance dossiers. Cell gigafactories around Salzgitter and Heilbronn are locking multi-year offtake frameworks with specialty metal processors.
France
Dunkirk and Verkor production sites are pulling foil demand from domestic conversion capacity expansions. France's national battery strategy channels public funding toward lithium-metal anode pilot lines. The ANSM monitors chemical safety compliance for aerospace-grade foil qualification pathways near Toulouse aviation clusters.
Poland
LG Energy Solution and SK On operations near Wrocław are generating localized foil demand without German supply chain congestion. EU Battery Regulation carbon-footprint thresholds are rewriting procurement specifications for Polish cell manufacturers. The emerging battery corridor is attracting foil distributors seeking volume commitments from gigafactory procurement teams.
Sweden
Northvolt's Skellefteå gigafactory is creating specialized demand for ultra-thin gauge formats in solid-state prototyping. REACH compliance pathways favor Scandinavian converters with renewable energy-powered rolling mills. Specialty metal processors in central Sweden are concentrating sub-50-micron rolling capacity for European automotive buyers.
Netherlands
Rotterdam distribution hubs are anchoring import logistics for Asian lithium suppliers serving European cell manufacturers. The country's national chemical regulator enforces ECHA substance registration for foil converters operating through Dutch ports. Amsterdam-area trading houses are structuring offtake guarantees for EU Critical Raw Materials Act strategic stockpiling mandates.
Europe Lithium Foil Market Competitive Landscape
Top-tier vendors anchor qualification pathways with German OEMs, while mid-tier converters compete on carbon-footprint certification and rolling precision. The market structure concentrates ultra-thin gauge capacity among specialty metal processors in Germany and Scandinavia, with broader standard foil supply fragmenting across European distributors. Three archetypes dominate: integrated chemical conglomerates with polymer-coating capabilities, pure-play lithium converters with rolling heritage, and trading houses with Rotterdam logistics advantages. Competitive moves center on backward integration into lithium carbonate feedstock and multi-year offtake framework negotiation with automotive cell gigafactories.
Among North American and Asian anchors, Albemarle Corporation exemplifies the processing-heritage archetype, while Ganfeng Lithium Co., Ltd. occupies a position within the logistics-anchored tier. BASF SE represents the chemical-conglomerate vector with polymer-coated foil architectures. These three names illustrate how competitive positioning fragments across feedstock control, distribution geography, and materials engineering specialization.
| Leading Market Players |
|---|
| Albemarle Corporation |
| Ganfeng Lithium Co., Ltd. |
| BASF SE |
| Merck KGaA |
| American Elements |
| Thermo Fisher Scientific |
| Nanoshel LLC |
| The Honjo Chemical Corporation |
| UACJ Foil Corporation |
| Others |
Pricing and Supply Chain Analysis
Ultra-thin gauge rolling technology migration toward sub-20-micron formats is simultaneously concentrating production economics among German and Scandinavian specialty metal processors while fragmenting procurement costs across automotive and aerospace buyer archetypes. This dual transformation compresses margin pools for commodity converters while rewarding oxide-controlled surface engineering capabilities with premium positioning.
Pricing Analysis
Cost-down pressure on standard foil accelerates because South American brine feedstock volatility transmits directly into European converter pricing structures. Three-tier pricing structure across specialty, thin, and standard gauges separates solid-state qualification premiums from legacy industrial applications. EU Battery Regulation carbon-footprint certification tiers now command measurable premiums over uncertified alternatives. Automotive cell gigafactories exhibit highest price sensitivity due to multi-year offtake volume commitments, while aerospace developers prioritize lot-traceability documentation over unit economics.
Supply Chain Analysis
Lithium carbonate feedstock rests on Chilean and Argentine brine operations, with Chinese chemical processing dominating intermediate conversion. Specialty rolling capacity draws from Germany, Sweden, and limited Japanese heritage metalworkers. Single-source vulnerability concentrates in sub-50-micron gauge capacity where retiring technician cohorts threaten output continuity. Distribution runs through Rotterdam port logistics for Asian material inflows, supplemented by direct mill relationships for high-volume automotive contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Battery Regulation's recycled-content mandates and carbon-footprint thresholds construct a compliance moat favoring incumbent converters with established ECHA dossiers and renewable energy-powered rolling infrastructure.
For Market Incumbents: Cement qualification pathways with Stuttgart and Munich OEMs by locking multi-year offtake frameworks before pilot lines scale to production volumes. Deepen backward integration into carbonate feedstock through South American brine offtakes to insulate margin structures from spot market volatility. Prioritize sub-20-micron rolling technician apprenticeship programs to defend against workforce scarcity threats from retiring German metalworking cohorts. For New Entrants and Emerging Players: Polymer-coated foil architectures offer a technology-first wedge into solid-state prototyping relationships where BASF SE and chemical conglomerates currently dominate interface engineering. Target Poland's emerging Wrocław battery corridor before German supply chain congestion extends qualification timelines. Pursue aerospace qualification pathways near Toulouse aviation clusters where traceability premiums offset lower volumes against automotive scale economics. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated chemical conglomerates seeking polymer-coating capabilities or automotive OEMs securing captive anode material supply. Five-to-ten year viability hinges on EU Critical Raw Materials Act strategic stockpiling mandate execution and solid-state platform adoption rates. Watch for silicon-anode architecture pivots by major OEMs as the inflection signal threatening lithium-metal anode demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Carbonate Feedstock | Secures margin insulation from South American brine spot volatility for European converters. |
| Sub-20-Micron Rolling Capacity Expansion | Captures solid-state battery prototyping demand from Stuttgart and Munich OEM platforms. |
| Polymer-Coated Foil Architecture Development | Addresses dendrite suppression requirements for next-generation solid-state cell interfaces. |
| ECHA REACH Dossier Completion | Establishes chemical safety compliance moat under EU Battery Regulation qualification protocols. |
| Renewable Energy-Powered Mill Certification | Unlocks carbon-footprint tier premiums from EU Battery Regulation procurement specifications. |
Research Methodology
Independent corroboration across cell manufacturer procurement executives, specialty metal processor plant managers, and ECHA regulatory affairs specialists underwrites the qualitative findings in this analysis. Secondary validation draws from EU Battery Regulation implementation documents, trade customs data for lithium material flows, and SEC filings from publicly traded chemical conglomerates. Bottom-up demand modeling from gigafactory capacity announcements triangulates against top-down market sizing from carbonate feedstock trade volumes.
Rate-of-change decomposition across the projection horizon separates volume growth from price-mix effects in specialty versus standard foil categories. Segmentation dimensions include product type, end-use application, thickness gauge, and packaging format alongside regional production cluster dynamics. CAGRs derive from rolling capacity utilization trends, solid-state platform adoption curves, and carbon-footprint certification penetration assumptions. Key inputs incorporate lithium carbonate spot price volatility bands and technician workforce retirement schedules.
Several conditions sit outside the modeled scope, including potential silicon-anode substitution breakthroughs, geopolitical disruptions to South American brine operations, and unannounced EU Battery Regulation threshold revisions. Forecasts reflect documented assumptions about solid-state commercialization timelines and OEM platform commitments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
Europe Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
China Battery Manufacturing Equipment Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Middle East and Africa Electric Vehicle Battery Separator Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market