
 Generator Sets Market | 2026-2036
Generator Sets Market Size, Share, and Industry Trends Forecast 2026-2036
Generator Sets Market Analysis
Multi-sourcing of critical engine components is broadening across the generator sets supply base as OEMs reduce exposure to single foundry dependencies. Cummins Inc. leverages captive engine manufacturing across multiple continents to sustain delivery reliability for industrial customers. Caterpillar Inc. anchors its position through integrated alternator and control system production. Generac Holdings Inc. competes in residential standby segments through direct channel control and installer network density.
Generator sets are electromechanical devices comprising a prime mover engine and electrical alternator assembled on a common skid, rated by output capacity in kilowatts and operational duty cycle. These systems provide primary or emergency electrical power where grid supply is unavailable, unstable, or insufficient for critical loads. Diesel fuel type retains the largest installed base across industrial and standby applications due to energy density and rapid start capability, while gas-fueled units are gaining share in continuous-duty and grid-connected deployments where emissions regulations favor cleaner combustion. Portable generators occupy the entry-level price tier with thinner margins, whereas industrial generators command premium positioning through customized enclosure, paralleling controls, and extended runtime engineering.
EPA Tier 4 Final mandates in the United States and EU Stage V requirements in Europe are forcing engine redesigns, after-treatment integration, and higher manufacturing costs across diesel-centric product lines. India's Central Pollution Control Board enforces emission norms for gensets up to 800 kW, compelling domestic assembly adaptation and localized catalyst supply chains. Stakeholders must monitor fuel flexibility roadmaps and hybrid integration architectures as grid modernization and carbon pricing reshape backup power investment criteria.
Market Dynamics
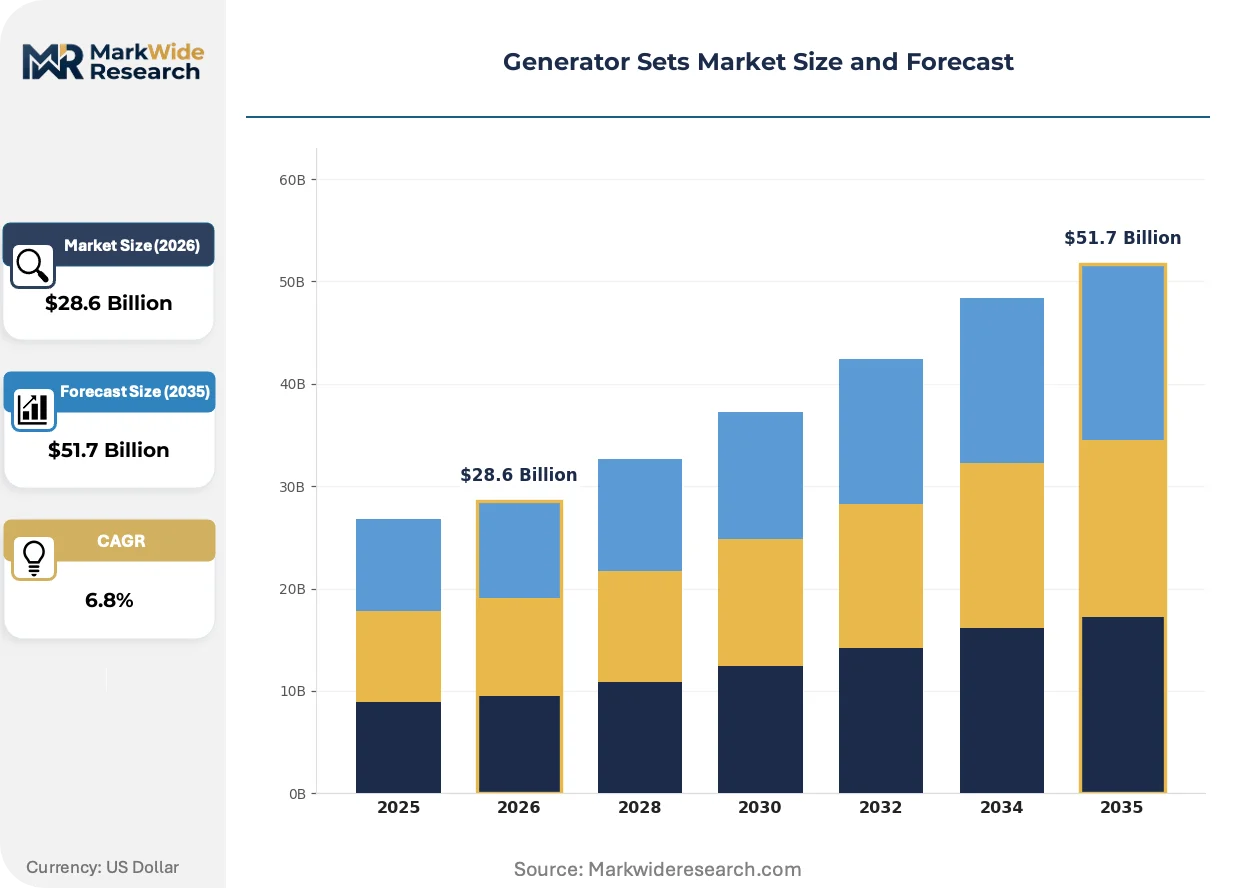
EPA Tier 4 Final and EU Stage V emissions standards are compressing diesel engine availability while data center operators accelerate backup power procurement, creating a supply-demand tension that favors gas-fueled and hybrid architectures.
Growth Catalysts
- Data center buildout:Hyperscale operators in Virginia, Frankfurt, and Singapore are specifying N+1 redundancy with 2-megawatt-class gensets for mission-critical uptime.
- India's grid instability:Commercial and industrial facilities across Maharashtra, Gujarat, and Tamil Nadu deploy gensets as primary power during monsoon-related distribution failures.
- EU Stage V certification:Stringent particulate and NOx limits for non-road engines are accelerating after-treatment adoption and factory requalification across European manufacturing bases.
Market Restraints
- Foundry concentration:Cylinder block and head casting capacity clusters in China and India, exposing OEMs to regional logistics disruptions and alloy price volatility.
- Platinum group metals:Diesel oxidation catalysts and selective catalytic reduction systems depend on palladium and rhodium, with prices subject to South African supply interruptions.
- Battery energy storage substitution:Lithium-ion systems with four-hour duration are capturing grid-balancing and short-duration backup applications from reciprocating engine solutions.
Strategic Opportunities
- Hybrid genset-battery systems:Integrating reciprocating engines with lithium-ion storage enables spinning reserve optimization and fuel consumption reduction for island microgrids.
- Saudi Arabia's Vision 2030:Giga-project construction and entertainment district electrification are driving demand for mobile and stationary power rental fleets.
- Renewable natural gas pathways:Landfill and agricultural biogas-to-electricity projects in California and the Netherlands qualify for carbon credits while utilizing existing gas engine platforms.
Industry Challenges
- Emissions calibration engineering:EPA Tier 4 Final and EU Stage V certification requires specialized combustion modeling and after-treatment thermal management expertise that remains scarce in smaller OEM engineering departments.
- Paralleling control integration:Synchronizing multiple gensets with utility feeds and renewable inverters demands power electronics competency that stretches traditional mechanical service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Generator Sets Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Generators, Standby Generators, Inverter Generators, Industrial Generators Fuel Type: Diesel, Gas, Biofuel, LPG End User: Residential, Commercial, Industrial, Construction Deployment: On-Grid, Off-Grid, Hybrid, Remote |
| Companies Covered | Caterpillar Inc., Cummins Inc., Generac Holdings Inc., Kohler Co., Atlas Copco AB, Briggs & Stratton Corporation, Rolls-Royce Holdings plc, Doosan Corporation, AKSA Power Generation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Generator Sets Market Emerging Trajectories
Digitalization of power system control and fuel flexibility engineering are converging to redefine genset value propositions beyond kilowatt output toward integrated energy-as-a-service delivery.
Containerized battery-genset hybrid architectures are electrifying backup power economics for data centers and industrial campuses. Microsoft and Amazon Web Services are specifying these systems for new hyperscale facilities in Iowa and Dublin. The technology is electrifying traditional standby genset procurement by enabling demand-response revenue participation and reduced runtime maintenance.
EPA Tier 4 Final enforcement is eliminating non-compliant diesel engines above 751 horsepower from US commercial availability. Engine manufacturers are integrating diesel particulate filters and selective catalytic reduction hardware that adds cost and packaging volume. Industrial standby applications in Texas and California are absorbing these changes through extended purchase lead times and factory-certified installation requirements.
Power-as-a-service contracting is displacing capital purchase for mid-scale commercial users. Energy service companies in Germany and Japan are offering fixed-rate agreements covering equipment, fuel, and maintenance. Data center operators in Frankfurt and Osaka are adopting this model to convert backup power from balance-sheet assets to operating expenses aligned with utilization risk.
Generator Sets Market Segmentation
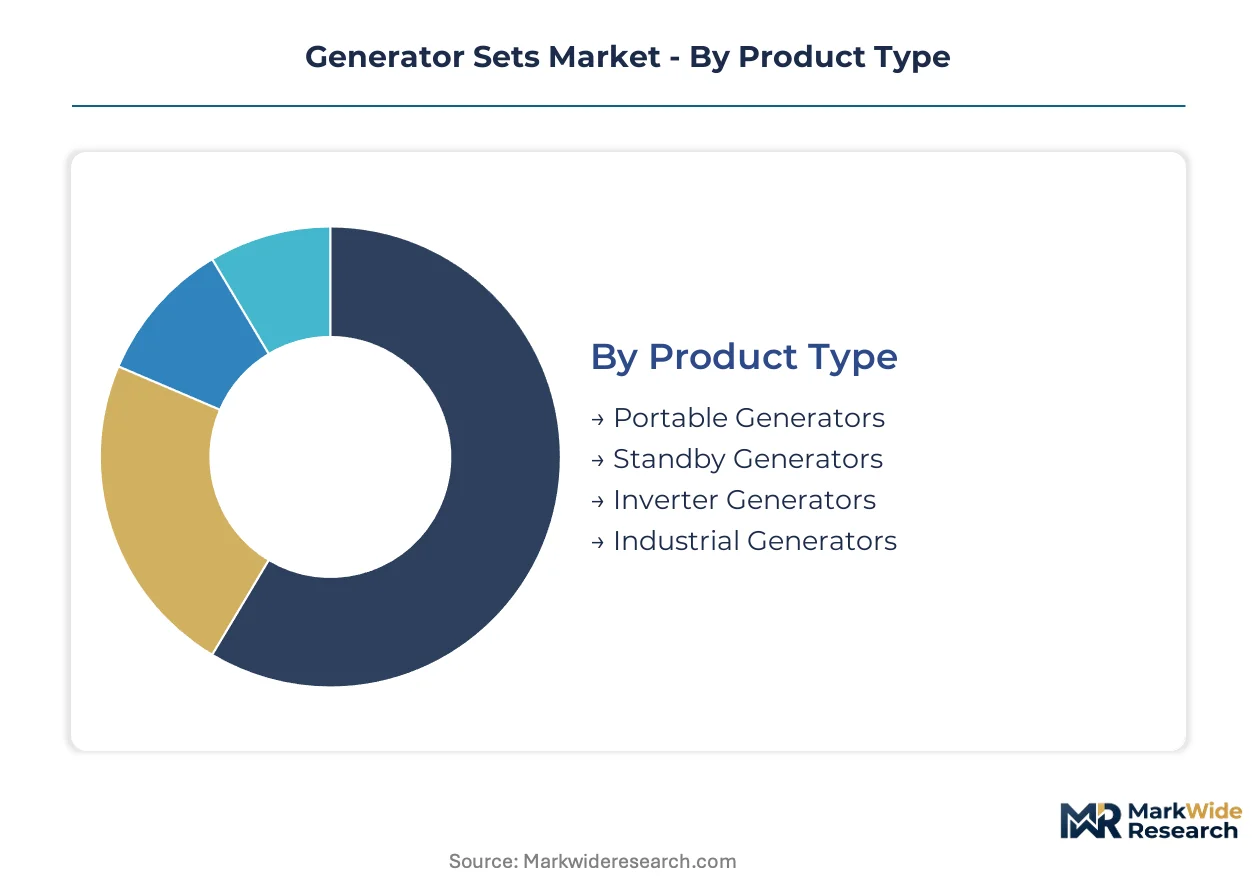
Generator sets serve vastly different duty cycles and reliability requirements across customer profiles. Product architecture, fuel chemistry, and grid connectivity status each create distinct procurement criteria and margin structures for manufacturers.
Product Type:
Volume concentrates in standardized standby units for residential and small commercial backup, while premium engineering margins attach to customized industrial configurations with paralleling controls and extended runtime.
- Portable Generators:Compact gasoline or inverter-based units rated below 10 kW for recreational, emergency home, and light construction use. Demand clusters with homeowners in hurricane-prone US Gulf Coast states and outdoor event rental fleets in Germany.
- Standby Generators:Fixed-installation systems with automatic transfer switches for seamless grid failure response, typically 10-150 kW. Deployment concentrates in suburban residential developments across Texas and Florida where utility reliability varies seasonally.
- Inverter Generators:Variable-speed engine-alternator sets producing clean sine wave output for sensitive electronics. Mature deployment sits with recreational vehicle owners and mobile medical clinics. Newer deployment is concentrated in telecom tower backup across rural India.
- Industrial Generators:Heavy-duty skid-mounted or containerized systems exceeding 150 kW with engineered enclosures and remote monitoring. Data center operators in Virginia and hyperscale cloud facilities in Frankfurt specify these for N+1 redundancy requirements.
Standby generators represent the largest installed base by unit count. Industrial generators command the steepest expansion trajectory as data center buildout accelerates.
Fuel Type:
Energy density and start-up speed differentiate fuel chemistry selection, with emissions regulations increasingly constraining diesel deployment in urban and continuous-duty applications.
- Diesel:Compression-ignition engines dominate standby and prime power above 75 kW due to rapid load acceptance and fuel stability. EPA Tier 4 Final compliance costs are compressing availability for non-road engines above 751 horsepower in the United States.
- Gas:Spark-ignited natural gas and biogas engines gain share in grid-connected combined heat and power and landfill gas-to-energy projects. California renewable natural gas pathways qualify for LCFS credits while utilizing existing engine platforms.
- Biofuel:Hydrotreated vegetable oil and fatty acid methyl ester blends enable carbon intensity reduction in existing diesel infrastructure. Deployment concentrates in European industrial campuses with Scope 1 emissions reduction mandates.
- LPG:Propane-fueled systems offer extended fuel storage stability and cleaner combustion for residential standby and food service backup. Rural properties across Australia and parts of Texas without natural gas pipeline access favor this chemistry.
Diesel retains the largest revenue share. Gas-fueled units are gaining share fastest as carbon pricing and air quality regulations reshape investment criteria.
End User:
Reliability requirements and procurement sophistication diverge sharply between residential consumers specifying standardized packages and industrial buyers demanding engineered system integration.
- Residential:Single-family homeowners and small multi-unit buildings seeking automatic backup for essential circuits. Hurricane corridors in Florida and grid-unstable suburbs around Mumbai drive replacement cycles and first-time installation.
- Commercial:Retail, healthcare, and hospitality facilities requiring business continuity for revenue protection. Regional hospital networks in Germany and cold chain logistics operators in Saudi Arabia prioritize 10-second start capability.
- Industrial:Manufacturing plants, mines, and process industries where power interruption causes equipment damage or safety hazards. Petrochemical complexes along the US Gulf Coast specify Class 1 Division 2 rated enclosures for hazardous area deployment.
- Construction:Mobile and rental fleet applications for temporary site electrification during building phases. Giga-project construction under Saudi Vision 2030 is mobilizing large rental fleets for Neom and Qiddiya developments.
Industrial end users generate the highest average transaction values. Construction rental demand is expanding most quickly in Middle Eastern megaproject corridors.
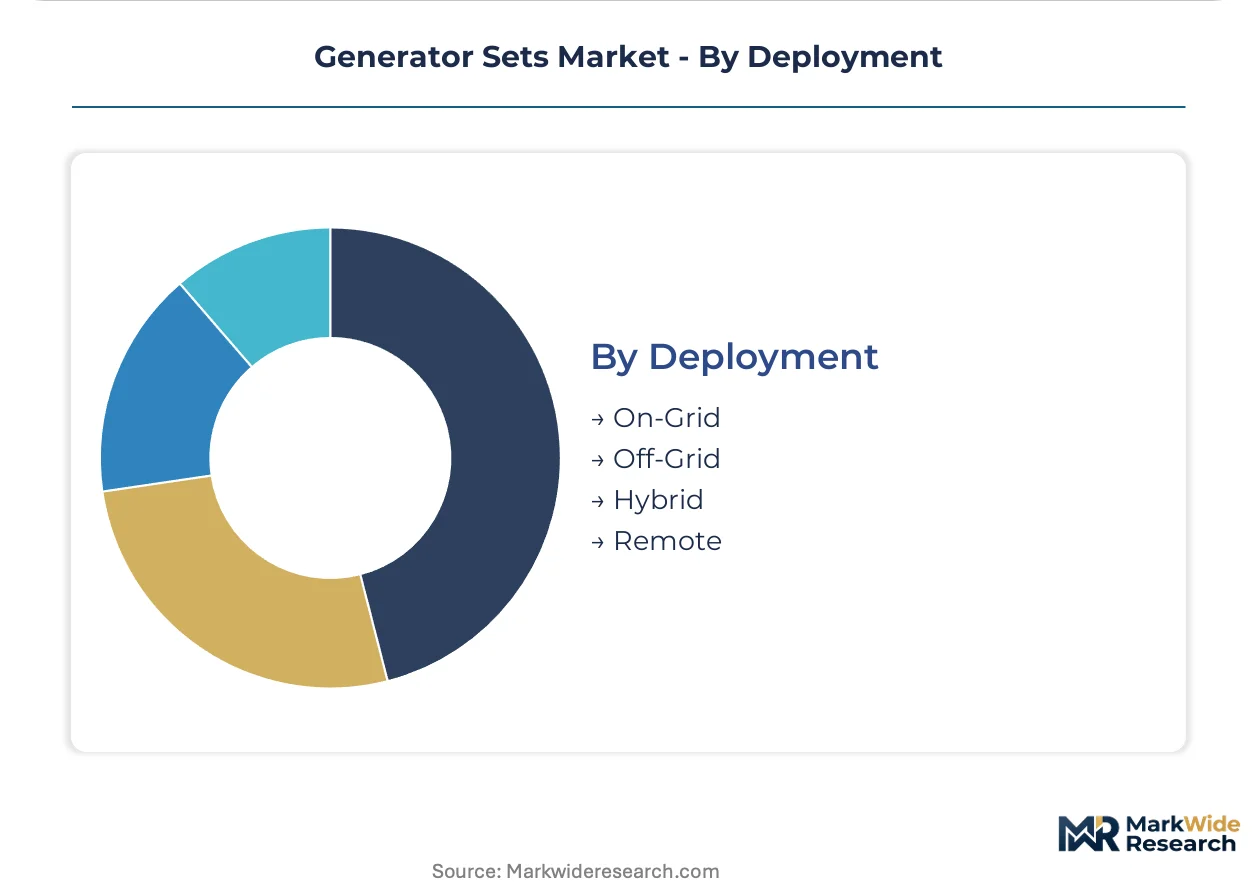
Deployment:
Grid connectivity status determines fuel logistics, runtime engineering, and control system complexity for system designers and operators.
- On-Grid:Backup systems synchronized with utility infrastructure for automatic load transfer during outages. Data centers in Northern Virginia and financial services hubs in Singapore specify these for Tier III and IV uptime certification.
- Off-Grid:Primary power systems for locations without utility extension, common in remote mining and agricultural processing. Indonesian nickel mining concessions and Australian cattle stations rely on continuous-duty diesel or gas configurations.
- Hybrid:Integrated reciprocating engine and battery storage architectures enabling spinning reserve optimization. Microsoft and Amazon Web Services are specifying containerized battery-genset hybrids for new hyperscale facilities in Iowa and Dublin.
- Remote:Satellite-monitored unmanned installations requiring predictive maintenance and fuel logistics coordination. Telecom tower operators across sub-Saharan Africa and rural India deploy these with extended fuel tanks and solar augmentation.
On-grid standby represents the largest installed base. Hybrid deployment is climbing the fastest as lithium-ion costs decline and demand-response revenue streams emerge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for cylinder blocks and heads clusters in China and India, exposing generator set OEMs to regional logistics disruptions while EPA Tier 4 Final and EU Stage V standards reshape engine availability across North America and Europe.
United States
Data center operators in Northern Virginia specify N+1 redundancy with 2-megawatt-class gensets for Tier III and IV uptime certification. EPA Tier 4 Final mandates eliminate non-compliant diesel engines above 751 horsepower from commercial availability. Industrial standby deployments in Texas absorb compliance costs through extended purchase lead times and factory-certified installation requirements.
India
Commercial and industrial facilities across Maharashtra, Gujarat, and Tamil Nadu deploy gensets as primary power during monsoon-related distribution failures. The Central Pollution Control Board enforces emission norms for gensets up to 800 kW, compelling domestic assembly adaptation and localized catalyst supply chains. Foundry and machining clusters in Pune and Chennai supply critical engine components to both domestic OEMs and export markets.
Germany
EU Stage V certification requirements for non-road engines accelerate after-treatment adoption and factory requalification across European manufacturing bases. Energy service companies offer power-as-a-service contracting with fixed-rate agreements covering equipment, fuel, and maintenance. Frankfurt-area data center operators adopt this model to convert backup power from balance-sheet assets to operating expenses.
Saudi Arabia
Giga-project construction and entertainment district electrification under Vision 2030 drive demand for mobile and stationary power rental fleets. Neom and Qiddiya developments mobilize large rental fleets for temporary site electrification during building phases. The national regulator enforces grid connection standards that favor synchronized backup systems for critical infrastructure.
China
Domestic foundry capacity for cast iron and aluminum engine components supplies both local OEMs and multinational manufacturers with cost-competitive sourcing. MIIT emission standards for non-road mobile machinery tighten particulate limits in key industrial provinces. Manufacturing clusters in Shandong and Jiangsu integrate after-treatment systems for both domestic compliance and export certification to EU Stage V markets.
Generator Sets Market Vendor Landscape
Global majors compete with regional champions across engine manufacturing and alternator integration capabilities. The vendor base separates into captive engine producers, independent genset assemblers, and rental fleet operators with vertical service networks. Three archetypes dominate: integrated engine-alternator manufacturers with multi-continent production, specialized enclosure and control system engineers, and power rental companies with dense service technician coverage. Competitive moves center on backward integration into foundry capacity and hybrid system architecture partnerships with battery storage providers.
Among integrated engine manufacturers, Caterpillar Inc., Cummins Inc., and Kohler Co. exemplify the captive production archetype through in-house engine platforms spanning multiple horsepower classes and emission certification tiers. These companies anchor the premium industrial segment where N+1 redundancy specifications and extended runtime engineering command margin premiums over standardized standby units.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Cummins Inc. |
| Generac Holdings Inc. |
| Kohler Co. |
| Atlas Copco AB |
| Briggs & Stratton Corporation |
| Rolls-Royce Holdings plc |
| Doosan Corporation |
| AKSA Power Generation |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap foundries across Shandong and Jiangsu provinces anchor cylinder block and head casting capacity, creating pricing discipline through captive supply relationships while private-equity-rolled-up rental fleet operators in North America and the Middle East squeeze procurement terms through volume aggregation. This ownership fragmentation produces divergent pricing power across diesel engine tiers, with integrated manufacturers defending premium positioning through factory-certified installation networks while independent assemblers compete on unbundled equipment quotes.
Pricing Analysis
Warranty and factory service bundling separates premium industrial genset tiers from unbundled standby equipment quotes, with Caterpillar and Cummins commanding 15-25% premiums through multi-year maintenance contracts while regional assemblers compete on stripped hardware pricing. Three-tier pricing structure across premium, standard, and economy levels reflects EPA Tier 4 Final certification status, paralleling control sophistication, and enclosure engineering grades. Pricing pressure stems from lithium-ion battery substitution in sub-four-hour backup applications, compressing margins in the 50-200 kW standby segment. Commercial facility managers exhibit highest price sensitivity, whereas hyperscale data center operators prioritize N+1 redundancy uptime guarantees over capital cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum group metal supply for diesel oxidation catalysts and selective catalytic reduction systems, exposing OEMs to rhodium and palladium price volatility. Foundry capacity concentrates in China, India, and Germany, with Shandong and Jiangsu provinces feeding both domestic MIIT compliance and EU Stage V export certification. Raw material dependencies span nodular cast iron for engine blocks, copper windings for alternators, and ceramic substrates for after-treatment systems. Tariff exposure on Chinese aluminum castings threatens cost structures for North American genset assemblers. Distribution runs through factory-direct channels for industrial accounts and dense installer networks for residential standby segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The generator sets sector is becoming a vertical-integration race, with backward integration into foundry capacity and forward integration into power-as-a-service contracting representing the decisive levers for margin capture and customer lock-in.
For Market Incumbents: Lock in foundry capacity through long-term offtake agreements or captive production in India and China, insulating against alloy price volatility and regional logistics disruptions. Secure EPA Tier 4 Final and EU Stage V certification pipelines ahead of regulatory deadlines to eliminate non-compliant competitors from commercial availability. Battery energy storage substitution threatens the sub-200 kW standby segment; defend positioning through hybrid genset-battery architecture partnerships with lithium-ion suppliers. For New Entrants and Emerging Players: Capture power-as-a-service contracting whitespace in Germany and Japan, where commercial users seek operating-expense conversion of backup power investments. Target Saudi Vision 2030 giga-project rental fleets, where construction-phase electrification demands outstrip incumbent service technician density. Penetrate through mobile hybrid containerized systems that enable demand-response revenue participation alongside traditional backup functionality. For Investors and Strategic Acquirers: EPA Tier 4 Final enforcement eliminating non-compliant engines above 751 horsepower is the leading indicator that regulatory compliance capabilities will command acquisition premiums. Position for five-to-ten year viability through targets possessing captive engine platforms and factory-certified installation networks. Monitor hybrid system adoption rates at hyperscale data center developments as the inflection signal for technology transition pace.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foundry Capacity | Captive cylinder block casting insulates Cummins and Caterpillar from Shandong logistics disruptions and alloy price spikes. |
| Hybrid Genset-Battery Architecture Development | Containerized integration with lithium-ion storage enables Microsoft and Amazon Web Services demand-response revenue participation. |
| Power-as-a-Service Contracting Expansion | Fixed-rate agreements covering equipment, fuel, and maintenance convert balance-sheet assets to operating expenses for Frankfurt data centers. |
| EPA Tier 4 Final Certification Acceleration | Factory requalification ahead of enforcement deadlines eliminates non-compliant competitors from above-751-horsepower commercial availability. |
| Rental Fleet Density Buildout in Saudi Arabia | Service technician concentration at Neom and Qiddiya captures Vision 2030 construction-phase electrification demand. |
Methodological Framework
Multi-period observation of EPA Tier 4 Final compliance timelines, EU Stage V certification progressions, and data center hyperscaler capex disclosures anchored the trend analysis, supplemented by interviews with plant engineers at industrial facilities, procurement directors at rental fleet operators, after-treatment system suppliers, and EPC contractors. Primary fieldwork across Maharashtra, Virginia, and Frankfurt validated demand patterns for grid-backup and prime power applications. Secondary sources included EIA power reliability data, Central Pollution Control Board emission norm filings, customs records for engine component trade flows, and SEC disclosures from publicly traded OEMs. Bottom-up unit economics triangulated against top-down market sizing from foundry capacity and alternator production estimates.
Segment-weighting applied product type, fuel chemistry, end-user vertical, and deployment configuration as the dimensional framework, with industrial generators receiving proportionate emphasis reflecting data center N+1 redundancy procurement acceleration. CAGRs derived from regression analysis of historical installation data against projected hyperscale facility buildout, renewable natural gas pathway expansion, and battery substitution thresholds. Forecast inputs incorporated MIIT emission standard tightening timelines in China and Saudi Vision 2030 project mobilization schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium-ion cost decline trajectories, carbon pricing implementation pace, and South African platinum group metal supply interruptions. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and foundry capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Generators
North America Gasoline Gensets Market
Generators
Africa Portable Generator Market
Generators
Gas Generator Sets Market
Generators
South America Generator Sets Market
Generators
Residential Gas Generator Market
Generators
China Generator Sets Market
Generators
Middle-East and Africa Generator Sets Market
Generators
Asia-Pacific Gas Generator Market
Generators
Asia-Pacific Diesel Generator Market
Generators
Middle-East and Africa Portable Generator Market
Generators
Power Generator Rental Market
Generators
Asia-Pacific Portable Generator Market
Generators
China Diesel Generator Market
Generators
Generator (Up to 20 Kva) Market
Generators
Middle East Portable Generator Market
Generators
Industrial Generator Sets Market