
 Consumer Battery Market | 2026-2036
Consumer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Battery Market Intelligence
High energy density tiering is redrawing competitive boundaries in consumer cells. LG Energy Solution leverages its cylindrical cell expertise to dominate power tool and e-mobility sub-supply. Panasonic anchors premium electronics segments through sustained cobalt-reduction chemistry programs. Samsung SDI differentiates via prismatic form factor specialization for slim-device OEMs.
A consumer battery is an electrochemical energy storage device engineered for single-user or household applications, typically operating at voltages between 1.2V and 48V with capacities spanning from sub-1000 mAh coin cells to 5000 mAh-plus lithium-ion packs, manufactured through electrode coating, calendering, and electrolyte filling processes to deliver portable power for cordless operation. Lithium-ion chemistry leads value generation due to its gravimetric energy density advantage, while alkaline retains volume dominance in disposable primary markets. The above-5000 mAh capacity band captures the fastest expansion as cordless power tools and residential energy storage systems displace corded alternatives.
China's SAMR enforces GB standards for cell cycle life and thermal stability, while the EU Battery Regulation mandates recycled content thresholds and digital passports for market access. Japan's METI directs JIS standards for button cell safety in compact electronics. Stakeholders must monitor how divergent recycling mandates reshape raw material procurement geography and cell design specifications.
Market Dynamics
Energy density tiering is fragmenting procurement patterns as cordless power tool OEMs and residential storage integrators demand divergent cell specifications from overlapping supplier pools.
Growth Catalysts
- Cordless power tool electrification:Professional contractors are retiring gas-powered equipment fleets, creating pull-through demand for 18V-40V lithium-ion packs with rapid-charge capabilities.
- EU Battery Regulation recycled content mandates:The delegated act specifying minimum recovered lithium and cobalt thresholds is forcing OEMs to secure long-term offtake from European recycling infrastructure.
- Solid-state electrolyte pilot production:South Korean and Japanese material suppliers are scaling oxide and sulfide electrolyte deposition capacity for 2027-2028 automotive crossover applications.
Market Restraints
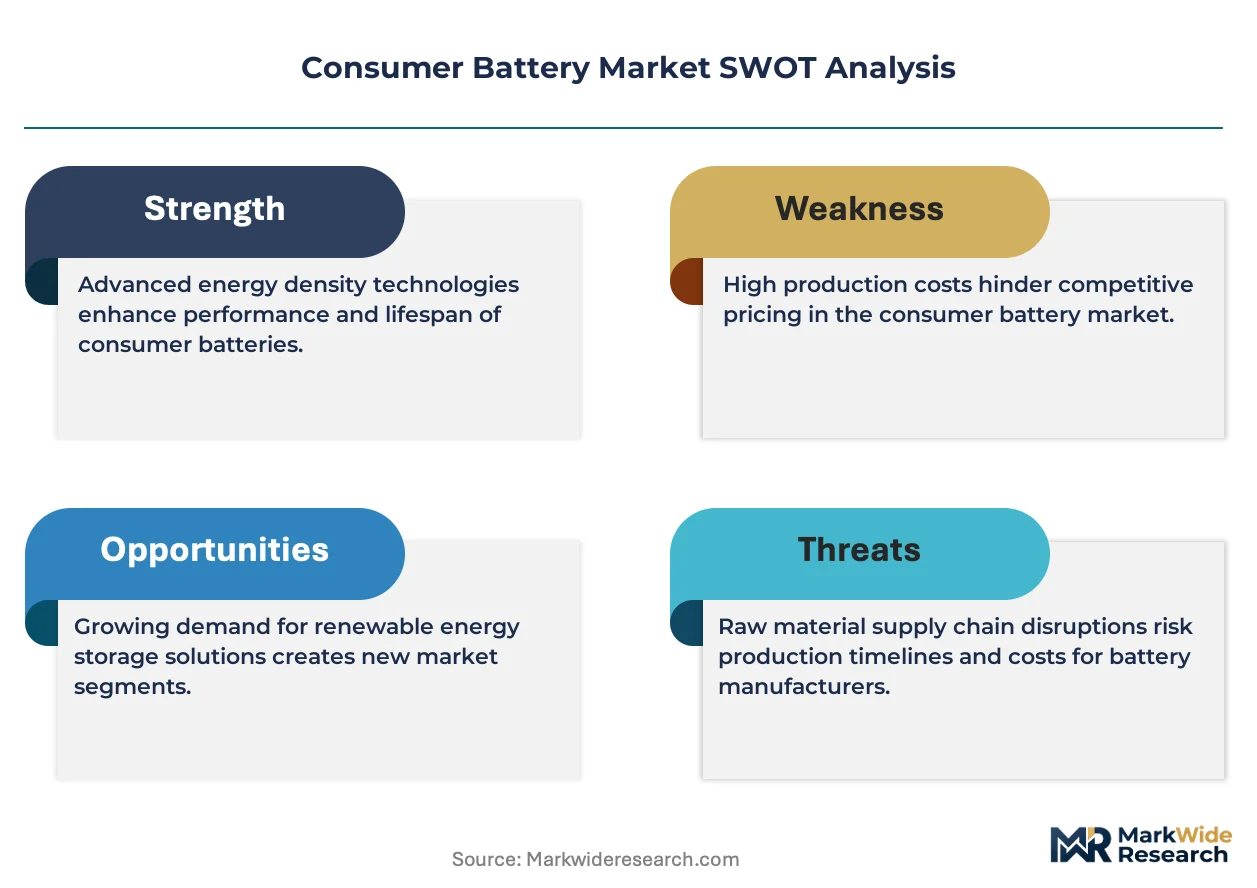
- Cobalt price volatility:Artisanal mining concentration in the Democratic Republic of Congo exposes cathode precursor costs to ESG-driven supply suspensions.
- East Asian cell production concentration:Over 70% of cylindrical and prismatic lithium-ion capacity sits within 500 kilometers of Seoul and Shanghai, creating single-point-of-failure risk.
- Alkaline chemistry energy density ceiling:Zinc-manganese primary cells cannot exceed 150 Wh/kg, permanently capping them to low-drain remote sensor and flashlight applications.
Strategic Opportunities
- India BIS certification gap:Domestic cell assembly lines serving smartphone and laptop OEMs remain undersupplied as import substitution policies accelerate local manufacturing incentives.
- Residential solar-plus-storage bundling:German and Italian installers are attaching 5-15 kWh battery systems to rooftop photovoltaic sales, creating attached-growth channels for consumer-grade cells.
- Sodium-ion chemistry crossover:CATL and BYD are transferring cylindrical form factor expertise from lithium lines to sodium-ion pilots for sub-1000 cycle applications.
Industry Challenges
- Electrolyte formulation talent scarcity:Experienced scientists capable of optimizing carbonate additive blends for high-voltage cathodes command premium compensation across Shenzhen and Nagoya.
- UN 38.3 certification backlog:Third-party testing laboratory capacity constraints in Hamburg and Shanghai are extending cell shipment approval timelines by 6-10 weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Battery Market |
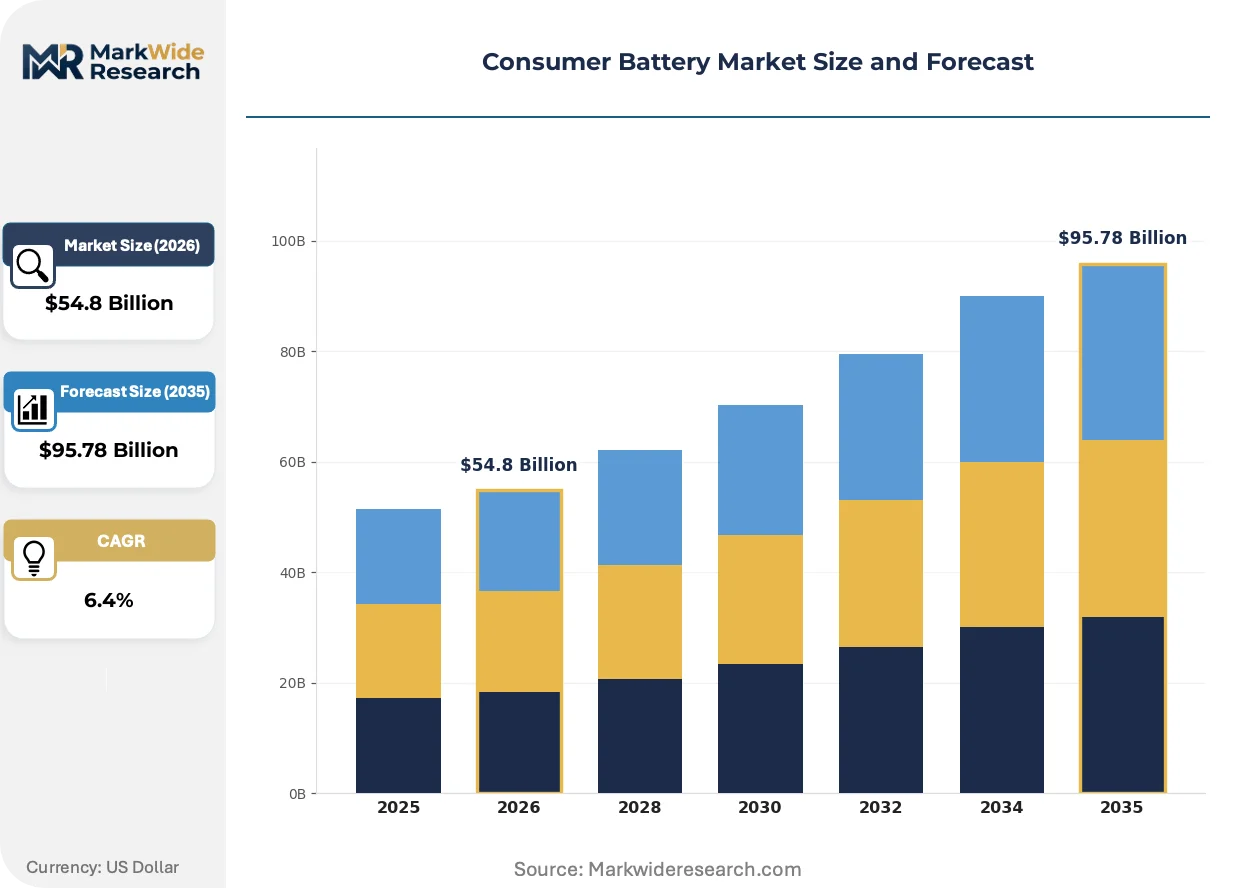
| Market Size in 2026 | $54.8 Billion |
| Market Size in 2035 | $95.78 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Alkaline, Lead-acid Application: Electronic Devices, Power Tools, Electric Vehicles, Renewable Energy Storage Capacity: Below 1000 mAh, 1001-3000 mAh, 3001-5000 mAh, Above 5000 mAh Form Factor: Cylindrical, Prismatic, Button Cell, Packaged Modules |
| Companies Covered | SK On, EVE Energy, CATL, Sunwoda, Samsung SDI, BYD, Panasonic, Gotion High-Tech, LG Energy Solution, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Battery Market Strategic Shifts & Innovations
Cell architecture standardization is colliding with chemistry diversification as OEMs seek interchangeability without sacrificing chemistry-specific performance optimization.
Silicon-dominant anodes are decomposing the graphite supply chain's century-long dominance in consumer cells. Power tool manufacturers are qualifying 10-15% silicon oxide blends for 2025-2026 product cycles. The technology is decomposing incumbent anode supplier relationships and forcing electrode coating equipment retrofits across cylindrical cell lines.
China's GB 31241-2022 thermal runaway propagation standard is mandating 5-minute alarm intervals before cell venting in portable electronics. SAMR enforcement has triggered redesigns of multi-cell pack architectures. Premium laptop OEMs are responding by specifying ceramic-coated separators and phase-change material intercell barriers.
Direct-to-installer distribution is bypassing traditional electronics wholesale channels for residential storage systems. German solar installers now source 48V rack-mounted battery modules directly from South Korean cell packagers. This pattern is most visible in Bavaria and Baden-Württemberg where installer consolidation has created purchasing cooperatives with sufficient volume to negotiate master service agreements.
Consumer Battery Market Segmentation
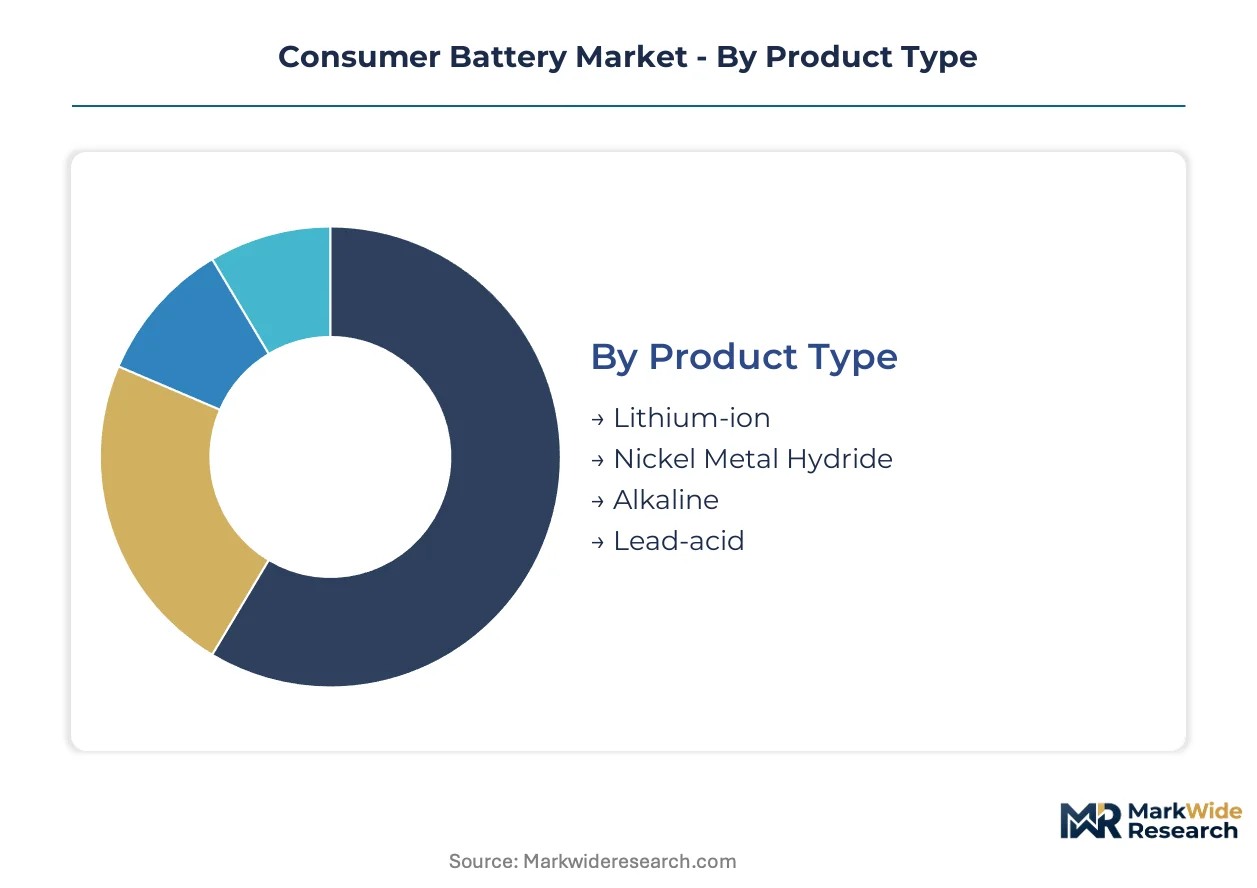
Consumer battery procurement channels diverge sharply by segment. Electronics OEMs source through consolidated distributors, while power tool manufacturers negotiate direct cell offtake from South Korean packagers. Residential storage integrators increasingly bypass wholesale entirely, purchasing rack-mounted modules straight from Chinese assembly lines.
Product Type:
Lithium-ion cells flow through premium electronics distributors, while alkaline channels through mass retail. Nickel metal hydride and lead-acid serve specialized industrial procurement networks with longer contract cycles.
- Lithium-ion:Rechargeable chemistry deploying layered oxide cathodes and graphite or silicon-blend anodes, achieving 150-250 Wh/kg gravimetric density. Demand concentrates in Shenzhen and Seoul manufacturing corridors for smartphone and laptop OEMs, driven by cordless power tool electrification requiring 18V-40V rapid-charge packs.
- Alkaline:Primary zinc-manganese dioxide cells with aqueous potassium hydroxide electrolyte, delivering 1.5V nominal voltage and 100-150 Wh/kg density. Volume concentrates in disposable markets across German and US retail channels for remote sensors and flashlights, constrained by permanent energy density ceilings below lithium alternatives.
- Nickel Metal Hydride:Rare-earth alloy anode chemistry retaining niche positioning in hybrid vehicle auxiliary systems and medical devices requiring stable voltage discharge curves.
- Lead-acid:Mature flooded and valve-regulated designs serving stationary backup power and entry-level residential storage in price-sensitive Indian and Southeast Asian markets.
By volume, alkaline leads. By growth pace, lithium-ion is expanding most quickly.
Application:
Cost tiering separates consumer-grade electronics cells from industrial power tool packs and utility-scale storage modules. Premium pricing attaches to automotive-qualified cells, while economy tiers serve disposable electronics.
- Electronic Devices:Smartphones, laptops, tablets, and wearables demanding slim-form-factor cells with 500-1000 cycle life. Procurement flows through consolidated distributors in Taipei and Seoul serving Apple, Samsung, and Dell supply chains.
- Power Tools:Professional-grade 18V-40V battery packs for cordless drills, saws, and lawn equipment. Milwaukee and DeWalt OEMs specify cylindrical 21700 cells from LG Energy Solution and Samsung SDI with 15-minute fast-charge protocols.
- Electric Vehicles:Two-wheeler and low-speed EV applications in Indian and Southeast Asian markets, plus auxiliary 12V systems in passenger cars.
- Renewable Energy Storage:Residential solar-plus-storage bundling in German and Italian installer channels, driving attached-growth for 5-15 kWh lithium iron phosphate systems.
Electronic devices capture the largest revenue pool. Renewable energy storage shows the steepest expansion trajectory.
Capacity:
Volume scale inversely correlates with margin percentage. Sub-1000 mAh cells ship in billion-unit batches at single-digit margins, while above-5000 mAh packs command premium pricing through direct installer channels.
- Below 1000 mAh:Coin cells and slim prismatic designs for hearing aids, smartwatches, and IoT sensors. Japan's METI JIS standards govern button cell safety in compact electronics, with Sony and Panasonic anchoring supply.
- 1001-3000 mAh:Standard smartphone and power tool battery packs, the workhorse capacity band where Chinese cell makers achieve maximum manufacturing scale.
- 3001-5000 mAh:Premium laptop and professional power tool applications, with Samsung SDI prismatic specialization targeting slim-device OEMs.
- Above 5000 mAh:Residential storage systems and high-end power tool platforms displacing corded alternatives. CATL and BYD cylindrical expertise transfers to this band, with German solar installers sourcing directly from South Korean packagers.
Below 1000 mAh dominates unit shipments. Above 5000 mAh gains share fastest.
Form Factor:
Supply concentration shapes procurement flexibility. Cylindrical cells offer maximum supplier interchangeability, while prismatic designs lock OEMs into specific coating equipment and pack architectures.
- Cylindrical:Standardized 18650 and 21700 formats enabling supplier switching between LG Energy Solution, Panasonic, and Samsung SDI. China's GB 31241-2022 thermal runaway standards mandate 5-minute alarm intervals, triggering ceramic-coated separator adoption.
- Prismatic:Aluminum-cased flat cells optimized for slim smartphones and laptops. Samsung SDI differentiation in this format creates switching costs for OEMs through customized pack integration.
- Button Cell:Coin and pill formats for hearing aids and wearables, with Panasonic and Varta commanding premium positioning through mercury-free chemistry compliance.
- Packaged Modules:Pre-assembled 48V rack systems for residential storage, where German installer cooperatives negotiate master service agreements directly with South Korean cell packagers.
Cylindrical leads in production flexibility. Packaged modules are climbing the fastest as direct-to-installer distribution bypasses traditional channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing clusters within 500 kilometers of Seoul and Shanghai control over 70% of cylindrical and prismatic lithium-ion capacity. Procurement geography now follows divergent regulatory mandates rather than pure cost optimization.
China
Smartphone OEMs and power tool assemblers drive cylindrical cell demand through Shenzhen and Dongguan corridors. SAMR enforces GB 31241-2022 thermal runaway propagation standards mandating 5-minute alarm intervals before cell venting. CATL and BYD transfer cylindrical expertise to sodium-ion pilots in Fujian and Guangdong for sub-1000 cycle applications.
South Korea
Milwaukee and DeWalt specify 21700 cells with 15-minute fast-charge protocols for professional power tool fleets. MFDS aligns with international testing protocols while Seoul maintains R&D tax incentives for solid-state electrolyte development. Busan-Ulsan manufacturing corridors host LG Energy Solution and Samsung SDI cylindrical cell lines serving cordless equipment OEMs.
Germany
Residential solar-plus-storage bundling creates attached-growth channels as installers attach 5-15 kWh battery systems to rooftop photovoltaic sales. The EU Battery Regulation mandates recycled content thresholds and digital passports for market access. Bavarian and Baden-Württemberg installer cooperatives negotiate master service agreements directly with South Korean cell packagers.
United States
Power tool electrification retires gas-powered contractor equipment fleets, pulling 18V-40V lithium-ion packs with rapid-charge capabilities. OSHA and EPA frameworks govern workplace battery safety and recycling infrastructure development. Texas and California distribution hubs consolidate incoming cylindrical cell shipments from East Asian suppliers for domestic pack assembly.
Japan
Premium electronics segments sustain demand for cobalt-reduction chemistry programs in slim-form-factor devices. METI directs JIS standards for button cell safety in compact electronics and hearing aids. Nagoya and Kanto manufacturing clusters anchor Panasonic's mercury-free chemistry compliance for coin cell production.
Consumer Battery Market Key Industry Players
Concentration sits with diversified chemistry specialists and cylindrical form factor leaders. The vendor base splits between integrated material-to-cell producers and packagers dependent on external cathode supply. Three archetypes dominate: South Korean cylindrical specialists, Chinese scale-driven integrators, and Japanese premium chemistry innovators. Competitive moves center on backward integration into cathode precursor production and direct-to-installer distribution bypassing wholesale channels.
Within the South Korean specialist tier, LG Energy Solution and Samsung SDI exemplify cylindrical cell expertise serving power tool OEMs. CATL anchors the Chinese integrator archetype through scale-driven production corridors. Panasonic occupies the premium chemistry position through sustained cobalt-reduction programs targeting electronics segments.
| Leading Market Players |
|---|
| SK On |
| EVE Energy |
| CATL |
| Sunwoda |
| Samsung SDI |
| BYD |
| Panasonic |
| Gotion High-Tech |
| LG Energy Solution |
| Others |
Cost & Logistics Intelligence
Silicon-dominant anodes replacing graphite feedstocks are simultaneously redrawing procurement geography toward South Korean and Japanese material suppliers and compressing electrode coating cost structures across cylindrical cell lines. This substitution dynamic concentrates pricing power with oxide and sulfide electrolyte developers while forcing legacy anode producers into defensive margin positioning.
Pricing Analysis
EU Battery Regulation recycled content mandates dictate the pricing tier structure across premium, standard, and economy levels. Certification-grade cells with verified lithium and cobalt recovery thresholds command 15-20% premia over uncertified alternatives. Cost compression in standard-tier cylindrical cells is intensifying because Chinese integrators are transferring lithium-ion scale advantages to sodium-ion pilots. Power tool OEMs show least price sensitivity due to rapid-charge protocol requirements, while residential storage installers negotiate aggressively on 48V rack-mounted modules.
Supply Chain Analysis
China and South Korea anchor cylindrical and prismatic cell fabrication, with Japan retaining premium chemistry specialization. Cathode precursor supply draws from Congolese cobalt and Chilean lithium deposits, creating ESG-driven suspension exposure. Single-source vulnerability concentrates in East Asian separator and electrolyte additive production. Distribution runs through consolidated electronics distributors for smartphone OEMs and direct-to-installer channels for German solar-plus-storage bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumer battery markets sit in early-cycle expansion as cordless power tool electrification and residential solar-plus-storage bundling create attached-growth channels with penetration headroom in professional contractor and installer segments.
For Market Incumbents: Consolidate cylindrical cell expertise through backward integration into cathode precursor production, particularly securing European recycling infrastructure offtake to meet EU Battery Regulation thresholds. Add ceramic-coated separator capacity in South Korean corridors to preempt GB 31241-2022 compliance costs. Lock direct-installer relationships in Bavaria and Baden-Württemberg before channel consolidation completes. For New Entrants and Emerging Players: BIS certification fast-tracks for Indian domestic cell assembly lines present immediate white-space access as smartphone and laptop OEMs accelerate import substitution. Target undersupplied sodium-ion cylindrical pilots for sub-1000 cycle applications where CATL and BYD have not yet established procurement lock-in. Pursue German installer cooperative master service agreements as the most penetrable downstream channel. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European recycling infrastructure operators holding long-term offtake contracts with power tool OEMs. Five-to-ten-year viability hinges on cathode chemistry diversification beyond cobalt-heavy layered oxides. Watch solid-state electrolyte pilot production scale-up in South Korean and Japanese corridors as the inflection signal for next-generation cell architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captures margin from Congolese cobalt and Chilean lithium supply chains while meeting EU recycled content mandates. |
| Ceramic-Coated Separator Capacity Expansion | Enables GB 31241-2022 thermal runaway compliance for premium laptop and power tool OEM specifications. |
| Direct-to-Installer Distribution Buildout | Bypasses wholesale channel capture in German solar-plus-storage bundling through Bavarian purchasing cooperatives. |
| Sodium-Ion Cylindrical Form Factor Transfer | Extends existing lithium-ion coating equipment to sub-1000 cycle residential storage and low-speed EV applications. |
| European Recycling Infrastructure Offtake | Secures delegated act compliance for minimum recovered lithium and cobalt thresholds in power tool packs. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SAMR enforcement bulletins, EU delegated act drafts, and UN 38.3 testing laboratory capacity reports. Cell manufacturing executives, power tool OEM procurement directors, German solar installer cooperative managers, and electrolyte formulation scientists provided structured input. Customs data from Shenzhen and Busan-Ulsan corridors, plus SEC filings from diversified battery producers, supplied volume and value triangulation against bottom-up capacity modeling.
Segmentation dimensions modeled span lithium-ion, alkaline, nickel metal hydride, and lead-acid chemistries; electronic devices, power tools, electric vehicles, and renewable energy storage applications; below-1000 mAh through above-5000 mAh capacity tiers; and cylindrical, prismatic, button cell, and packaged module form factors. CAGRs were derived from production capacity expansion schedules and OEM offtake contract visibility across the projection horizon. Solid-state electrolyte pilot timelines and sodium-ion chemistry crossover rates provided industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained East Asian manufacturing concentration and stable EU Battery Regulation enforcement timelines; material deviation would warrant model refresh. Cobalt price volatility from ESG-driven supply suspensions, UN 38.3 certification backlogs extending shipment approvals, or divergent recycling mandates reshaping raw material procurement geography could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Bio Based Battery Market
Batteries
N-Type Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Nickel Cadmium Battery Market
Batteries
US Motive Lead Acid Battery Market
Batteries
India Battery Cell Market
Batteries
India Lead-Acid Battery Market
Batteries
Disposable Batteries Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Malaysia Battery Market
Batteries
Floor Scrubber Battery Market
Batteries
Watch Battery Market
Batteries
Mobile Battery Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market