
 N-Type Battery Market | 2026-2036
N-Type Battery Market Size, Share, and Industry Trends Forecast 2026-2036
N-Type Battery Market Insights
Multi-source cathode procurement is consolidating as tier-one cell producers tighten supply-chain control. CATL leverages captive lithium refining and integrated precursor capacity to secure feedstock margins. LG Energy Solution anchors its position through joint-venture cathode plants in South Korea and Poland. Samsung SDI differentiates via silicon-anode R&D pipelines and premium automotive qualification tracks.
N-type batteries employ negatively doped silicon substrates with phosphorus diffusion to achieve higher carrier lifetimes and lower degradation than P-type counterparts, yielding conversion efficiencies above 25% in photovoltaic-integrated storage systems. Solid-state chemistry variants command premium positioning due to thermal stability gains and reduced fire-risk profiles in electric vehicle architectures. Grid storage applications sustain the fastest deployment velocity as utility-scale developers prioritize cycle-life duration over energy density metrics. Flow battery configurations occupy niche industrial backup roles where discharge duration exceeds four hours.
FDA guidelines for battery-powered medical devices and EPA hazardous-material transport rules shape US market access requirements, while China's GB standards and MIIT industry catalogs dictate cell certification thresholds for domestic manufacturers. The EU Battery Regulation and CE marking frameworks impose carbon-footprint disclosure and recycled-content mandates that European-bound suppliers must navigate. Stakeholders should monitor evolving chemistry-class thresholds in national subsidy schemes and pre-position qualification data for next-generation solid-state platforms before compliance windows tighten.
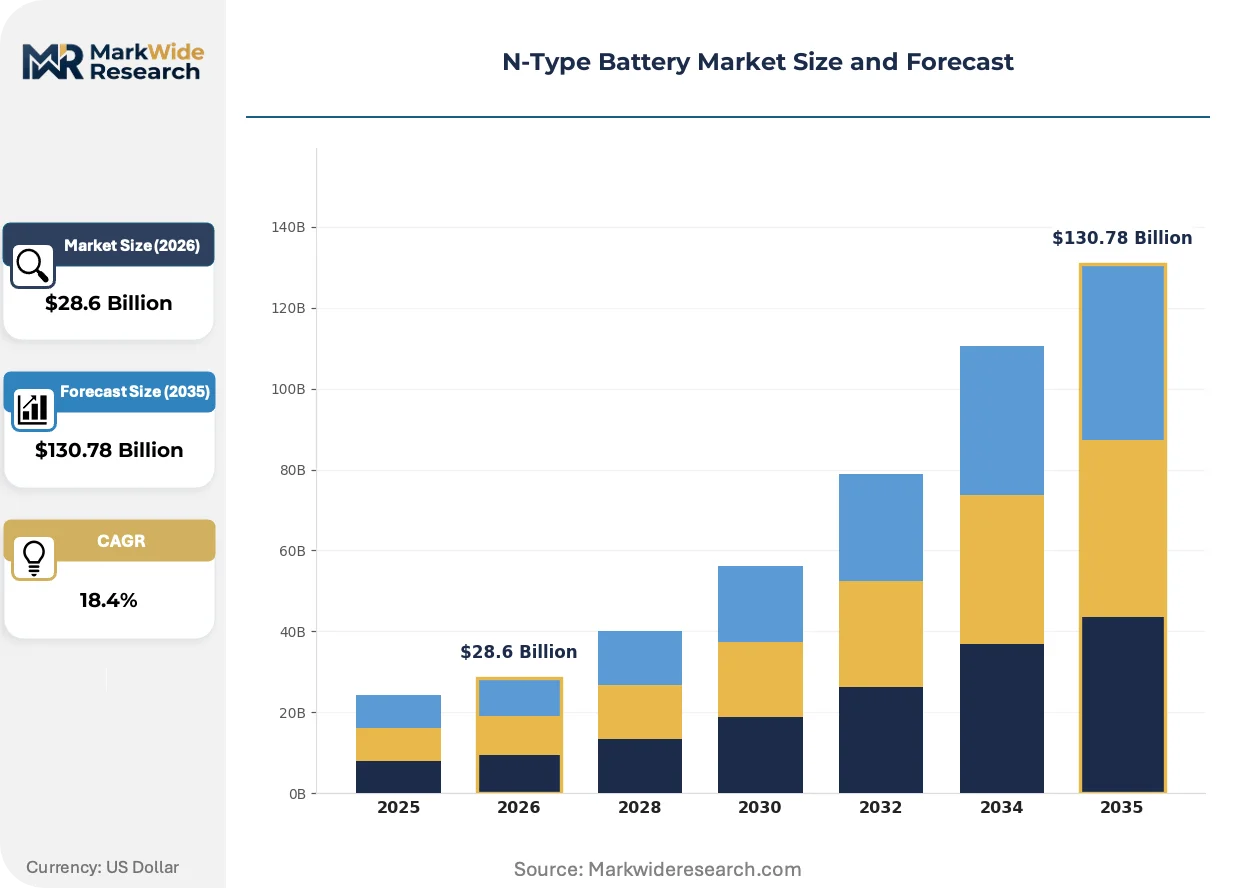
Market Dynamics
China's updated GB standards for battery safety and energy density are compressing product qualification cycles, forcing cell manufacturers to accelerate chemistry validation and manufacturing scale-up simultaneously.
Growth Catalysts
- Automotive platform electrification:Electric vehicle OEMs are mandating longer-range configurations that favor high-efficiency N-type architectures, pulling procurement volumes upward.
- EU Battery Regulation carbon mandates:Recycled-content thresholds and carbon-footprint disclosure requirements are advantaging suppliers with closed-loop precursor capabilities.
- Solid-state thermal stability:Reduced fire-risk profiles in solid-state variants are unlocking premium automotive qualification tracks previously inaccessible to conventional lithium-ion.
Market Restraints
- Lithium feedstock volatility:Spodumene and brine concentrate pricing swings compress cathode precursor margins for non-integrated producers.
- East Asian supply concentration:South Korean cathode material hubs and Chinese cell assembly corridors create single-point vulnerability for European and North American offtakers.
- Silicon-anode expansion limits:Volume expansion during lithiation cycles degrades cell longevity, constraining silicon loading percentages below theoretical maximums.
Strategic Opportunities
- Grid storage cycle-life premium:Utility-scale developers in Texas and California are prioritizing duration over density, opening procurement channels for N-type configurations optimized for 8,000+ cycles.
- US IRA domestic content credits:Battery cell and module manufacturing tax credits are incentivizing North American assembly investments.
- Photovoltaic-battery convergence:N-type silicon substrates are absorbing bifacial panel architectures, creating unified supply chains for solar-plus-storage installations.
Industry Challenges
- Solid-state electrolyte manufacturing scale-up:Ceramic and sulfide electrolyte processing requires dry-room infrastructure beyond current lithium-ion asset bases.
- Multi-jurisdiction certification lag:Parallel qualification under China's MIIT catalogs, EU CE marking, and US UN38.3 transport rules extends time-to-revenue by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Type Battery Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $130.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Li-ion, Li-Po, Solid-State, Flow Battery End User: Automotive, Consumer Electronics, Renewable Energy, Industrial Technology: Battery Management Systems, Energy Density Enhancement, Thermal Management, Fast Charging Application: Grid Storage, Portable Devices, Electric Vehicles, Backup Power |
| Companies Covered | CATL, LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI, BYD Company, SK On, Tesla, SVOLT Energy Technology, Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Type Battery Market Trends and Innovations
Process integration and chemistry substitution are compressing cost structures while regulatory pressure on carbon intensity reconfigures supply chain geography. Three developments are commanding strategic attention.
Phosphorus-doped silicon substrates are absorbing manufacturing investment from P-type legacy lines as cell producers chase conversion efficiencies above 25% in photovoltaic-integrated storage systems. Automotive OEMs with 800-volt platforms are qualifying these architectures fastest. The technology is absorbing capacity that would otherwise serve legacy lead-acid replacement markets.
China's MIIT industry catalogs are tightening cell certification thresholds for domestic manufacturers, disqualifying lower-density chemistries from national subsidy schemes. This industrial consequence is accelerating R&D redirection toward solid-state platforms. Tier-one producers are responding by pre-positioning qualification data before compliance windows tighten further.
Automotive buyers are consolidating supplier panels from six-plus vendors to three or fewer qualified cell sources per platform, compressing switching flexibility. This concentration is displacing spot-market procurement in favor of multi-year offtake agreements with volume commitments. The pattern is most visible in German and South Korean automotive supply chains.
N-Type Battery Market Segmentation
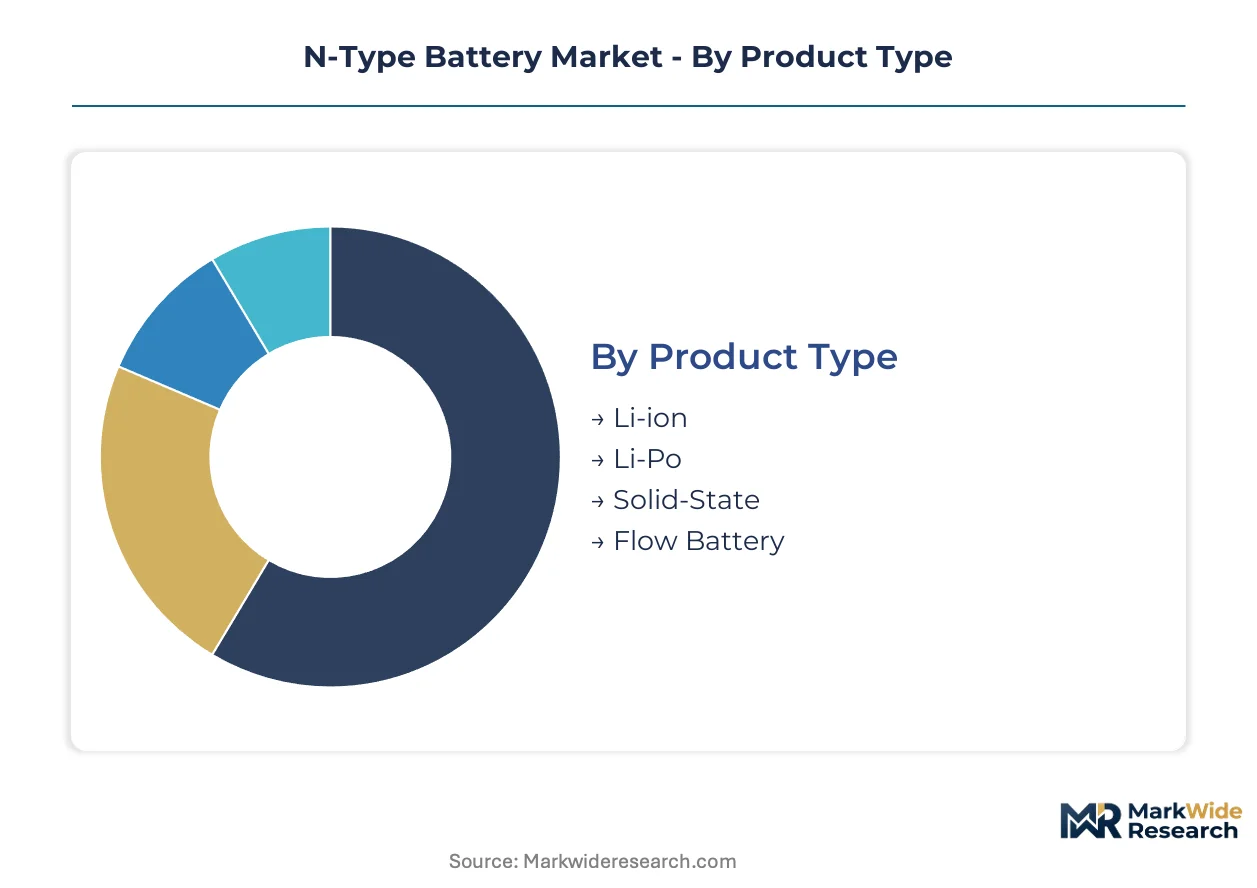
N-type battery architectures fragment across chemistry classes, end-use specifications, and integration complexity. Procurement patterns diverge sharply between automotive qualification tracks and utility-scale deployment cycles. Understanding these fault lines clarifies where margin pools concentrate and which technology transitions threaten incumbent positions.
Product Type:
Supply concentration in cathode precursor refining and electrolyte manufacturing tilts competitive advantage toward chemistry families with captive feedstock control.
- Li-ion:NCM and LFP variants dominate current manufacturing capacity. CATL and LG Energy Solution anchor procurement volumes through integrated precursor plants in China and South Korea. Automotive OEMs with 800-volt platforms are qualifying these cells fastest for long-range configurations.
- Solid-State:Ceramic and sulfide electrolyte variants command premium positioning due to thermal stability gains. Samsung SDI differentiates through silicon-anode R&D pipelines targeting premium automotive qualification tracks previously inaccessible to conventional lithium-ion.
- Li-Po:Pouch configurations serve consumer electronics where form-factor flexibility outweighs energy density metrics.
- Flow Battery:Vanadium and zinc-bromine systems occupy niche industrial backup roles where discharge duration exceeds four hours.
Li-ion absorbs the bulk of installed capacity; solid-state is expanding most quickly as qualification timelines compress.
End User:
Cost tier differentiation separates qualification-intensive automotive contracts from price-sensitive industrial procurement.
- Automotive:Electric vehicle OEMs mandate longer-range configurations that favor high-efficiency N-type architectures. Platform electrification pulls procurement volumes upward through multi-year offtake agreements with volume commitments.
- Renewable Energy:Utility-scale developers in Texas and California prioritize cycle-life duration over energy density metrics. Grid storage applications sustain deployment velocity for configurations optimized for 8,000-plus cycles.
- Consumer Electronics:Smartphone and laptop manufacturers drive demand for slim-form-factor cells with moderate discharge rates.
- Industrial:Forklift and material-handling equipment operators favor lead-acid replacement cycles with lower upfront capital requirements.
Automotive contracts command the steepest expansion trajectory; industrial procurement remains most price-elastic.
Technology:
Customer type segmentation separates integrated platform providers from component suppliers licensing intellectual property.
- Battery Management Systems:Silicon carbide gate drivers and model-predictive control algorithms enable cell-level monitoring precision. Tier-one automotive suppliers embed these systems within platform architectures to satisfy functional safety standards.
- Fast Charging:800-volt architectures and cooled cable assemblies reduce dwell times at charging stations. Korean and German automotive supply chains are consolidating supplier panels around qualified fast-charging cell sources.
- Energy Density Enhancement:Silicon-anode loading and high-nickel cathode formulations push gravimetric performance.
- Thermal Management:Liquid cooling loops and phase-change materials stabilize operating temperatures in high-discharge scenarios.
Battery Management Systems capture the largest share of technology licensing revenue; fast charging is climbing the fastest as infrastructure deployment accelerates.
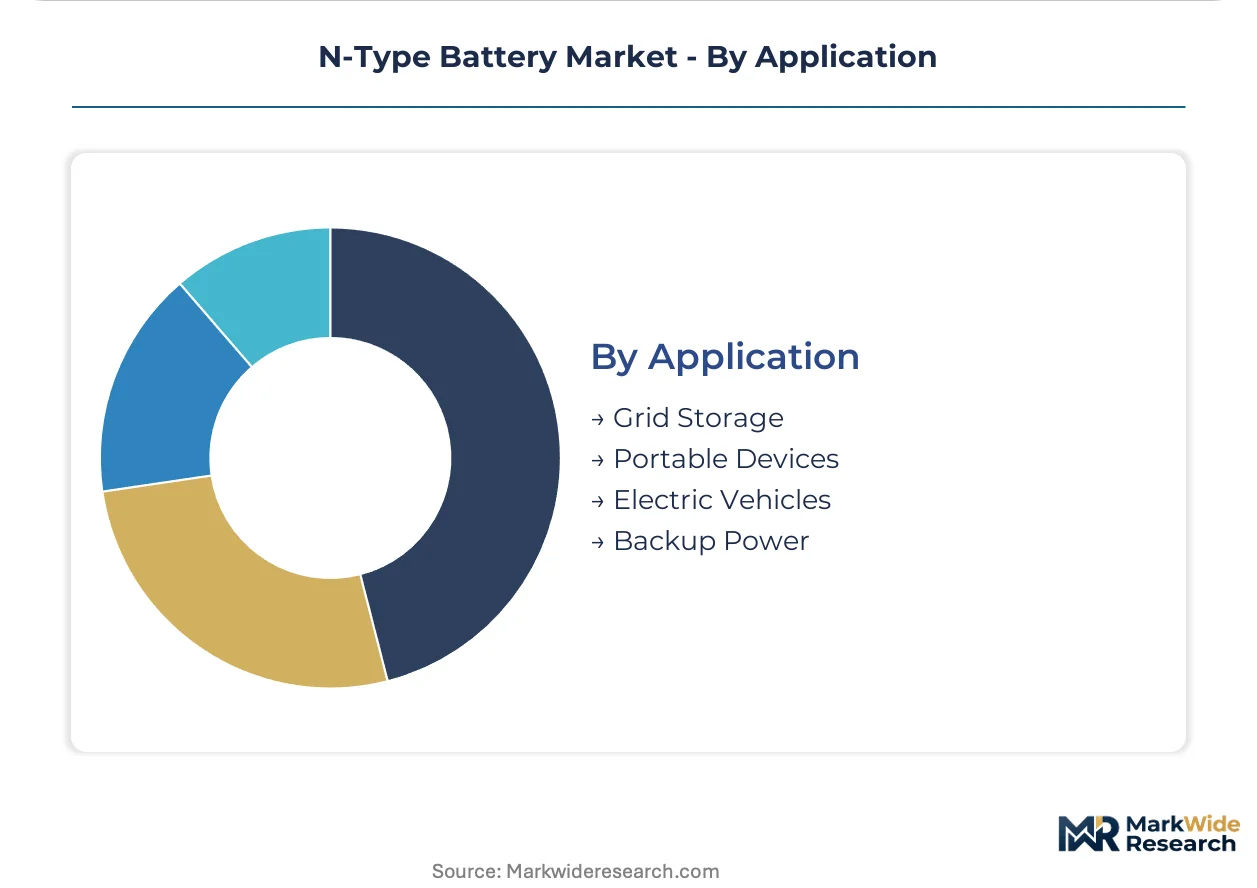
Application:
Geography dictates deployment priority, with East Asian manufacturing clusters serving export markets and domestic installations differently.
- Electric Vehicles:Passenger car and commercial truck platforms absorb the majority of high-efficiency cell output. China's GB standards and MIIT industry catalogs compress qualification cycles for domestic manufacturers.
- Grid Storage:Utility-scale battery installations in California and Texas prioritize duration over density. Developers favor N-type configurations with extended cycle-life warranties for revenue-stacking strategies.
- Portable Devices:Power tools and medical equipment require compact energy sources with predictable discharge curves.
- Backup Power:Data center and telecommunications operators specify four-hour discharge capabilities for outage protection.
Electric vehicles anchor current demand volume; grid storage is gaining share fastest as interconnection queues clear.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lithium brine deposits in Chile's Atacama Desert and hard-rock spodumene mines in Western Australia anchor raw-material flows for cathode precursor refining. These feedstock localities concentrate upstream bargaining power in South American and Australian mining jurisdictions before chemical processing shifts to East Asian cell manufacturing corridors.
China
Domestic EV manufacturers are absorbing high-efficiency cell output for 800-volt platform architectures. MIIT industry catalogs and updated GB standards compress qualification cycles for domestic producers. The Yangtze River Delta and Pearl River Delta manufacturing corridors concentrate cathode precursor refining and cell assembly capacity.
South Korea
Automotive OEMs in Germany and the United States source qualified cells through multi-year offtake agreements. The country's national industrial regulator enforces battery safety certification through KBA-aligned testing protocols. The Busan-Ulsan industrial complex anchors cathode material production for export markets.
Germany
Premium automotive platforms mandate solid-state qualification timelines for next-generation vehicle architectures. The EU Battery Regulation imposes carbon-footprint disclosure and recycled-content thresholds on European-bound suppliers. The Baden-Württemberg and Bavaria automotive clusters concentrate cell qualification laboratories and pilot production lines.
United States
Utility-scale developers in Texas and California prioritize cycle-life duration over energy density for grid storage deployments. The Inflation Reduction Act domestic content credits incentivize North American cell and module assembly investments. The Midwest manufacturing corridor and Southeast battery belt attract cathode precursor plant announcements.
Japan
Silicon-anode R&D pipelines target premium automotive qualification tracks with thermal stability requirements. METI industrial policy directs subsidy schemes toward solid-state chemistry validation. The Kanto and Kansai metropolitan areas concentrate materials science research institutions and pilot-scale electrolyte manufacturing.
N-Type Battery Market Competitive Landscape
Global majors compete with regional champions across integrated precursor supply and automotive qualification access. The vendor base organizes into three tiers: captive-refining conglomerates with lithium brine or hard-rock positions, joint-venture specialists leveraging regional automotive relationships, and technology licensors monetizing solid-state intellectual property. Strategic moves concentrate on backward integration into lithium refining and multi-year offtake contracting to secure volume commitments.
Among Chinese producers, CATL and BYD Company exemplify the captive-refining archetype through upstream control over lithium carbonate and hydroxide processing. LG Energy Solution and Samsung SDI occupy positions within the Korean joint-venture tier, anchoring cathode plant investments in Poland and Hungary to satisfy EU Battery Regulation compliance timelines. These four names represent the dominant competitive anchors across East Asian manufacturing clusters.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI |
| BYD Company |
| SK On |
| Tesla |
| SVOLT Energy Technology |
| Gotion High-Tech |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate and hydroxide processing costs cascade through cathode precursor pricing tiers before reaching automotive OEM offtake negotiations, with integrated Chinese refiners capturing margin pools that non-integrated European assemblers cannot access. Spot-market volatility in spodumene concentrate from Western Australian hard-rock mines feeds directly into contract renegotiation clauses for South Korean cathode plants, compressing pricing predictability for buyers without captive feedstock arrangements.
Pricing Analysis
Warranty bundling separates premium automotive qualification tracks from standard industrial procurement, with 8,000-plus cycle guarantees and thermal-runaway liability coverage commanding substantial premiums over unbundled cell-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under China's MIIT catalogs and EU Battery Regulation carbon-footprint thresholds. Cost compression in the standard tier is intensifying because cathode precursor spot markets remain exposed to lithium brine pricing swings from Chile's Atacama operations. Industrial forklift replacement buyers exhibit the highest price elasticity, while German premium automotive platforms demonstrate minimal sensitivity to cell cost given platform electrification mandates.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and Korean automotive supply chains, while distributor networks serve fragmented industrial and portable-device segments with lower volume thresholds. Geographic concentration centers on China's Yangtze River Delta and Pearl River Delta manufacturing corridors for cell assembly, South Korea's Busan-Ulsan complex for cathode materials, and Japan's Kanto region for silicon-anode R&D feedstocks. The chain draws from Australian spodumene, Chilean lithium brine, and Indonesian nickel laterite as primary raw material anchors. Single-source vulnerability in East Asian precursor refining exposes European and North American offtakers to logistics chokepoint risk through the Strait of Malacca shipping corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state electrolyte manufacturing capacity represents the binding constraint propping cell pricing premiums, with dry-room infrastructure shortages limiting qualified supply faster than automotive platform demand expands. OEM procurement officers face extended allocation queues for thermal-stable variants as qualification timelines compress.
For Market Incumbents: Lock in multi-year offtake agreements with volume commitments before Chinese MIIT catalog tightening disqualifies additional chemistry classes from subsidy eligibility. Secure backward integration into lithium refining through joint-venture structures in Western Australia or Chile to defend against spodumene concentrate margin erosion. Prioritize silicon-anode R&D investment to maintain differentiation as solid-state platforms commoditize thermal stability advantages. For New Entrants and Emerging Players: US IRA domestic content credits in the United States open a window for North American assembly investments targeting Texas and California utility-scale developers with cycle-life-optimized N-type configurations. White-space concentration sits in grid storage applications where 8,000-plus cycle warranties remain undersupplied relative to interconnection queue growth. Pursue direct sales relationships with independent power developers rather than competing for automotive qualification tracks where incumbent relationships are entrenched. For Investors and Strategic Acquirers: Samsung SDI's silicon-anode pilot line announcements are the leading indicator that premium automotive qualification tracks are opening to non-incumbent technology licensors. Long-term viability across the analysis window favors asset-light intellectual property holders with solid-state electrolyte patents over capital-intensive cell manufacturers facing ceramic processing scale-up costs. Target acquisition profiles should emphasize pre-qualified laboratory relationships with German KBA-aligned testing protocols and captive precursor pilot capacity in Poland or Hungary.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Joint Venture | Secures lithium hydroxide supply from Western Australian hard-rock mines for EU Battery Regulation compliance. |
| Solid-State Pilot Line Scale-Up | Builds dry-room infrastructure beyond current lithium-ion asset bases for automotive qualification. |
| Silicon-Anode R&D Partnership | Targets premium 800-volt platform thermal stability requirements through Japanese materials science institutions. |
| Multi-Year Offtake Agreement | Locks volume commitments from German automotive OEMs consolidating supplier panels to three qualified sources. |
| Grid Storage Cycle-Life Certification | Opens procurement channels with California utility developers prioritizing duration over density metrics. |
Research Methodology
Document review covered SEC filings from cell manufacturers, MIIT industry catalog updates, EU Battery Regulation implementation guidance, and EIA grid storage deployment databases, complemented by interviews with cathode plant operations managers, automotive platform engineers at German OEMs, utility procurement officers in Texas and California, and solid-state materials scientists at Japanese research institutions. Secondary validation drew from customs trade data tracking lithium concentrate flows, FERC interconnection queue filings, and IEA battery technology roadmaps. Bottom-up cell production estimates triangulated against top-down automotive electrification demand projections.
Market size and growth trajectory outputs across the analysis window reflect segment-level modeling of chemistry class adoption curves, end-use application deployment cycles, and regional regulatory compliance timelines. The analytical framework incorporated product type segmentation across Li-ion, solid-state, and flow battery architectures; end-user differentiation between automotive, renewable energy, and industrial buyers; technology licensing revenue from battery management systems and fast-charging infrastructure; and application-specific demand patterns for electric vehicles versus grid storage. CAGRs were derived from fitted adoption curves calibrated to historical qualification timeline compression and subsidy scheme evolution.
The model assumes a particular technology adoption path; alternative pathways for sulfide electrolyte solid-state platforms would alter the outlook if ceramic processing yields fail to scale as projected. Forecasts reflect assumptions regarding MIIT catalog enforcement intensity, IRA domestic content credit continuity, and lithium brine production expansion timelines in Chile. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Solid-State Car Battery Market
Batteries
18650 And 21700 Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Modular Battery Pack Market
Batteries
Home Inverter Battery Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
Southeast Asia Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
India Electric Vehicle Battery Manufacturing Equipment Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Zinc-Ion Battery Cells Market
Batteries
Japan Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Flow Battery Market
Batteries
Silicon Battery Market