
 Malaysia Battery Market | 2026-2036
Malaysia Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Battery Market Foresight
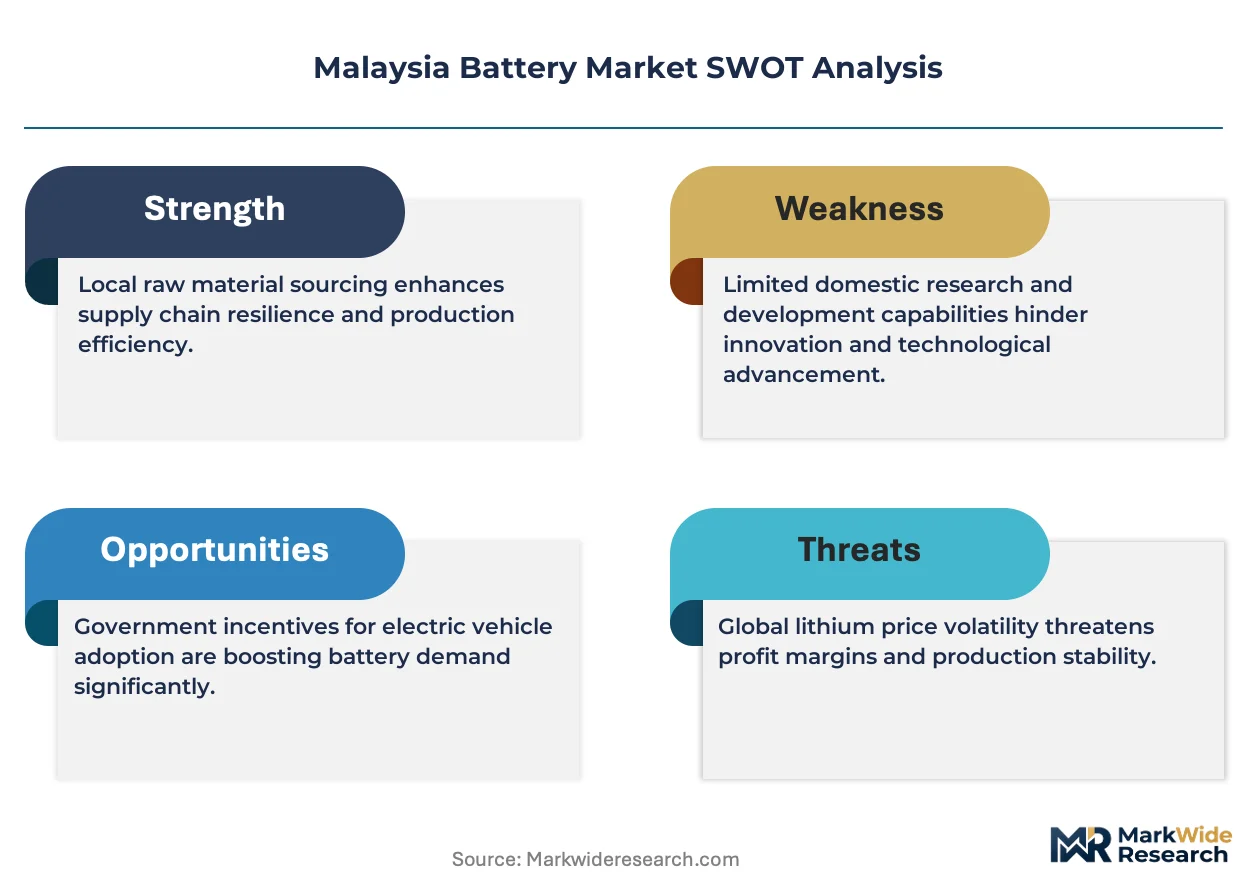
Malaysia's National Energy Transition Roadmap is shifting procurement patterns across the battery value chain, compelling industrial buyers to source locally assembled energy storage systems. CATL leverages its integrated cathode material operations to anchor supply commitments to Penang-based assembly plants. Samsung SDI competes through specialized cylindrical cell formats designed for tropical climate resilience. Yokohama Batteries Sdn Bhd dominates the replacement market for commercial vehicle starter batteries through established distributor networks in Port Klang and Johor Bahru.
A battery electrochemically stores and releases energy through reversible redox reactions, with lithium-ion cells achieving energy densities of 250-300 Wh/kg using nickel-manganese-cobalt cathode formulations for electric traction applications. The Malaysia battery industry serves grid stabilization, mobility electrification, and uninterruptible industrial power as its core commercial functions. Lithium-ion chemistry leads value generation due to accelerating electric vehicle assembly partnerships between foreign cell makers and domestic original equipment manufacturers. Lead-acid technology sustains margin pools in the backup power segment where telecommunications and data center operators prioritize capital efficiency over energy density. Energy Storage Systems technology is displacing conventional diesel generator sets in island and remote industrial installations across Peninsular Malaysia and East Malaysia.
BIS certification requirements for imported cells and SIRIM standards for local battery assembly shape product compliance costs and market access timelines for foreign manufacturers. The Sustainable Energy Development Authority Malaysia administers feed-in tariff and net energy metering frameworks that directly determine project bankability for grid-connected battery installations. Stakeholders must monitor regulatory alignment between domestic content requirements and ASEAN-wide rules of origin as regional electric vehicle supply chains consolidate.
Market Dynamics
Malaysia's National Energy Transition Roadmap is restructuring procurement patterns across the battery value chain, compelling industrial buyers to source locally assembled energy storage systems and reshaping competitive positioning among foreign cell manufacturers and domestic assemblers.
Growth Catalysts
- Net Energy Metering Framework:The Sustainable Energy Development Authority Malaysia's tariff structures improve project bankability for grid-connected battery installations, accelerating commercial and industrial adoption.
- Electric Vehicle Assembly Partnerships:Foreign cell makers are establishing production partnerships with domestic original equipment manufacturers, creating localized supply chains for mobility electrification.
- Klang Valley Industrial Clustering:Concentrated demand from logistics operators and data centers in this corridor generates economies of scale for battery system integrators.
Market Restraints
- Cobalt and Nickel Price Volatility:Raw material cost swings for nickel-manganese-cobalt cathode formulations compress margins for lithium-ion cell producers serving the Malaysian market.
- SIRIM Certification Timelines:Local battery assembly standards create extended market access delays for foreign manufacturers unfamiliar with domestic compliance procedures.
- Lead-Acid Substitution Resistance:Telecommunications and data center operators prioritize capital efficiency over energy density, sustaining incumbent technology in backup power segments.
Strategic Opportunities
- East Malaysia Island Installations:Remote industrial sites across Sabah and Sarawak present untapped demand as energy storage systems displace diesel generator sets.
- Domestic Content Incentives:Manufacturing incentives under the National Energy Transition Roadmap reward local cathode material processing and cell assembly operations.
- Commercial Fleet Electrification:Logistics operators in Port Klang and Johor Bahru are expanding electric vehicle procurement, creating dedicated demand for high-cycle-life battery configurations.
Industry Challenges
- BIS Certification Complexity:Imported cells face extended testing protocols, forcing manufacturers to maintain dual compliance tracks for regional and domestic standards.
- Electrochemical Engineering Talent Scarcity:Local universities produce insufficient specialists in battery management systems and thermal runaway prevention, constraining domestic R&D expansion.
- Legacy Power System Integration:Grid stabilization projects require complex retrofitting of existing substation infrastructure, extending deployment timelines and technical risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Battery Market |
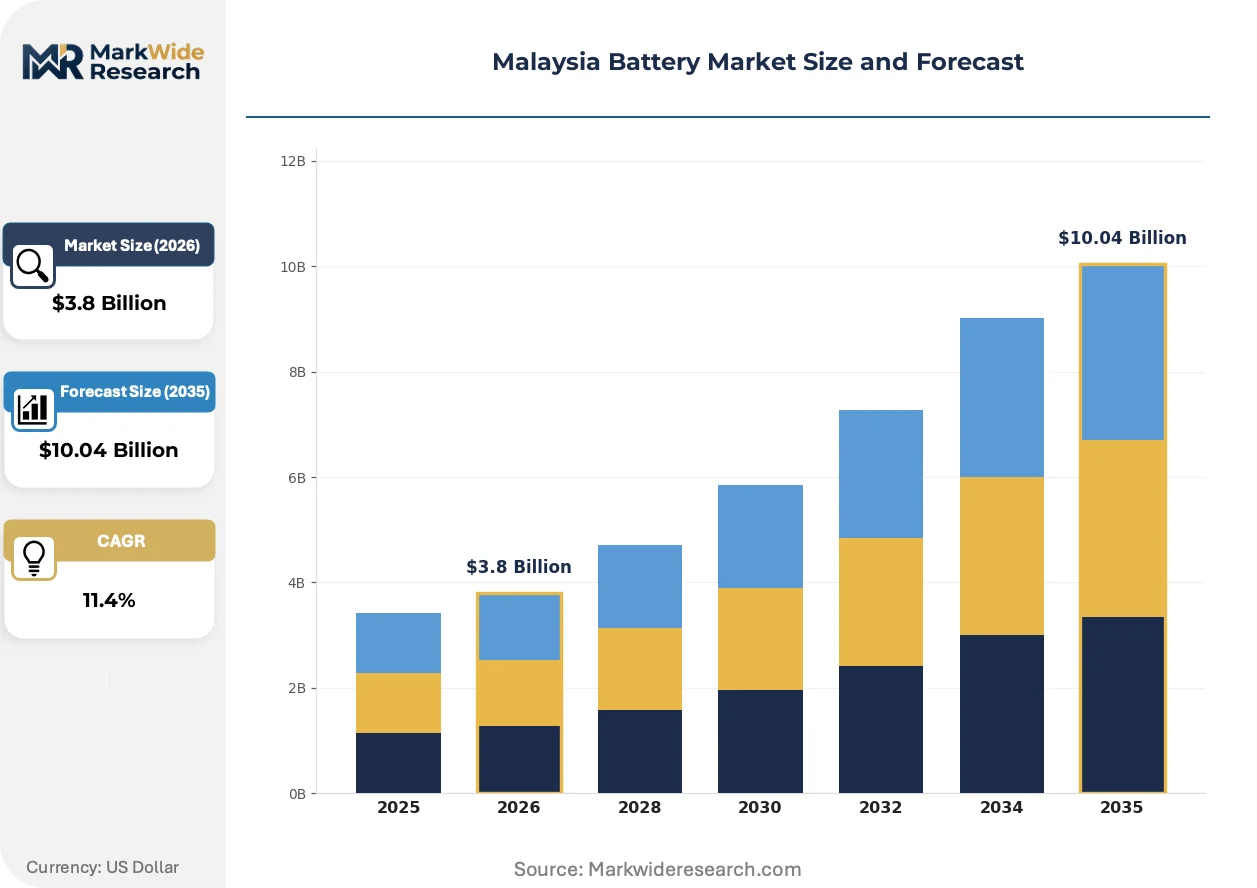
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Nickel-cadmium, Flow End User: Consumer Electronics, Automotive, Renewable Energy, Industrial Technology: Energy Storage Systems, Portable Power, Electric Vehicles, Grid Storage Application: Backup Power, Electric Transportation, Power Tools, UPS |
| Companies Covered | LG Energy Solution, Samsung SDI, CATL, Panasonic, GS Yuasa Corporation, BYD, ATL, Yokohama Batteries Sdn Bhd, Dynacraft Industries Sdn Bhd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Battery Market Shifts & Advancements
Electrochemical storage technologies and regulatory frameworks are converging to reshape how energy is stored and dispatched across Peninsular Malaysia and East Malaysia, with implications for industrial power reliability and transportation electrification.
Sodium-ion battery chemistry is expanding into grid stabilization and commercial backup power applications where energy density requirements are moderate. Utility operators and industrial facility managers are piloting sodium-ion installations for stationary storage, attracted by reduced dependence on cobalt and nickel supply chains. This chemistry is expanding into market segments previously dominated by lead-acid systems, compressing the addressable market for conventional backup technologies.
SIRIM standards for local battery assembly and BIS certification requirements for imported cells are tightening product compliance costs and market access timelines. These regulatory instruments favor manufacturers with established testing relationships and domestic assembly capabilities. Foreign cell makers are responding by anchoring cathode material operations to Penang-based facilities, reducing certification friction for regionally sourced products.
Commercial logistics operators are consolidating fleet procurement decisions at the corporate level, shifting purchasing authority away from individual depot managers. This concentration is compressing supplier negotiation cycles and favoring battery system integrators with national service networks. The pattern is most visible in the Klang Valley corridor, where industrial zone clustering enables standardized maintenance protocols and volume pricing arrangements.
Malaysia Battery Market Segmentation
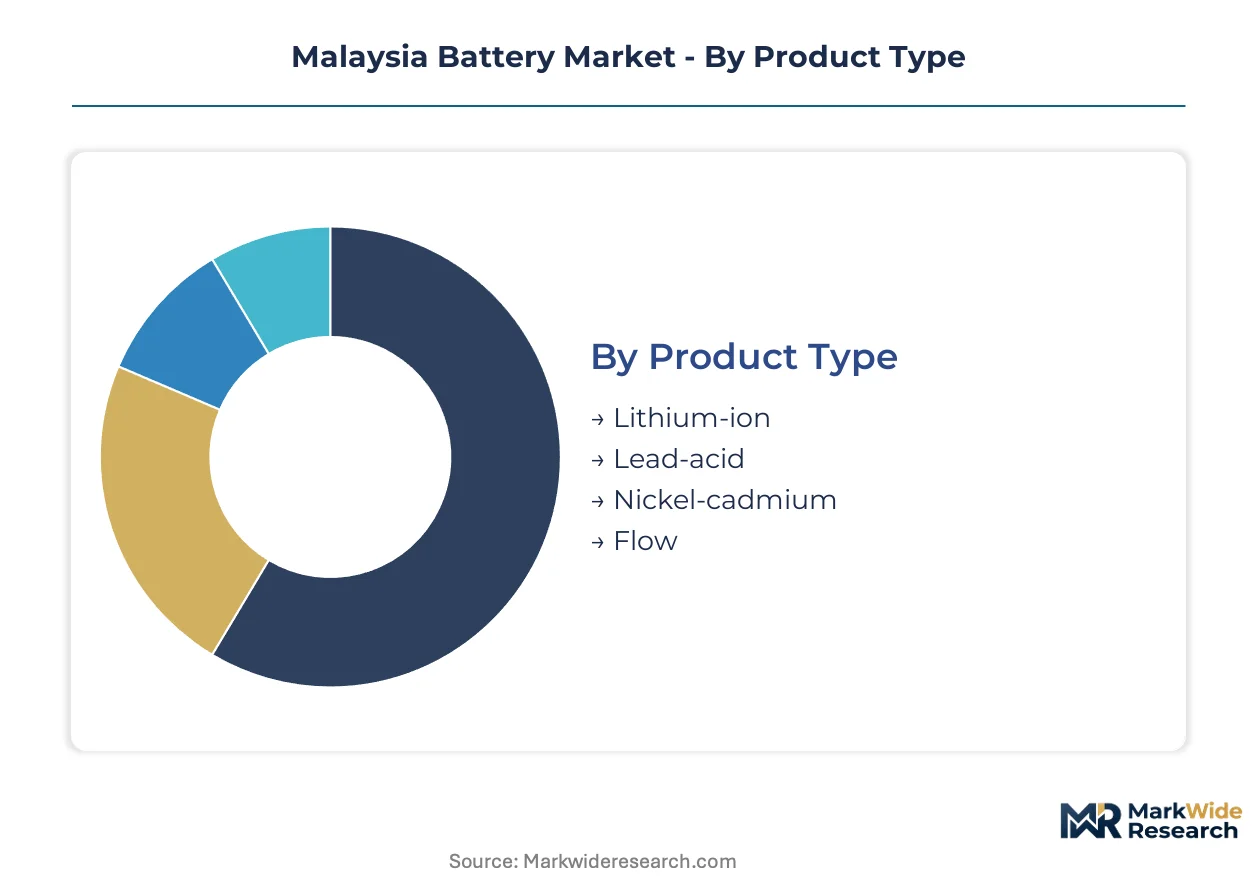
Battery procurement in Malaysia diverges sharply across use cases, with chemistry selection, form factor, and certification requirements varying by end-use intensity and grid interconnection standards. Understanding these segment boundaries enables suppliers to align cathode material sourcing and assembly location decisions with buyer technical specifications and SEDAR tariff eligibility.
Product Type:
Chemistry choice reflects the tension between energy density requirements and raw material supply security under the National Energy Transition Roadmap.
- Lithium-ion:Nickel-manganese-cobalt cathode formulations achieve 250-300 Wh/kg energy density for electric traction and grid stabilization applications. Demand concentrates in the Klang Valley corridor where CATL and Samsung SDI anchor assembly partnerships with domestic OEMs, though cobalt and nickel price volatility compresses margin pools for imported cells.
- Lead-acid:Flooded and valve-regulated designs dominate commercial vehicle starter batteries and telecommunications backup power. Yokohama Batteries Sdn Bhd maintains distributor network advantages in Port Klang and Johor Bahru, capitalizing on capital-efficient procurement priorities among data center operators.
- Nickel-cadmium:Sintered plate construction delivers extreme temperature tolerance for industrial process control and railway signaling applications in tropical climates.
- Flow:Vanadium redox systems serve long-duration grid storage for utility-scale renewable integration across Peninsular Malaysia's transmission-constrained zones.
Lithium-ion leads on scale; flow batteries lead on momentum in utility procurement pipelines.
End User:
Customer type determines volume concentration, technical service requirements, and channel structure for battery system integrators.
- Consumer Electronics:Cylindrical and pouch cell formats for smartphones, laptops, and power banks. Manufacturing concentrates in Penang-based electronics clusters serving regional export markets.
- Automotive:Passenger EVs, commercial logistics fleets, and two-wheeler electrification drive demand for high-cycle-life configurations. Fleet procurement centralization at corporate headquarters in the Klang Valley is compressing supplier negotiation cycles.
- Renewable Energy:Solar-plus-storage installations under SEDA Malaysia's net energy metering framework. Project bankability depends on domestic content compliance and SIRIM certification timelines.
- Industrial:Uninterruptible power for manufacturing facilities, oil and gas platforms, and remote mining operations across Sabah and Sarawak.
Automotive leads on scale; renewable energy leads on momentum as feed-in tariffs improve project economics.
Technology:
System architecture separates stationary from mobile applications, with thermal management and battery management system complexity scaling accordingly.
- Energy Storage Systems:Containerized and building-integrated designs displacing diesel generators in island and remote industrial installations. Sodium-ion chemistry is expanding into this segment, reducing dependence on cobalt supply chains.
- Portable Power:Compact lithium-ion packs for consumer and professional tool applications. Form factor standardization enables cross-brand compatibility in construction and maintenance sectors.
- Electric Vehicles:Pack-level integration with thermal runaway prevention systems. Foreign cell makers are establishing cathode material operations in Penang to anchor regional supply commitments.
- Grid Storage:Utility-scale installations for frequency regulation and renewable firming. SEDA Malaysia tariff structures directly determine deployment timelines.
Electric vehicles lead on scale; energy storage systems lead on momentum as diesel displacement accelerates in East Malaysia.
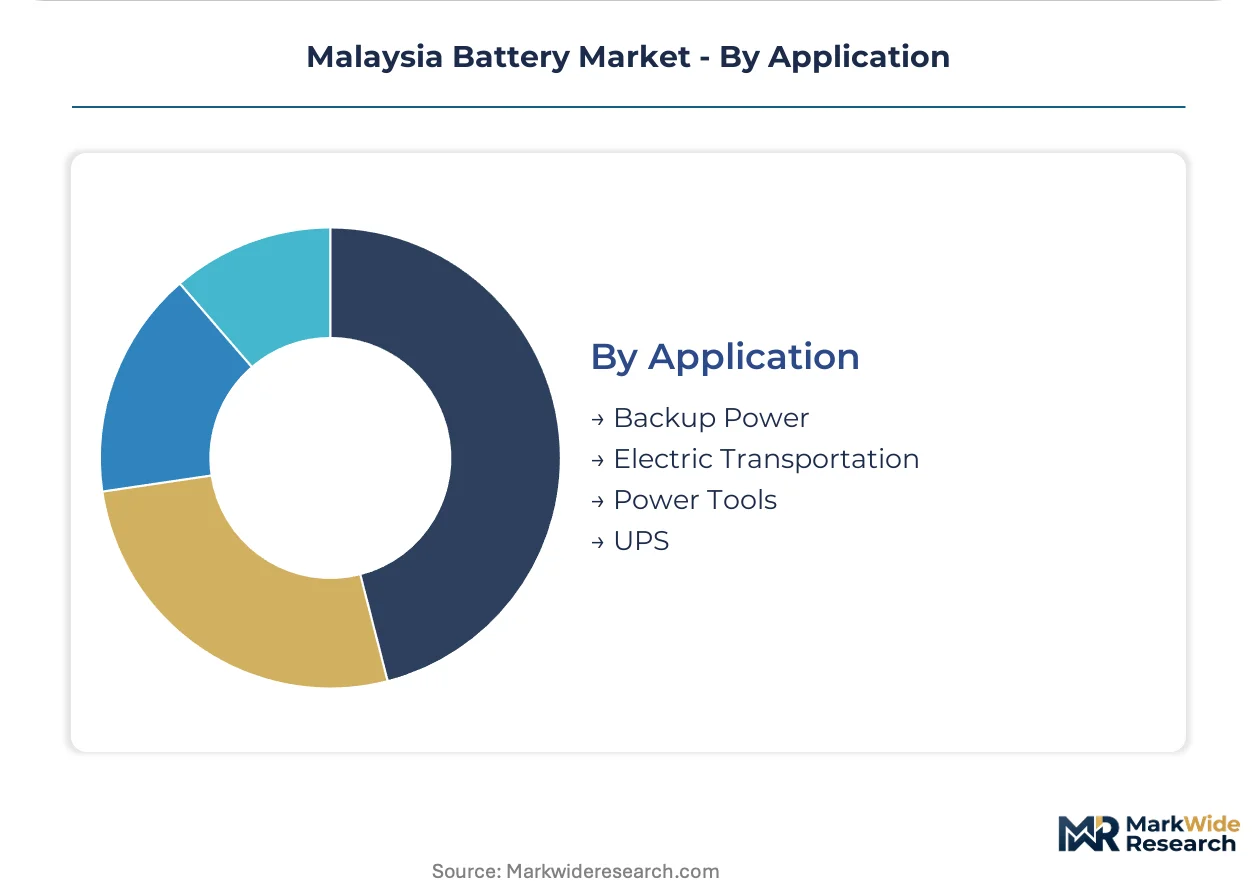
Application:
Use case intensity shapes cycle life requirements, depth of discharge specifications, and maintenance protocol design.
- Backup Power:Lead-acid technology sustains incumbent position in telecommunications and data center UPS where capital efficiency outweighs energy density. SIRIM standards for local assembly favor domestic manufacturers.
- Electric Transportation:High-discharge-rate cells for buses, trucks, and logistics vehicles. Commercial fleet operators in Port Klang are consolidating procurement decisions at corporate level.
- Power Tools:Compact cylindrical formats for professional construction and manufacturing maintenance. Interchangeable battery platforms reduce total cost of ownership.
- UPS:Online and line-interactive systems for critical facility power quality. Data center clustering in the Klang Valley generates economies of scale for system integrators.
Backup power leads on scale; electric transportation leads on momentum as logistics fleet electrification expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysia's battery industry traces its modern foundations to Penang's electronics manufacturing expansion in the 1970s, when semiconductor and component assembly established the technical workforce and supplier networks that now support cell production. The sector has since diversified across cathode material processing, pack assembly, and energy storage system integration.
Penang
CATL anchors cathode material operations to serve regional electric vehicle supply chains, leveraging the state's established electronics infrastructure. SIRIM standards for local battery assembly favor manufacturers with domestic testing relationships. The Bayan Lepas industrial zone concentrates foreign cell maker partnerships with domestic original equipment manufacturers.
Selangor
Commercial logistics operators in Port Klang and Shah Alam are consolidating fleet electrification procurement at corporate headquarters. The Sustainable Energy Development Authority Malaysia administers net energy metering frameworks that determine project bankability for grid-connected installations. Data center clustering in Cyberjaya generates economies of scale for battery system integrators serving uninterruptible power demand.
Johor
Yokohama Batteries Sdn Bhd maintains distributor network advantages for commercial vehicle starter batteries through established channels in Johor Bahru. The Iskandar Malaysia development corridor attracts energy storage system deployments for industrial zone microgrids. Port of Tanjung Pelepas logistics operators are expanding electric vehicle procurement for container handling and last-mile delivery.
Sabah
Remote industrial sites across the state present untapped demand as energy storage systems displace diesel generator sets in island installations. SEDA Malaysia feed-in tariff structures improve project economics for solar-plus-storage configurations in off-grid mining and oil and gas platforms. Kota Kinabalu serves as the technical service hub for East Malaysia battery deployments.
Sarawak
Utility-scale vanadium redox flow battery installations serve long-duration grid storage for renewable integration across transmission-constrained zones. The Sarawak Corridor of Renewable Energy attracts industrial power consumers seeking firm renewable supply backed by electrochemical storage. Kuching-based engineering firms specialize in retrofitting legacy substation infrastructure for grid stabilization projects.
Malaysia Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Malaysia's battery value chain, with integrated cathode material operations commanding supply security premiums while specialized assemblers flex capacity to demand swings. The market structure concentrates around three strategic archetypes: Korean and Japanese conglomerates with regional manufacturing footprints, Chinese vertically integrated cell makers securing upstream material control, and domestic distributors with established service networks in commercial vehicle aftermarket segments. Competitive moves center on anchor investments in Penang-based cathode processing facilities and corporate-level fleet procurement partnerships with logistics operators in the Klang Valley corridor.
Within the multinational conglomerate tier, LG Energy Solution and Samsung SDI occupy positions defined by cylindrical cell specialization and tropical climate resilience engineering. CATL represents the vertically integrated archetype, with its Penang-anchored material operations exemplifying how foreign cell makers are responding to domestic content incentives under the National Energy Transition Roadmap. Yokohama Batteries Sdn Bhd sits within the domestic distributor archetype, leveraging established Port Klang and Johor Bahru networks that commercial vehicle operators rely on for replacement market access.
| Leading Market Players |
|---|
| LG Energy Solution |
| Samsung SDI |
| CATL |
| Panasonic |
| GS Yuasa Corporation |
| BYD |
| ATL |
| Yokohama Batteries Sdn Bhd |
| Dynacraft Industries Sdn Bhd |
| Others |
Supply & Pricing Matrix
Sovereign-backed Chinese cell producers anchor cathode material processing in Penang, compressing procurement costs for domestic assemblers while forcing Korean and Japanese competitors to absorb margin erosion or cede share. This ownership pattern tightens pricing discipline across lithium-ion supply tiers as state-supported capacity expansion feeds downstream cost pass-through pressure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates SIRIM-certified domestic assembly from imported cells and uncertified gray-market products. Premium tiers command spread through tropical climate resilience engineering and after-sales service bundling, while economy tiers face compression from sodium-ion substitution in grid storage. Logistics operators in Port Klang exhibit highest price sensitivity, prioritizing capital efficiency over energy density for commercial fleet procurement.
Supply Chain Analysis
Freight cost escalation for nickel and cobalt concentrates from Indonesia and the Democratic Republic of Congo is reshaping raw material procurement economics for Malaysian cathode processors. Cell production draws from Chinese precursor chemical supply, South Korean separator membrane technology, and Japanese electrolyte formulations. Single-source vulnerability concentrates in Indonesian nickel processing, while distribution runs through Penang-based integrators serving Klang Valley demand clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with Malaysia's National Energy Transition Roadmap mandating domestic content thresholds that expand addressable market for compliant suppliers.
For Market Incumbents: Anticipate sodium-ion chemistry erosion in grid storage by securing backward integration into cathode material processing before feed-in tariff windows close. Defend against Chinese state-backed pricing pressure through SIRIM certification moats and corporate fleet service contracts that lock in maintenance revenue streams. For New Entrants and Emerging Players: Begin with East Malaysia island installations where diesel displacement creates immediate payback visibility and incumbent service networks remain thin. Target Sabah mining platforms and Sarawak utility microgrids with containerized energy storage systems, using Kota Kinabalu technical partnerships to overcome electrochemical engineering talent scarcity. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic distributors with established Port Klang and Johor Bahru aftermarket channels, particularly where family ownership creates succession-driven exit pressure. Long-term viability hinges on successful pivot from lead-acid replacement cycles to lithium-ion service capabilities. Watch SEDA Malaysia tariff adjustment announcements as inflection signal for grid-connected storage deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Processing Localization | Penang-anchored operations reduce SIRIM certification friction for CATL and Samsung SDI supply commitments. |
| Corporate Fleet Electrification Partnerships | Logistics operators in Klang Valley corridor consolidate procurement authority, compressing supplier negotiation cycles. |
| Sodium-Ion Chemistry Scale-Up | Grid stabilization applications in East Malaysia reduce cobalt supply chain dependence for utility-scale deployments. |
| Technical Service Network Expansion | Kota Kinabalu and Kuching hubs address electrochemical engineering talent scarcity constraining domestic R&D growth. |
| Net Energy Metering Project Development | SEDA Malaysia tariff structures determine bankability for solar-plus-storage configurations across Peninsular Malaysia. |
Research Methodology
Direct dialogue with battery system integrators, cathode material procurement managers, SEDA Malaysia policy officers, and commercial fleet operations directors grounded qualitative assessments in operational reality. Secondary validation drew from BIS certification filings, SIRIM standards documentation, Sustainable Energy Development Authority tariff schedules, and customs trade records for cell and precursor chemical imports. Bottom-up installation tracking across Peninsular Malaysia and East Malaysia triangulated against top-down value chain estimates.
Top-down macroeconomic framing anchored sector-level demand projections, while bottom-up project pipelines across renewable energy, automotive, and industrial segments supplied granular growth drivers. Chemistry type, end-use intensity, and grid interconnection standards formed core segmentation dimensions, with regional regulatory cluster effects layered across the projection horizon. CAGRs emerged from fitted growth curves calibrated to disclosed capacity expansion timelines and feed-in tariff phase-out schedules.
Several conditions sit outside the modeled scope, including unannounced revisions to National Energy Transition Roadmap domestic content thresholds, abrupt nickel or cobalt price shocks exceeding historical volatility bands, and regulatory harmonization failures between Malaysian SIRIM standards and ASEAN-wide rules of origin. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
North America Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Battery Cell Market
Batteries
Myanmar Battery Market
Batteries
Atomic Battery Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Denmark Rechargeable Battery Market
Batteries
Aluminum Based Battery Market
Batteries
Solid-State Car Battery Market
Batteries
SLI Battery Market
Batteries
Middle-East and Africa Consumer Battery Market
Batteries
Bio Based Battery Market
Batteries
Military Battery Packs Market
Batteries
Middle East and Africa Battery Market
Batteries
East Asia Battery Market
Batteries
Non-Rechargeable Battery Market