
 Lithium Battery Wet Separator Market | 2026-2036
Lithium Battery Wet Separator Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery Wet Separator Market Insights
Separator coating as a subscription-linked performance layer is shifting how cell manufacturers contract for wet separator supply. Asahi Kasei Corporation leverages its polyolefin chemistry depth to anchor premium ceramic-coated separator output for Japanese automotive cellmakers. SK IE Technology competes through integrated coating-to-assembly lines that control delivery timing across Korean battery plants. Toray Industries differentiates via biaxially oriented polyethylene membranes that sustain higher thermal stability thresholds in prismatic cell formats.
A lithium battery wet separator is a microporous polyolefin membrane, typically 7–25 micrometers thick, manufactured through a wet biaxial stretching process using plasticizer extraction to create interconnected pore structures that enable lithium-ion transport while preventing internal short circuits. Its primary commercial purpose is to serve as the physical barrier between anode and cathode in high-energy-density cells where thermal shutdown functionality is critical. Polyethylene wet separators dominate volume shipments for electric vehicle applications where puncture resistance and ionic conductivity specifications are most demanding. Ceramic coating technology captures expanding margin pools as cellmakers specify alumina or boehmite surface layers to enhance dimensional stability above 130°C. Composite separators combining polypropylene substrates with hybrid ceramic-polymer coatings represent the fastest-growing product configuration for next-generation solid-state transition cells.
China's SAMR enforces GB standards for separator mechanical strength and electrolyte compatibility that determine market access for domestic and imported membrane supply. The EU Battery Regulation through ECHA-linked due diligence requirements is mandating traceability in separator polymer sourcing that reshapes supplier qualification protocols. Korea's MFDS battery safety testing protocols and Japan's METI circular economy directives are converging on separator recyclability specifications. Stakeholders must monitor how solid-state electrolyte development timelines alter wet separator investment horizons and coating equipment utilization rates.
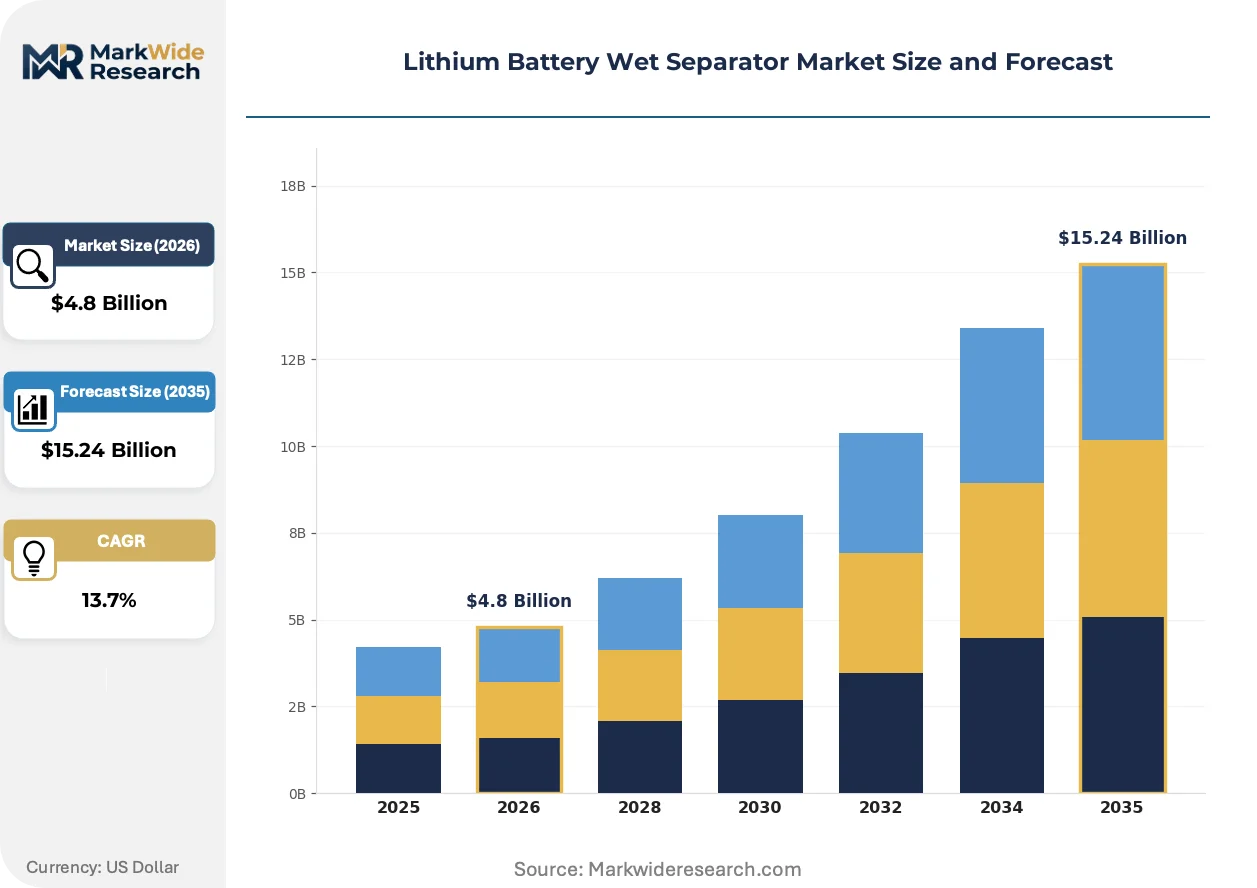
Market Dynamics
Cell manufacturers are consolidating wet separator procurement around integrated coating capabilities, compressing supplier margins while elevating technical qualification barriers for membrane-only producers.
Growth Catalysts
- EU Battery Regulation traceability mandates:ECHA-linked due diligence requirements are forcing cellmakers to requalify separator suppliers, creating replacement demand for certified membrane producers.
- Solid-state transition preparation:Hybrid ceramic-polymer composite separators are capturing pilot-line orders from automotive cell developers bridging liquid-electrolyte and solid-state architectures.
- South Korea production clustering:Cathode suppliers and separator coaters are co-locating near SK IE Technology and LG Energy Solution plants, reducing logistics friction for just-in-time membrane delivery.
Market Restraints
- Ultra-high molecular weight polyethylene supply concentration:Three Asian petrochemical complexes control over 70% of battery-grade resin output, exposing membrane producers to feedstock allocation risk.
- China GB standard mechanical strength thresholds:SAMR-enforced puncture resistance specifications exceed legacy production capabilities, requiring capital-intensive line upgrades for market access.
- Dry-process separator substitution in energy storage:Stationary battery manufacturers are specifying uniaxially stretched polypropylene membranes for cost-sensitive grid applications, displacing wet-process volume.
Strategic Opportunities
- India PLI scheme battery manufacturing incentives:Domestic cell production subsidies are attracting separator coaters to establish local ceramic-layer application capacity.
- Subscription-linked performance contracting:Cell manufacturers are piloting separator supply agreements tied to thermal shutdown reliability metrics rather than per-square-meter pricing.
- Prismatic cell format thermal stability requirements:Biaxially oriented polyethylene membranes with enhanced dimensional stability above 130°C are capturing specification wins from pouch cell producers.
Industry Challenges
- Coating equipment utilization volatility:Solid-state electrolyte development timelines are creating stranded asset risk for ceramic-layer deposition lines commissioned on five-year depreciation schedules.
- Cross-border polymer traceability documentation:EU Battery Regulation requirements for virgin versus recycled content certification are extending supplier qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery Wet Separator Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Ceramic, Composite End User: Automobile Manufacturers, Consumer Electronics, Industrial Applications, Energy Storage Systems Technology: Electrospinning, Coating, Membrane, Formation Application: Electric Vehicles, Portable Electronics, Grid Storage, Renewable Energy |
| Companies Covered | Asahi Kasei Corporation, Toray Industries, Sumitomo Chemical Co., Ltd., ENTEK International, SK IE Technology, UBE Corporation, Shanghai Energy New Materials Technology Co., Ltd., W-Scope Corporation, Sinoma Lithium Film Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery Wet Separator Market Trends and Innovations
Membrane architecture is converging with surface engineering, as base film properties become secondary to coating functionality in cell manufacturer technical specifications.
Ceramic-polymer hybrid coating technology is unifying thermal stability and ionic conductivity functions in a single surface layer. Automotive cell producers in South Korea and Japan are specifying alumina-boehmite composite coatings for prismatic formats. This unification is compressing the supplier base toward integrated coating-to-membrane producers.
China's NMPA battery safety standards are mandating separator shutdown temperature windows below 140°C with mechanical integrity retention above 150°C. Domestic membrane producers are accelerating biaxial stretching line investments to meet these dual-threshold requirements. Korean and Japanese suppliers with existing ceramic coating capabilities are capturing premium tier qualification slots.
Cell manufacturers are consolidating supplier relationships around three-year framework agreements with volume commitments and technical co-development clauses. Tier 1 automotive battery producers are displacing spot-market membrane purchases. This concentration is most visible in South Korea where SK IE Technology and domestic cathode suppliers cluster advanced cell production.
Lithium Battery Wet Separator Market Segmentation
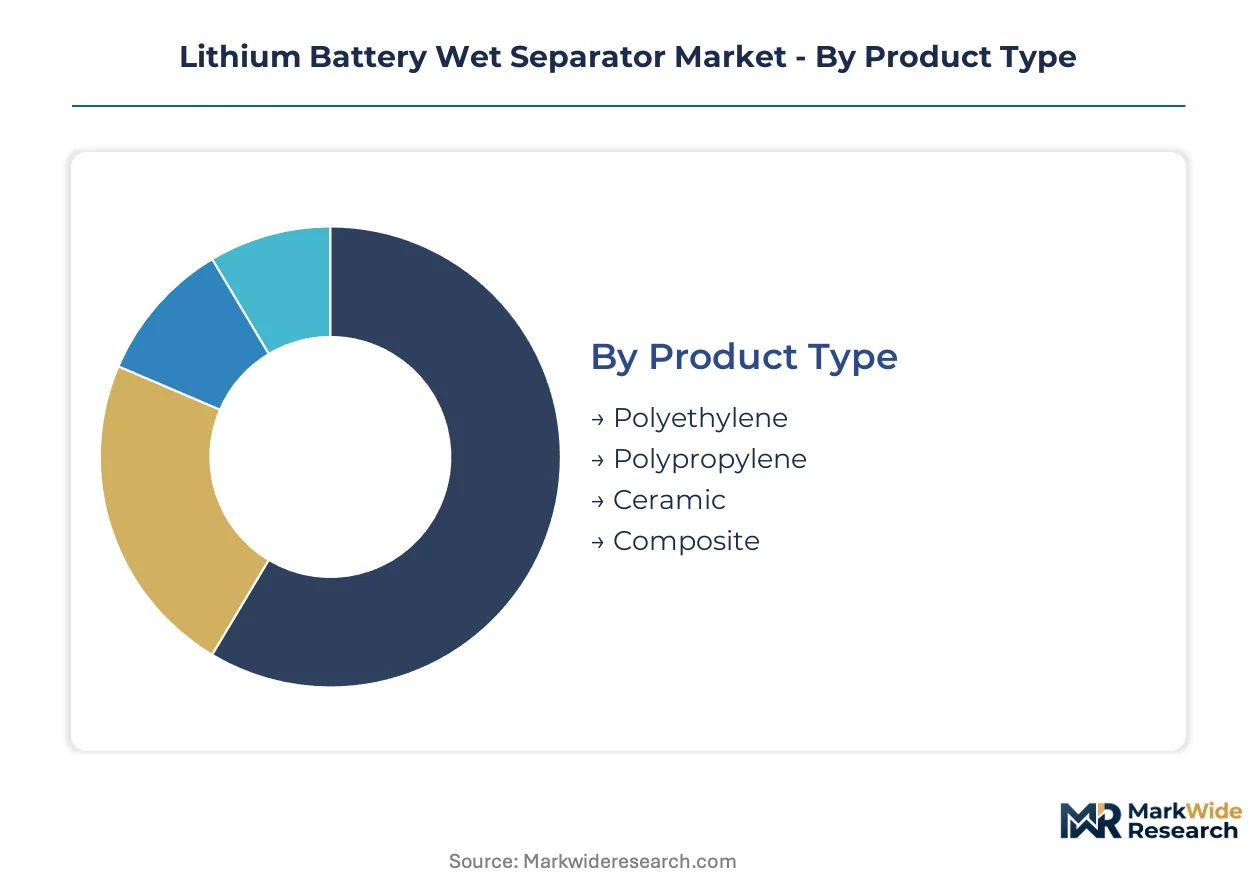
Wet separator procurement patterns diverge sharply across end-use applications, with automotive cell manufacturers demanding integrated coating capabilities while energy storage buyers prioritize membrane-only supply. Understanding these segment boundaries clarifies where technical qualification barriers concentrate versus where price competition dominates.
Product Type:
Standalone membrane products serve cost-sensitive storage applications, while ceramic-coated and composite variants embed directly into high-performance cell architectures requiring thermal shutdown precision.
- Polyethylene:Dominant base material for biaxially oriented wet-process membranes, typically 7–16 micrometers thick with interconnected pore structures formed through plasticizer extraction. Demand concentrates in South Korean automotive cell plants where SK IE Technology and LG Energy Solution specify puncture resistance above 300 gf for prismatic formats. NMPA battery safety standards in China enforce shutdown temperatures between 130–140°C, favoring PE's thermal profile.
- Ceramic:Surface-engineered separators carrying alumina or boehmite layers deposited via slot-die or gravure coating, enhancing dimensional stability above 130°C. Japanese automotive cellmakers through METI-linked supply chains specify ceramic-coated PE substrates for next-generation prismatic cells bridging liquid and solid-state electrolyte generations. EU Battery Regulation traceability mandates are accelerating qualification of coated products with documented polymer sourcing.
- Polypropylene:Lower-density alternative with higher melting point but reduced ionic conductivity, specified in hybrid separator stacks where mechanical rigidity outweighs rate capability requirements.
- Composite:Multi-layer architectures combining PP substrates with hybrid ceramic-polymer coatings, designed for solid-state transition cells requiring electrolyte compatibility across temperature extremes.
Polyethylene leads volumes today; ceramic is gaining share fastest.
End User:
Customer concentration varies by procurement sophistication, with automotive OEMs consolidating around framework agreements while industrial buyers fragment across spot-market membrane purchases.
- Automobile Manufacturers:Tier 1 battery producers specify wet separators with integrated ceramic coating and three-year volume commitments. Korean cathode suppliers co-locate with separator coaters near SK IE Technology plants to reduce logistics friction for just-in-time delivery. MFDS battery safety testing protocols enforce separator qualification cycles exceeding 18 months for automotive certification.
- Energy Storage Systems:Stationary battery manufacturers favor uncoated polyethylene membranes in cost-sensitive grid applications, with procurement shifting toward dry-process substitutes where cycle life requirements permit. China's SAMR GB standards for separator mechanical strength create entry barriers for uncertified suppliers.
- Consumer Electronics:Pouch cell producers in Japan specify thin-gauge PE membranes with premium pricing tied to dimensional uniformity for smartphone and laptop applications.
- Industrial Applications:Forklift and warehouse automation battery suppliers source standard-grade wet separators through distributor channels with minimal coating requirements.
Automobile manufacturers command premium tier positioning; energy storage systems expand most quickly.
Technology:
Process intensity separates captive coating operations from merchant membrane supply, with equipment utilization rates diverging across deposition and formation stages.
- Coating:Ceramic-layer application via slot-die, gravure, or spray methods, representing the highest-margin segment as cellmakers outsource surface engineering to qualified separator producers. Korean integrated coating-to-assembly lines control delivery timing across battery plants, compressing margins for standalone membrane suppliers. Stranded asset risk emerges where solid-state electrolyte timelines accelerate beyond five-year equipment depreciation schedules.
- Membrane:Base film production through wet biaxial stretching with plasticizer extraction, concentrated among Asian petrochemical complexes controlling ultra-high molecular weight polyethylene resin supply. Three complexes account for dominant battery-grade resin output, exposing producers to feedstock allocation constraints.
- Electrospinning:Nanofiber formation for specialty separator architectures with high porosity, limited to pilot-scale production for solid-state cell development.
- Formation:Post-stretching thermal and chemical treatment to stabilize pore structure and surface energy for electrolyte wetting.
Membrane production anchors supply volumes; coating commands margin expansion.
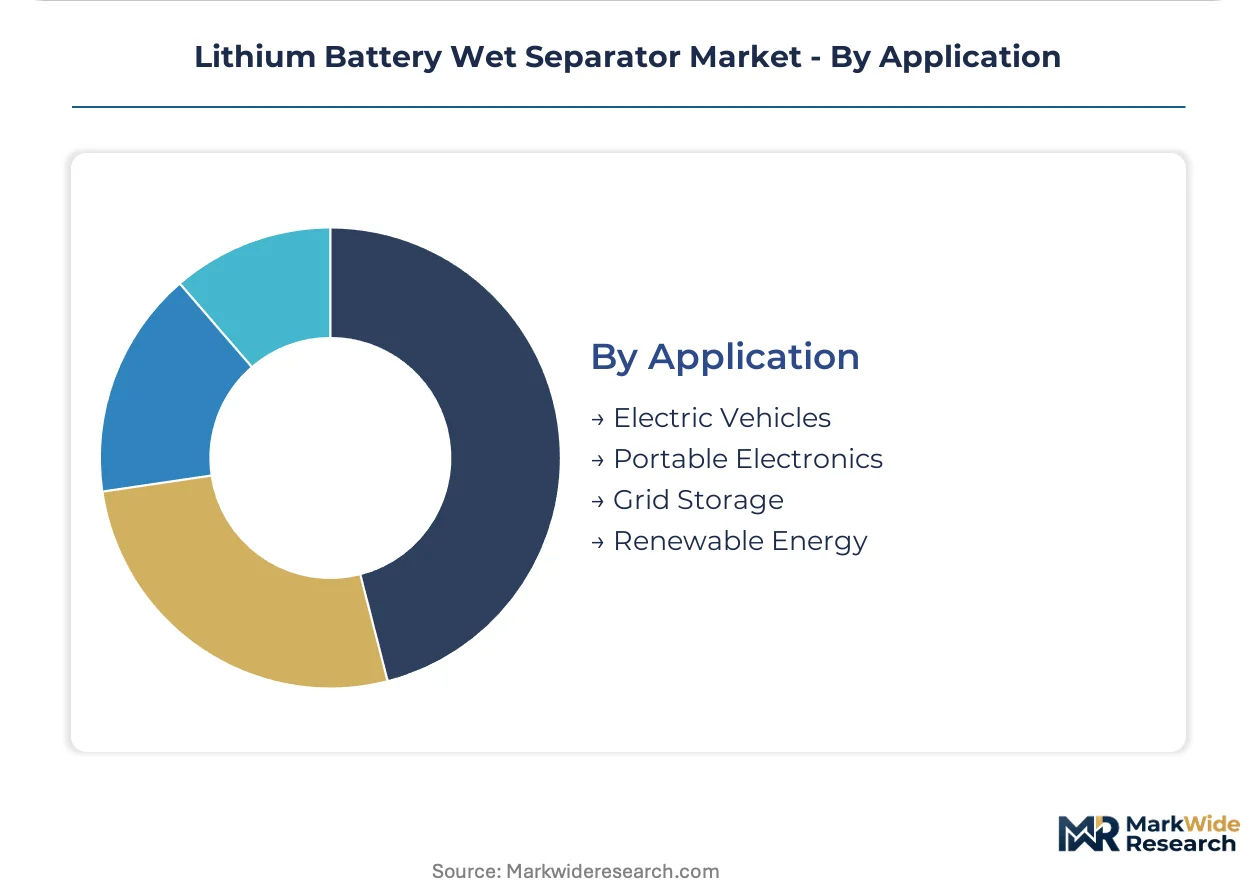
Application:
Energy density requirements scale with mobility constraints, creating tiered specification ladders from stationary storage to electric aviation.
- Electric Vehicles:Dominant demand driver specifying ceramic-coated PE membranes with thermal shutdown reliability above 150°C mechanical integrity retention. Prismatic cell formats favor biaxially oriented structures from Toray Industries and Asahi Kasei Corporation. EU Battery Regulation due diligence through ECHA is requalifying separator suppliers for European automotive cell plants.
- Grid Storage:Cost-optimized procurement accepting dry-process polypropylene substitutes where calendar life exceeds cycle life priorities. India's PLI scheme battery manufacturing incentives are attracting separator coaters to establish local ceramic-layer capacity for emerging domestic cell production.
- Portable Electronics:Thin-gauge requirements below 12 micrometers with premium pricing for dimensional uniformity in pouch cell formats.
- Renewable Energy:Hybrid solar-storage systems specifying mid-grade wet separators with moderate coating levels for residential and commercial installations.
Electric vehicles dominate revenue concentration; grid storage shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea commands premium-tier separator procurement through integrated coating clusters, while China enforces the strictest mechanical strength standards for market access. Japan maintains ceramic-coating leadership for automotive qualification. India and Germany represent emerging demand poles with diverging regulatory pathways.
China
Domestic cell producers drive wet separator volumes for electric vehicle battery packs. SAMR-enforced GB standards mandate puncture resistance above 300 gf and shutdown temperatures between 130–140°C. Zhejiang and Jiangsu provinces concentrate biaxial stretching line investments as local membrane producers upgrade legacy equipment for NMPA certification.
South Korea
SK IE Technology and LG Energy Solution anchor procurement for prismatic cell formats with ceramic-coated specifications. MFDS battery safety testing protocols enforce 18-month qualification cycles for automotive certification. Gyeonggi-do and Chungcheongnam-do host cathode suppliers co-locating with separator coaters for just-in-time membrane delivery.
Japan
Automotive cellmakers specify premium ceramic-coated polyethylene through METI-linked supply chains. METI circular economy directives converge on separator recyclability specifications for next-generation cells. Osaka and Nagoya industrial corridors concentrate biaxially oriented membrane production for hybrid solid-state transition architectures.
India
Domestic battery manufacturing subsidies under the PLI scheme attract separator coaters to establish local ceramic-layer application capacity. Central Electricity Authority grid storage mandates create mid-grade wet separator demand for utility-scale installations. Gujarat and Tamil Nadu emerge as cell production clusters requiring qualified membrane supply.
Germany
Automotive OEMs requalify separator suppliers under EU Battery Regulation due diligence through ECHA-linked requirements. REACH and RoHS compliance documentation extends supplier qualification cycles by 8–14 months. Saxony and Baden-Württemberg host pilot solid-state cell lines specifying hybrid ceramic-polymer composite separators.
Lithium Battery Wet Separator Market Competitive Landscape
Top-tier vendors anchor integrated coating-to-membrane supply, while membrane-only producers face compressed margins and elevated technical barriers. The supplier base stratifies around ceramic-layer deposition capabilities versus base film commodity supply. Three archetypes dominate: petrochemical-integrated resin controllers, coating-specialized fabricators, and automotive-qualified system suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as cell manufacturers consolidate procurement relationships.
Among Japanese industrial conglomerates, Asahi Kasei Corporation and Toray Industries exemplify the premium-tier archetype through polyolefin chemistry depth. SK IE Technology occupies a position within the Korean integrated supplier tier. These three entities represent the concentration of automotive-qualified membrane production with established ceramic-coating capabilities.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Toray Industries |
| Sumitomo Chemical Co., Ltd. |
| ENTEK International |
| SK IE Technology |
| UBE Corporation |
| Shanghai Energy New Materials Technology Co., Ltd. |
| W-Scope Corporation |
| Sinoma Lithium Film Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ultra-high molecular weight polyethylene resin spot indices in Northeast Asia cascade through membrane production economics into three distinct pricing tiers for automotive, storage, and industrial cell manufacturers. Cellmakers with ceramic coating specifications absorb premium markups while spot-market membrane buyers face compressed margins from feedstock allocation constraints.
Pricing Analysis
Capacity additions in China's Zhejiang and Jiangsu provinces are reshaping price floors for base polyethylene membranes as domestic producers upgrade biaxial stretching lines for NMPA certification. Three-tier pricing structure across premium, standard, and economy levels separates automotive-qualified ceramic-coated supply from uncertified membrane-only products. Cost compression in standard-grade segments is intensifying because Korean integrated coaters control delivery timing through captive logistics networks. Energy storage system manufacturers exhibit highest price sensitivity, while Tier 1 automotive cell producers prioritize thermal shutdown reliability over per-square-meter cost.
Supply Chain Analysis
Ocean freight rates from Korean industrial corridors to European automotive cell plants directly impact landed costs for ceramic-coated membrane shipments under EU Battery Regulation traceability mandates. Supply concentrates in South Korea, Japan, and China, with three Asian petrochemical complexes anchoring ultra-high molecular weight polyethylene resin output. Downstream distribution runs through just-in-time delivery agreements co-locating separator coaters with cathode suppliers near SK IE Technology and LG Energy Solution facilities. Single-source vulnerability persists where automotive qualification cycles exceeding 18 months lock cellmakers into existing supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lithium battery wet separator market functions as a stable compounder anchored by electric vehicle production expansion that sustains decade-long procurement cycles for safety-critical membrane supply.
For Market Incumbents: Deepen ceramic coating equipment utilization through hybrid ceramic-polymer composite development for solid-state transition architectures. Secure captive ultra-high molecular weight polyethylene resin supply via backward integration into petrochemical partnerships. Defend against dry-process separator substitution in grid storage by qualifying mid-grade wet membranes for India's PLI scheme battery manufacturing incentives. For New Entrants and Emerging Players: Solid-state electrolyte compatibility testing capabilities offer a technology-first wedge into automotive pilot-line supply relationships. Target India's Gujarat and Tamil Nadu cell production clusters where domestic ceramic-layer application capacity remains underdeveloped. Pursue qualification partnerships with European automotive OEMs facing ECHA-linked supplier requalification timelines under EU Battery Regulation mandates. For Investors and Strategic Acquirers: Consolidation pressure builds where coating equipment utilization volatility creates stranded asset risk for ceramic-layer deposition lines commissioned on standard depreciation schedules. Membrane-only producers without integrated coating capabilities represent acquisition targets over a long-term viability window. Watch solid-state electrolyte development pilot-line announcements as the critical inflection signal for wet separator investment horizon compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive ultra-high molecular weight polyethylene access insulates membrane producers from petrochemical allocation constraints. |
| Ceramic Coating Capacity Expansion | Slot-die and gravure line additions capture premium tier qualification slots under China's NMPA safety standards. |
| Hybrid Composite Separator Development | Alumina-boehmite surface layers bridge liquid-electrolyte and solid-state cell architectures for automotive qualification. |
| Co-location with Cathode Suppliers | Just-in-time delivery clusters near SK IE Technology and LG Energy Solution plants reduce logistics friction. |
| EU Battery Regulation Compliance Investment | ECHA-linked traceability documentation extends supplier qualification cycles, creating replacement demand for certified producers. |
Research Methodology
Multiple input streams — executive interviews with membrane production directors, procurement leads at Tier 1 battery producers, and regulatory affairs specialists at ceramic coating equipment manufacturers — were reconciled against secondary validation from SAMR GB standard filings, MFDS battery safety testing protocols, and customs trade data for ultra-high molecular weight polyethylene resin flows. Bottom-up volume modeling across polyethylene, ceramic-coated, and composite product configurations was triangulated with top-down demand aggregation from electric vehicle production forecasts and grid storage deployment pipelines.
Historical capacity utilization patterns at biaxial stretching facilities were cross-referenced against panel input from coating equipment vendors and automotive cell qualification officers to anchor growth projections across the analysis window. Segmentation dimensions included base material chemistry, coating technology integration, end-use application intensity, and regional regulatory cluster stringency. CAGRs were derived from elasticity modeling of membrane demand against battery pack production volumes, with explicit incorporation of solid-state electrolyte transition timelines and NMPA certification upgrade cycles as scenario variables.
The model holds under sustained electric vehicle production expansion and stable petrochemical feedstock availability; deviation in solid-state commercialization acceleration or resin supply disruption would shift investment horizon assumptions materially. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Cylindrical Lithium-Ion Battery Market
Lithium-ion Battery
Industrial Lithium-Ion Batteries Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
Graphene Battery Technology Market
Lithium-ion Battery
Tanktwo String Cell Battery Market
Lithium-ion Battery
Silicon Anode Lithium-Ion Battery Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Laminated Lithium Ion Secondary Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Dual Carbon Battery Market
Lithium-ion Battery
Lithium Silicon Battery Market
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lithium-Ion (Li-Ion) Batteries Market