
 Li-Mno2 Button Battery Market | 2026-2036
Li-Mno2 Button Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Li-Mno2 Button Battery Market Insights
Medical device OEMs is unwinding the historical dominance of consumer electronics buyers in premium Li-MnO2 procurement. Panasonic sustains technology leadership through proprietary cathode formulation expertise and cleanroom manufacturing scale. EVE Energy leverages backward integration into lithium foil and separator materials to control cost structures across cylindrical and coin cell formats. SAFT anchors defense and aerospace demand with hermetic sealing technologies that exceed standard commercial specifications.
A Li-MnO2 button battery is a primary lithium cell employing a lithium metal anode and manganese dioxide cathode, typically delivering nominal voltages of 3.0V with energy densities reaching 230 Wh/kg through precision stamping and crimp-seal assembly. Its primary commercial purpose centers on providing stable, decade-long power to devices where battery replacement is impractical or impossible. Consumer electronics applications remain the volume foundation, though margin pools have migrated toward medical devices where ISO 13485 traceability and hermetic reliability command price premiums. Industrial equipment demand is accelerating fastest among application categories, driven by remote monitoring nodes and IoT sensors requiring extended field life without maintenance access.
FDA device regulations and PMDA quality management standards shape product qualification pathways, with ISO 15194 biocompatibility testing adding compliance layers for implantable applications. The EU MDR and REACH substance restrictions further constrain cathode material sourcing and end-of-life disposal pathways for cells sold into European medical channels. Stakeholders must monitor evolving UN 38.3 transport test protocols and IEC 60086-4 safety standards, as harmonization gaps between regional certification regimes determine which suppliers can serve cross-border medical OEM contracts without redundant qualification cycles.
Market Dynamics
Medical device OEMs are accelerating their migration from consumer-grade to medical-grade Li-MnO2 cells, driven by Japan's PMDA post-market surveillance tightening and the EU MDR's traceability mandates. This demand rotation is compressing procurement cycles for ISO 13485-certified suppliers while elevating hermetic sealing and biocompatibility testing from premium options to baseline requirements.
Growth Catalysts
- Active implantable medical devices:Cardiac monitors and drug-delivery pumps require decade-long power autonomy without replacement access, pulling premium cell demand from cardiac rhythm management OEMs.
- Japan PMDA post-market surveillance rules:Tighter documentation requirements for batteries in implantables push suppliers toward higher-grade manufacturing protocols and extended qualification datasets.
- Remote industrial IoT sensors:Oilfield and pipeline monitoring nodes in inaccessible locations mandate maintenance-free power, expanding addressable demand beyond traditional consumer electronics volumes.
Market Restraints
- Lithium metal foil supply concentration:Raw material refining clusters in South America and Australia create geographic vulnerability for anode material procurement.
- REACH substance restrictions:EU cathode material sourcing faces constrained end-of-life disposal pathways, adding compliance friction for European medical channel access.
- Primary cell substitution pressure:Rechargeable solid-state alternatives in low-power wearables threaten long-term share in consumer applications where replacement access exists.
Strategic Opportunities
- India medical device manufacturing:CDSCO regulatory alignment with ISO 13485 creates entry pathways for certified suppliers as domestic production scales under PLI scheme incentives.
- Cell-to-pack integration services:Medical OEM demand for pre-qualified battery-PCBA modules opens margin expansion beyond discrete cell sales.
- Hermetic sealing technology convergence:Fusion of glass-to-metal seal expertise with laser welding automation enables next-generation implantable reliability tiers.
Industry Challenges
- ISO 15194 biocompatibility certification timelines:Extended test protocols for implantable applications delay product launches and tie up R&D capital.
- Cleanroom manufacturing scale-up:Medical-grade production capacity requires specialized facility investment with long depreciation cycles and limited contract manufacturer alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li-Mno2 Button Battery Market |
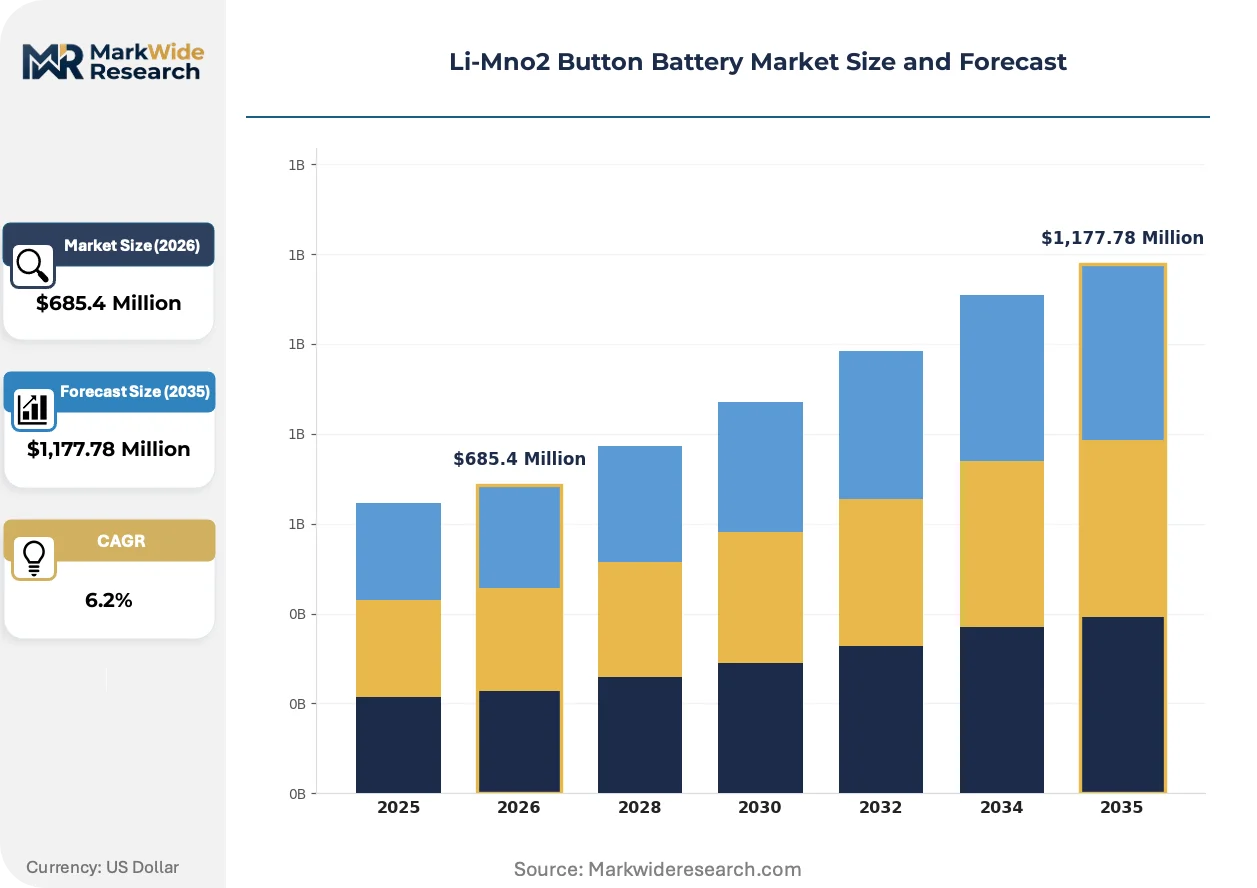
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cell, Pack, Module, System Application: Consumer Electronics, Medical Devices, Automotive, Industrial Equipment End User: OEMs, Retailers, Distributors, Service Providers Sales Channel: Online, Offline, Direct Sales, Third-Party Retail |
| Companies Covered | Hitachi Maxell, Panasonic, Energizer, Duracell, SAFT, EVE Energy, FDK, Vitzrocell, HCB Battery Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li-Mno2 Button Battery Market Trends and Innovations
Precision stamping and crimp-seal assembly techniques are advancing cathode density uniformity, while regulatory harmonization efforts between IEC 60086-4 and UN 38.3 protocols reshape qualification economics. These forces are compressing the supplier base toward integrated manufacturers with captive materials capabilities.
Advanced cathode formulation with surface-treated manganese dioxide is supplanting standard electrolytic grades in implantable applications. Cardiac rhythm management OEMs are adopting these formulations within 18-month qualification windows. The technology is supplanting commodity-grade cells in premium medical procurement, compressing margin pools for undifferentiated suppliers.
EU MDR device regulations now mandate unique device identification for batteries in active implantables, extending traceability requirements through distribution channels. This forces suppliers to implement serialized production records and blockchain-enabled chain-of-custody systems. Implantable neuromodulation devices face the steepest compliance cost escalation, with OEMs consolidating supplier bases to reduce audit burden.
Certification-driven procurement preferences now dominate medical battery selection, with ISO 13485 and ISO 15194 documentation outweighing unit cost in sourcing decisions. Distributors serving hospital procurement are ceding ground to direct OEM-supplier relationships with embedded quality engineering support. Germany's medical device clusters exhibit this channel compression most acutely, as TGA-aligned Australian OEMs follow similar direct-sourcing patterns.
Li-Mno2 Button Battery Market Segmentation
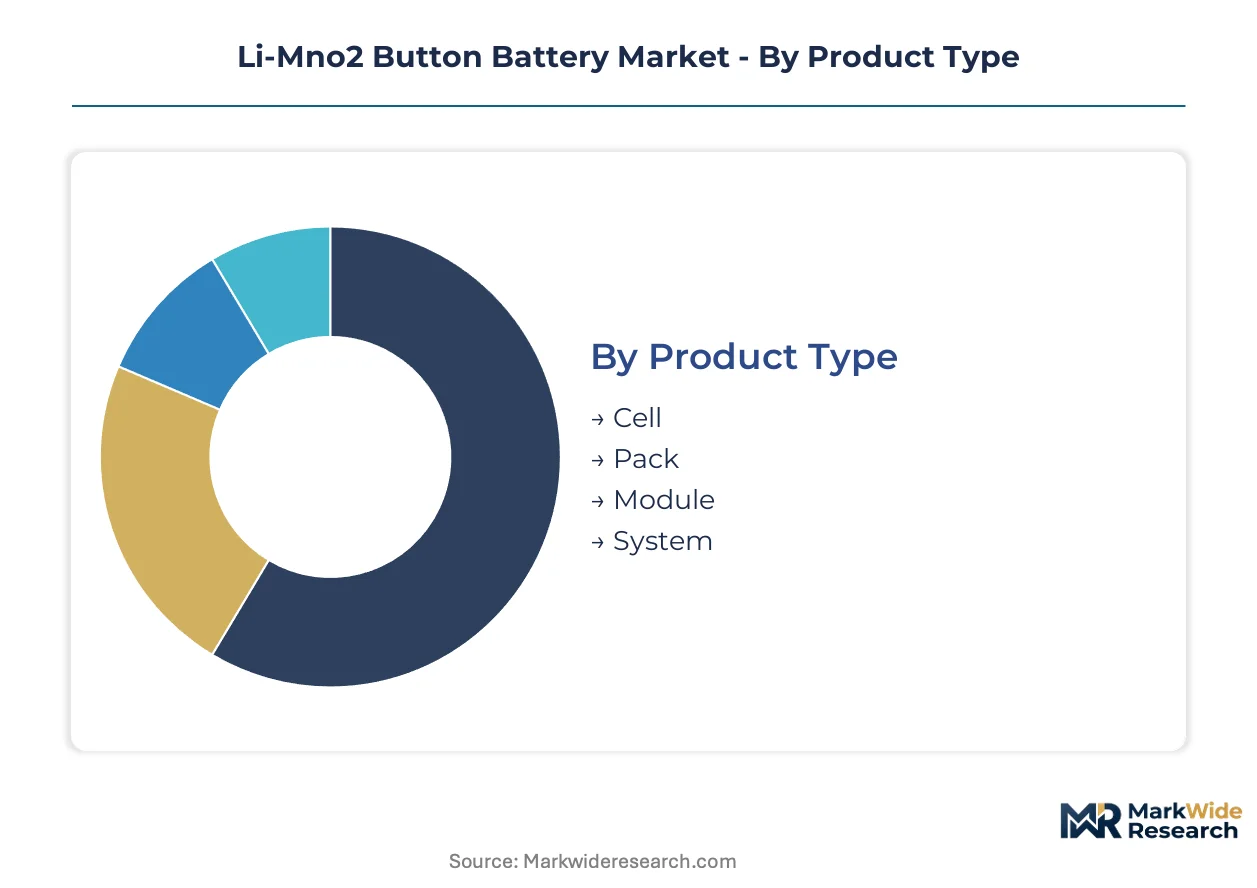
Segmentation in Li-MnO2 button batteries reveals how procurement channels diverge between price-sensitive consumer volumes and certification-heavy medical contracts. Channel economics and regulatory burden split the supplier base into distinct operational models serving each tier.
Product Type:
Discrete cells flow through distributors to aftermarket replacement markets, while pack and module assemblies move through direct OEM contracts with embedded quality engineering support.
- Cell:Individual button cells in standard IEC dimensions serve replacement markets and low-volume device assembly. Consumer electronics procurement concentrates in South Korean and Japanese trading houses, though margin compression from commodity-grade competition constrains supplier economics.
- Pack:Pre-assembled cell-PCBA combinations with integrated protection circuits address medical OEM demand for drop-in power solutions. Cardiac rhythm management manufacturers in Germany and Switzerland are consolidating procurement around qualified pack suppliers to reduce internal battery engineering headcount.
- Module:Multi-cell arrays with thermal management and telemetry interfaces support industrial IoT sensor networks requiring extended field life.
- System:Fully integrated power subsystems with enclosure, connector, and firmware for implantable neuromodulation devices command the highest certification burden and longest qualification cycles.
Cell dominates installed base. Pack is where expansion concentrates.
Application:
Application segments stratify by regulatory intensity, with ISO 13485 traceability requirements creating cost tiers that separate medical procurement from consumer volumes.
- Consumer Electronics:Hearing aids, calculators, and key fobs drive volume demand for standard-grade CR2032 and CR2450 formats. Japanese and South Korean electronics OEMs anchor procurement through established trading relationships, though rechargeable solid-state alternatives threaten long-term share in wearable applications where replacement access exists.
- Medical Devices:Implantable cardiac monitors, drug-delivery pumps, and neuromodulation systems require decade-long power autonomy without maintenance access. FDA and PMDA post-market surveillance tightening has elevated hermetic sealing and biocompatibility testing from premium options to baseline procurement requirements.
- Automotive:Tire pressure monitoring systems and keyless entry fobs represent steady replacement demand with moderate qualification barriers.
- Industrial Equipment:Remote oilfield sensors and pipeline monitoring nodes in inaccessible locations mandate maintenance-free power, expanding addressable demand fastest among application categories.
Consumer electronics commands volume leadership. Medical devices capture margin concentration.
End User:
OEM procurement patterns diverge sharply between medical device manufacturers demanding direct supplier relationships and consumer electronics buyers accepting distributor intermediaries.
- OEMs:Medical device manufacturers in Germany, Switzerland, and Japan are consolidating supplier bases to reduce audit burden, preferring direct contracts with embedded quality engineering support over distributor relationships.
- Retailers:Electronics chains and pharmacy outlets serve replacement demand for hearing aid and consumer device batteries, with price transparency compressing margins for standard-grade cells.
- Distributors:Specialized medical device distributors are ceding ground to direct OEM-supplier relationships as traceability requirements intensify.
- Service Providers:Industrial maintenance contractors and medical device service organizations procure replacement cells for field repairs, with inventory pooling arrangements reducing per-transaction costs.
OEMs dominate premium procurement. Retailers anchor consumer replacement volumes.
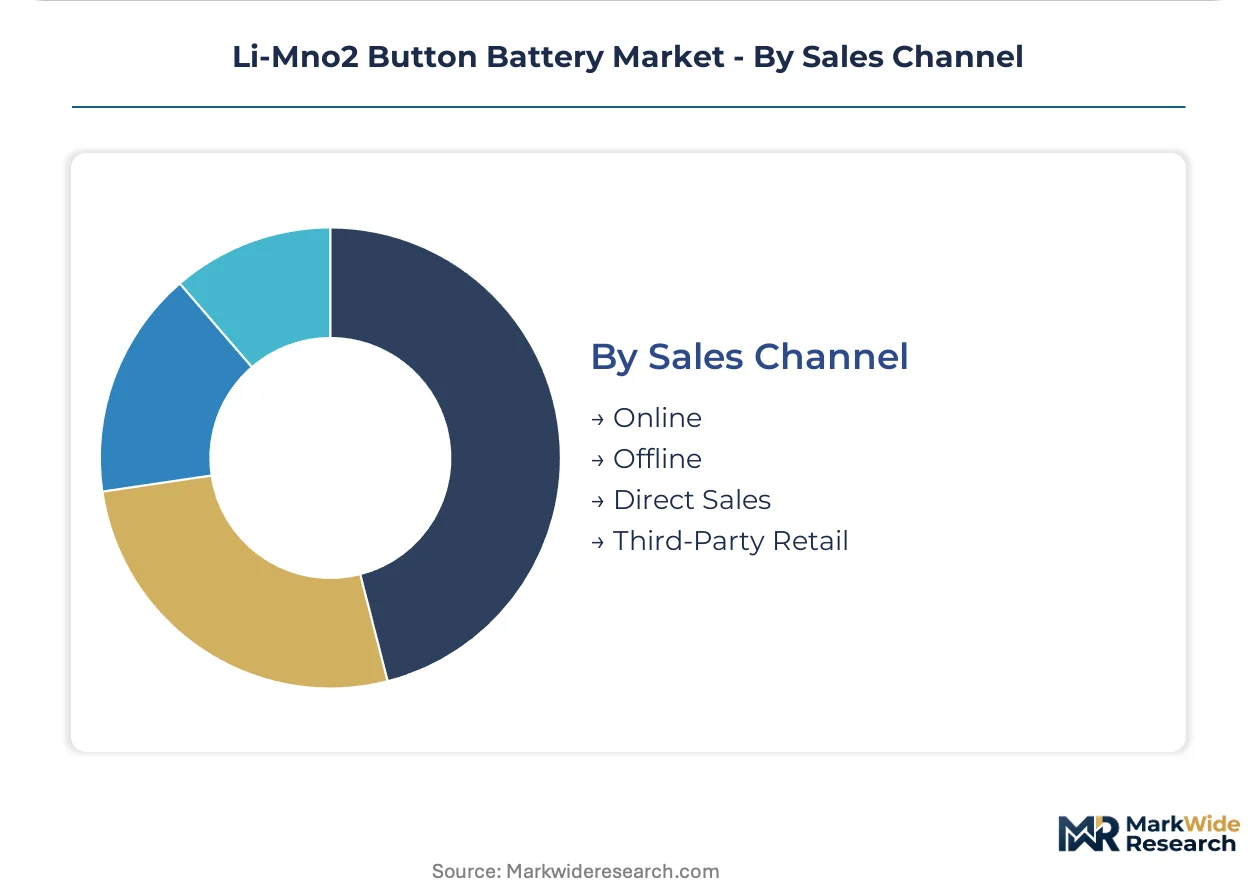
Sales Channel:
Channel structure reflects the certification divide between medical-grade direct sales and consumer-grade third-party retail.
- Online:E-commerce platforms serve consumer replacement demand and small-volume industrial procurement, with price transparency favoring standard-grade commodity cells.
- Offline:Brick-and-mortar electronics and pharmacy retail maintains presence for urgent replacement needs, particularly for hearing aid users requiring immediate battery access.
- Direct Sales:Dedicated account management with quality engineering support serves medical OEMs in Germany, Switzerland, and Japan, with serialized production records and blockchain-enabled chain-of-custody systems meeting EU MDR traceability mandates.
- Third-Party Retail:Mass-market distributors and trading houses handle consumer electronics volumes, with limited differentiation beyond price and delivery reliability.
Direct sales commands medical procurement. Third-party retail anchors consumer volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing clusters in South Korea and Japan anchor premium cell production for medical and industrial applications. European medical device OEMs in Germany and Switzerland drive certification-heavy procurement. United States demand concentrates in cardiac rhythm management and defense aerospace channels.
Japan
PMDA post-market surveillance tightening for active implantable medical devices accelerates demand for ISO 13485-certified cells with extended qualification datasets. METI cleanroom manufacturing standards elevate hermetic sealing requirements from premium options to baseline procurement mandates. Tokyo-Osaka industrial corridors concentrate cell-to-pack integration capabilities serving domestic cardiac monitor OEMs.
South Korea
MFDS alignment with ISO 15194 biocompatibility protocols opens procurement pathways for implantable neuromodulation device manufacturers. Government-backed battery R&D consortia support cathode formulation advancement for decade-long power autonomy applications. Seoul-Incheon production clusters specialize in cylindrical and coin cell formats with backward integration into separator materials.
Germany
EU MDR unique device identification mandates for batteries in active implantables force serialized production records and blockchain-enabled chain-of-custody systems. TGA-aligned Australian OEMs follow German direct-sourcing patterns, consolidating supplier bases to reduce audit burden. Munich-Stuttgart medical device corridors exhibit acute channel compression as distributors cede ground to embedded quality engineering relationships.
Switzerland
Swissmedic regulatory frameworks for implantable drug-delivery systems demand hermetic sealing technologies exceeding standard commercial specifications. Cardiac rhythm management manufacturers consolidate procurement around qualified pack suppliers to reduce internal battery engineering headcount. Basel-Zurich clusters specialize in pre-assembled cell-PCBA combinations with integrated protection circuits.
United States
FDA device regulations shape product qualification pathways for cardiac monitors and neuromodulation systems requiring maintenance-free power. Defense and aerospace demand anchors on hermetic sealing specifications exceeding consumer-grade capabilities. Boston-Minneapolis medical device corridors drive direct OEM-supplier relationships with embedded quality engineering support.
Li-Mno2 Button Battery Market Competitive Landscape
Concentration sits with diversified electronics conglomerates and specialized primary cell manufacturers. Japanese and South Korean producers dominate premium medical procurement through captive cathode formulation expertise and cleanroom scale. Three archetypes define competitive positioning: integrated materials-to-cell manufacturers, defense-aerospace specialists with hermetic sealing capabilities, and consumer electronics volume players. Capacity expansion and strategic partnerships represent the dominant competitive moves as medical-grade qualification timelines extend.
Among East Asian-based producers, Panasonic exemplifies the integrated archetype with proprietary cathode capabilities, while EVE Energy occupies a position defined by backward integration into lithium foil and separator materials. SAFT anchors the defense-aerospace specialist tier. These three represent distinct strategic postures: conglomerate-backed medical-grade scale, mid-cap materials-integrated cost control, and hermetic sealing technology leadership.
| Leading Market Players |
|---|
| Hitachi Maxell |
| Panasonic |
| Energizer |
| Duracell |
| SAFT |
| EVE Energy |
| FDK |
| Vitzrocell |
| HCB Battery Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Cleanroom manufacturing scale economies in South Korea and Japan establish price floors that commodity-grade suppliers cannot match, compressing margin pools toward integrated producers with captive cathode formulation capabilities. Medical-grade procurement premiums widen as ISO 13485 certification requirements harden, while consumer electronics volumes face relentless cost pressure from undifferentiated trading houses.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with ISO 15194 biocompatibility certification and hermetic sealing grade serving as the primary price differentiation drivers. Cost compression in consumer-grade cells is intensifying because rechargeable solid-state alternatives threaten replacement-access applications. Medical device OEMs exhibit the lowest price sensitivity, prioritizing qualification documentation over unit economics, while retail replacement buyers drive aggressive commoditization.
Supply Chain Analysis
Japan and South Korea anchor precision cathode stamping and crimp-seal assembly for premium medical applications, drawing from lithium metal foil refiners in South America and separator material specialists in East Asia. Single-source vulnerability concentrates in high-purity electrolytic manganese dioxide feedstock, where Australian and Gabonese mining clusters face logistics chokepoint exposure. Distribution runs through direct OEM contracts for medical-grade cells, with third-party trading houses handling consumer electronics volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates insurmountable switching costs. ISO 15194 and ISO 13485 qualification timelines extending beyond eighteen months lock incumbent positions against insurgent competition.
For Market Incumbents: Shield market position by deepening backward integration into lithium foil and separator materials to control cost structures against emerging Chinese volume players. Prioritize hermetic sealing technology R&D to maintain premium tier access as PMDA and FDA documentation requirements tighten post-market surveillance obligations. For New Entrants and Emerging Players: Cell-to-pack integration services for mid-tier medical OEMs represent the most penetrable white space, where incumbents under-serve buyers seeking drop-in power solutions without internal battery engineering headcount. Target Indian CDSCO-aligned manufacturers scaling under PLI scheme incentives, offering pre-qualified module assemblies with embedded protection circuits as the primary go-to-market angle. For Investors and Strategic Acquirers: Hermetic sealing technology specialists with glass-to-metal seal expertise and laser welding automation capabilities constitute the priority acquisition archetype for portfolio exposure to implantable neuromodulation growth. Long-term viability rests on regulatory entrenchment deepening across the projection horizon, with EU MDR unique device identification implementation serving as the critical signal to watch for compliance cost inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 15194 Biocompatibility Certification Investment | Unlocks procurement pathways with cardiac rhythm management OEMs in Germany and Switzerland. |
| Backward Integration into Lithium Foil Production | Captures margin compression resistance against South Korean trading house competition. |
| Cell-to-Pack Integration Service Launch | Addresses medical OEM demand for pre-qualified battery-PCBA modules with reduced internal engineering. |
| Hermetic Sealing Technology Acquisition | Secures defense and aerospace procurement tiers exceeding standard commercial specifications. |
| India CDSCO Regulatory Alignment Program | Positions for PLI scheme beneficiary procurement as domestic medical device manufacturing scales. |
Research Methodology
Cross-validation between primary interviews with biomedical engineers, cardiac device procurement managers, GPO contracts specialists, and cleanroom manufacturing directors anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, PMDA approval databases, EU MDR technical documentation, and customs trade records for lithium primary cell imports. Bottom-up cell shipment estimates and top-down medical device power budget analysis complete the triangulation.
Sensitivity analysis across cathode formulation cost scenarios, qualification timeline variations, and regulatory harmonization gaps shapes the analytical framework. Segmentation dimensions modeled include product format tier, application regulatory intensity, end-user procurement pattern, and regional certification cluster. CAGRs derive from installed base replacement cycles and new device adoption curves, with cardiac rhythm management OEM procurement concentration and industrial IoT sensor deployment rates serving as key forecast inputs.
Underlying assumptions cover stable lithium metal foil supply availability and continued PMDA-FDA regulatory convergence, with deviation risk concentrated in REACH substance restriction expansion and solid-state rechargeable substitution acceleration. Recalibration cycles align with material shifts in EU MDR enforcement intensity and India PLI scheme incentive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Taiwan Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Smart Battery Market
Batteries
Advanced Batteries Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Absorbed Glass Mat (AGM) Separator Batteries Market
Batteries
Sodium-Ion Battery Electrolyte Market
Batteries
Middle East and Africa Battery Market
Batteries
Battery Terminal Brushes Market
Batteries
Global Zinc Air Batteries Market
Batteries
Secondary Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Automotive Starting Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Redox Flow Battery Market
Batteries
PERC Battery Market