
 Disposable Batteries Market | 2026-2036
Disposable Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Batteries Market Intelligence
Electrochemical engineering talent scarcity is bifurcating the competitive landscape between legacy mass producers and specialized lithium cell developers. Duracell Inc. leverages its brand equity and retail shelf dominance across North American and European mass channels. Energizer Battery, Inc. sustains alkaline leadership through continuous manufacturing scale investments and private-label partnerships. Panasonic Corporation anchors premium lithium primary cell supply for industrial and medical OEMs in Japan and select Asian markets.
Disposable batteries are single-use electrochemical cells designed for irreversible discharge, typically employing alkaline manganese dioxide, zinc-carbon, or lithium iron disulfide chemistries with nominal voltages ranging from 1.5V to 3V, manufactured through automated winding, electrolyte filling, and sealed can formation processes. Their primary commercial purpose is to provide portable, maintenance-free power for consumer and industrial devices where recharging infrastructure is impractical or cost-prohibitive. Alkaline cells occupy the largest value share across remote controls and flashlights due to their balanced energy density and shelf stability. Lithium primary batteries represent the fastest-expanding chemistry segment, driven by medical instruments and security systems requiring wide temperature tolerance and low self-discharge. Zinc-carbon retains volume significance in price-sensitive emerging markets despite structural margin compression relative to alkaline formulations.
The EU Battery Regulation and REACH framework mandate recycled content thresholds and restricted substance declarations, reshaping material sourcing and labeling requirements for cells sold in Europe. EPA hazardous waste classifications in the United States govern end-of-life handling protocols for mercury-containing and silver oxide chemistries, influencing collection infrastructure investments. India's BIS certification and E-Waste Management Rules impose conformity testing and extended producer responsibility obligations on importers and domestic manufacturers. Stakeholders must monitor evolving chemistry-specific compliance timelines and assess regional manufacturing localization to preserve market access and cost competitiveness.
Market Dynamics
Design-for-recycling mandates under the EU Battery Regulation are forcing manufacturers to reconfigure cell architectures and material compositions, compressing margins for legacy alkaline producers while creating entry barriers for new chemistry developers.
Growth Catalysts
- Portable medical diagnostics:Home-use glucose monitors and pulse oximeters require reliable lithium primary cells with decade-long shelf stability, expanding OEM procurement volumes.
- REACH substance restrictions:European hazardous material declarations are accelerating mercury-free silver oxide adoption in precision instrumentation.
- Rural electrification gaps:India’s uneven grid coverage sustains zinc-carbon demand for basic lighting and radios in tier-3 towns and villages.
Market Restraints
- Manganese dioxide price volatility:Alkaline cathode material costs fluctuate with mining output from Gabon and South Africa, squeezing contract manufacturer margins.
- Lithium metal supply concentration:Primary cell-grade lithium production clusters in Chile and Argentina, exposing buyers to geopolitical disruption and currency risk.
- Rechargeable substitution:USB-C rechargeable NiMH and lithium-ion cells are displacing disposables in high-drain consumer electronics.
Strategic Opportunities
- Industrial IoT sensors:Smart agriculture and asset tracking deployments require wide-temperature lithium thionyl chloride cells with 20-year operational life.
- BIS certification pathways:India’s streamlined conformity assessment for zinc-carbon imports offers faster market entry for compliant Asian manufacturers.
- Design-for-recycling formats:Modular cell constructions that ease material separation align with EU Battery Regulation collection targets and producer responsibility schemes.
Industry Challenges
- Electrochemical engineering scarcity:Fewer universities maintain active primary cell research programs, constraining R&D pipeline for next-generation chemistries.
- Dual certification timelines:Medical device OEMs require simultaneous FDA and CE marking, extending product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Batteries Market |
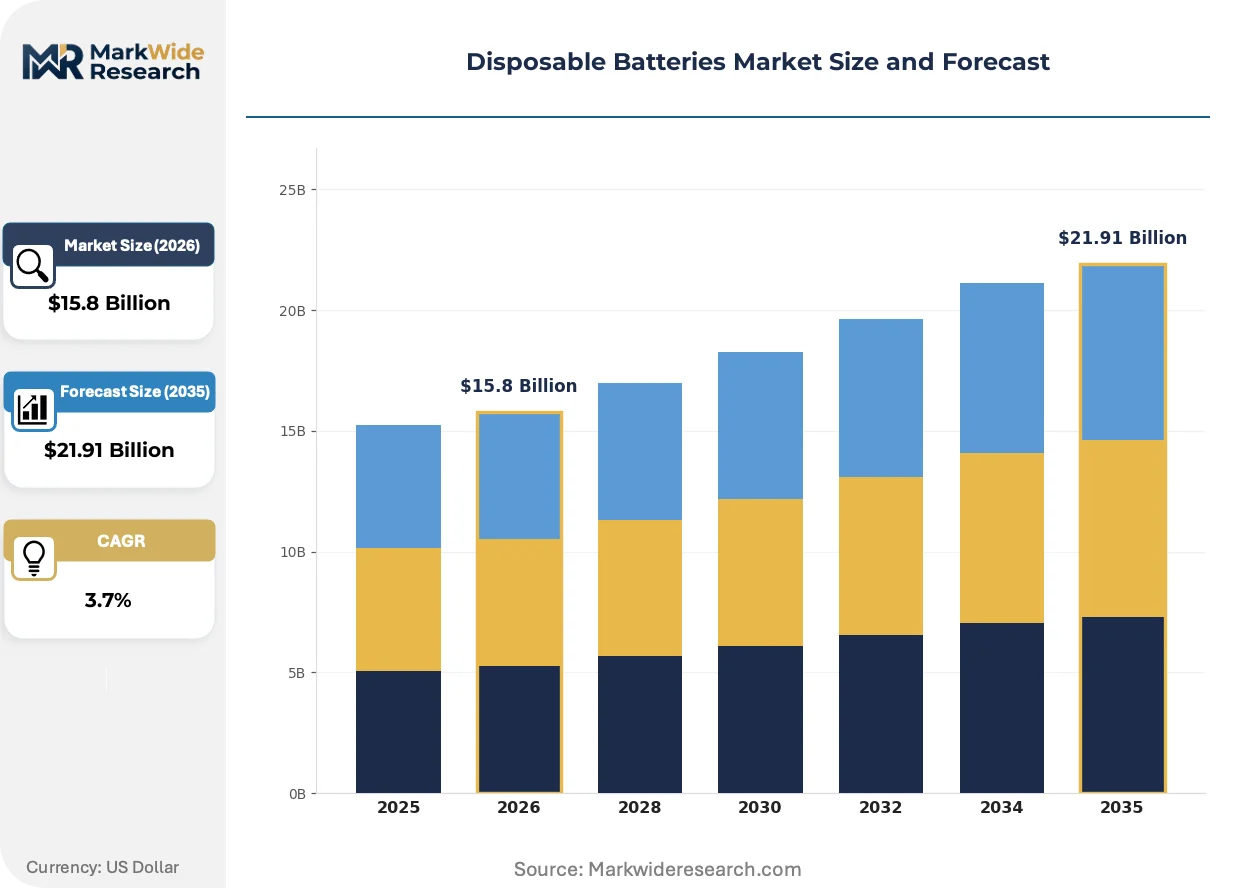
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $21.91 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, Zinc-Carbon, Lithium, Silver Oxide, Zinc-Air Application: Remote Controls, Flashlights, Personal Care Devices, Toys, Portable Electronics Packaging Type: Blister Packs, Cardboard Boxes, Plastic Shrink Wrap, Bulk Packaging End User: Consumer Electronics, Industrial Equipment, Security Systems, Medical Instruments |
| Companies Covered | GP Batteries International, Rayovac, Duracell Inc., Sony, Changhong New Energy Tech, Energizer Battery, Inc., Eveready Industries India Ltd., Camelion Batterien GmbH, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Batteries Market Strategic Shifts & Innovations
Solid-state electrolyte research and automated disassembly robotics are converging to reshape how disposable batteries are formulated, manufactured, and recovered at end-of-life.
Lithium iron disulfide chemistry is bifurcating the premium segment from commodity alkaline. Security system installers and cold-chain logistics operators specify this chemistry for its minus-forty-degree performance envelope. The resulting demand concentration is compressing R&D budgets for legacy manganese dioxide formulations while redirecting capital toward thin-film lithium manufacturing.
EU Battery Regulation recycled content thresholds are mandating supply chain reconfiguration. Cell producers must document cobalt, lithium, and nickel recovery rates through certified collection networks. Medical device manufacturers selling into Germany and France face the steepest compliance ramps, with several firms establishing dedicated European packaging and labeling operations to satisfy national registry requirements.
Direct procurement from specialty distributors is displacing traditional electronics wholesale channels for industrial primary cells. Facility managers in oil and gas, telecommunications, and utility sectors now specify battery chemistries through technical procurement platforms rather than generalist distributors. This pattern is most pronounced in Texas, Alberta, and the North Sea offshore cluster, where maintenance contractors consolidate spend across remote site operations.
Disposable Batteries Market Segmentation
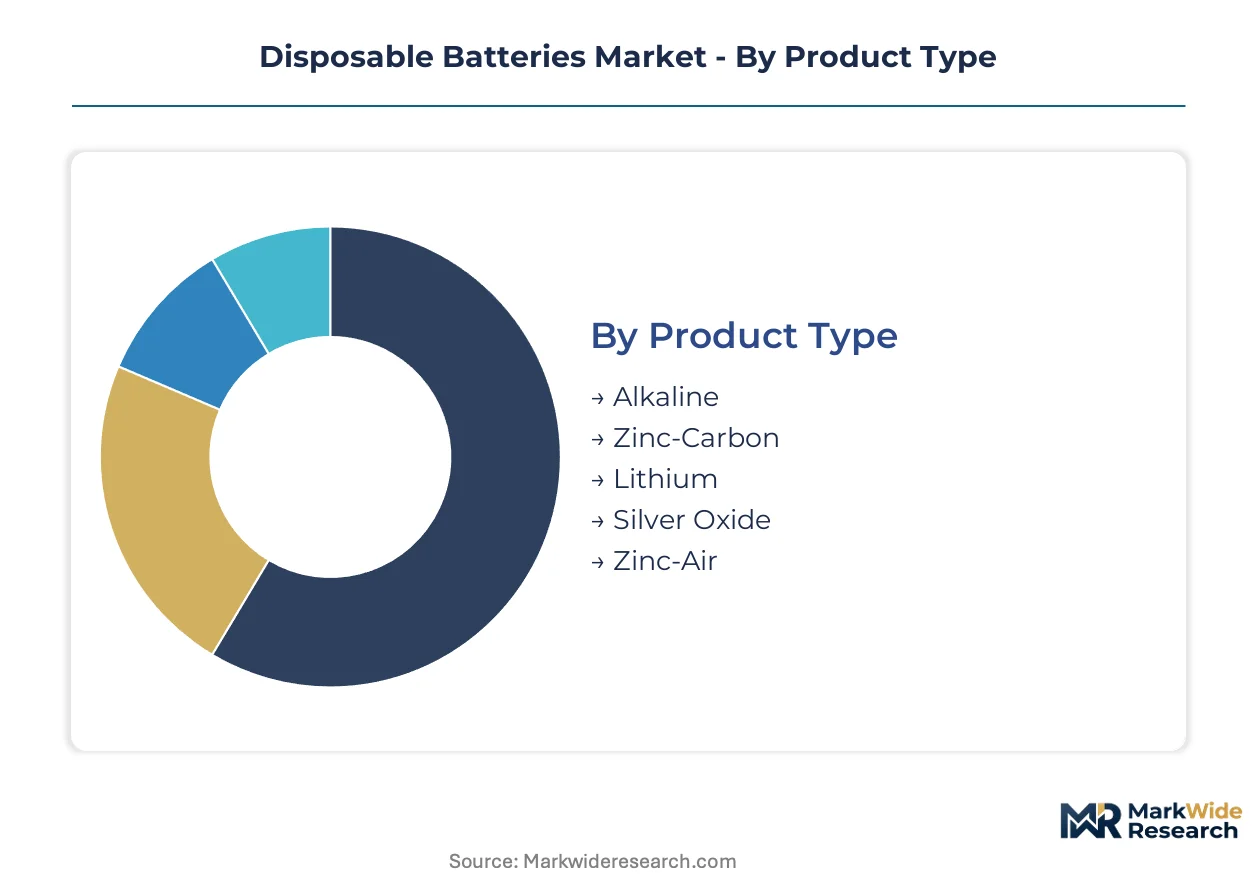
Segmentation in disposable batteries reveals how chemistry selection, packaging format, and end-use specifications create distinct margin profiles and compliance obligations across the value chain. Understanding these divisions exposes where regulatory pressure concentrates and where procurement patterns are shifting.
Product Type:
REACH substance restrictions and EU Battery Regulation recycled content mandates differentiate compliance burdens across electrochemical formulations, with lithium and silver oxide facing steeper documentation requirements than alkaline or zinc-carbon alternatives.
- Alkaline:Manganese dioxide cathodes paired with zinc anodes deliver 1.5V nominal output with balanced energy density for moderate-drain devices. Demand concentrates in North American and European retail channels for remote controls and flashlights, where shelf stability and brand recognition sustain volume despite rechargeable substitution pressure.
- Lithium:Iron disulfide and thionyl chloride variants operate across minus-forty to sixty-degree Celsius ranges with sub-one-percent annual self-discharge. Medical instrument OEMs in Germany and Japan specify these cells for glucose monitors and pulse oximeters requiring decade-long operational reliability under FDA and PMDA scrutiny.
- Zinc-Carbon:Leclanché chemistry retains cost advantage through simple zinc anode and ammonium chloride electrolyte construction. Rural electrification gaps in India and tier-3 African markets sustain demand for basic lighting and radio applications where price sensitivity overrides performance specifications.
- Silver Oxide:Button cell format with zinc-silver oxide chemistry delivers stable voltage discharge curves for precision instruments. Mercury-free formulations are accelerating under REACH restrictions for European watch and calculator manufacturers.
- Zinc-Air:Atmospheric oxygen cathode design yields highest energy density among aqueous systems for hearing aid applications. Miniaturization trends in personal audio devices are expanding miniature cell procurement from Danish and Swiss hearing instrument specialists.
Established volume favors alkaline; emerging adoption favors lithium.
Application:
Power consumption profiles and duty cycle requirements stratify procurement specifications, with continuous-draw medical and security applications demanding chemistry-grade validation that intermittent-use consumer segments rarely require.
- Remote Controls:Low-drain infrared and RF transmission circuits prioritize shelf stability over peak current delivery. Alkaline cells dominate North American and Japanese living room electronics, though USB-C rechargeable NiMH substitution is accelerating in Korean and Chinese smart home deployments.
- Flashlights:High-drain LED drivers and intermittent emergency use patterns favor lithium primary cells for cold-weather reliability. Industrial safety coordinators in Alberta oil sands and North Sea offshore platforms specify lithium iron disulfide for minus-forty-degree performance envelopes.
- Personal Care Devices:Electric toothbrushes, grooming tools, and beauty appliances require vibration-tolerant cell construction. Waterproofing requirements in shower-adjacent applications are driving gasket-sealed alkaline procurement from German and Japanese appliance OEMs.
- Toys:High-volume seasonal demand with moderate drain characteristics sustains zinc-carbon relevance in price-sensitive markets. Safety certification complexity under ASTM and EN 71 standards is pushing major brands toward alkaline for liability mitigation.
- Portable Electronics:Digital cameras, handheld gaming, and portable audio demand high-pulse-current capability. Lithium primary cells are climbing fastest in premium compact electronics where weight reduction and cold-weather reliability justify unit cost premiums.
Seasonal volume concentrates in toys; reliability premiums concentrate in portable electronics.
Packaging Type:
Retail channel configuration and industrial procurement scale determine format selection, with sustainability mandates reshaping material specifications differently across consumer-facing and B2B segments.
- Blister Packs:Thermoformed PVC or PET trays with printed card backing dominate supermarket and electronics retail display. EU single-use plastics directives are forcing German and French retailers toward fiber-based alternatives with reduced petroleum-derived content.
- Cardboard Boxes:Corrugated containment for multi-cell industrial shipments aligns with warehouse club and facility management procurement. Bulk pharmaceutical and medical device OEMs in Switzerland and the Netherlands specify recycled-content cardboard for ESG reporting alignment.
- Plastic Shrink Wrap:Polyolefin film bundling for multi-packs offers tamper evidence and moisture protection. Cost-sensitive emerging market distributors in India and Southeast Asia favor this format for transportation durability in humid climates.
- Bulk Packaging:Unpackaged cell trays or loose-fill containers for automated assembly line feeding. Industrial IoT sensor manufacturers in Texas and Alberta specify bulk lithium thionyl chloride delivery to minimize handling labor in remote site deployments.
Consumer visibility favors blister packs; procurement efficiency favors bulk packaging.
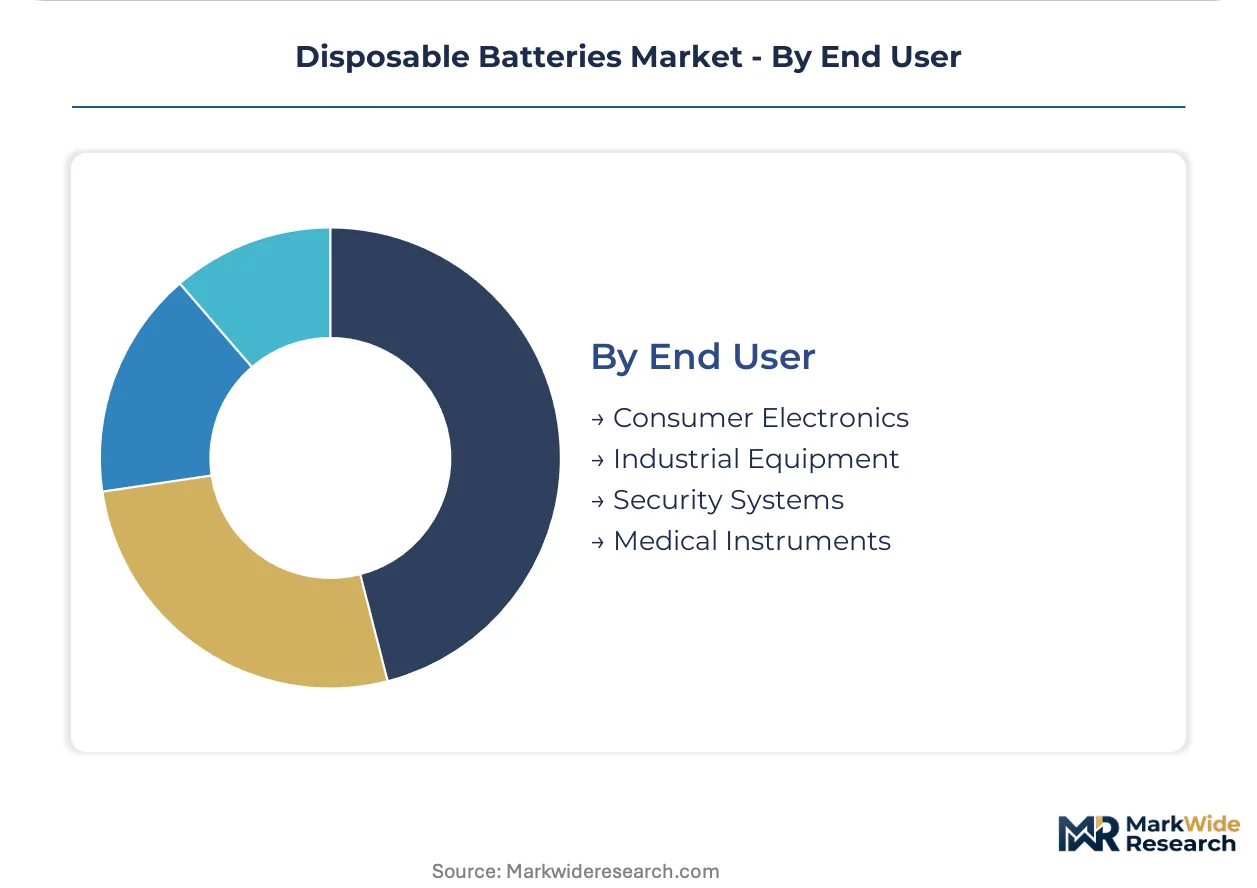
End User:
Validation requirements and operational criticality create tiered supply relationships, with medical and industrial segments demanding lot traceability and chemistry certification that consumer channels rarely enforce.
- Consumer Electronics:Mass-market OEM procurement prioritizes unit cost and supply security over performance differentiation. Original equipment specifications from Japanese and Korean television manufacturers are standardizing on alkaline for remote bundled inclusion.
- Industrial Equipment:Asset tracking sensors, pipeline monitors, and environmental loggers require wide-temperature lithium thionyl chloride with twenty-year operational life. Oil and gas facility managers in Texas and the North Sea are consolidating primary cell spend through technical procurement platforms.
- Security Systems:Wireless motion detectors, glass break sensors, and control panel backup demand decade-long standby reliability. Installer networks in Germany and France specify lithium iron disulfide for minus-forty-degree performance in unheated commercial premises.
- Medical Instruments:FDA and CE-marked devices require chemistry-grade documentation and lot-level traceability. Home-use glucose monitor manufacturers in Germany and Massachusetts face dual certification timelines extending product launch cycles eighteen to twenty-four months.
Volume scale favors consumer electronics; margin premium favors medical instruments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Industrial buyers in Germany and Japan specify lithium primary cells for medical instruments and security systems. Rural households in India and tier-3 African markets sustain zinc-carbon volume for basic lighting. North American retail channels favor alkaline bundled with consumer electronics.
United States
Security system installers and oilfield facility managers drive lithium iron disulfide procurement for cold-weather reliability. EPA hazardous waste classifications govern end-of-life handling for mercury-containing chemistries. Texas and Alberta oil sands operators consolidate primary cell spend through technical procurement platforms for remote site deployments.
Germany
Medical device OEMs in Baden-Württemberg and Bavaria specify lithium primary cells for glucose monitors requiring decade-long shelf stability. EU Battery Regulation recycled content thresholds mandate supply chain reconfiguration through certified collection networks. Stuttgart and Munich house dedicated European packaging operations serving German and French national registry requirements.
Japan
PMDA scrutiny and precision instrumentation demand anchor premium lithium primary cell supply for industrial and medical OEMs. METI efficiency standards and JIS certification frameworks shape domestic procurement specifications. Kanto and Kansai manufacturing clusters concentrate thin-film lithium production for advanced medical applications.
India
Rural electrification gaps in tier-3 towns and villages sustain zinc-carbon demand for basic lighting and radios. BIS certification and E-Waste Management Rules impose conformity testing and extended producer responsibility on importers and domestic manufacturers. Eveready Industries anchors volume production from Kolkata and Noida facilities serving price-sensitive mass markets.
China
Consumer electronics OEMs in Shenzhen and Dongguan standardize alkaline bundled with television remotes and flashlights. GB standards and MIIT industrial policy guide domestic manufacturing scale investments. Yangtze River Delta producers supply private-label alkaline cells to North American and European retail channels.
Disposable Batteries Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with brand equity and retail shelf dominance separating mass-market alkaline producers from premium lithium cell developers. The competitive landscape bifurcates between legacy mass producers sustaining manufacturing scale through private-label partnerships and specialized developers serving medical and industrial OEMs with chemistry-grade validation. Three archetypes dominate: brand-anchored consumer players, industrial-specialist lithium suppliers, and emerging-market zinc-carbon volume producers. Capacity expansion and design-for-recycling reconfiguration represent the dominant competitive moves as EU regulatory timelines compress.
Among brand-anchored consumer players, Duracell Inc. and Energizer Battery, Inc. occupy positions defined by retail channel dominance and continuous manufacturing investments. Panasonic Corporation exemplifies the industrial-specialist archetype, anchoring premium lithium supply for medical instrument OEMs in Japan and select Asian markets. Eveready Industries India Ltd. represents the emerging-market volume producer, sustaining zinc-carbon and alkaline production for rural electrification gaps and price-sensitive mass channels.
| Leading Market Players |
|---|
| GP Batteries International |
| Rayovac |
| Duracell Inc. |
| Sony |
| Changhong New Energy Tech |
| Energizer Battery, Inc. |
| Eveready Industries India Ltd. |
| Camelion Batterien GmbH |
| Panasonic Corporation |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between medical device OEMs and specialty lithium suppliers lock in both cathode material access and decade-long price visibility against manganese dioxide spot market swings. These contracts insulate procurement teams from Gabon mining output disruptions while compressing margins for contract manufacturers locked into alkaline commodity pricing.
Pricing Analysis
Contract-based long-term offtake dominates procurement for medical instrument OEMs requiring lithium iron disulfide with FDA chemistry-grade documentation. Pricing stratifies across premium lithium primary cells, standard alkaline formulations, and economy zinc-carbon tiers based on certification level and volume scale. Cost compression in alkaline runs through manganese dioxide price volatility from South African mining disruptions. Industrial IoT buyers exhibit lowest price sensitivity due to twenty-year operational life requirements; rural Indian distributors show highest sensitivity where zinc-carbon unit economics determine purchase decisions.
Supply Chain Analysis
Strategic stockpiling of primary cell-grade lithium metal prevails among Japanese and German medical device manufacturers facing Chilean supply concentration risks. Raw material sourcing draws from Chilean and Argentine lithium brine operations, Gabonese and South African manganese dioxide mines, and Korean electrolyte additive specialists. Single-source vulnerability in lithium metal refining creates exposure to Atacama Basin water rights disputes. Distribution runs through technical procurement platforms for industrial buyers and mass retail channels for consumer alkaline volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among industrial facility managers consolidating primary cell spend across remote oilfield and offshore operations. Technical procurement platforms in Texas and the North Sea now aggregate demand sufficient to influence supplier qualification standards.
For Market Incumbents: Compound brand equity in retail alkaline through private-label partnership density while redirecting R&D capital toward thin-film lithium production for medical OEMs. Defend against rechargeable NiMH substitution by emphasizing shelf stability in emergency preparedness kits. Prioritize backward integration into manganese dioxide sourcing to offset Gabon supply volatility.
For New Entrants and Emerging Players: Differentiate on design-for-recycling modular cell architectures that satisfy EU Battery Regulation material separation mandates. Target industrial IoT sensor deployments in smart agriculture and cold-chain logistics where lithium thionyl chloride specifications remain underserved. Pursue direct technical procurement platform relationships rather than generalist distributor channels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialty lithium suppliers with decade-long medical device OEM contracts and chemistry-grade validation capabilities. Five-to-ten-year viability favors industrial-specialist archetypes over mass-market alkaline producers facing rechargeable substitution. Monitor BIS certification pathway acceleration in India as inflection signal for zinc-carbon import volume shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-for-Recycling Cell Architecture | Modular constructions ease material separation under EU Battery Regulation collection targets. |
| Thin-Film Lithium Manufacturing Scale-Up | Japanese and German medical OEMs specify advanced cells for glucose monitor applications. |
| Technical Procurement Platform Integration | Texas oilfield managers consolidate spend across remote site operations through specialized channels. |
| BIS Certification Pathway Investment | Streamlined Indian conformity assessment accelerates market entry for compliant Asian manufacturers. |
| Mercury-Free Silver Oxide Formulation | REACH restrictions accelerate adoption for European watch and precision instrument manufacturers. |
Research Approach
A standing panel of electrochemical engineering directors, medical device procurement managers, industrial facility maintenance heads, and retail category buyers provided ongoing calibration across primary interview rounds. Secondary validation drew from EPA hazardous waste classifications, ECHA REACH substance databases, BIS conformity assessment records, and customs trade flow documentation. Bottom-up cell chemistry demand modeling triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by electrochemical formulation, packaging format, end-use application, and regional regulatory cluster. CAGRs were derived from chemistry-specific demand curves incorporating medical instrument OEM procurement cycles and rural electrification gap persistence. Forecast inputs included manganese dioxide mining output projections and lithium metal refinery capacity announcements.
The analysis sits within stated boundaries; outcomes outside sustained EU Battery Regulation enforcement or abrupt rechargeable technology cost reductions would require recalibration. Forecasts reflect documented assumptions regarding medical device certification timelines and industrial IoT deployment rates. Revision becomes warranted when lithium metal supply concentration crosses geopolitical disruption thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Low Temperature Battery Market
Batteries
Bio Based Battery Market
Batteries
Yacht Battery Market
Batteries
DMC for Battery Market
Batteries
Nimh Battery Market
Batteries
Military Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Battery Cell Market
Batteries
Power Tool Batteries Market
Batteries
Lithium Thionyl Chloride Battery Market
Batteries
Nas Battery Market
Batteries
Battery Pack Balancer Market
Batteries
Asia Power Tool Batteries Market
Batteries
Zinc-Manganese Oxide Batteries Market
Batteries
Aluminum-Air Battery Market
Batteries
South America Consumer Battery Market