
 Floor Scrubber Battery Market | 2026-2036
Floor Scrubber Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Scrubber Battery Market Analytics
China is reconfiguring its battery component supply chains to serve the floor scrubber segment with dedicated lithium-ion cell lines. EnerSys leverages its North American distribution network to dominate aftermarket replacement cycles. Crown Battery sustains its position through deep specialization in deep-cycle lead-acid architectures for price-sensitive institutional buyers.
Floor scrubber batteries are electrochemical energy storage systems engineered for deep-cycle discharge, typically operating at 24V to 48V with capacities optimized for continuous 4-8 hour cleaning shifts. Lithium-ion chemistries now displace lead-acid in commercial end-user fleets where runtime extension and opportunity charging justify higher upfront capital outlay. Sealed AGM technology retains substantial share in institutional settings where maintenance staff scarcity elevates total-cost-of-ownership calculations over raw energy density metrics.
OSHA indoor air quality standards and California CARB regulations constrain lead-acid deployment in enclosed commercial spaces, directly steering procurement toward sealed lithium-ion alternatives. The EU Battery Directive and REACH substance restrictions add compliance layers for imports entering European distribution channels. Stakeholders must track how regional safety certifications fragment product platform strategies across jurisdictions.
Market Dynamics
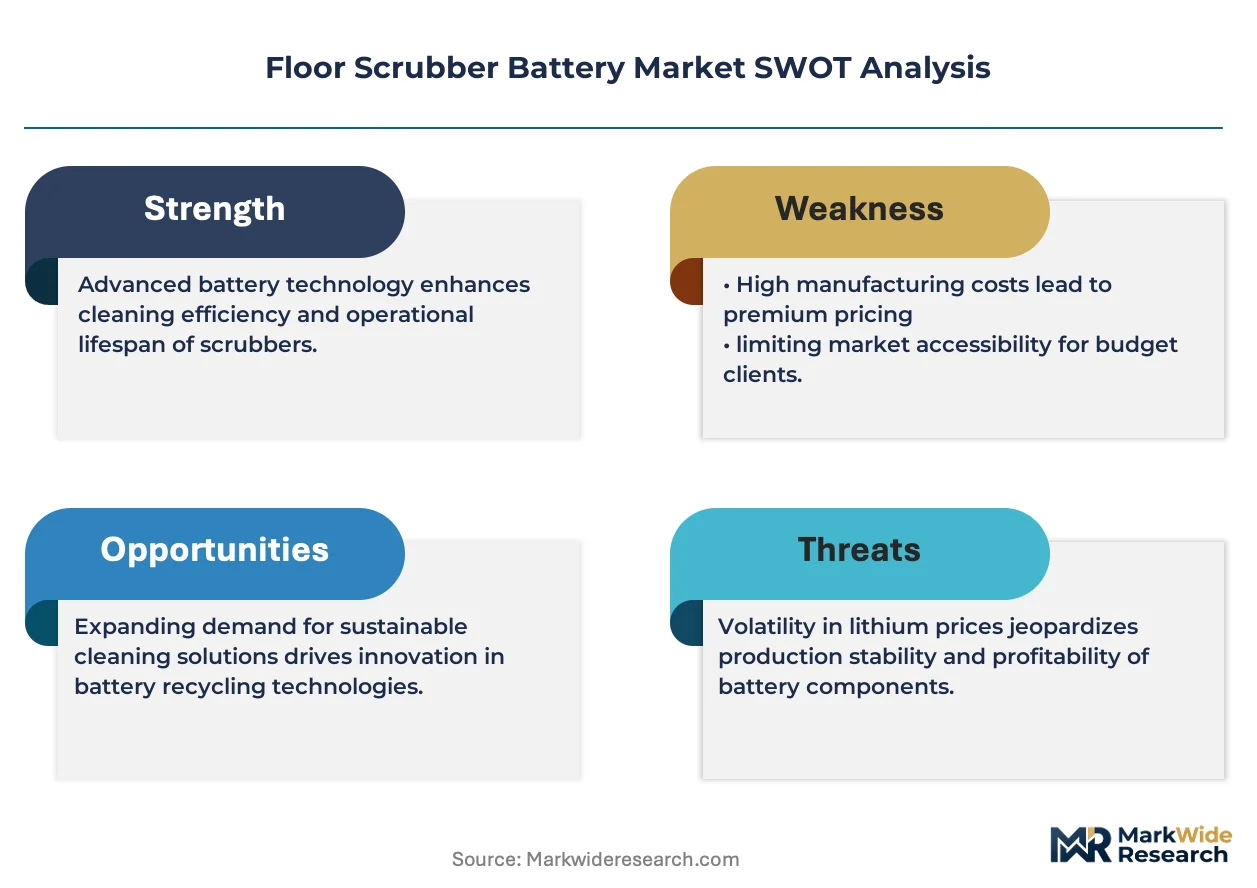
The floor scrubber battery market is being fundamentally restructured by lithium-ion chemistry substitution, driven by indoor air quality mandates that render lead-acid systems operationally untenable in enclosed commercial environments.
Growth Catalysts
- OSHA workplace exposure limits:Federal indoor air quality standards in the United States prohibit lead-acid battery gassing in enclosed logistics facilities, forcing fleet conversions to sealed lithium-ion alternatives.
- Opportunity charging infrastructure:Rapid-charge dock systems enable 24/7 cleaning operations in distribution centers, eliminating the 8-hour shift downtime that constrained lead-acid economics.
- California CARB standards:The state's commercial indoor emissions regulations create precedent-setting compliance pressure that propagates through national retail and warehouse chains headquartered in the state.
Market Restraints
- Lithium carbonate price volatility:Cathode material cost swings compress OEM margins and delay payback calculations for fleet operators evaluating chemistry conversion.
- Cell supply concentration:Cylindrical lithium-ion production for industrial applications clusters in East Asian manufacturing zones, exposing procurement to geopolitical logistics friction.
- Lead-acid residual infrastructure:Existing charging stations, maintenance tooling, and technician training create switching cost inertia for institutional buyers with sunk capital in legacy systems.
Strategic Opportunities
- EU Battery Directive compliance services:European importers face mandatory carbon footprint disclosure and recycled content thresholds, creating advisory and certification revenue streams for testing laboratories.
- Second-life automotive cell repurposing:Degraded electric vehicle battery packs retain sufficient capacity for floor scrubber duty cycles, opening circular supply chains for cost-sensitive municipal and educational buyers.
- Battery-as-a-service models:Leasing structures transfer capital burden from facility managers to suppliers, accelerating adoption among small commercial cleaning contractors with constrained balance sheets.
Industry Challenges
- UL 2580 thermal runaway certification:Lithium-ion pack validation for commercial floor equipment requires 12-18 month test cycles, delaying product launches and freezing development roadmaps.
- Legacy fleet integration complexity:Mixed-voltage environments (24V lead-acid alongside 36V/48V lithium-ion) demand dual infrastructure investments that fragment procurement decisions across facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Scrubber Battery Market |
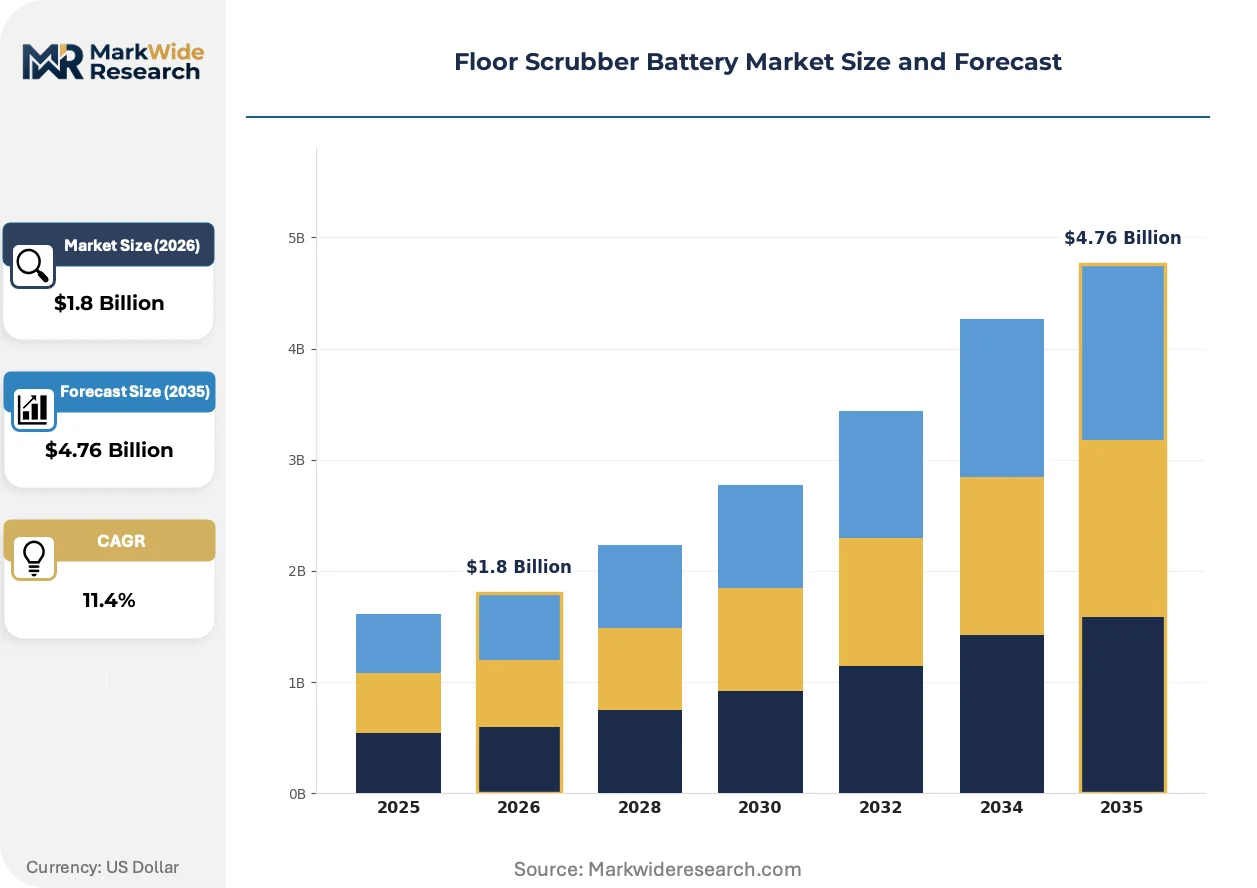
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead Acid, Lithium-ion, Nickel Cadmium, Gel End User: Commercial, Industrial, Institutional, Residential Technology: Sealed, Gel Cell, Flooded, AGM Capacity: 24V, 36V, 48V, Others |
| Companies Covered | Crown Battery, East Penn Manufacturing, EnerSys, Exide Technologies, Trojan Battery Company, U.S. Battery Manufacturing, Blue Line Battery Inc., Flux Power, Discover Battery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Scrubber Battery Market Evolving Landscape
Lithium-ion cell virtualization is compressing the hardware-software boundary in floor scrubber power systems, enabling predictive maintenance and fleet optimization that lead-acid architectures cannot support.
Battery management system virtualization is virtualizing how energy storage is monitored and controlled in commercial cleaning equipment. Large retail distribution centers and third-party logistics operators are deploying cloud-connected packs at accelerating rates. This virtualization is virtualizing the traditional separation between power hardware and operational software, allowing fleet managers to optimize charge cycles across hundreds of units from centralized dashboards.
REACH substance restrictions and the EU Battery Directive are tightening material traceability requirements for cells entering European commercial channels. Manufacturers must now document cobalt sourcing and establish recycling partnerships before market entry. Pack assemblers serving German and French cleaning equipment OEMs are restructuring supplier qualification protocols to preempt regulatory rejection at customs.
Facility managers are consolidating vendor relationships from equipment-plus-battery separate purchasing toward integrated powertrain procurement. This concentration is compressing the aftermarket replacement channel and elevating OEM captive finance offerings. The shift is most pronounced in United States big-box retail chains operating standardized national cleaning fleets.
Floor Scrubber Battery Market Segmentation
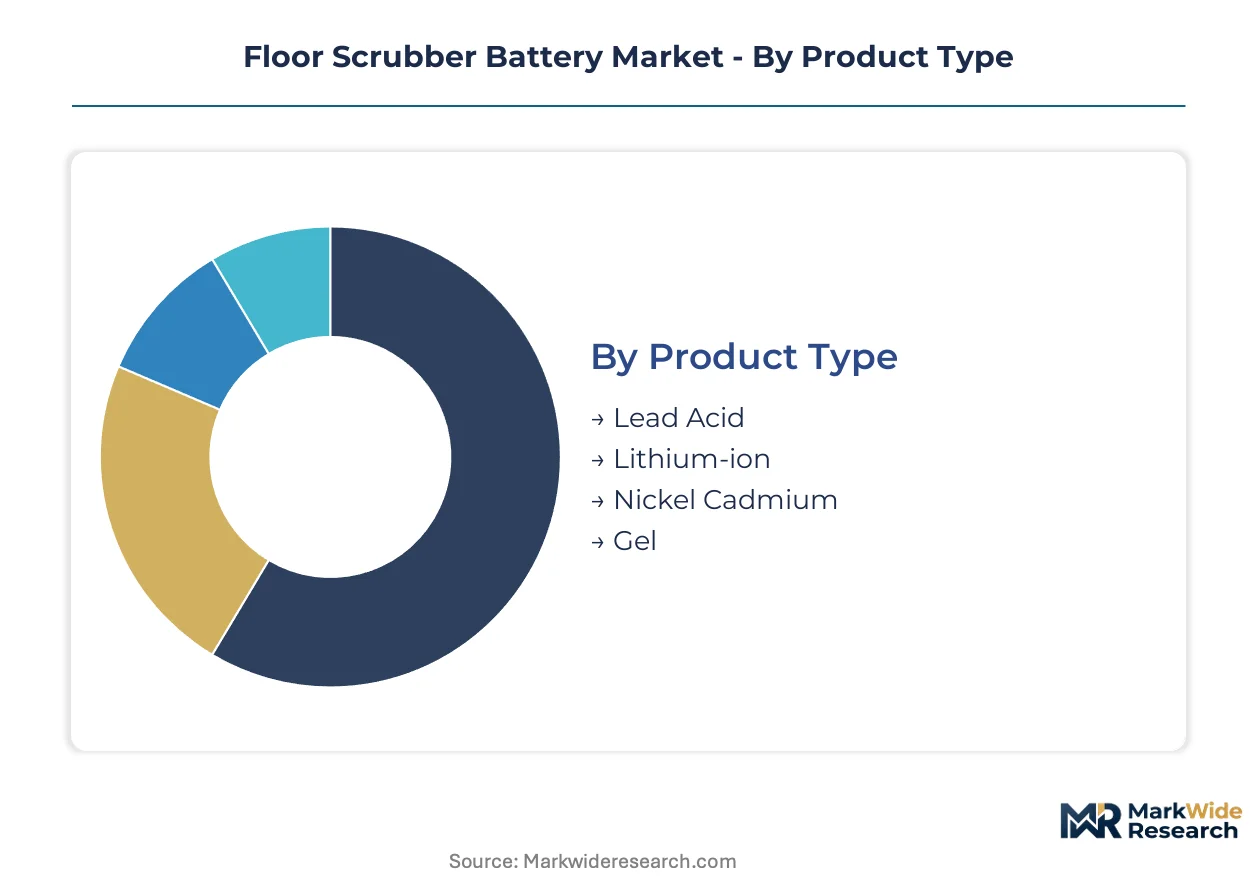
Floor scrubber battery procurement splits across chemistry, voltage, and operational environment, each dimension carrying distinct service lifecycle implications. Replacement cycle frequency and technical support intensity vary dramatically between sealed lithium-ion packs for 24/7 distribution centers and flooded lead-acid systems in municipal maintenance yards.
Product Type:
After-sales-service intensity diverges sharply across chemistries, with lithium-ion demanding specialized thermal management diagnostics and lead-acid requiring electrolyte monitoring and watering protocols.
- Lithium-ion:Energy-dense cylindrical or prismatic cells with integrated battery management systems enable opportunity charging and 4,000+ cycle lifespans. Demand concentrates in United States retail distribution centers where OSHA indoor air quality mandates prohibit lead-acid gassing and California CARB standards accelerate fleet electrification timelines.
- Lead Acid:Mature flooded or sealed architectures deliver lower capital cost per kilowatt-hour but impose 8-hour charging cycles and ventilation requirements. Institutional buyers in price-sensitive municipal and educational segments sustain residual demand despite regulatory pressure in enclosed commercial environments.
- Gel:Valve-regulated lead-acid with immobilized electrolyte offers maintenance-free operation for intermittent-use cleaning fleets.
- Nickel Cadmium:Rugged chemistry tolerates extreme temperature swings in outdoor or unconditioned storage applications.
By volume, Lead Acid leads. By growth pace, Lithium-ion is expanding most quickly.
End User:
Procurement authority structures fragment across customer types, with industrial buyers centralizing fleet decisions at headquarters while institutional purchasers delegate to facilities managers with constrained capital budgets.
- Industrial:Third-party logistics operators and manufacturing facilities run continuous cleaning shifts across million-square-foot footprints. These buyers prioritize runtime extension and rapid charging to eliminate shift-change downtime, driving lithium-ion adoption in United States warehouse clusters near Chicago, Dallas, and Atlanta.
- Commercial:Retail chains and hospitality groups standardize equipment across national portfolios. Procurement teams negotiate integrated powertrain packages that bundle scrubber chassis with captive battery supply, compressing aftermarket channel margins.
- Institutional:Government buildings, hospitals, and universities balance upfront cost constraints against maintenance staff scarcity, favoring sealed AGM technologies.
- Residential:Small commercial cleaning contractors and building service operators purchase through distributor networks with limited technical support infrastructure.
Industrial buyers command the largest unit volumes. Commercial segments are gaining share fastest as retail chains consolidate vendor relationships.
Technology:
Cell construction determines maintenance burden and installation flexibility, with sealed designs eliminating ventilation infrastructure and flooded variants retaining cost advantages for open-air operations.
- AGM:Absorbent glass mat separators immobilize electrolyte in thin-fiber matrices, enabling vibration resistance and any-orientation mounting. United States airport terminals and hospital corridors specify AGM for spill-proof compliance with Joint Commission safety standards.
- Sealed:Maintenance-free operation appeals to facilities with limited trained technician availability, particularly in multi-site commercial portfolios.
- Gel Cell:Thixotropic electrolyte formulation withstands deep discharge cycling better than standard AGM in intermittent-use patterns.
- Flooded:Removable cell caps permit specific gravity testing and electrolyte replacement, sustaining presence in outdoor municipal fleets with adequate ventilation.
AGM dominates current procurement volumes. Sealed technology is climbing the fastest as maintenance staff scarcity elevates total-cost-of-ownership calculations.
Capacity:
Voltage selection correlates with scrubber platform size and cleaning path width, creating distinct procurement clusters across walk-behind and ride-on equipment categories.
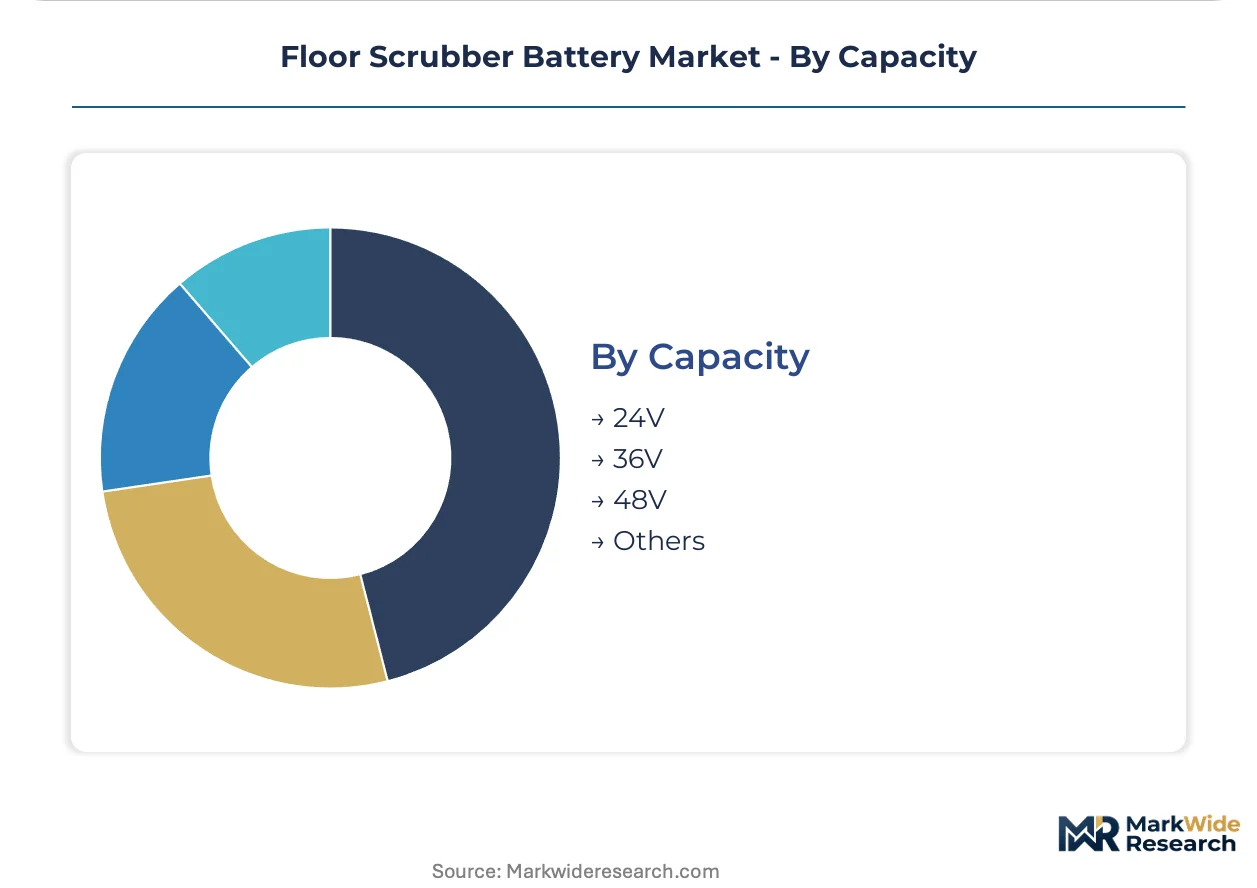
- 24V:Standard for walk-behind scrubbers in 20-28 inch cleaning paths. Compact form factors suit narrow retail aisles and congested back-of-house environments in United States grocery and big-box chains.
- 36V:Mid-size ride-on platforms serving 32-40 inch paths in distribution centers and manufacturing floors.
- 48V:Industrial-grade ride-on machines with 50+ inch paths and solution recovery tanks exceeding 100 gallons.
- Others:Specialized voltages for custom OEM platforms and legacy fleet retrofits.
24V systems lead by installed base. 48V configurations are gaining share fastest as distribution centers expand cleaning equipment scale to match facility footprints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian cell manufacturing dominates lithium-ion supply for floor scrubber applications, while North American demand concentrates in warehouse clusters responding to indoor air quality mandates. Distribution center electrification and regulatory pressure are reconfiguring procurement geography across three continents.
United States
Third-party logistics operators and retail distribution centers in Chicago, Dallas, and Atlanta are converting lead-acid fleets to lithium-ion to satisfy OSHA workplace exposure limits. California's CARB commercial indoor emissions standards propagate through national chains headquartered in the state. The Inland Empire warehouse cluster east of Los Angeles anchors the fastest fleet replacement velocity.
Germany
Industrial cleaning equipment OEMs in Baden-Württemberg and Bavaria specify battery packs compliant with REACH substance restrictions and the EU Battery Directive's carbon footprint disclosure rules. The country's national chemical regulator enforces strict cobalt sourcing documentation for cells entering European distribution. Stuttgart's manufacturing corridor drives premium sealed lithium-ion procurement for export-oriented machine builders.
China
Domestic cell producers are dedicating cylindrical lithium-ion lines to industrial equipment segments including floor scrubbers. The Ministry of Industry and Information Technology's dual carbon goals accelerate factory electrification mandates that indirectly boost cleaning equipment demand. The Yangtze River Delta manufacturing zone concentrates pack assembly operations serving both domestic logistics parks and export markets.
Japan
Automotive battery pack assemblers are repurposing degraded electric vehicle cells for secondary-use floor scrubber applications under METI circular economy guidelines. The country's industrial standards body certifies thermal management systems for commercial cleaning equipment. The Nagoya manufacturing belt hosts pilot programs integrating second-life cells into municipal cleaning fleets.
Canada
Airport authorities and hospital networks in Toronto and Vancouver specify spill-proof AGM and sealed lithium-ion technologies to comply with Health Canada indoor air quality guidance. The country's national pharmaceutical regulator influences procurement standards in healthcare-adjacent cleaning operations. Ontario's Golden Horseshoe logistics corridor is standardizing on opportunity-charging lithium-ion configurations for 24/7 distribution operations.
Floor Scrubber Battery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cell supply and battery management systems. The vendor base organizes around three archetypes: legacy lead-acid manufacturers defending replacement cycles, lithium-ion pack assemblers capturing fleet conversions, and industrial battery distributors bridging technical support gaps. Consolidation pressure runs through captive finance offerings and integrated powertrain procurement. Geographic expansion and technology licensing represent the dominant competitive vectors.
Among North American-established manufacturers, Crown Battery and East Penn Manufacturing exemplify the deep-cycle specialization archetype, while EnerSys occupies a position spanning both legacy lead-acid distribution and lithium-ion transition strategies. These companies anchor the aftermarket replacement channel even as procurement shifts toward OEM-integrated powertrain packages.
| Leading Market Players |
|---|
| Crown Battery |
| East Penn Manufacturing |
| EnerSys |
| Exide Technologies |
| Trojan Battery Company |
| U.S. Battery Manufacturing |
| Blue Line Battery Inc. |
| Flux Power |
| Discover Battery |
| Others |
Value Network & Pricing Analysis
The Yangtze River Delta manufacturing cluster anchors cylindrical lithium-ion cell capacity for industrial equipment, concentrating cathode material bargaining power among a handful of integrated producers. This geographic concentration transmits downstream into pack-level pricing tiers that stratify across certification grades and thermal management sophistication.
Pricing Analysis
OSHA workplace exposure limits dictate the pricing tier structure across the United States market, segmenting procurement into UL 2580-certified premium packs, standard sealed lithium-ion configurations, and residual lead-acid economy alternatives. Price differentiation hinges on certification grade and after-sales service bundling, with premium tiers commanding substantial markups for thermal runaway documentation and fleet management software integration. Cost compression in the standard tier is intensifying because lithium carbonate volatility compresses OEM margins and delays fleet operator payback calculations. Institutional buyers in municipal and educational segments exhibit the highest price sensitivity, while third-party logistics operators prioritize runtime economics over upfront capital outlay.
Supply Chain Analysis
Contract manufacturing for battery management systems and pack assembly concentrates in Foxconn Industrial Internet and BYD Electronics facilities serving the industrial equipment segment. Cell supply draws from China, South Korea, and Japan, with cylindrical formats for deep-cycle applications resting on cathode active material flows from integrated chemical processors. Raw material dependencies span lithium carbonate, cobalt sulfate, and electrolyte solvents. Single-source vulnerability around high-nickel cathode precursors exposes procurement to geopolitical logistics friction. Distribution runs through OEM captive finance channels and industrial battery distributors bridging technical support gaps for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-as-a-service platform economics are restructuring procurement from capital expenditure to operational expenditure models, creating interoperability requirements between fleet management software and charging infrastructure networks.
For Market Incumbents: Insulate replacement cycle revenue by deepening captive finance offerings and securing exclusive supply agreements with retail distribution center operators facing OSHA compliance deadlines. Invest in UL 2580 certification capacity to accelerate product launches before emerging pack assemblers complete validation cycles. Vertical integration into battery management system firmware development preserves margin against commoditizing cell supply. For New Entrants and Emerging Players: Mid-market commercial cleaning contractors in secondary United States metropolitan areas represent the most penetrable entry point, as these buyers lack balance sheet capacity for integrated powertrain procurement and remain underserved by distributor technical support infrastructure. Second-life automotive cell repurposing for municipal and educational fleets offers a circular supply chain angle with defensible cost positioning against virgin lithium-ion packs. Target battery-as-a-service leasing structures to transfer capital burden and accelerate adoption velocity. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because indoor air quality mandates propagate through national retail chains and create durable replacement demand for sealed lithium-ion alternatives. Acquisition candidates include battery management system software specialists and regional pack assemblers with UL certification velocity. Monitor California CARB standard adoption timelines in other states as the primary inflection signal for fleet conversion acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| UL 2580 Certification Investment | Thermal runaway validation accelerates product launches before competitors complete test cycles. |
| Battery-as-a-Service Launch | Leasing structures transfer capital burden from facility managers to suppliers. |
| Second-Life Cell Partnership | Automotive pack repurposing opens circular supply chains for cost-sensitive municipal buyers. |
| Backward Integration into BMS | In-house firmware development preserves margin against commoditizing cell supply. |
| Opportunity Charging Infrastructure | Rapid-charge dock systems enable 24/7 cleaning operations in distribution centers. |
Research Methodology
Operator-level perspectives from warehouse fleet managers, commercial cleaning contractors, battery pack procurement leads, and aftermarket service technicians anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from customs trade records, OSHA enforcement databases, SEC filings of publicly traded battery manufacturers, and CARB regulatory dockets. Bottom-up unit economics from scrubber deployment models triangulated against top-down market sizing from equipment manufacturer production disclosures.
Scenario-bracketing around lithium carbonate price trajectories and regulatory adoption timelines framed the analytical envelope across the projection horizon. Segmentation dimensions modeled include chemistry type, voltage configuration, end-user category, and regional regulatory cluster. CAGRs were derived from installed base turnover rates and fleet electrification velocity assumptions. Industry-specific forecast inputs incorporated opportunity charging infrastructure penetration and second-life automotive cell supply availability.
Stress conditions across lithium raw material cost bands, OSHA enforcement intensity variations, and EU Battery Directive compliance timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet replacement cycles and chemistry conversion payback thresholds. Quarterly review of CARB standard propagation, UL 2580 certification queue lengths, and lithium carbonate spot price movements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Battery Plate Market
Batteries
United States Household Battery Market
Batteries
Flow Battery Market
Batteries
South and Central America Battery Market
Batteries
Rechargeable Battery Market
Batteries
India Lead-Acid Battery Market
Batteries
Dry Cell Battery Market
Batteries
Medical Batteries Market
Batteries
Zinc Ion Batteries Market
Batteries
Low Temperature Battery Market
Batteries
All-In-One Solar Storage Battery Market
Batteries
Marine Powerboat Battery Market
Batteries
Europe SLI Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Iron Flow Battery Market