
 Zinc-Manganese Oxide Batteries Market | 2026-2036
Zinc-Manganese Oxide Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc-Manganese Oxide Batteries Market Analytics
Lithium cobalt oxide is pivoting toward manganese-rich cathode formulations as raw material volatility reshapes cell economics. Nanfu Battery leverages captive manganese sourcing to sustain cost advantages across alkaline cell production. Panasonic Holdings Corporation anchors its industrial battery portfolio with advanced rechargeable zinc-manganese platforms for grid storage. VARTA AG competes through specialized medical device power solutions that emphasize stable discharge profiles.
Zinc-manganese oxide batteries electrochemically couple a zinc metal anode with a manganese dioxide cathode in alkaline or mildly acidic electrolytes, typically delivering nominal voltages of 1.5V for primary cells and 1.0-1.5V for rechargeable variants depending on formulation. These systems serve as cost-competitive power sources for disposable consumer electronics, backup medical equipment, and emerging grid-scale storage where cycle life requirements remain moderate. Alkaline batteries occupy the dominant revenue position due to entrenched household demand and established retail distribution through supermarkets and online retail channels. Rechargeable batteries represent the fastest-expanding product category as industrial manufacturers and renewable energy systems operators seek alternatives to lithium-ion for stationary applications with lower energy density tolerances.
China's SAMR enforces GB standards on battery safety and circularity that directly shape manganese cell design requirements for domestic producers. The EPA in the United States regulates mercury and cadmium content limits that constrain formulation choices for alkaline batteries sold through American retail channels. India's BIS certification mandates for imported cells create compliance barriers that favor local assembly partnerships. Stakeholders must monitor how evolving solid-state electrolyte research intersects with zinc-manganese chemistry to determine whether next-generation platforms displace incumbent liquid-electrolyte architectures.
Market Dynamics
Lithium supply constraints are forcing grid-scale storage operators toward rechargeable zinc-manganese systems as a chemically distinct alternative, while China's GB standards accelerate domestic manufacturing upgrades that reshape cell design requirements across East Asian production clusters.
Growth Catalysts
- Raw material volatility:Manganese-rich cathode formulations are gaining traction as cobalt price instability disrupts lithium-ion economics. Battery manufacturers are reformulating cell chemistries to reduce dependency on constrained supply chains.
- Stationary storage demand:Renewable energy systems operators are procuring zinc-manganese platforms for grid-scale installations where energy density requirements remain moderate. These systems offer cost-competitive alternatives for backup power applications.
- GB standards enforcement:China's SAMR mandates on battery safety and circularity are accelerating domestic manufacturing upgrades. Producers are redesigning cells to meet recyclability requirements that exceed previous specifications.
Market Restraints
- Cycle life limitations:Zinc-manganese rechargeable variants face technical constraints in deep-discharge applications compared to lithium-ion alternatives. Grid operators must oversize installations to compensate for capacity fade over operational lifespans.
- Mercury and cadmium content limits:The EPA in the United States constrains formulation choices for alkaline batteries sold through American retail channels. Manufacturers must reformulate legacy chemistries to maintain market access.
- Input cost volatility:Manganese dioxide pricing fluctuates with steel industry demand patterns, creating margin pressure for cell producers. Battery manufacturers lack hedging mechanisms for this commodity exposure.
Strategic Opportunities
- Medical device power solutions:Stable discharge profiles in zinc-manganese chemistry align with backup power requirements for critical healthcare equipment. Manufacturers can target hospital procurement contracts with specialized form factors.
- Online retail channel expansion:E-commerce platforms are displacing traditional supermarket distribution for consumer battery sales. Direct-to-consumer models enable premium positioning and subscription-based replenishment programs.
- Solid-state electrolyte convergence:Research programs at South Korean and Japanese cell chemistry innovation centers are exploring solid-state architectures compatible with zinc-manganese couples. Successful integration would resolve dendrite formation issues in rechargeable variants.
Industry Challenges
- Electrochemical engineering talent scarcity:Battery manufacturers face recruitment difficulties for specialists in aqueous electrolyte systems. Universities have prioritized lithium-ion research programs, creating pipeline gaps for alternative chemistries.
- BIS certification timelines:India's import mandates for cells create extended approval periods that favor local assembly partnerships. Foreign producers must navigate bureaucratic procedures that delay market entry.
- Legacy system integration complexity:Grid-scale storage operators require battery management systems compatible with existing inverter architectures. Zinc-manganese platforms need customized communication protocols that increase engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc-Manganese Oxide Batteries Market |
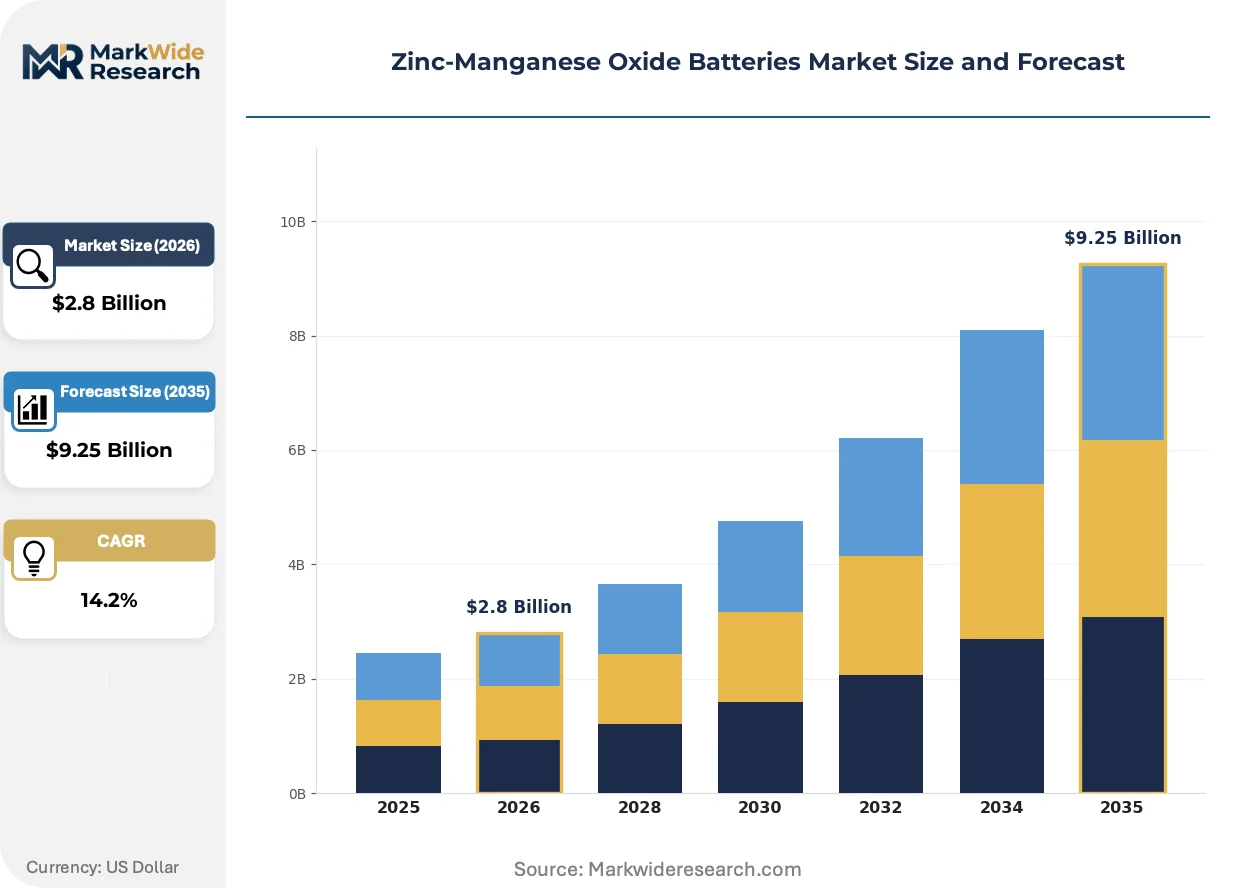
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Batteries, Rechargeable Batteries, Specialty Batteries, Silver-Oxide Batteries Application: Consumer Electronics, Power Tools, Medical Devices, Renewable Energy Systems End User: Households, Industrial Manufacturers, Healthcare Facilities, Automotive Sector Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Nanfu Battery, GPB International, Duracell, Urban Electric Power, Zhongyin (Ningbo) Battery, Panasonic Holdings Corporation, Zhejiang Mustang Battery, VARTA AG, Sunergy Battery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc-Manganese Oxide Batteries Market Evolving Landscape
Solid-state electrolyte research is intersecting with zinc-manganese chemistry to determine whether next-generation platforms displace incumbent liquid-electrolyte architectures. This technological inflection point is reshaping R&D allocation across cell manufacturers.
Manganese-rich cathode formulations are consolidating as the dominant pathway for cost reduction in alkaline and rechargeable cell production. Industrial battery manufacturers are adopting these chemistries at accelerating rates for grid storage contracts. The technology is consolidating supplier power around captive manganese sourcing capabilities that insulate producers from raw material volatility.
China's GB standards on battery safety and recyclability are mandating design changes that exceed previous domestic requirements. Cell producers must reconfigure manufacturing lines to meet circularity specifications for material recovery. The rechargeable battery segment faces the most significant compliance burden as SAMR enforcement intensifies for industrial-scale installations.
Hospital procurement departments are unbundling after-sales service from hardware contracts for backup medical equipment power systems. Buyers are negotiating separate maintenance agreements that shift performance risk to battery suppliers. This behavioral shift is most visible in Japan and South Korea where healthcare facility operators are consolidating vendor relationships around outcome-based service models.
Zinc-Manganese Oxide Batteries Market Segmentation
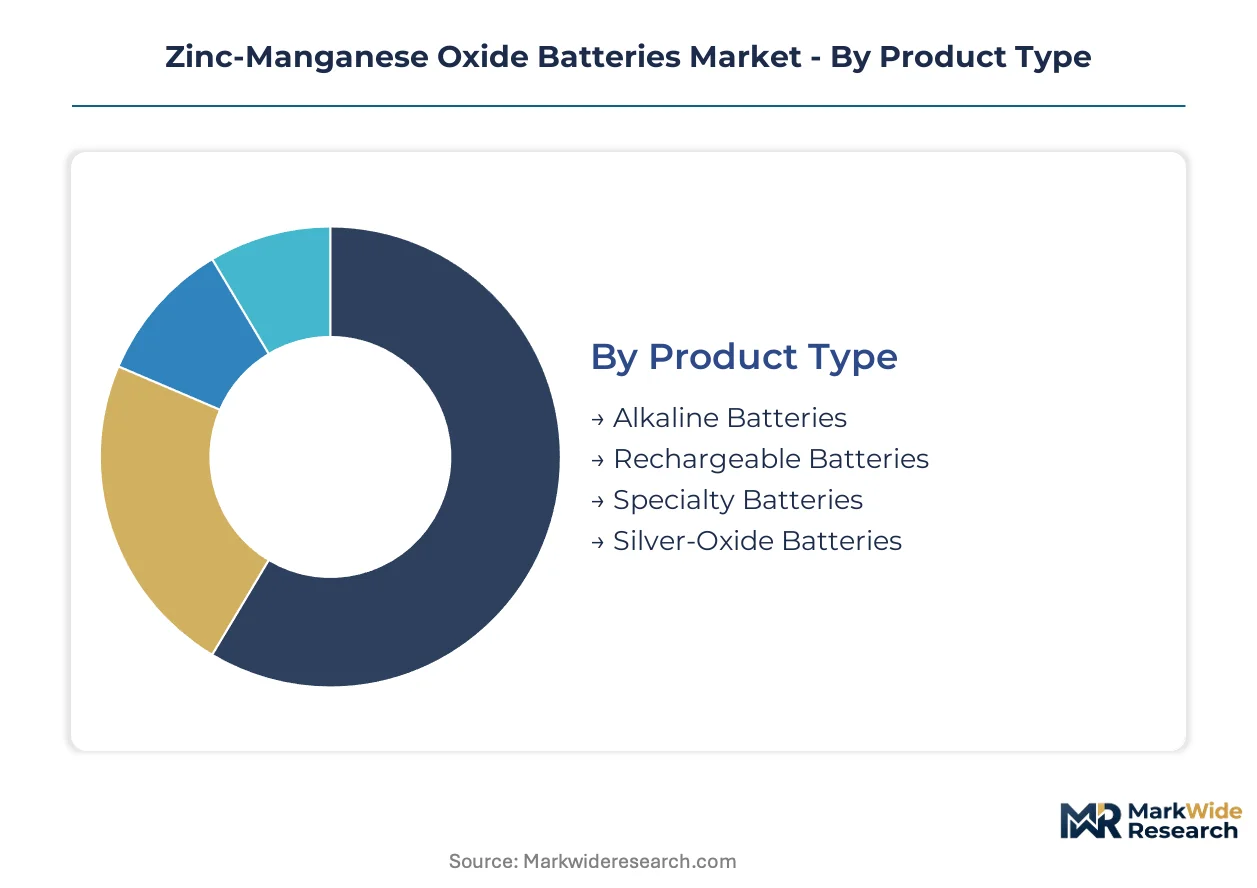
Zinc-manganese oxide battery procurement patterns diverge sharply across product architectures and end-use environments. Certification requirements from SAMR, EPA, and BIS create compliance moats that reshape competitive positioning within each segment tier.
Product Type:
GB standards enforcement by SAMR imposes divergent recyclability burdens across primary versus rechargeable cell architectures, with specialty formulations facing additional mercury-content scrutiny from EPA.
- Alkaline Batteries:Primary cells utilizing zinc metal anodes and manganese dioxide cathodes in potassium hydroxide electrolyte deliver 1.5V nominal output. Household demand through supermarket channels sustains volume leadership despite flat growth trajectories. EPA mercury limits constrain legacy formulation redesigns for US market access.
- Rechargeable Batteries:Secondary zinc-manganese systems achieve 1.0-1.5V depending on electrolyte acidity and cycling protocol. Renewable energy systems operators in South Korea and Japan are procuring these platforms for grid-scale installations where lithium-ion supply constraints intensify. SAMR circularity mandates impose the heaviest compliance burden on this segment.
- Specialty Batteries:Custom form factors for extreme temperature or vibration environments.
- Silver-Oxide Batteries:High-energy-density variants for precision instrumentation.
Alkaline batteries sit at the top of the volume ranking, with rechargeable batteries climbing the fastest.
Application:
End-use concentration determines margin structure, with medical and renewable energy applications commanding premium positioning against commoditized consumer segments.
- Consumer Electronics:Remote controls, wireless peripherals, and portable audio devices drive replacement-cycle demand. Online retail channels are displacing supermarket distribution for these applications. BIS certification timelines create entry barriers for imported cells serving Indian consumer markets.
- Power Tools:Cordless equipment manufacturers favor lithium-ion for energy density, relegating zinc-manganese to backup and budget-tier offerings.
- Medical Devices:Stable discharge profiles align with backup power requirements for critical healthcare equipment in Japan and South Korea. Hospital procurement departments are unbundling after-sales service from hardware contracts, shifting performance risk to battery suppliers.
- Renewable Energy Systems:Grid-scale storage operators are expanding procurement of rechargeable zinc-manganese platforms where cycle life requirements remain moderate. These installations compensate for capacity fade through oversizing strategies.
Consumer electronics maintains volume dominance, though renewable energy systems gain share fastest.
End User:
Customer type dictates purchasing modality, with industrial buyers negotiating long-term supply agreements against household transactional patterns.
- Households:Price-sensitive replacement demand through retail channels.
- Industrial Manufacturers:Grid-scale storage operators and equipment OEMs procure through direct sales with customized form factors.
- Healthcare Facilities:Japanese and South Korean hospital systems consolidate vendor relationships around outcome-based service models for backup power systems.
- Automotive Sector:Limited penetration confined to auxiliary power and legacy internal combustion applications.
Households anchor volume rankings, with healthcare facilities expanding fastest.
Distribution Channel:
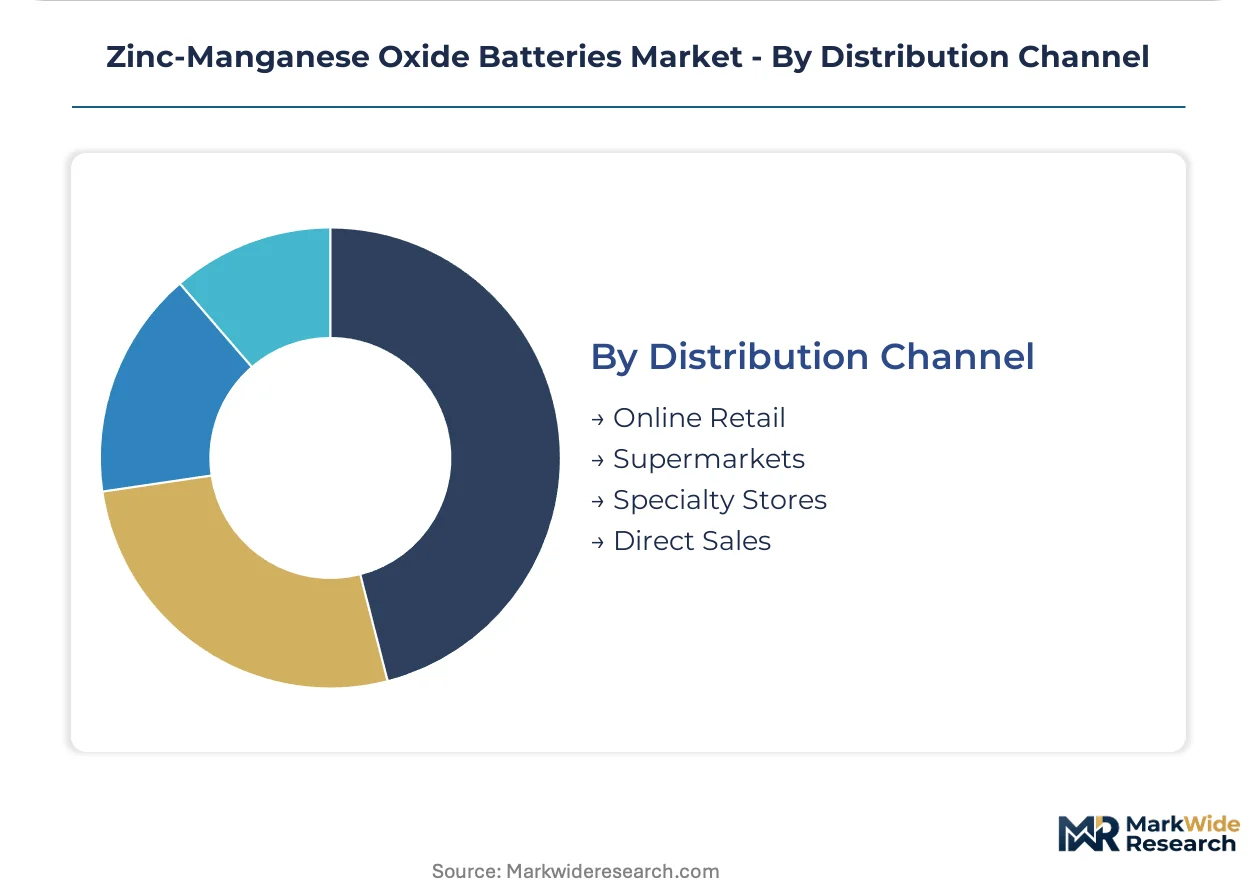
Channel mix determines working capital intensity and margin capture, with direct sales enabling premium positioning against mass retail price compression.
- Online Retail:E-commerce platforms enable subscription-based replenishment programs and direct-to-consumer premium positioning. This channel is displacing traditional supermarket distribution for consumer battery sales.
- Supermarkets:Entrenched alkaline battery volume through impulse and planned replenishment purchases.
- Specialty Stores:Electronics retailers and industrial supply distributors serve professional and enthusiast segments.
- Direct Sales:Industrial battery manufacturers engage grid-scale storage operators and healthcare procurement departments through negotiated contracts.
Supermarkets retain volume leadership, with online retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian production clusters anchor manufacturing capacity for zinc-manganese oxide batteries, with cell chemistry innovation programs concentrated in South Korean and Japanese industrial zones. Regulatory enforcement by China's SAMR and India's BIS reshape competitive access across the largest demand markets.
China
Domestic manufacturers expand rechargeable cell output for grid-scale storage contracts as lithium supply constraints intensify. SAMR enforces GB standards on battery safety and circularity that accelerate manufacturing line upgrades. Ningbo and Zhejiang province host concentrated alkaline cell production serving household demand through established distribution networks.
United States
Grid operators procure zinc-manganese platforms for stationary backup installations where cycle life requirements remain moderate. EPA mercury and cadmium content limits constrain formulation choices for alkaline batteries sold through American retail channels. Industrial battery specialists concentrate in Great Lakes manufacturing corridors serving medical device and renewable energy customers.
Japan
Cell chemistry innovation programs in Osaka and Nagoya industrial zones advance rechargeable zinc-manganese architectures for grid storage applications. METI industrial policy supports domestic battery R&D through targeted funding mechanisms. Healthcare facility operators consolidate vendor relationships around outcome-based service models for backup medical equipment power systems.
South Korea
Renewable energy systems operators expand procurement of rechargeable platforms as lithium-ion supply constraints disrupt project timelines. National research institutes coordinate solid-state electrolyte programs compatible with zinc-manganese couples. Seoul Capital Area anchors industrial battery manufacturing serving regional export markets.
India
Imported cell manufacturers navigate BIS certification timelines that favor local assembly partnerships for consumer electronics applications. Central Electricity Authority procurement guidelines shape utility-scale storage technology selection. Maharashtra and Gujarat host emerging domestic cell assembly operations targeting price-sensitive household replacement demand.
Zinc-Manganese Oxide Batteries Market Competitive Landscape
Global majors compete with regional champions across technology licensing and captive raw material access. The vendor base stratifies into three tiers: diversified electronics conglomerates with integrated cell manufacturing, specialized battery producers with manganese supply advantages, and regional fabricators serving price-sensitive consumer segments. Strategic differentiation concentrates on backward integration into manganese sourcing, formulation expertise for rechargeable variants, and direct sales relationships with industrial procurement departments. Capacity expansion and geographic licensing agreements represent the dominant competitive moves.
Within the diversified conglomerate tier, Panasonic Holdings Corporation and VARTA AG exemplify scale-driven positioning through industrial battery portfolios. Among Asia-based specialists, Nanfu Battery occupies a position emphasizing captive manganese sourcing for cost-competitive alkaline production. Urban Electric Power represents the emerging rechargeable platform segment focused on grid-scale storage applications.
| Leading Market Players |
|---|
| Nanfu Battery |
| GPB International |
| Duracell |
| Urban Electric Power |
| Zhongyin (Ningbo) Battery |
| Panasonic Holdings Corporation |
| Zhejiang Mustang Battery |
| VARTA AG |
| Sunergy Battery |
| Others |
Value Network & Pricing Analysis
Electrochemical engineering talent scarcity in South Korean and Japanese industrial zones widens pricing-tier spreads between commodity alkaline cells and specialized rechargeable platforms for grid storage applications.
Pricing Analysis
Input-cost pass-through from manganese dioxide volatility feeds directly into contract renegotiations for industrial battery procurement. Three-tier pricing structure across premium certified, standard commercial, and economy retail levels reflects GB compliance burden differentials. Pricing pressure stems from steel industry demand fluctuations for manganese feedstock. Household consumers through supermarket channels exhibit highest price sensitivity, while grid-scale storage operators prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Freight cost escalation on electrolyte shipments from Chinese coastal provinces compresses margins for alkaline cell assemblers in India and Southeast Asia. Manufacturing gravity centers on China, South Korea, and Japan, with manganese dioxide sourcing drawing from Australian and Gabonese mining operations. Single-source vulnerability concentrates in high-purity manganese refining capacity. Distribution runs through supermarket retail for consumer volumes and direct sales contracts for industrial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory layering, with China's SAMR circularity mandates for industrial-scale installations creating structural demand for compliant rechargeable platforms.
For Market Incumbents: Anticipate lithium-ion supply constraints accelerating competitor entry into grid storage segments. Secure captive manganese sourcing through long-term offtake agreements with Australian and African producers. Invest in solid-state electrolyte R&D partnerships with South Korean national research institutes to defend technical differentiation against emerging aqueous chemistry specialists.
For New Entrants and Emerging Players: BIS certification timelines in India open a window for local assembly partnerships serving consumer electronics replacement demand. Target Maharashtra and Gujarat manufacturing zones where domestic cell operations face limited technical competition. Pursue hospital procurement contracts in Japan and South Korea through outcome-based service model positioning.
For Investors and Strategic Acquirers: Industrial battery conglomerates are the most active acquirer in this space, seeking manganese supply security and rechargeable formulation expertise. Five-to-ten year viability hinges on solid-state electrolyte convergence resolving dendrite formation in zinc-metal anodes. Monitor South Korean and Japanese patent filings for zinc-manganese solid-state architectures as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Sourcing | Captive supply from Australian mining operations insulates Nanfu Battery and Zhongyin from commodity volatility. |
| Solid-State Electrolyte R&D Partnership | Collaboration with Osaka and Nagoya innovation centers advances Panasonic's rechargeable platform for grid storage. |
| GB Standards Compliance Certification | SAMR circularity mandates force manufacturing line upgrades that favor capitalized domestic producers in Ningbo. |
| Direct Sales Channel Expansion | Urban Electric Power negotiates long-term supply agreements with renewable energy systems operators bypassing distributor markups. |
| Medical Device Service Unbundling | VARTA AG shifts performance risk through separate maintenance contracts with Japanese hospital procurement departments. |
Research Methodology
Coverage spans East Asian production clusters, North American grid storage procurement corridors, and Indian consumer electronics markets, with primary inputs from each. The research combines interviews with cell chemistry R&D directors, grid operator procurement officers, and hospital biomedical engineers with secondary validation through SAMR regulatory filings, EPA mercury content databases, and BIS certification records. Bottom-up volume modeling and top-down value triangulation anchor the analytical framework.
Rate-of-change decomposition separates volume growth from price realization effects across the projection horizon. Segmentation dimensions include product architecture tier, end-use application, customer type, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to historical shipment data and forward procurement pipeline visibility. Forecast inputs incorporate manganese dioxide price indices and lithium carbonate supply constraint indicators.
Revisions become necessary when SAMR enforcement intensity shifts, solid-state electrolyte research achieves commercial breakthrough, or lithium supply constraints ease materially. Forecasts reflect documented assumptions on technology adoption curves and regulatory implementation timelines. A model refresh is warranted upon material change in GB standards compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Non-Rechargeable Battery Market
Batteries
Italy Rechargeable Battery Market
Batteries
Mobile Battery Market
Batteries
Global Industrial Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Primary Lithium Battery Market
Batteries
North America Battery Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
Disposable Batteries Market
Batteries
Submarine Batteries Market
Batteries
Drone Lithium Battery Charger Market
Batteries
Global Marine Battery Market
Batteries
Inverter Battery Market
Batteries
North Europe Battery Market
Batteries
Printable Battery Market
Batteries
Hybrid Flow Battery Market